 1-888-601-9980
Compare life insurance quotes in British Columbia
Get an instant quote, compare top insurers, and choose coverage that fits your family needs and budget.




Life insurance in British Columbia
Life insurance in British Columbia helps protect your family’s finances if you die unexpectedly. Coverage can help replace lost income, pay off a mortgage, cover childcare and other household expenses, or support long-term financial goals. In British Columbia, the average life insurance coverage is higher than in many provinces in Canada. Whether you are looking for affordable life insurance in Vancouver or anywhere else in British Columbia, it is best to compare life insurance quotes with PolicyAdvisor. Our advisors will help you compare quotes across 30+ insurers.
How much does life insurance cost in British Columbia
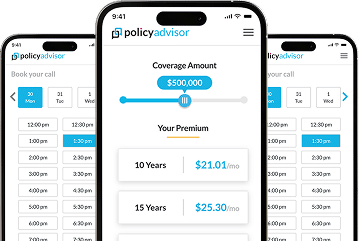
Life insurance premiums in BC are priced based on individual risk and age, but term coverage remains comparatively affordable for most healthy applicants. The cost of life insurance for a 25-year old male seeking $500,000 in coverage for a 20-year term is $31 per month, while a female applicant seeking the same coverage pays $22 per month.
Below are estimated monthly premiums for healthy non-smokers in British Columbia:
| Age | Male | Female |
|---|---|---|
| 25 | $31 | $22 |
| 35 | $33 | $26 |
| 45 | $75 | $54 |
| 55 | $223 | $155 |
| 65 | $716 | $487 |
Term life insurance premiums, $500,000 death benefit, non-smoking, 20-year term
How life insurance works in British Columbia
Here’s how a life insurance policy works in British Columbia:
- Choose your coverage: Decide how much life insurance you need and choose a policy type, such as term or whole life insurance
- Apply for a policy: Submit a life insurance application with information about your age, health, lifestyle, income, and coverage needs
- Complete underwriting: The insurer assesses your application and determines your eligibility and premium. Some applications may require a medical exam
- Pay your premium: Once approved, pay your monthly or annual premium to keep the policy active
- Keep your policy active: Your coverage remains in place as long as you meet the policy requirements and keep up with premium payments
- Your beneficiary receives the benefit: If you die while the policy is active, your beneficiary can file a claim. Once approved, the insurer pays the death benefit directly to them
Types of life insurance in British Columbia
Term life insurance
Provides coverage for a set period, commonly 10, 20, or 30 years. It can help protect your family during your highest financial-responsibility years, such as while paying a mortgage, raising children, or replacing employment income.
- Lower monthly premiums than most permanent policies
- Strong short- to mid-term protection for temporary financial obligations
- Common choice for young families seeking substantial coverage on a budget
- Flexible coverage amounts to match income, debts, and family needs
- Renewal or conversion options may be available, depending on the policy
Whole life insurance
Provides lifelong coverage as long as premiums are paid, along with a cash value component that can grow over time. Whole life insurance is often considered for estate planning, final expenses, and long-term wealth transfer.
- Permanent protection that can remain in place for life
- Cash value component that grows on a tax-deferred basis
- Predictable, subject to policy terms
- Useful for estate planning and leaving a financial legacy
- Potential access to cash value through policy loans or withdrawals, depending on the policy
Do you need life insurance in British Columbia?
Yes, you may need life insurance in BC if someone depends on your income or would face financial obligations after your death. You must consider getting life insurance if you:
- Have dependents: Replace income and help cover childcare, education, and everyday expenses
- Have a mortgage or debts: Give your family funds to manage outstanding financial obligations
- Own a business: Help protect business partners, employees, or the company from financial disruption
- Want to cover final expenses: Set aside funds for funeral costs, taxes, or other end-of-life expenses
- Want to leave a legacy: Permanent life insurance can help transfer wealth or provide an inheritance
- Have limited savings: Life insurance can provide a larger financial safety net than savings alone
What determines your life insurance premium in British Columbia?
Life insurance premiums in British Columbia are calculated through a process called underwriting. Insurers assess your overall risk profile to determine how likely you are to make a claim during the policy term.
Since insurers in BC use different underwriting models, the same applicant can receive different quotes across providers. PolicyAdvisor allows you to instantly compare rates from the biggest Canadian insurers, helping you identify competitive pricing based on your unique profile.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them.
Why choose PolicyAdvisor for life insurance in British Columbia?
Buying life insurance in British Columbia doesn’t mean choosing the first insurer you find. Comparing multiple providers helps ensure you secure competitive quotes and the right policy structure for your needs. With PolicyAdvisor, you can:
No waiting for callbacks. No hidden pricing. Compare personalized insurance quotes upfront.
View multiple options side-by-side and find the best, most affordable option for your financial safety.
Your premiums stay fair and clear.
Explore your options without any pressure to buy.
Start your quote online in minutes and complete your application seamlessly.
Have questions? Speak to a licensed advisor for guidance anytime you need it.
How much life insurance coverage do you need in British Columbia?
The right coverage amount depends on your financial obligations and long-term responsibilities. A common rule is to get coverage equal to 7 to 10 times your annual income, but individual needs vary. When calculating your coverage needs, consider:
Because every household situation is different, using a life insurance calculator can help estimate a more precise coverage amount.
Get a personalized quote in seconds
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by

Life insurance in major British Columbia cities
Life insurance needs can vary across British Columbia’s major cities due to differences in housing markets, average mortgage balances, and household income levels. In cities where property prices and living costs are higher, residents often structure coverage to protect larger mortgage obligations and ensure long-term income replacement for their families.
Get life insurance quotes in different cities
- Vancouver
- Surrey
- Burnaby
- Richmond
- Abbotsford
- Coquitlam
Best life insurance companies in British Columbia
If you are in British Columbia, you can choose a life insurance plan from Canada’s top insurers, including Manulife, Sun Life, Canada Life, RBC Insurance, iA Financial, Empire Life, and a few others. Each insurer has different strengths and policy options. For instance, Manulife offers wellness-focused features, RBC Insurance provides flexible solutions that can support coverage laddering, and Sun Life has a wide selection of term and permanent policies. Canada Life also offers insurance solutions suited to families, incorporated professionals, and business owners with broader financial planning needs. If you are comparing the insurers, our guide to the best life insurance companies in Canada provides a detailed comparison.
How to apply for life insurance in British Columbia
Applying for life insurance in British Columbia usually starts with choosing your coverage amount and policy type, followed by a health questionnaire or medical exam. Once underwriting is complete, the insurer reviews your application and determines your final premium.
Comparing multiple insurers before applying helps ensure you receive the best possible pricing and policy structure based on your profile. With PolicyAdvisor, the process is streamlined:
-
Save time
Get instant quotes from BC’s top life insurance companies
-
Save money
Compare multiple quotes to find the best price
-
Shop anywhere
Use online tools from your phone or computer
-
Personalized service
Receive expert advice from a dedicated insurance advisor
Common mistakes to avoid when buying life insurance in British Columbia
-
Relying only on employer-provided coverage
Group insurance is often limited to one or two times your annual salary. This may not be enough to cover mortgage debt, long-term income replacement, or future education costs.
-
Underestimating how much coverage you need
Choosing a lower coverage amount to save on premiums can leave your family financially exposed.
-
Waiting too long to apply
Premiums increase with age, and health changes over time. Delaying coverage can result in higher costs or limited eligibility.
-
Not comparing multiple insurers
Life insurance quotes and underwriting standards vary between companies. Applying with only one insurer may mean paying more than necessary.
-
Choosing mortgage insurance instead of individual coverage
Mortgage insurance typically names the lender as beneficiary and coverage decreases over time. Individual life insurance provides more flexibility and control.
Frequently Asked Questions
Is life insurance mandatory in British Columbia?
No, life insurance is not legally required in British Columbia. However, it is strongly recommended if you have dependents, a mortgage, or outstanding debts. It ensures your family is financially protected and not burdened with repayments or daily expenses in your absence.
Can I get life insurance in British Columbia without a medical exam?
Yes, many insurers offer no-medical or simplified issue life insurance in British Columbia. These plans are ideal if you want faster approval or prefer to avoid medical tests. While premiums may be slightly higher, they provide a convenient option for many applicants.
What types of life insurance are popular in British Columbia?
Term life insurance and whole life insurance are the most common choices in British Columbia. Term plans are popular for covering temporary needs like mortgages and income replacement, while whole life insurance is used for long-term financial planning and estate transfer.
Can I get life insurance if I have a mortgage in British Columbia?
Yes, life insurance is often used to protect mortgage obligations in British Columbia. Instead of relying solely on mortgage insurance from a lender, many homeowners prefer individual life insurance policies because they offer fixed coverage, flexible beneficiaries, and better long-term value.
Is life insurance in Vancouver higher than elsewhere in BC?
No, the cost of life insurance in Vancouver will not be higher than in other cities in BC. This is because your city or province does not directly determine your life insurance premium. Insurers primarily consider factors such as age, health, smoking status, coverage amount, and policy term.