Whole life insurance cost in Canada: A complete guide

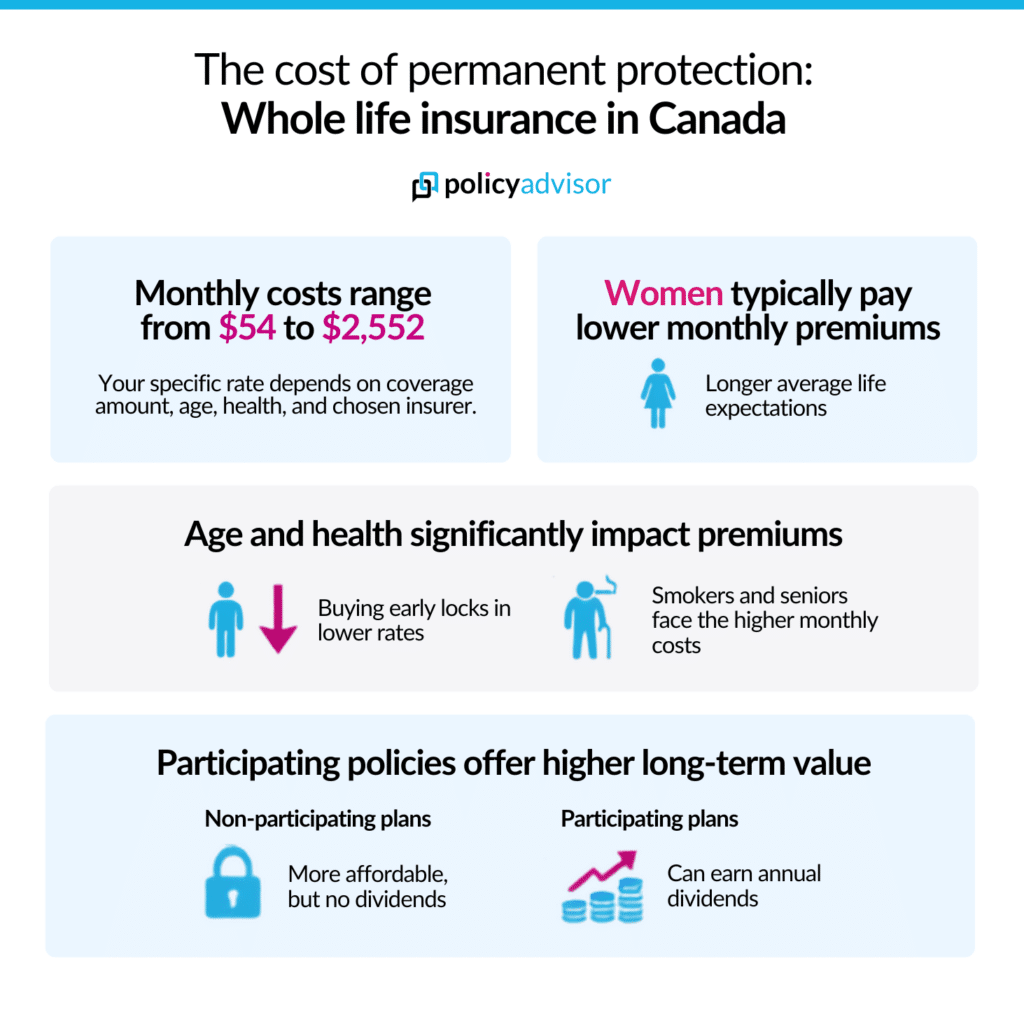
The cost of whole life insurance typically ranges from $54 to $2,552 per month, depending on your age, health, coverage amount, premium payment option, and the insurer you choose. While whole life insurance costs more than term life insurance, the higher premiums provide benefits that last a lifetime, including permanent coverage, level premiums, and tax-advantaged cash value growth. Some policies, such as participating policies, may also earn annual dividends, depending on the insurer and policy type, further increasing their long-term value.

Quick summary of whole life insurance costs in Canada

Cost category Typical monthly premium range 
By plan type
  • Participating policy: $118-$382
  • Non-participating policy: $57-$319
By coverage amount
  • $100,000: $57-$382
  • $250,000: $132-$914
  • $750,000: $350-$2,552
By applicant category
  • Male applicants: $71-$319
  • Female applicants: $57-$278
  • Smoking status: $57-$413
  • Children: Typically starts at $100 
  • Seniors: $277-$960
Payment option
  • 10 Pay: $70-$319
  • 20 Pay: $54-$323
  • Life Pay: $38-$209
By insurers
  • Foresters Life: $57-$319
  • Desjardins: $69-$334
  • Sun Life: $80-$346
  • Industrial Alliance: $81-$367
  • Canada Protection Plan: $102-$355

Disclaimer: The illustrative monthly premiums below are based on the examples used throughout this guide. Your actual premium will vary based on your personal profile, coverage needs, and the insurer you choose.

How much does whole life insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

What affects the cost of whole life insurance in Canada?

The whole life insurance cost depends on your personal profile, coverage needs, and the type of policy you choose. The following factors affect how the cost of your whole life insurance policy will be determined in Canada:

  • Age: Age is one of the biggest factors affecting whole life insurance premiums. Buying a policy at a younger age typically results in significantly lower premiums because insurers view younger applicants as lower-risk
  • Health: Your overall health, medical history, and any pre-existing conditions affect your premium. Applicants in good health typically qualify for lower whole life insurance rates
  • Smoking status: Smokers usually pay considerably higher premiums than non-smokers due to the increased health risks associated with tobacco and nicotine use. Many insurers offer non-smoker rates after you have been tobacco-free for at least 12 months
  • Gender: Women often pay lower premiums than men because, on average, they have a longer life expectancy
  • Coverage amount: Choosing a higher death benefit increases your premium since the insurer assumes a larger future payout
  • Policy type: Participating whole life insurance generally costs more than non-participating policies because it offers the potential to earn annual dividends, which may increase your policy’s cash value and death benefit over time
  • Premium payment option: The payment schedule you choose also affects your monthly premium. Policies with a 10-pay or 20-pay option have higher premiums because the policy is paid off in fewer years, while life pay spreads payments over a longer period, resulting in lower monthly costs
  • Insurance company: Premiums can vary between insurers because each company uses its own underwriting guidelines, dividend scale, and pricing structure. Comparing quotes from multiple insurers can help you find the best value for your needs
  • Policy riders: Adding optional riders, such as a child rider, disability waiver of premium, or guaranteed insurability rider, increases the overall cost of your policy but provides additional protection and flexibility
Read more about whole life insurance

Whole life insurance cost in Canada by plan type 

Different types of whole life insurance come with different premium costs and long-term benefits. In Canada, you can choose between participating and non-participating whole life insurance. Participating policies generally have higher premiums because they may pay annual dividends, while non-participating policies offer lower premiums with guaranteed benefits but no dividend potential.

What is the cost of participating whole life insurance?

The cost of participating whole life insurance typically starts at $138.42 per month for a 20-year-old non-smoker with $100,000 in coverage under a 20-pay premium option. For a comparable female applicant, the premium starts at $118. Participating policies may be suitable for individuals seeking lifelong coverage, guaranteed cash value growth, and the potential to earn eligible annual dividends, which may increase the policy’s cash value and death benefit over time.

Cost of participating whole life insurance

Age (in years) Male (non-smoker) Female (non-smoker)
20 $138.42 $118.89
30 $177.84 $156.15
40 $228.96 $207.00
50 $292.23 $270.81
60 $382.14 $351.81

*Illustrative monthly premiums for non-smoking male and female of various age ranges seeking a participating whole life insurance policy with $100,000 in coverage for a 20-pay premium option

What is the cost of non-participating whole life insurance?

The cost of non-participating whole life insurance typically ranges from $57 to $319 per month. It is generally more affordable than participating whole life insurance and may be a good option for individuals looking for permanent coverage, guaranteed cash value, and predictable premiums without dividend participation.

Cost of non-participating whole life insurance

Age (in years) Male (non-smoker) Female (non-smoker)
20 $70.74 $57.24
30 $100.35 $88.74
40 $141.66 $127.53
50 $223.83 $181.71
60 $319.41 $277.92

*Illustrative costs for non-smoking male and female of various age ranges seeking a non-participating whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Whole life insurance cost by coverage amount in Canada

The amount of coverage you choose directly affects the cost of your whole life insurance policy. In general, higher coverage amounts come with higher premiums because the insurer assumes a larger death benefit payout. For instance, the cost of whole life insurance with $100,000 in coverage will be lower than that of $250,000 in coverage because the insurer is assuming a smaller death benefit. The tables below show illustrative monthly premiums for different coverage amounts.

How much is a $100,000 whole life insurance policy?

The cost of a $100,000 whole life insurance policy typically ranges from $57.24 to $382.14 per month for non-smokers. This coverage amount is well suited for covering final expenses, leaving a modest inheritance, or supplementing an existing life insurance policy. It also provides lifelong protection while building guaranteed cash value over time.

Cost of a $100,000 whole life insurance policy

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
20 $70.74 $138.42 $57.24 $118.89
30 $100.35 $177.84 $88.74 $156.15
40 $141.66 $228.96 $127.53 $207.00
50 $223.83 $292.23 $181.71 $270.81
60 $319.41 $382.14 $277.92 $351.81

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

How much is a $250,000 whole life insurance policy?

The cost of a $250,000 whole life insurance policy ranges from $132 to $914 per month for non-smoking applicants, depending on age, gender, and whether you choose a participating or non-participating policy. This coverage amount may be suitable for individuals or families looking to replace a portion of their income, pay off outstanding debts, or help cover future financial obligations. 

Cost of a $250,000 whole life insurance policy

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
20 $156.38 $323.10 $132.30 $285.98
30 $225.45 $415.58 $204.75 $377.55
40 $328.05 $540.22 $298.35 $495.00
50 $521.55 $697.28 $427.95 $644.40
60 $765.45 $914.40 $649.80 $842.40

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $250,000 in coverage for a 20-pay premium option

How much is a $750,000 whole life insurance policy?

The cost of a $750,000 whole life insurance policy typically ranges from $350 to $2,552 per month for non-smokers, male and female. This higher coverage amount is designed for individuals with more complex financial needs, such as protecting a family’s lifestyle, supporting estate planning goals, or preserving wealth for future generations.

Premiums are higher for $750,000 in coverage because the insurer guarantees a larger death benefit. Like all other whole life insurance policies, it also offers lifelong coverage and guaranteed cash value growth according to the policy terms. Participating policies may also be eligible to earn annual dividends.

Cost of a $750,000 whole life insurance policy

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
20 $450.00 $892.35 $350.77 $801.90
30 $666.00 $1,162.35 $581.62 $1,059.07
40 $980.55 $1,522.12 $881.77 $1,401.30
50 $1,523.25 $1,966.95 $1,241.10 $1,829.93
60 $2,167.65 $2,552.18 $1,891.12 $2,382.75

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $750,000 in coverage for a 20-pay premium option

Find whole life insurance with the right coverage.

Get the lowest whole life insurance quotes from us.

Whole life insurance cost by applicant type in Canada

The cost of whole life insurance varies from one applicant to another because insurers assess each person’s level of risk before determining their premium. In general, younger applicants, women, and non-smokers tend to pay lower premiums, while older applicants and smokers typically pay more due to the higher likelihood of future insurance claims. The tables below show how whole life insurance premiums vary across common applicant types.

Cost of whole life insurance based on gender

The cost of whole life insurance for non-smokers typically ranges from $70.74 to $319.41 per month for males and $57.24 to $277.92 per month for females, depending on age. The cost of whole life insurance is generally lower for women, and they pay lower premiums than men. This is because females have a longer average life expectancy, resulting in a lower mortality risk for insurers over the lifetime of the policy.

Whole life insurance costs: Male vs female

Age (in years) Male  Female
20 $70.74 $57.24
30 $100.35 $88.74
40 $141.66 $127.53
50 $223.83 $181.71
60 $319.41 $277.92

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a non-participating whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Cost of whole life insurance based on smoking status

The cost of whole life insurance for smokers typically ranges from $84.60 to $413.34 per month, compared to $57.24 to $319.41 per month for non-smokers. Smokers pay higher premiums because tobacco and nicotine use increase the risk of serious health conditions and reduce life expectancy, increasing the likelihood of future claims.

Whole life insurance cost for a smoker vs. a non-smoker

Age (in years) Male (Non-smoker) Male (Smoker) Female (Non-smoker) Female (Smoker)
20 $70.74 $100.08 $57.24 $84.60
30 $100.35 $139.14 $88.74 $118.53
40 $141.66 $205.07 $127.53 $177.17
50 $223.83 $289.29 $181.71 $246.55
60 $319.41 $413.34 $277.92 $349.26

*Illustrative monthly premiums for smoking and non-smoking males and females of various age ranges seeking a non-participating whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Cost of whole life insurance for children

The cost of whole life insurance for children can start from $100 per month for a 20-pay participating whole life policy. Purchasing whole life insurance for a child at a young age allows parents or grandparents to lock in lower lifetime premiums while providing lifelong coverage and guaranteed cash value growth. Over time, eligible dividends may increase the policy’s cash value and death benefit, depending on the policy and dividend option selected.

Cost of life insurance for a male child

Age Monthly premiums Accumulated cash value Death benefit
5 years $100/month $0 $159,200
20 years $100/month $17,000 $159,200
35 years No payment of premiums after the first 20 years $50,000 $218,000
50 years $129,000 $347,000
70 years $401,000 $634,000

*Illustrative accumulated cash value and death benefit for a $100/month, 20-pay participating whole life insurance policy issued to a healthy 5-year-old boy. Projected cash values and death benefits assume current dividend scales and are not guaranteed; the actual policy values may vary

Cost of whole life insurance for seniors

The cost of whole life insurance for seniors typically ranges from $277.92 to $960.57 per month for seniors aged 60 to 80 with $100,000 in coverage under a 20-pay option. Premiums are generally higher for seniors because the likelihood of future insurance claims increases with age. Despite the higher cost, whole life insurance can help cover final expenses, leave a tax-efficient inheritance, and support estate-planning goals for seniors’ beneficiaries.

Whole life insurance costs for seniors

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
60 $319.41 $382.14 $277.92 $351.81
65 $409.14 $445.77 $345.06 $404.64
70 $544.95 $485.41 $441.54 $468.81
75 $782.37 $671.04 $607.05 $569.07
80 $960.57 $904.77 $745.38 $750.87

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Whole life insurance costs by premium payment option

The cost of whole life insurance ranges between $38 and $323, depending on your age and the payment option you choose. Your premium payment option determines how long you will pay for your whole life insurance policy and how much you will pay each month. Shorter payment periods generally have higher monthly premiums because the policy is paid off sooner, while longer payment periods spread the cost over more years.

  • 20 Pay: Pay premiums for 20 years, after which your policy remains fully paid up for life while your lifelong coverage and cash value continue to grow
  • T65: Pay premiums until age 65, making it a popular option for those who want to complete payments before retirement while keeping lifelong coverage
  • Life Pay: Pay premiums until age 100, resulting in the lowest monthly premiums by spreading the cost over the longest payment period

Whole life insurance cost by payment option

Age (in years) 20 Pay T65 Life Pay
20 $70.74 $54.81 $38.97
30 $100.35 $74.34 $52.65
40 $141.66 $128.70 $82.89
50 $223.83 $322.83 $131.76
60 $319.41 $209.16

*Illustrative monthly premiums for a male non-smoker of various age ranges seeking a non-participating whole life insurance policy with $100,000 in coverage

Cost of whole life insurance by insurer in Canada

The cost of whole life insurance can vary noticeably between insurers, even for applicants with the same age, gender, coverage amount, and policy type. For example, a 20-year-old non-smoking male pays $70.74 per month with Foresters Life, compared to $113.49 per month with Canada Protection Plan for the same $100,000 of coverage. Differences in underwriting, pricing, and product design mean that the same applicant may receive different premiums from different insurers. Hence, comparing quotes from best whole life insurance companies helps you find the perfect combination of premium, policy features, and long-term value.

Whole life insurance cost by insurer

Age (in years) Foresters Life Desjardins Sun Life iA Financial Group Canada Protection Plan
20 years Male: $70.74

Female: $57.24

Male: $78.21

Female: $69.66

Male: $91.17

Female: $80.46

Male: $94.68

Female: $81.90

Male: $113.49

Female: $102.96

30 years Male: $100.35

Female: $88.74

Male: $105.66

Female: $95.13

Male: $114.21

Female: $102.42

Male: $114.03

Female: $104.13

Male: $131.49

Female: $121.50

40 years Male: $141.66

Female: $127.53

Male: $151.29

Female: $134.01

Male: $166.23

Female: $150.93

Male: $177.03

Female: $147.96

Male: $171.81

Female: $160.56

50 years Male: $223.83

Female: $181.71

Male: $235.26

Female: $191.70

Male: $267

Female: $222.03

Male: $251.73

Female: $210.15

Male: $237.69

Female: $221.13

60 years Male: $319.41

Female: $277.92

Male: $333.72

Female: $294.48

Male: $346.41

Female: $306.90

Male: $366.75

Female: $303.75

Male: $355.32

Female: $317.25

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a non-participating whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Is whole life insurance worth the cost?

Yes, whole life insurance can be worth the cost if you are looking for lifelong financial protection and long-term wealth-building benefits. Whole life insurance typically costs more than a comparable term life insurance policy, but the higher premiums provide lifelong financial benefits, including:

  • Lifetime coverage that never expires as long as premiums are paid
  • Guaranteed cash value growth that accumulates over time
  • Level premiums that remain unchanged throughout the life of the policy
  • Tax-advantaged cash value growth while the policy remains in force
  • Support for estate planning and wealth transfer through a generally tax-free death benefit paid to beneficiaries
  • Potential annual dividends on participating whole life policies, which may increase the policy’s cash value and death benefit over time

How does the cost of whole life insurance compare to term life insurance?

Whole life insurance generally costs more than term life insurance for the same coverage amount because it provides lifelong coverage and accumulates cash value over time. For example, a $100,000 whole life insurance policy costs approximately $57 to $382 per month, while a $100,000 term life insurance policy costs around $7 to $44 per month, making term life insurance the more affordable option for short-term coverage needs.

If you only need life insurance for a specific period, such as while paying off a mortgage or supporting your family, term life insurance may be the more cost-effective option. If you need lifelong coverage or want to build cash value over time, whole life insurance may be worth considering.
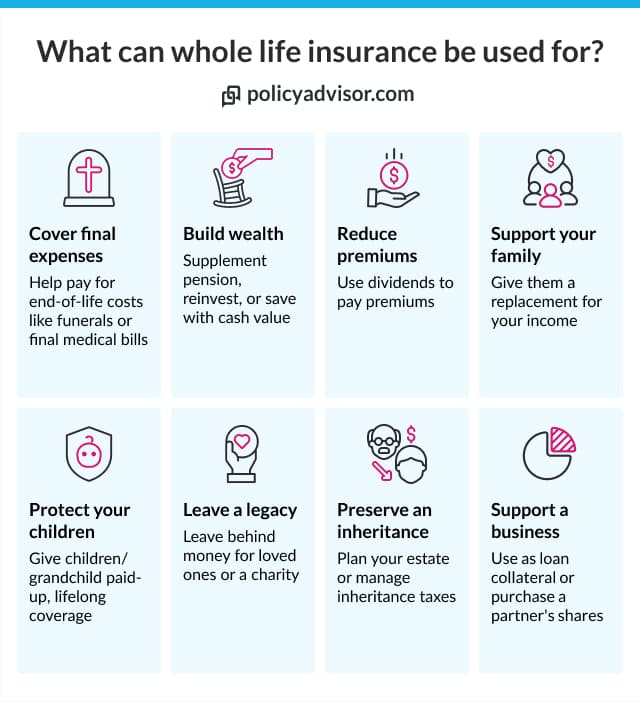
A whole life insurance policy can be used during your lifetime and can help benefit your beneficiaries after you pass away.

How to reduce the cost of whole life insurance

Although whole life insurance generally costs more than term life insurance, there are several ways to make coverage more affordable, such as buying early, choosing the right coverage amount, comparing quotes, and more. Here are some of the ways in which you can reduce the cost and get the cheapest whole life insurance:

  • Buy coverage early: Purchasing whole life insurance at a younger age helps you lock in lower premiums for life
  • Choose the right coverage amount: Choose a coverage amount that aligns with your financial needs without paying for more coverage than necessary
  • Maintain a healthy lifestyle: Good overall health and remaining tobacco-free can help you qualify for lower premiums 
  • Consider a non-participating policy: If dividend potential isn’t important to you, a non-participating policy can provide permanent coverage at a lower cost
  • Select a longer premium payment period: Options such as Life Pay generally have lower monthly premiums than shorter payment schedules like 20 Pay because premium payments are spread over the entire policy period
  • Compare quotes from multiple insurers: Premiums can vary significantly between insurance companies for the same coverage. Comparing quotes through PolicyAdvisor lets you evaluate plans from Canada’s leading insurers and find the best value based on your budget and financial goals. Schedule a call now to get instant whole life insurance quotes!
Need whole life insurance?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Why is whole life insurance more expensive than term life insurance?

Whole life insurance costs more because it provides lifelong coverage, guaranteed cash value accumulation, and a guaranteed death benefit. Participating policies may also be eligible to earn annual dividends, adding further long-term value. Term life insurance only covers you for a fixed period and does not build cash value, making it a more affordable option.

How does adding riders affect whole life insurance premiums?

Adding optional riders, such as critical illness coverage, accidental death benefits, or disability waiver of premium, increases whole life insurance premiums. Riders provide additional benefits tailored to individual needs but come at an added cost. For example, a critical illness rider might add 10-20% to the base premium.

Can I lower my whole life insurance premiums after buying a policy?

In most cases, your premiums are fixed when you purchase the policy and cannot be reduced later. However, you may be able to lower your overall costs by choosing a different payment option, reducing your coverage amount, or selecting a non-participating policy.

Can I switch from term life insurance to whole life insurance?

Yes, many term life insurance policies include a conversion option that allows you to convert some or all of your coverage to whole life insurance without completing a new medical exam. The conversion must usually be completed before a specified age or policy anniversary, depending on your insurer.

How much does a $250,000 whole life insurance policy cost?

The cost of a $250,000 whole life insurance policy ranges from $132-$914. The actual costs may vary based on your age, gender, health, smoking status, policy type, and insurer. In general, premiums are higher for $250,000 than for $100,000 in coverage.

Which premium payment option has the lowest monthly cost?

Life Pay typically offers the lowest monthly premiums because the cost of the policy is spread over the longest payment period. In contrast, 20 Pay policies have higher monthly premiums but are fully paid up sooner.

How can I reduce the cost of whole life insurance?

You can lower your whole life insurance premiums by purchasing coverage at a younger age, choosing an appropriate coverage amount, maintaining good health, selecting a non-participating policy, opting for a longer premium payment period, and comparing quotes from multiple insurers.
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much does life insurance cost in Canada in 2026?

The average cost of life insurance in Canada starts at around $7 per month for a healthy young adult purchasing a basic term life insurance policy. Depending on the type of policy, coverage amount, age, health, and insurer, premiums can range from $7 to over $3,276 per month. Individuals who smoke, have pre-existing medical conditions, work in high-risk occupations, or require larger coverage amounts generally pay higher premiums. On the other hand, young and healthy applicants typically qualify for lower premiums.

Quick summary: Average life insurance costs in Canada

Cost category Average cost (per month)
By plan type
  • Term life: $14-$200
  • Permanent life: $71-$382
  • No medical: $39-$380
By coverage amount
  • $100,000: $7-$44
  • $250,000: $10-$98
  • $500,000: $13-$177 
  • $1,000,000: $21-$330
  • $10,000,000: $166-$3276
By applicant category
  • Smokers: $42-$504
  • Seniors: $15-$267
  • Children: Starts at $100
  • Couples: $33-$1283
By term length
  • 10-year: $22-$40
  • 20-year: $28-$70
  • 30-year: $42-$144
By insurers
  • Sun Life: $16-$230
  • Manulife: $17-$213
  • Empire Life: $14-$200
  • Equitable Life: $14-$200
  • Canada Life: $16-$204

Disclaimer: The premiums shown above are illustrative estimates based on specific applicant profiles and policy assumptions, and your actual life insurance cost may vary depending on several factors such as your age, gender, health, smoking status, medical history, coverage amount, policy type, term length, and the insurer’s underwriting guidelines.

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Factors affecting life insurance cost in Canada

The cost of life insurance in Canada is mainly driven by factors like age, gender, health, coverage amount, and more. Some of these factors include: 

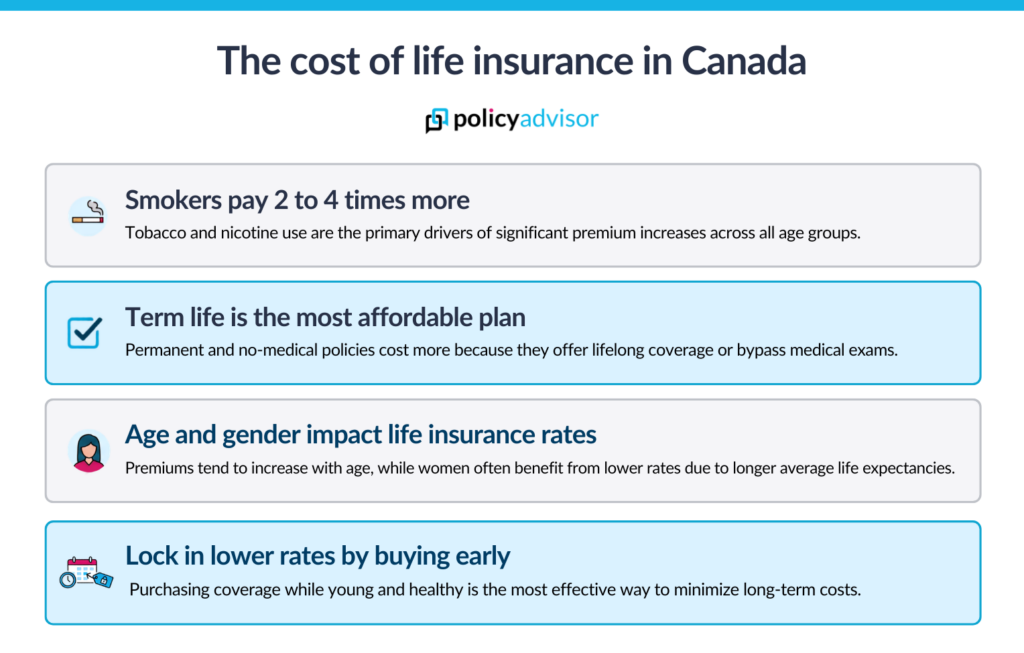
  • Age: The age of the individual directly affects the life insurance cost. The older the individual, the higher the premium
  • Gender: Life insurance premiums may vary by gender, with women generally paying lower premiums than men due to their longer average life expectancy
  • Coverage amount: The higher the coverage amount you choose, the higher the life insurance premium will be
  • Health: An individual’s health also affects premium rates. A healthy individual, compared to someone with a history of medical conditions, qualifies for lower rates
  • Smoking status: Any insurance company in Canada will charge a higher premium if you are a smoker. This is because the health risks associated with smoking are higher than those for a non-smoker
  • Lifestyle: If you are involved in high-risk activities as a result of your hobby or occupation, then the insurer views you as higher risk. This increased liability will also result in you paying higher premiums
Learn more about the different types of life insurance in Canada
life insurance cost

Life insurance costs by policy type

The type of life insurance policy you choose is one of the biggest factors affecting your premium. In general, term life insurance is the most affordable option, while permanent policies, such as whole life insurance, cost more because they provide lifelong coverage and can build cash value. No-medical life insurance also tends to have higher premiums since insurers assume more risk by offering coverage without requiring a medical exam.

What is the cost of term life insurance in Canada?

The cost of term life insurance in Canada with $500,000 in coverage can range from $14 to $200 per month, depending on the applicant’s age, gender, and health. Because term life insurance provides coverage for a fixed period and does not build cash value, it is the most affordable type of life insurance. It is well-suited for individuals and families looking to protect their income, cover a mortgage, or provide financial security during their highest-earning years.

Term life insurance cost in Canada

Age Male Female
20 years $22 $14
30 years $22 $15
40 years $27 $19
50 years $61 $45
60 years $200 $145

*Illustrative monthly cost of term life insurance for a 10-year period for individuals of various ages with $500,000 in coverage

What is the cost of whole life insurance in Canada?

In Canada, participating whole life insurance with $100,000 in coverage costs between $139 and $382 per month, whereas a non-participating policy may cost between $71 and $320 per month, depending on the applicant’s age and insurer. The cost of whole life insurance is generally several times more expensive than an equivalent term life policy because it provides lifelong coverage and builds cash value. 

Participating whole life insurance may also pay policy dividends, depending on the insurer’s dividend performance. It is commonly chosen for estate planning, wealth transfer, tax-advantaged savings, and leaving a guaranteed financial legacy.

Cost of whole life insurance in Canada

Age Participating ($100k coverage) – Paid Up additions Non-participating ($100k coverage)
20 years $139 $71
30 years $178 $100
40 years $229 $142
50 years $293 $224
60 years $382 $320

*Illustrative monthly costs for a male individual of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

What is the cost of a no-medical life insurance policy in Canada?

The cost of a 20-year no-medical life insurance policy with $500,000 in coverage ranges from $39 to $380 per month. While no-medical policies offer faster approval and do not require a medical exam, they generally cost more than fully underwritten life insurance because insurers take on greater underwriting risk. These policies are often suitable for individuals with pre-existing health conditions, those who may not qualify for traditional life insurance, or applicants who need coverage quickly.

Cost of a no-medical life insurance policy

Age Male Female
20 years $50.40 $39.15
30 years $54.90 $45.90
40 years $52.65 $41.40
50 years $105.30 $87.75
60 years $380.25  $280.35

*Illustrative monthly cost of a 20-year no-medical plan with $500,000 in coverage

Life insurance costs by coverage amount

The amount of term life insurance coverage you choose has a direct impact on your monthly premium. Higher coverage amounts generally cost more, although the premium increase is not always proportional. The cost of a $100,000 term life insurance policy will be much lower than that of a $250,000 term life policy. The coverage amount in the section below details the cost of different coverage amounts in Canada.

How much does a $100,000 life insurance policy cost?

A $100,000 term life insurance policy in Canada costs approximately $7 to $44 per month. While premiums remain relatively affordable for younger applicants, they increase significantly with age due to the higher insurance risk. A $100,000 may be suitable for people looking to cover final expenses, smaller debts, or supplement existing life insurance. However, it may not provide enough coverage for someone with a mortgage, dependents, or significant income replacement needs.

Cost of a $100,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $9.45 $7.71
30 years $9.45 $8.19
40 years $10.53 $9.72
50 years $18.00 $15.12
60 years $44.10 $33.57

*Illustrative monthly cost of term life insurance for a 10-year plan with $100,000 in coverage for a male/female non-smoker

How much does a $250,000 life insurance policy cost?

The cost of a $250,000 term life insurance policy ranges from approximately $10 to $98 per month. A $250,000 coverage is a popular choice for individuals and families looking to cover obligations such as a portion of their mortgage, income replacement, children’s education costs, outstanding debts, or other long-term expenses.

Cost of a $250,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $13.94 $10.35
30 years $13.94 $10.58
40 years $16.87 $13.50
50 years $34.20 $26.55
60 years $98.33 $71.55

*Illustrative monthly cost of term life insurance for a 10-year plan with $250,000 in coverage for male/female non-smoker

How much does a $500,000 life insurance policy cost?

A $500,000 term life insurance policy costs between $13 and $177 per month for healthy non-smokers. The exact premium will vary, with younger applicants typically qualifying for significantly lower rates. A $500,000 coverage can help replace income, pay off a mortgage, cover childcare, education costs, and other major financial obligations.

Cost of a $500,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $21.60 $13.95
30 years $21.60 $14.85
40 years $26.55 $18.90
50 years $57.60 $44.55
60 years $176.85 $133.20

*Illustrative monthly cost of term life insurance for a 10-year plan with $500,000 in coverage for male/female non-smoker

How much does a $1,000,000 life insurance policy cost?

The cost of a life insurance policy with $1,000,000 in coverage is between $21 and $330 per month. This coverage amount is commonly chosen by high-income earners, homeowners, parents with young children, business owners who need substantial coverage to replace income, pay off significant debts, fund future education costs, or leave a substantial financial legacy.

Cost of a $1,000,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $35.99 $21.15
30 years $35.54 $22.95
40 years $45.90 $31.05
50 years $108.00 $78.75
60 years $330.30 $253.80

*Illustrative monthly cost of term life insurance for a 10-year plan with $1,000,000 in coverage for male/female non-smoker

How much does a $10,000,000 life insurance policy cost?

The cost of a $10,000,000 term life insurance policy ranges from $166 to $3,276 per month. Premiums are substantially higher than those for lower-value policies because the insurer assumes a much larger financial risk. A $10,000,000 life insurance policy is suitable for high-net-worth families, business owners, executives, and professionals with significant financial obligations, business succession needs, or those with complex estate planning goals.

Cost of a $10,000,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $310.50 $166.50
30 years $310.50 $184.50
40 years $426.60 $292.50
50 years $1,044.00 $725.40
60 years $3,276.00 $2,394.00

*Illustrative monthly cost of term life insurance for a 10-year plan with $10,000,000 in coverage for male/female non-smoker

Find affordable life insurance with the right coverage.

Get the cheapest life insurance rates in Canada from top providers.

Life insurance costs by applicant category

Life insurance premiums can vary significantly depending on your personal circumstances and risk profile. In general, smokers, seniors, and individuals with health conditions tend to pay higher premiums because they present a greater insurance risk. Couples may have the option to reduce costs through certain joint life insurance policies, although individual policies may be more cost-effective in some cases.

How much is life insurance per month for smokers and non-smokers?

The cost of $500,000 in term life insurance for smokers ranges from $42 to $504 per month, while comparable coverage for non-smokers ranges from $21 to $177 per month. Smokers pay premiums that are often 2 to 4 times higher than non-smokers because tobacco and nicotine use are associated with a higher risk of serious health conditions, including heart disease, stroke, and cancer. 

The difference in premiums becomes more noticeable with age, as the combined impact of smoking and age increases an insurer’s expected risk. Quitting smoking can significantly reduce your premiums, but most insurers require you to remain tobacco-free for at least 12 months before you may qualify for non-smoker rates. The required tobacco-free period may vary by insurer. 

Cost of life insurance for smokers and non-smokers (male) for varying age groups

Age Smoker Non-smoker
30 years $42.30 $21.60
40 years $63.00 $26.55
50 years $180.45 $57.60
60 years $503.55 $176.85

*Illustrative monthly costs for a male individual seeking $500,000 in life insurance coverage for a 10-year policy

How much is life insurance per month for seniors?

The cost of $100,000 in term life insurance for male seniors ranges between $18 and $267 per month, while comparable coverage for female seniors is between $15 and $179 per month. Female applicants generally pay lower premiums than male applicants because they tend to have a longer life expectancy. As you get older, the premiums for life insurance for seniors increase due to the higher likelihood of health issues and claims during the policy term.

Cost of life insurance for seniors

Age Male Female
50 years $18.00 $15.12
55 years $26.28 $22.32
60 years $44.10 $33.57
65 years $76.41 $53.73
70 years $133.29 $92.34
75 years $267.48 $178.92

*Illustrative monthly costs for non-smoker seniors in various age ranges seeking a term life insurance policy with $100,000 in coverage

How much is life insurance per month for children?

Children’s whole life insurance typically starts at around $100 per month. Whole life insurance policies for children provide lifelong coverage and can build cash value over time, making them a long-term financial planning tool as well as a source of insurance protection.

Cost of whole life insurance for a female child

Age Monthly premiums Accumulated cash value Death benefit
5 years $100 $0 $180,200
20 years $100 $16,400 $180,200
35 years No payment of premiums after the first 20 years $50,000 $250,000
50 years $130,000 $400,000
70 years $408,000 $713,000

*Illustrative accumulated cash value and death benefit for a $100/month, 20-pay participating whole life insurance policy issued to a healthy 5-year-old girl. Projected cash values and death benefits assume current dividend scales and are not guaranteed; the actual policy values may vary

Cost of whole life insurance for a male child

Age Monthly premiums Accumulated cash value Death benefit
5 years $100 $0 $159,200
20 years $100 $17,000 $159,200
35 years No payment of premiums after the first 20 years $50,000 $218,000
50 years $129,000 $347,000
70 years $401,000 $634,000

*Illustrative accumulated cash value and death benefit for a $100/month, 20-pay participating whole life insurance policy issued to a healthy 5-year-old boy. Projected cash values and death benefits assume current dividend scales and are not guaranteed; the actual policy values may vary

How much is life insurance per month for couples?

The cost of $500,000 in term life insurance for couples typically ranges from $33 to $550 per month for non-smoking couples and from $76 to $1,283 per month for smoking couples. Couples can choose between two individual life insurance policies or a joint life insurance policy, with the latter potentially offering lower premiums in certain situations. Joint policies also simplify policy management by covering both partners under a single contract. However, individual policies may provide greater flexibility and, in some cases, better value depending on the couple’s coverage needs.

Cost of life insurance in Canada for smoking and non-smoking couples

Age group Monthly premium (Non-smoking couples) Monthly premium (Smoking couples)
35 years $33 $76
45 years $64 $185
55 years $168 $518
65 years $550 $1,283

*Quotes based on a $500,000 joint term policy in coverage for smoker and non-smoker couples in regular health seeking coverage for a 10-year term

Life insurance costs by insurance company

The cost of term life insurance from Canada’s leading insurers typically charges between $14 to over $230 per month for the sample policy shown below. Premium differences occur because each insurer uses its own underwriting guidelines, pricing models, and risk assessment criteria. As a result, two insurers may offer different premiums for the same applicant and coverage amount.

The table below compares illustrative monthly premiums from some of Canada’s leading insurance companies for the same applicant profile.

Life insurance monthly costs by insurer

Applicant age Sun Life Manulife Empire Life Equitable Life Canada Life
20 years Male: $25.20
Female: $16.65
Male: $25.71
Female: $17.06
Male: $22.05
Female: $14.40
Male: $22.04
Female: $14.84
Male: $68.40
Female: $16.19
30 years Male: $25.65
Female: $17.55
Male: $23.28
Female: $16.84
Male: $22.05
Female: $15.30
Male: $22.04
Female: $15.74
Male: $23.38
Female: $16.63
40 years Male: $31.95
Female: $23.40
Male: $29.13
Female: $22.66
Male: $27.00
Female: $19.35
Male: $26.99
Female: $19.79
Male: $29.98
Female: $24.00
50 years  Male: $72.00
Female: $51.30
Male: $67.16
Female: $48.37
Male: $61.65
Female: $45.90
Male: $61.28
Female: $45.89
Male: $67.12
Female: $53.28
60 years Male: $230.85
Female: $161.55
Male: $213.74
Female: $151.20
Male: $199.80
Female: $144.45
Male: $199.78
Female: $144.44
Male: $203.58
Female: $147.43

*Illustrative monthly cost of a 10-year term with $500,000 in coverage for a male/female non-smoker

How does term length affect life insurance premiums?

The cost of term life insurance ranges from about $22 to $144 per month in the example below, depending on your age and the length of the policy. For the same applicant and coverage amount, 10-year term policies are the most affordable, while 20-year and 30-year terms cost more because they provide coverage for a longer period and increase the likelihood of a claim during the term.

Cost of life insurance as per term length

Age 10-year term 20-year term 30-year term
30 years $22.04 $28.80 $42.75
35 years $22.04 $30.15 $53.55
40 years $26.99 $42.75 $85.05
45 years $40.05 $69.30 $143.92

*Illustrative monthly cost of a 10-year, 20-year, and 30-year term life insurance with $500,000 in coverage for a male non-smoker

Do individuals with pre-existing health issues pay higher life insurance premiums?

Yes, individuals with pre-existing health conditions generally pay higher life insurance premiums because they pose a greater risk to insurers. The exact increase depends on the type and severity of the condition, how well it is managed, your age, and the insurer’s underwriting guidelines. In some cases, applicants may still qualify for standard premium rates if their condition is stable and well-managed.

Depending on your medical history, insurers typically make one of the following underwriting decisions:

  • Standard premiums: If your condition is minor, stable, and well-managed, you may qualify for standard rates
  • Higher (rated) premiums: If your condition increases the insurer’s risk, you may be approved with a higher premium or an additional rating applied to your policy
  • Guaranteed issue or no-medical life insurance: If you are declined for traditional life insurance due to a serious medical condition, you may still qualify for guaranteed issue or no-medical life insurance. These policies don’t require a medical exam but generally come with higher premiums and lower coverage limits

How to lower your life insurance premiums?

There are several ways to reduce the cost of your life insurance premiums, such as maintaining a healthy lifestyle, choosing the right policy, comparing quotes from multiple insurers, and more. Listed below are the factors that will help you lower life insurance premiums:

  • Buy life insurance early: Purchasing a policy when you are younger and in good health can help you lock in lower premiums for the duration of your coverage.
  • Quit smoking: Most insurers offer significantly lower premiums to applicants who have remained tobacco-free for at least 12 months
  • Maintain good health: Managing your weight, blood pressure, and other health conditions can improve your eligibility for preferred rates
  • Choose the right coverage amount: Buy enough coverage to meet your financial needs without paying for more insurance than necessary
  • Opt for term life insurance: If you only need coverage for a specific period, term life insurance is generally much more affordable than permanent life insurance
  • Consider laddering life insurance policies: Instead of purchasing one large policy, you can combine multiple term life policies with different coverage amounts and durations. This allows your coverage to decrease as your financial obligations reduce, helping lower overall premium costs.
  • Choose riders carefully: Only add optional riders, such as critical illness, child, or disability riders, if they meet a specific need. Unnecessary riders can increase your premium
  • Select a shorter policy term: Shorter term lengths usually cost less than longer-term policies with the same coverage amount
  • Pay your premiums annually: You may reduce your overall cost when you pay annually instead of making monthly payments
  • Compare quotes from multiple insurers: Compare and find the best life insurance policy for your needs

To get the most affordable life insurance quotes, reach out to our expert advisors at PolicyAdvisor. Our advisors will help you get quotes from the top life insurance providers in Canada and choose the one that best fits your needs and budget.

Looking for expert assistance?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently Asked Questions

What are life insurance premiums?

Life insurance premiums are the payments policyholders make to maintain their coverage. They can be paid monthly, quarterly, or annually, depending on the policy. The cost of your premium will be based on factors like age, health, smoking status, coverage amount, policy type, and the insurer.

What is the average cost of life insurance in Canada?

The cost of life insurance in Canada starts at around $7 per month for a healthy young adult purchasing a basic term insurance policy. The premiums can range from $7 to over $3,276 per month, depending on your age, health, coverage amount, policy type, and insurer.

What is the cheapest life insurance in Canada?

Term life insurance is generally the cheapest life insurance in Canada. Because it provides coverage for a fixed period and does not build cash value, premiums are significantly lower than those for whole life or universal life insurance.

Why are life insurance premiums different for men and women?

Life insurance premiums are generally higher for men because, on average, men have a shorter life expectancy than women. Insurers use actuarial data to estimate risk, which results in lower premiums for female applicants with similar health and lifestyle profiles.

Is it cheaper to buy life insurance when you are younger?

Yes, buying life insurance at a younger age usually results in lower premiums because younger applicants generally have fewer health risks and a longer life expectancy. Purchasing coverage early can help lock in lower rates for the duration of your policy.

Can I get life insurance without a medical exam?

Yes, many insurers offer no-medical or simplified issue life insurance that does not require a medical exam. These policies are easier and faster to obtain but usually have higher premiums and lower coverage limits than fully underwritten life insurance.

How much life insurance do I need?

The amount of life insurance you need depends on your income, financial obligations, and future goals. While it is recommended to get coverage equal to 10-15 times your annual income, the ideal amount varies based on factors such as your mortgage, outstanding debts, living expenses, your children’s future education costs, and any existing savings or life insurance coverage. The easiest way to determine the right amount is to use our life insurance calculator, which estimates your coverage needs based on your unique financial situation and helps you choose a policy that provides adequate protection for your loved ones.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How to Use Whole Life Insurance to Build Wealth: An Investment Guide

Whole life insurance is a powerful financial tool that combines lifelong coverage with a cash value component that can be used to achieve various financial goals. By leveraging the cash value policyholders can supplement their retirement income, plan their estates, and even grow their business. In this blog, we’ll answer a question many Canadians ask: how to use whole life insurance to create wealth.

Whether you’re looking to enhance your financial portfolio or secure your family’s future, a whole life policy can help you achieve both these goals. 

What is your Whole Life Insurance worth?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Why do you need life insurance?

Life insurance is essential for ensuring your loved ones are financially secure in the event of your unexpected passing. A life insurance policy can help cover expenses such as:

  • Funeral costs
  • Outstanding debts
  • Mortgages
  • Daily living expenses
  • Children’s education
  • Retirement planning 

A life insurance policy is a versatile financial tool that brings financial protection and peace of mind to you and your loved ones. 

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

How does whole life insurance work as an investment?

A whole life policy can help build wealth because of the two key components it offers: cash value for both participating and non-participating policies, and dividends for participating policies only. Policyholders can leverage either of these two components to create a source of income for various financial goals, supplement retirement income, fund large expenses, and even invest in new businesses. 

The cash value component and dividends (for participating policies) can be accessed in different ways. The cash value can be:

  • Withdrawn 
  • Accessed as a policy loan
  • Used as a loan collateral

Withdrawing the cash value and taking a policy loan can be taxable if the amount exceeds the policy’s true value. When you use it as a loan collateral with a third party lender, it is not taxable. 

Accessing cash value and its implications

Cash withdrawal  Policy loan Collateral loan
Ideal for Policyholders who want a small amount of cash for immediate use, and who may not intend to repay it Policyholders who want a larger amount of cash and want to avoid a loan from a bank or other lender Policyholders who want a large amount of cash and are comfortable with debt 
Cash withdrawal/loan limit Limited to the available non-guaranteed cash value 90% of available cash value 100% of available cash value
Intention to repay Never Typically in the short-term At death
Tax implication Taxable if the withdrawal amount exceeds the policy’s true value Taxable if the withdrawal amount exceeds the policy’s true value Not taxable 

Dividends on the other hand can be used in two different ways:

  • Policyholders can reinvest the dividends into their policy (enhanced protection and paid-up additions)
  • Get paid in cash or hold on deposit 

When the dividends are reinvested into the policy, they are not liable to any taxes. If the policyholder chooses to get paid in cash or hold the dividend payout on deposit, it is subject to taxes. 

Accessing dividends and how it impacts the policy

Feature Reinvest dividends Receive dividends in cash or hold on deposit
Purpose Increase policy value through enhanced protection or paid-up additions Provide liquidity for immediate use or savings
Impact on policy Boosts the death benefit and cash value of the policy No impact on the policy’s value
Tax implications Not taxable when reinvested into the policy Subject to taxes if received as cash or held on deposit
Ideal for Policyholders looking for long-term growth and enhanced financial security Policyholders seeking additional income or liquidity
Flexibility Funds stay within the policy and contribute to future growth Offers immediate access to funds for any purpose

Find a whole life plan that works for you!

Speak to one of our advisors and get a customized whole life insurance plan that offers lifelong protection! 

Whole life insurance for estate tax funding

When you pass away, it is assumed that you have disposed of all your assets and an executor will be required to pay any taxes before your estate is distributed among your beneficiaries. These assets include any Registered Retirement Savings Plan (RRSPs), capital gains, and more. 

The substantial value of these assets are also subject to the highest tax rates. Paying off these taxes significantly reduces the value that your beneficiaries get. 

If you pass away with an active whole life insurance policy, your beneficiaries (such as surviving family members) receive a tax-free cash payout from your insurance company. This payout is not considered part of your income or your beneficiaries’ incomes and is not taxed as such when you pass. This is because you paid your life insurance premiums using funds on which you paid income tax as well.

The payout from your whole life insurance policy offsets the taxes on your estate and provides immediate liquidity to meet any other estate settlement costs. 

Learn more about estate planning with life insurance

Retirement planning with whole life insurance

While the primary purpose of a whole life policy is the death benefit, retired individuals can use the cash value component and the dividends to supplement their income. The cash value serves as an emergency fund that can be used for medical emergencies, paying off debt, travelling post retirement, children’s weddings or education, and more.

The dividends can be reinvested in the policy to increase the death benefit and to buy additional coverage. This will enhance the legacy a policyholder leaves for their loved ones. Depending on the dividend strategy, policyholders can also access it as cash when required. 

Using whole life insurance for businesses

Whole life insurance offers several benefits for business owners, including key person insurance, funding a buy-sell agreement, and serving as collateral for a business loan. A whole life policy ensures the stability and continuity of business operations. Here’s how:

Using whole life insurance for a business

Aspect Purpose Benefit
Key person insurance Protects the business against financial losses that could

result from the death of a key employee or owner

Provides the business with a death benefit to cover the costs

of finding and training a replacement, offsetting lost revenue, and

maintaining business operations during the transition period

Funding buy-sell agreements Facilitates the smooth transfer of business ownership in the

event of an owner’s death

Ensures that the remaining owners can buy out the deceased

owner’s shares without financial strain

Collateral for business loans Provides a means to secure financing for business operations

or expansion

The policy’s cash value can be used as collateral to obtain

business loans, potentially at more favorable terms

Diversify your investment portfolio

A whole life insurance policy is a reliable way to diversify your investment portfolio. It offers stability and guaranteed cash value growth and death benefit, making it a more stable investment as compared to market-dependent assets. 

Whole life insurance keeps you protected against market volatility especially during downturns. 

Get affordable whole life insurance.

Compare and get the best plans!

What is whole life insurance?

Whole life insurance is a type of permanent life insurance that offers lifelong coverage, has a death benefit, and a cash value component, all of which remain active as long as premiums are paid. With its investment component, a whole life policy offers a unique blend of stability, growth, and flexibility, making it a powerful financial product. 

The death benefit is the amount paid to beneficiaries upon the insured’s death, while the cash value is a savings feature that grows over time, offering guaranteed returns. 

Key features of whole life insurance

The features of a whole life insurance policy can be different based on whether it’s a participating or non-participating policy. Participating policies allow policyholders to receive dividends, which can be used to reduce premiums, purchase additional coverage, or be taken as cash.

These dividends are not guaranteed but depend on the insurer’s financial performance. In contrast, non-participating policies do not offer dividends but often come with fixed premiums and guaranteed benefits, providing more predictable coverage.

Both types offer lifelong protection and a cash value component, but the choice depends on individual financial goals and risk preferences.

Features of a participating vs. non-participating whole life policy

Feature Participating Life Insurance Non-Participating Life Insurance
Definition Offers dividends to policyholders based on the participating account’s performance  Does not provide dividends; only offers guaranteed death benefits
Premiums Higher due to the potential for dividends and additional benefits Lower as it only includes guaranteed benefits and no profit-sharing
Dividends Policyholders may receive dividends No dividends are paid to policyholders
Cash Value Growth Cash value grows faster Cash value grows at a fixed rate
Suitability Suitable for individuals seeking long-term growth Ideal for those wanting a straightforward, cost-effective policy

Read more about how a whole life insurance policy works in Canada
Get a whole life policy that suits your needs!

Book some time with our licensed experts!

Whole life insurance vs other investment options

When compared to other investment options such as stocks, bonds, or real estate, whole life insurance proves to be a lower risk choice. This is because of the guaranteed cash value and dividends (in case of participating policies). 

Here is how whole life insurance compares to other investment options:

Whole life insurance vs other investments

Feature Whole Life Insurance Stocks Bonds Real Estate
Market dependency Not dependent on market performance Highly dependent on stock market performance Dependent on interest rate environment Dependent on real estate market conditions
Risk level Low risk High risk, subject to market volatility Low to moderate risk, depends on issuer Moderate to high risk
Cash value  Guaranteed, grows tax-deferred Potential for high returns, but with high volatility Fixed returns, generally lower than stocks Potential for appreciation, but can be unpredictable
Liquidity Moderate, can borrow against or withdraw from cash value High, can sell stocks quickly Moderate, can sell bonds, but may incur penalties Low to moderate, depends on market conditions
Tax implications Cash value grows tax-deferred; death benefit is tax-free Capital gains tax on profits Interest income taxed as ordinary income Capital gains tax on property sales; rental income taxed
Income generation Can borrow against cash value or withdraw for income Dividends, selling stocks Interest payments Rental income or profits from sale
Protection / Guarantee Death benefit is guaranteed No guarantees, subject to market risk Principal and interest typically guaranteed No guarantees, subject to market risk
Ease of Access Accessible via loans or withdrawals, but may reduce benefits Easily accessible, can trade on stock exchanges Accessible but may involve penalties for early withdrawal Low accessibility; selling property takes time

Can you make money on whole life insurance?

Yes, you can make money on a whole life insurance using the cash value and/or the dividends your policy generates. Both cash value and dividends are living benefits and can be accessed in different ways. 

While the cash value is technically a portion of your death benefit, accessing it as a policy loan that you repay will ensure your policy’s value remains intact. You can use your cash value to for any small or large financial needs such as:

  • Medical emergencies
  • Weddings 
  • Children’s education
  • Supplementing retirement income 
  • And more

The dividends can either be reinvested into the policy or taken as cash or deposit. If you take the dividends as cash or deposit, they may be subject to tax. Dividends can be used for similar purposes as cash value. 

Do wealthy people use whole life insurance?

Yes, wealthy people use whole life insurance to grow, protect, and transfer their wealth. The death benefit from a whole life policy is tax-free, making it an ideal inheritance for the wealthy. High-net worth individuals with a whole life policy that has a significant cash value component can use it to invest in their businesses, take out a collateral loan, plan their estates, and more.

Common misconceptions about whole life insurance

Whole life insurance is often misunderstood due to its complex nature and the different investment options it offers. Some of the common misconceptions about whole life insurance are:

  • It is too expensive: The high premiums of a whole life policy include the death benefit and the cash value or dividends. The investment components also grow in a tax-deferred manner, offsetting the high initial premium costs
  • Other investment options are better: Unlike stocks, bonds, mutual funds, and real estate, whole life insurance is not subject to market risks. It is a less volatile investment option
  • Whole life insurance is for the wealthy: This is a common misconception owing to the high premiums. But whole life insurance is for anyone who is looking for lifelong protection with guaranteed returns

How long does it take to build up money in a whole life insurance policy?

A whole life insurance policy typically starts building cash value after a few years, often around the second or third year of the policy. In the early years, most of the premium payments go toward covering the cost of insurance and administrative fees.

The growth of cash value depends on the policy’s design, premium payments, and investment performance within the insurer’s portfolio. The timeline varies based on the policy structure and premium allocation.  

  • Early years: Some cash value is generated, but most of the premium amount goes towards administrative costs 
  • 3-5 years: Cash value begins accumulating meaningfully
  • 10+ years: Cash value growth accelerates, benefiting from compound interest

Start building wealth with whole life insurance

A whole life insurance policy is more than just a safety net for your loved ones—it is a versatile financial tool that offers guaranteed growth while you are alive. If you want to build wealth with a whole life policy but are unsure of how to go about it, schedule a call with one of our licensed advisors. 

Build wealth with a whole life policy!

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

How can I use the cash value of my whole life insurance policy to fund my retirement?

The cash value of your whole life policy can supplement your retirement income and help meet immediate financial goals. It can be accessed through loans or withdrawals to maintain your lifestyle post retirement, travel, and more. 

What are the best strategies to create generational wealth with whole life insurance?

Whole life insurance can create generational wealth by providing a guaranteed, tax-free death benefit to your heirs. You can also use it to fund trusts or cover estate taxes, ensuring your assets are passed on intact. Additionally, reinvesting dividends and growing the cash value increases the policy’s long-term financial benefits, securing wealth for future generations.

How does whole life insurance compare to other investment options for wealth building?

Whole life insurance offers guaranteed returns, tax advantages, and lifelong coverage, making it a low-risk, stable component of a diversified financial plan. Unlike stocks or real estate, it is not subject to market volatility and provides a predictable way to build wealth.

Can I use whole life insurance to fund my children’s education expenses?

Yes, the cash value of a whole life insurance policy can be accessed to fund education expenses. You can withdraw or borrow against the cash value to pay for tuition, books, or other costs.

What are the tax implications of borrowing against the cash value of a whole life insurance policy?

Borrowing against the cash value is generally tax-free as long as the policy remains in force. However, if the policy lapses or is surrendered, the loan amount exceeding the adjusted cost basis may become taxable as income. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Canada Life whole life insurance review (2026)

Canada Life’s participating life insurance policies maintain a dividend scale interest rate of 6.00%. Additionally, Canada Life has consistently paid dividends for over 170 years, and its participating account has never missed a distribution year. This is a remarkable record that reflects the insurer’s financial resilience and reliability across economic cycles.

In this review, we explore Canada Life’s whole life insurance offerings, that provide lifelong protection, guaranteed cash value accumulation, and long-term dividend potential.

Best for charitable giving
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Plans offered
Estate Select
Wealth Select
My Par Gift
Average term life cost
10-pay
20-pay
pay-to-100
A.M. Best financial strength rating
A+
Dividend Scale Interest Rate (DSIR)
6.00%

PolicyAdvisor rating

Canada Life whole life insurance earns a 4 out of 5 rating from PolicyAdvisor. It is a leading choice for Canadians who want to use whole life insurance to support charitable giving. Its My Par Gift plan is specifically designed for charitable contributions, with a single premium and cash value starting from year one. It is also known for its long history of dividend payments, a large and financially strong participating account, and disciplined long-term financial management.

Canada Life’s participating plans share in company earnings through annual, non-guaranteed dividends. Dividends depend on participating account investment returns, insurance claims, expenses, taxes, lapses, policyholder behaviour, and surplus management. Each year, Canada Life’s Board of Directors reviews and approves the dividend scale for the following policy year.

Canada Life participating account financials:

  • Participating account size: $59.2 billion in total assets
  • Policies in force: 1.4 million participating life insurance policies
  • Participating account surplus: $3.06 billion
  • Dividend history: Dividends paid to participating policyowners since 1848
  • Participating account structure: Canada Life operates the largest combined open participating account in Canada
  • Dividend drivers: investment experience, mortality experience, expenses, taxes, lapses, withdrawals, and policy terminations

Canada Life’s long dividend history and sizable participating account support stable long-term performance. However, like all insurers, dividends are not guaranteed and can increase or decrease depending on annual experience.

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Canada Life offers two participating whole life options

  • Estate Select: A traditional participating whole life policy focused on long-term guarantees and stable estate protection
  • Wealth Select: A participating whole life policy designed for higher early cash value growth, long-term accumulation, and estate enhancement potential

Both plans provide lifetime coverage with guaranteed base values and the opportunity to enhance policy value through dividends.

Source: Canada Life Financial Facts 2024

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Canada Life whole life insurance costs and value

This example shows the projected premiums, cash value growth, and death benefit for a 30-year-old non-smoker female purchasing $100,000 of Canada Life whole life coverage with life pay and enhanced paid-up additions.

Projected premiums, cash value, and death benefit over time


Policy Year Age Annual premium paid Total premiums paid Total cash value Death benefit
0 30 $800.00 $800.00 $0 $100,000.00
10 40 $800.00 $8,000.00 $1,745 $100,000.00
20 50 $800.00 $16,000.00 $13,419.00 $100,000.00
30 60 $800.00 $24,000.00 $36,739.00 $100,000.00
40 70 $800.00 $32,000.00 $68,267.00 $121,507.00
50 80 $800.00 $40,000.00 $118,346.00 $164,409.00
55 85 $800.00 $44,000.00 $151,779.00 $192,112.00
60 90 $800.00 $48,000.00 $190,882.00 $224,144.00


* Values shown are non-guaranteed illustrations based on current assumptions and the insurer’s dividend scale. Actual premiums, cash values, and death benefits may vary. This example is for informational purposes only and does not constitute a policy guarantee.

What are the benefits of Canada Life’s whole life insurance?

Canada Life’s whole life policies provide lifelong coverage while building guaranteed cash value that you can use during your lifetime. They also allow you to pay off your policy quickly (in 10 or 20 years) or spread payments over a longer period of time (until age 100). Key benefits include:

  • No maximum coverage: Canada Life’s whole life policies have no set upper limit, meaning you can get as much coverage as you need. However, amounts over $50 million require special underwriting
  • Four dividend options: Dividends can be received in the form of cash payments, premium reductions, paid-up additions, and enhanced insurance
  • Additional deposit option (ADO): You can increase your policy’s coverage and cash value by making extra payments. However, ADO is subject to MTAR limits, so excess payments may be restricted once the policy is close to the tax-exempt shelf
  • Flexibility with premium offset: You can cover some or all of your premium payments using dividends. However, you must bear in mind that premium offset is not guaranteed and depends on investment performance, interest environment, and company experience
  • Children’s term life insurance rider: You can include term life insurance on your children with these policies. Future children are added at no additional cost until you turn 55

When it comes to coverage, Canada Life offers several options, including:

  • Single life: Covers one person and pays a death benefit upon their passing
  • Joint-first-to-die: Covers two people and pays a death benefit when the first insured person dies. The surviving person remains covered for an additional 60 days, during which they can buy a new policy on their life, with no underwriting
  • Joint-last-to-die (premiums to first death): Covers two people with premiums payable until the death of the first insured person. Premium payments are higher under this plan
  • Joint-last-to-die (premiums to last death): Covers two people with premiums payable until the death of the second insured person. Premium payments are lower under this plan

Types of whole life insurance offered by Canada Life

Canada Life offers two participating whole life policies with lifetime coverage, cash value growth, and annual dividends. Here’s how they differ:

  • Estate Select: Provides higher cash value and payout in later years and is ideal for parents looking to secure their children’s future
  • Wealth Select: Offers early cash value growth and is ideal for business owners seeking near-term liquidity
Key features of Canada Life’s Estate Select and Wealth Select plans


Category Estate Select Wealth Select
Premium type Fixed, with flexible payment options (Max 10, Max 20, and Pay to age 100) Fixed, with flexible payment options (Max 10, Max 20, and Pay to age 100)
Coverage amount range $25,000 to no maximum $100,000 to no maximum
Dividend options
  • Cash payment
  • Premium reduction
  • Paid-up additions
  • Enhanced coverage
  • Cash payment
  • Premium reduction
  • Paid-up additions
  • Enhanced coverage
Policy loan availability Allow loans from cash value. However, ADO premium payments are paused while a loan is active. They resume after full repayment Allow loans from cash value. However, ADO premium payments are paused while a loan is active. They resume after full repayment
Payment flexibility Monthly or annually Monthly or annually
Living benefits
  • Cash withdrawal
  • Policy loan
  • Collateral loan
  • Premium offset
  • Cash withdrawal
  • Policy loan
  • Collateral loan
  • Premium offset
Additional riders Accidental death benefit, waiver of premium benefit, guaranteed insurability rider, business growth protection rider (if policy corporately-owned), and child’s term life insurance rider Accidental death benefit, waiver of premium benefit, guaranteed insurability rider, business growth protection rider, and child’s term life insurance rider


Source: Canada Life  

What are the pros and cons of Canada Life’s whole life insurance?

Canada Life’s whole life policies offer several benefits, from unlimited coverage to multiple payment and dividend options. However, they also have some limitations. Let’s take a closer look at them:

Advantages and disadvantages of Canada Life’s whole life insurance policy


Pros Cons
Offers unlimited coverage based on your needs (special quote needed for amounts over $50M) Under the joint-last-to-die (first death) plan, Additional Deposit Option (ADO) payments stop after the first insured person’s death. That means the survivor can no longer enhance their policy using ADO contributions
Includes term life insurance rider for children that covers future children at no additional cost (until you turn 55) Premium offset availability depends on the participating account’s earnings
Offers flexibility to increase coverage and cash value through the additional deposit option (ADO) Canada Life has the lowest dividend rate compared to other insurers
Allows you to offset some or all of your premiums using dividends 

See how Canada Life compares to other whole life insurance providers in Canada

Highlights of Canada Life’s whole life insurance policy document

A Canada Life whole life insurance policy document (for Estate Select or Wealth Select) typically includes the following core sections and details:

  • Policyholder and insured information: Names, birth dates, and identifying information for the policy owner and the insured person
  • Coverage amount: The face amount payable as the death benefit, along with any additional coverage or riders selected.
  • Premium schedule: The premium amount, payment frequency (monthly, annual, etc.), and payment duration (10-pay, 20-pay, or to age 100). This section also outlines grace periods and the consequences of missed payments
  • Dividend options: The available choices for using annual dividends, such as receiving them in cash, reducing premiums, purchasing paid-up additions, or selecting enhanced coverage
  • Guaranteed values: Tables showing the annual buildup of guaranteed cash value and death benefit. Non-guaranteed values based on current dividend scales are also typically included
  • Policy loans and withdrawals: Rules for accessing cash value, including loan interest rates and how additional deposits are treated if a policy loan is active
  • Riders and optional benefits: Information on add-on features such as children’s term insurance, accidental death benefits, waiver of premium, and guaranteed insurability, along with the conditions for each
  • Beneficiary designation: Instructions for naming or changing beneficiaries and an explanation of revocable versus irrevocable beneficiary status
  • Plan structures: Details on whether the contract is single life, joint-first-to-die, or joint-last-to-die, and any related privileges such as survivor purchase rights
  • Termination and surrender conditions: Requirements and outcomes if the policy is cancelled or surrendered, including any surrender charges and the cash value payable to the owner
  • Investment and participating account disclosure: Information on how premiums are invested within the participating account and how dividends are determined for policyholders
  • Other legal provisions: Definitions, limitations, exclusions, such as the suicide clause, incontestability rules, reinstatement rights, and instructions on how to submit a claim

These sections are designed to give policyholders clear disclosure of their coverage, obligations, and available options throughout the life of a Canada Life whole life insurance policy.

What are the different limited-pay options offered by Canada Life?

Canada Life offers its participating whole life policies (Estate Select and Wealth Select) with three standard premium payment structures: 10-pay, 20-pay, and pay-to-age-100. The first two are true limited-pay designs, while pay-to-100 is a lifetime premium schedule that is often grouped with them as a third option.

  • Max 10 (10-pay): All required premiums are paid over 10 years. After year 10, the base policy is fully paid-up as long as no new riders or additional deposits are added
  • Max 20 (20-pay): Premiums are level and payable for 20 years. After year 20, the base policy becomes paid-up for life
  • Pay to age 100: Premiums remain level and continue until age 100. This is not a limited-pay option in the strict definition, but it is one of the three standard payment patterns available

Estate Select and Wealth Select can be issued using any of the three premium schedules (Max 10, Max 20, or pay-to-100) for both single-life and joint-life structures. Policyholders can later use features such as premium offset, where dividends cover ongoing premiums, to reduce or eliminate out-of-pocket payments. Contractually, however, the three payment structures listed above are the available choices at issue.

What are the different whole life dividend options that Canada Life offers?

Canada Life offers four dividend options that allow policyholders to customize the performance of their participating whole life insurance to their financial goals.

  • Cash payments: Dividends can be received as cash payouts, providing immediate flexibility, though the amount received may be taxable depending on the policy’s adjusted cost basis
  • Premium reductions: Dividends can reduce or eventually eliminate out-of-pocket premiums through a premium-offset strategy, depending on long-term dividend performance
  • Paid-up additions: Many policyholders reinvest dividends to buy paid-up additional coverage, which increases the death benefit, guaranteed cash value, and future dividend-earning potential, helping the policy compound over time
  • Enhanced coverage: This option combines paid-up additions with a term insurance component, offering higher early protection while gradually transitioning to permanent paid-up coverage as the policy matures

How are dividends for Canada Life’s participating policies distributed

Dividends in Canada Life’s participating policies are distributed based on the earnings of the participating (or “par”) account. This account combines premiums from all participating policyholders and invests them in a diverse portfolio of assets.

“Par” account earnings depend on several factors, including investment returns, policy cancellations, insurance claims, and operational costs. When the account outperforms expectations, Canada Life shares the excess earnings with policyholders through dividends. 

While dividends are not guaranteed and can vary, Canada Life has a strong track record of maintaining its dividend scale, having paid annual dividends at an interest rate of 5.25% to 6.00% over the past few years.

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%

How are Canada Life whole life insurance premiums invested?

When you pay premiums into a Canada Life participating whole life policy, they are pooled into the company’s participating account. Canada Life manages this account with two goals:

  • Long-term stability
  • Returns that respond to economic conditions

The account uses a disciplined asset–liability matching strategy to ensure that investment income can reliably support guarantees, cash values, and dividends.

Canada Life participating account: Asset mix (June 30, 2025)


Asset class % of Account What it means for policyholders
Fixed income (Total 60.0%) Stable returns that support guarantees
Public bonds 28.3% Long-term stability and predictable income
Private placements 14.9% Higher yield with controlled risk
Mortgages 9.8% Strong cash flow and diversification
Cash & equivalents 7.0% Liquidity for claims and guarantees
Non-fixed income (Total 30.7%) Helps support future dividend potential
Public equity 13.7% Market growth participation
Real estate 12.3% Inflation hedge and rental income
Private equity 4.7% Long-term growth with low correlation
Other assets 9.3% Derivatives and other holdings used for risk management


Source: Canada Life Combined Open Participating Account – June 30, 2025

Affordable Coverage for You and Your Loved Ones

Find the lowest whole life insurance rates in Canada within minutes!

Are “par” account investments affected by market conditions?

Yes. While Canada Life employs a long-term investment strategy and “smoothing” mechanism to spread investment gains and losses over several years, changes in interest rates, stock prices, and real estate can still affect the “par” account’s investments.

How can I access my Canada Life whole life cash value?

You can access your policy’s cash value through:

  • Cash withdrawals: You can withdraw part or all of your cash value. A full withdrawal will result in your policy’s cancellation
  • Policy loans: You can borrow against your cash value. However, you won’t be able to make Additional Deposit Option (ADO) payments while your loan is active
  • Collateral loan: You can use your policy as collateral for a loan 
  • Premium offset: If you have enough cash value, you can use it to pay part or all of your due premiums

What additional benefits or riders does Canada Life offer on their whole life plans?

Canada Life offers several additional benefits or riders on its whole life policies, including:

  • Total disability insurance benefit: Covers required premium payments if the insured experiences certain disabilities. To qualify, the insured must be 18 or older when the policy is issued
  • Accidental death benefit: Provides a higher payout if death is caused by certain types of accident. This can help beneficiaries manage unexpected payments that may arise due to the covered accident
  • Waiver of premium benefit: Covers required premium payments if the insured under this benefit becomes disabled 
  • Guaranteed insurability rider: Allows you to obtain new permanent policies on the insured person without medical underwriting
  • Business growth protection rider: Allows you to purchase additional permanent policies on the insured person over a 10- or 15-year period
  • Children’s term life insurance rider: Provides term life insurance coverage for your children, including adopted and stepchildren. Future children are automatically added at no additional cost until you turn 55
See how Canada Life compares to the best whole life insurance providers in Canada

How to apply for Canada Life’s whole life insurance with PolicyAdvisor?

You can get a personalized whole life insurance quote for Canada Life through PolicyAdvisor, where you can compare different plans and policies from Canada’s top providers. Schedule a free consultation with our licensed advisors to explore the best options to protect your legacy.

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Is Canada Life’s whole life insurance worth it?

If you want lifelong protection with cash value growth that you can access in many ways, a whole life policy could be a smart choice. However, premiums for whole life insurance are generally higher than those for term life and may exceed some budgets.

Does Canada Life offer participating policies with dividends?

Yes. Canada Life offers two participating whole life policy plans, Estate Select and Wealth Select, with flexible payment options.

Do I need medical underwriting for a Canada Life whole life insurance plan?

Yes, Canada Life requires medical underwriting for new whole life insurance policies. However, if you already have whole life insurance, you can enhance your coverage using the Guaranteed Insurability Rider, without any underwriting.

How does the Canada Life participating account work?

Canada Life’s participating account pools premiums from all participating policyholders and invests them in a diversified portfolio of assets. The account’s earnings are influenced by various factors, including investment returns, mortality claims, policy cancellations, and operational expenses. When the account’s earnings exceed expectations, the surplus is distributed among policyholders as dividends.

What is the children’s term life insurance rider?

The children’s term life insurance rider is an optional add-on to Canada Life’s whole life insurance policies. It provides term life coverage for your biological, adopted, and stepchildren. Future children are automatically covered at no additional cost until you turn 55.

What happens if I stop paying my premiums?

If you miss a payment on your Canada Life whole life insurance policy, you have 31 days to make it up. If the premium remains unpaid after this period, Canada Life will automatically take out a policy loan on your behalf, provided your policy has enough cash value. This loan will keep your policy active as long as there’s sufficient cash value to cover future premiums and interest charges.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Equitable whole life insurance review (2026)

Equitable Life is one of Canada’s strongest mutual insurers, recognized for disciplined investment management, consistent dividend performance, and a clear focus on policyholder value. 

The company’s 10-year average DSIR is approximately 6.24%, underscoring its reliability and competitive long-term cash value performance. In 2025, the company maintained a 6.40% dividend scale interest rate for its participating policies. This dividend scale rate remains unchanged from the previous year and is one of the highest among Canadian participating insurers, which may support steady cash value growth for policyholders.

In this review, we’ll explain how Equitable’s whole life insurance plans work, their key benefits, features, dividend performance, and why the company remains a top choice for Canadians looking to balance protection with long-term financial growth.

Best for mutual company
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Plans offered
Equimax Estate Builder
Equimax Wealth Accumulator
Payment options
10-pay
20-pay
pay-to-100
A.M. Best financial strength rating
N/A
Dividend Scale Interest Rate (DSIR)
6.40%

PolicyAdvisor rating

Equitable whole life insurance earns a 5 out of 5 rating from PolicyAdvisor for its mutual ownership structure, competitive dividend scale, and long-term focus on policyholder value. As a Canadian mutual life insurer, Equitable distributes profits back to participating policyholders rather than external shareholders, reinforcing long-term stability and strong participating performance.

Equitable’s participating whole life policies share in the company’s profits through annual dividends. The Dividend Scale Interest Rate reflects the participating account’s investment performance and is used to help determine dividend payments, which are not guaranteed and are declared at the sole discretion of Equitable’s Board of Directors each year.

Equitable’s participating account highlights (2025–2026):

  • Estimated par block assets: $2.7 billion (largest Canadian mutual)
  • Dividend scale interest rate (DSIR): 6.40% 
  • Par policyholders: 312,000+
  • Expected dividends paid to policyholders: ~ $175 million  
  • Par business history: 102 years with uninterrupted participating business
  • Dividend on deposit interest rate: 3.50%  
  • Policy loan interest rate: ~ 6.50% for most Equimax policies with qualifying policy numbers  
  • Dividends are not guaranteed and vary based on investment performance, mortality experience, expenses, and other participating account factors

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Equitable offers two participating whole life plan options under the Equimax product line:

  • Equimax Estate Builder®: Designed for long-term value and legacy goals
  • Equimax Wealth Accumulator®: Designed for earlier cash value accumulation and financial flexibility

Equitable participating policies offer multiple premium payment options, including lifelong premiums, 20-pay, and 10-pay structures, giving policyholders flexibility to match their financial planning needs.

Rating methodology

PolicyAdvisor rates Equitable whole life insurance 5/5 based on factors similar to those used for other participating products including mutual company advantages, dividend scale stability, long-term cash-value performance, premium payment flexibility, participating account strength, and available riders.

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%

What are the key features of Equitable’s whole life insurance?

Equitable offers participating whole life insurance for individuals looking to safeguard their financial future. These insurance options can be availed by individuals within 80 years of age and have a minimum coverage range of $10,000 (for single policies). Policy loans and dividends are available in Equitable’s whole life insurance, with varying degrees of tax advantage. Find out more below:

Key features of Equitable whole life insurance 


Category Details
Policy type Whole life insurance 
Cash value accumulation Available. Can be accessed after the first year of purchasing the policy
Maximum issue age 80 years
Coverage amount range $10,000 to no maximum
Dividend options Paid-up additions, enhanced protection, or paid in cash/held on deposit
Policy loan availability Available
Tax benefits Tax-advantaged growth of cash value
Payment options Life pay, 10 years, and 20 years payment options available
Additional riders Disability waiver of premium, critical illness, Excelerator Deposit Option (EDO)


Additional policyholder support (KIND program)

New Equimax participating whole life policies include Equitable’s built-in KIND program. It provides compassionate and snap advances, access to policy cash value in cases of severe disability, and bereavement counselling benefits.

What is Equimax by Equitable?

Equimax is Equitable Life’s flagship participating whole life insurance product, designed to provide lifelong protection while steadily building cash value. It combines guaranteed coverage and level premiums with the potential for long-term financial growth through annual participating dividends.

Equimax is available in two plan options tailored to different financial goals: Equimax Estate Builder®, ideal for long-term wealth transfer and legacy planning, and Equimax Wealth Accumulator®, suited for individuals or business owners seeking higher early cash values and financial flexibility.

How does Equimax’s participating whole life insurance work?

Equitable Life’s Equimax participating whole life insurance combines guaranteed lifelong protection with long-term growth through dividends. It’s designed for clients who want both security and a financial asset that builds value over time.

Here’s how the plan works:

  • Permanent life insurance coverage: This type of policy provides lifetime protection with guaranteed premiums and death benefits, ensuring stability for estate and wealth transfer goals
  • Guaranteed cash value: Equitable whole life builds cash value over time within the policy. Wealth Accumulator begins accumulating cash value early, while Estate Builder focuses on stronger long-term growth
  • Participating policy and dividends: As a participating plan, Equimax is eligible to receive annual dividends based on the performance of Equitable Life’s participating account, which reflects factors like investment returns, expenses, and mortality experience
  • Dividend options: Policyholders can choose how to use their dividends, receive them in cash, keep them on deposit to earn interest, buy paid-up additions (PUAs) for more coverage, or apply them to reduce premiums. The Enhanced Protection Option, available only at issue, combines PUAs with a one-year term addition for extra coverage flexibility
  • Premium payment choices: Equitable offers flexible payment schedules-10 Pay, 20 Pay, or Pay to Age 100. Once the payment period ends, coverage remains in force for life
  • Access to cash value: Policyholders can access built-up cash values through loans or withdrawals. Cash value can also serve as collateral for financing needs, though such actions may affect future dividends or death benefits
  • Mutual company advantage: As a mutual insurer, Equitable Life operates without shareholders, meaning participating policyholders share in the company’s long-term success through dividends and stable account management
Read more about how a whole life insurance policy works in Canada

What are the different Equitable whole life insurance plans to choose from?

Equitable Life offers two participating whole life insurance plans under its Equimax product line, Equimax Estate Builder and Equimax Wealth Accumulator. Both plans offer lifetime coverage and the opportunity to build guaranteed cash values, but they cater to different financial goals.

  • Equimax Estate Builder is designed for clients focused on long-term value, estate planning, and wealth transfer. It provides higher death benefits and steady cash value growth, making it ideal for individuals who want to leave a lasting financial legacy or support charitable giving
  • Equimax Wealth Accumulator offers stronger early cash value growth and greater liquidity in the initial years. It’s suited for clients or business owners who may need access to cash value earlier for opportunities like funding education, buying property, or investing in a business
Key differences between Equimax Estate Builder and Equimax Wealth Accumulator


Category Equimax Estate Builder® Equimax Wealth Accumulator®
Primary focus Designed for long-term estate planning, wealth transfer, and legacy growth Focused on higher early cash values and short-to-medium-term liquidity
Ideal for Individuals and families aiming to grow and transfer wealth tax-efficiently Business owners or professionals who value early access to cash within 20 years
Cash value growth Moderate in early years, strong long-term accumulation Higher early cash values, with slightly lower long-term accumulation
Death benefit growth Higher long-term death benefit to offset estate or capital gains taxes Moderate death benefit growth, emphasizing cash accessibility
Dividend options Dividends can be received in cash, on deposit, or used to purchase paid-up additions (PUAs) Dividends can be received in cash, on deposit, or used to purchase paid-up additions (PUAs)
Premium payment options Available as 10 Pay, 20 Pay, or Pay to Age 100 Available as 10 Pay, 20 Pay, or Pay to Age 100
Liquidity and collateral use Strong long-term value, typically used for estate purposes or future borrowing High early cash values make it well-suited for collateral loans or funding business opportunities
Child or grandchild coverage Ideal for lifelong coverage with gradual value growth for education or inheritance Offers earlier access to cash values for education or financial milestones
Charitable giving Well-suited for estate donations or legacy philanthropy Allows more flexibility for lifetime charitable contributions
Business protection Works well for long-term shareholder or key-person protection with stable growth Better for businesses that prioritize early liquidity and short-term funding options
Coverage availability Available as Single Life, Joint First-to-Die, or Joint Last-to-Die Available as Single Life, Joint First-to-Die, or Joint Last-to-Die
Minimum sum insured $10,000 (child) or $50,000 (adult) $10,000 (child) or $50,000 (adult)
Maximum sum insured Up to $25,000,000 total Equimax coverage Up to $25,000,000 total Equimax coverage

Equitable Life whole life insurance costs and value

This example shows the projected premiums, cash value growth, and death benefit for a 30-year-old non-smoker female purchasing $100,000 of Equitable Life whole life coverage with life pay and enhanced paid-up additions.

Projected premiums, cash value, and death benefit over time


Policy Year Age Annual premium paid Total premiums paid Total cash value Death benefit
0 30 $818.47 $818.47 $0.00 $100,000.00
10 40 $818.47 $8,184.70 $4,608.00 $100,000.00
20 50 $818.47 $16,369.40 $21,481.00 $100,000.00
30 60 $818.47 $24,554.10 $46,652.00 $118,700.00
40 70 $818.47 $32,738.80 $90,510.00 $163,023.00
50 80 $818.47 $40,923.50 $163,638.00 $228,448.00
55 85 $818.47 $45,015.85 $214,083.00 $272,181.00
60 90 $818.47 $49,108.20 $274,165.00 $323,796.00


* Values shown are non-guaranteed illustrations based on current assumptions and the insurer’s dividend scale. Actual premiums, cash values, and death benefits may vary. This example is for informational purposes only and does not constitute a policy guarantee.

What are the pros and cons of Equitable’s whole life insurance policy?

Equitable has several advantages, such as lucrative riders, availability for a collateral loan, multiple dividend payout options, and tax-free death benefits. However, there are some disadvantages, such as the non-availability of a non-participating whole life insurance option, higher premium costs, and slow cash value growth during the initial days of the Equitable Estate Builder plan.

Pros and cons of Equitable whole life insurance


Pros Cons
EquiLiving Critical Illness Rider provides a lump-sum payout for covered illnesses to cover medical costs or support recovery This policy has higher premiums compared to term insurance, making it less accessible for tight budgets
Excelerator Deposit Option allows additional tax-deferred contributions to enhance the policy’s cash value growth Equitable does not have a non-participating whole life insurance option to choose from
Variable dividend options provide flexibility to increase the death benefit, reduce premiums, earn interest, or receive cash It is not ideal for short-term goals or individuals seeking immediate returns
Tax-advantaged growth offers long-term savings potential and typically tax-free death benefits for beneficiaries

Highlights of Equitable’s whole life insurance policy document

An Equitable Life whole life insurance policy document includes:

  • Policyholder and insured details: Names, ages and coverage start dates for the owner and insured
  • Coverage amount: The death benefit and any additional term or rider coverage selected
  • Payment and premium schedule: The chosen pay structure (10-pay, 20-pay or life pay), premium amount, billing frequency and premium guarantees
  • Dividend options: How dividends can be used, including paid-up additions, cash payout, enhanced protection, premium reduction or left on deposit
  • Guaranteed values: Tables showing guaranteed cash value and death benefit, along with illustrated non-guaranteed values based on the current dividend scale
  • Policy loans and withdrawals: Rules for borrowing or withdrawing from cash value, including limits and interest rates
  • Riders and living benefits: Available add-ons such as critical illness, term riders, accelerator deposit option and waiver of premium
  • Beneficiary designation: How to assign or update primary and contingent beneficiaries
  • Surrender and cancellation provisions: Steps to terminate the policy and access any guaranteed surrender value
  • Participating account disclosure: How dividends are generated and how the participating account operates
  • Legal and definitions: Key legal terms, exclusions, reinstatement rights and claim procedures

What are the different limited-pay options offered by Equitable?

Equitable Life offers three limited pay structures for its participating whole life insurance plans (Equimax Estate Builder and Equimax Wealth Accumulator):

  • 10-pay: Premiums are paid for 10 years. Once the payment period ends, the policy is fully paid up and lifelong coverage continues with no further premiums
  • 20-pay: Premiums are paid for 20 years, after which the policy is fully paid up for life
  • Life pay: Premiums are paid for life or until age 100, depending on the contract. This option usually offers lower annual premiums than 10-pay or 20-pay plans

Why should you purchase Equitable Life whole life insurance for children?

By purchasing Equitable’s whole life insurance policies for your child or grandchild, you’re giving them more than just lifelong coverage;, you’re setting the foundation for their financial future. Equitable Life whole life insurance for children offers permanent coverage at children’s rates, with paid-up options in 10 or 20 years.

It provides tax-advantaged cash value growth, offering financial flexibility through loans or withdrawals for future needs. Also, ownership can transfer tax-free to the child upon adulthood, securing their financial foundation.

For example, if you buy a 20-pay whole life insurance for a 5-year-old child at an annual premium of $1,200, the policy’s value will continue to grow without any further premium payments after the first 20 years. 

By simply paying $100 a month, parents can now secure the financial future of their children, ensuring they have enough coverage to fund important life events as well as emergencies and can also leave a fortune behind for their future generations.

How can you pay for Equitable whole life insurance?

Equitable Life provides three main payment options for its Equimax whole life insurance policies: Life Pay, 10 Pay, and 20 Pay. Each of these payment options can be beneficial to different individuals based on their unique situations.

  • Life Pay: This option requires premiums to be paid throughout the policyholder’s lifetime or until death. It’s designed for those who prefer lower annual payments spread over a longer period
  • 10 Pay: In this scenario, the premiums are paid for only 10 years, after which the policy is fully paid up. This option is ideal for individuals who want to secure lifelong coverage quickly and have the financial resources to afford higher annual payments
  • 20 Pay: This option allows policyholders to complete premium payments over 20 years. It balances affordability and early completion, making it suitable for those who want to avoid lifetime payments but prefer a payment period longer than 10 years

Does Equimax help with tax payouts during death?

Yes, Equimax Estate Builder whole life plan can help with tax payouts upon death. This specific plan is designed to provide a larger death benefit, which can be used to offset estate taxes and other final expenses. 

The death benefit is typically paid out tax-free to beneficiaries, providing them with the funds needed to settle the estate without the burden of additional tax liabilities.

The Equimax Estate Builder whole life plan provides a death benefit that can be used to:

  • Cover estate taxes: The death benefit can help beneficiaries pay for estate taxes, ensuring the full value of the estate is passed on without forcing them to liquidate assets
  • Leave a legacy behind: The policy ensures that the financial legacy you leave behind remains intact, allowing your beneficiaries to inherit more

How are whole life insurance dividends determined by Equitable?

Equitable Life’s whole life insurance dividends are determined by the performance of its participating (PAR) account. The financial performance of PAR accounts can depend on factors like investment returns, mortality payouts, premium lapses, and tax obligations. 

Strong investment performance, fewer claims, and lower premiums lapsing can lead to higher dividends, while the opposite may result in lower payouts. 

Dividends are paid at the sole discretion of Equitable Life’s board of directors. As such, dividends can vary from year to year depending on the insurer’s performance. The decision to distribute dividends is made with the aim of ensuring steady, predictable returns while minimizing volatility.

Equitable Life Dividend Scale Interest Rate (DSIR): 2020–2025


Year DSIR
2025 6.40%
2024 6.40%
2023 6.25%
2022 6.05%
2021 6.05%
2020 6.20%

Now, let’s take a look at the average dividend scale returns by Equitable’s participating accounts and interest rates over the last 30 years:

Equitable Life dividend scale over 30 years


Timeframe Equitable PAR account return Equitable dividend scale interest rate
5 years 6.52% 6.15%
10 years 6.26% 6.37%
20 years 6.79% 6.95%
30 years 7.35% 7.72%
Standard deviation over 30 years 1.79% 1.31%


Source: Equitable dividend scale interest rate, 2024

Learn more about the cost of whole life insurance in Canada

Which Equitable whole life plan type is right for you?

Equitable’s Estate Builder and Wealth Accumulator plans are built to suit the diverse needs of policyholders. From long-term goals to immediate cash value accumulation, individuals can choose the right Equimax plan for them based on their individual needs.

Here’s how you can determine the right policy for yourself:


What to look for Equimax Estate Builder Equimax Wealth Accumulator
If you are looking for higher long term benefits for planning your estate
If you’re looking for a higher death benefit that can reduce tax burden for your next of kin during transfer of property
If you’re looking for affordable insurance coverage to secure the financial future of your children or grandchildren
If you’re looking to build immediate cash value to start a business
If you’re looking to make philanthropic donations but also reduce your tax implications now and in the future
If you’re looking to create a steady retirement fund
If you’re looking for quick access to higher cash value through a policy loan or collateral loan

Find out about the best whole life insurance companies in Canada
Let us help you choose the best Equitable whole life plan

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

What are the various dividend options on an Equimax whole life insurance plan?

Equitable’s participating whole life insurance has several dividend options to choose from, including cash payout, premium reduction, paid-up additions, on-deposit, and enhanced protection.

  • Paid in cash: Dividends are paid directly to the policyholder each year
    Best for: Clients who want annual income or flexibility rather than reinvestment
  • Premium reduction: Dividends reduce future premiums, lowering out-of-pocket costs while keeping coverage intact
    Best for: Clients seeking immediate savings and simplicity
  • On deposit: Dividends are held in an interest-bearing account with Equitable Life and can be withdrawn anytime
    Best for: Clients who prefer liquidity and guaranteed interest growth
  • Paid-Up Additions (PUA): Dividends buy additional permanent coverage that grows cash value and death benefit tax-deferred
    Best for: Clients focused on long-term accumulation and estate enhancement
  • Enhanced protection: Combines base permanent coverage with a one-year renewable term (OYT) layer. Dividends first pay OYT costs; any remainder buys PUAs that gradually replace the term layer
    Best for: Clients who want higher early coverage, faster growth, and stronger estate value

What is the living benefit offered by Equimax whole life insurance?

The living benefit offered by Equimax whole life insurance allows policyholders to access a portion of their policy’s cash value if the life insured becomes severely disabled due to a physical or mental impairment. 

This benefit can be applied once per policy year and is subject to Equitable Life’s administrative guidelines. Any payment made under the Living Benefit will reduce the policy’s death benefit. 

Individuals suffering from life-threatening conditions such as cancer, AIDS, coronary artery disease, myocardial infarction, chronic kidney or liver failure, Alzheimer’s disease, etc, can be eligible to receive Living Benefits under their whole life insurance policy. Also, the insured individual must have been impaired for a period of 90 days significantly affecting their day-to-day life, and their ability to continue employment.

What are the additional riders available with Equitable’s Equimax whole life insurance?

Whole life insurance by Equitable has customization options along with various riders such as critical illness, additional term life insurance, disability waiver, and more. Insured individuals can choose from these options to further enhance their chances for a higher payout in case of severe illness or disability.

  • Disability waiver of premium rider: Waives premiums if the policyholder becomes disabled, ensuring continued coverage without financial strain
  • Term life insurance rider: Available only with single policies, this allows you to add term life insurance coverage to your whole life policy, providing additional protection within a single plan
  • EquiLiving critical illness rider: Offers financial protection in the event of a severe illness, allowing you to access benefits for medical or living expenses
  • Excelerator Deposit Option (EDO): Enables you to make lump-sum contributions to your policy, boosting its cash value and increasing your death benefit
Explore the differences between universal and whole life insurance to make an informed choice

How to get the best whole life insurance quotes in Canada?

When it comes to finding the best whole life insurance quotes in Canada, you have a few options. You could spend hours browsing different websites and comparing policies on your own, but that can quickly become overwhelming and time-consuming. This is where PolicyAdvisor comes in!

What sets PolicyAdvisor apart is not just the competitive pricing and multiple options to choose from, but also the lifetime after-sales support. After you’ve secured your policy, you’re not left on your own. Our team of expert advisors is always available to help with any questions or adjustments you need, ensuring you have ongoing support every step of the way. It’s a stress-free way to get the best coverage while knowing you’re always taken care of, now and in the future.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Can I transfer ownership of my Equitable whole life insurance policy to my children or grandchildren? 

Yes, Equitable allows you to transfer ownership of your whole life insurance policy to your children or grandchildren when they reach the age of majority. 

This is a great way to start building generational wealth, as they can access the policy’s cash value for future expenses such as education or a down payment on a house.

Can I add extra coverage to my Equitable whole life insurance policy in the future? 

Yes, Equitable offers various options to increase your coverage over time. With features like paid-up additions, you can use dividends to purchase additional life insurance, increasing your death benefit and cash value. This flexibility allows you to tailor your policy as your life circumstances evolve, ensuring that you always have the coverage you need.

What happens to my Equitable whole life policy if I stop making premium payments? 

If you stop making premium payments on your Equitable whole life policy, it won’t necessarily lapse immediately. The policy’s cash value can be used to cover the premiums for a period of time, depending on how much cash value you’ve accumulated. However, once the cash value is exhausted, your coverage may likely end. It’s important to keep track of your policy’s status from time to time.

Can a person with pre-existing conditions be eligible for the Living Benefit of a whole life insurance policy?

No, a person with pre-existing conditions may not be eligible for the Living Benefit under Equitable’s whole life insurance policy if the condition existed at the time the policy was first issued or at the date of the last reinstatement.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

iA Whole Life Insurance Review – 2026

Best for Health Accommodation
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Whole life insurance policies offered
Non-participating policy, PAR Estate, PAR Wealth
Dividend Scale Interest Rate (DSIR)
6.35%
AM Best Rating
A+

Industrial Alliance (iA) Whole Life Insurance offers lifelong protection combined with the opportunity to build guaranteed cash value over time. It is designed for those seeking stability and long-term financial growth in Canada. Policyholders can also benefit from potential dividends, flexible payment options, and access to the accumulated cash value for future needs.

Whether you are looking to safeguard your family, build long-term savings, or leave a meaningful legacy, iA Whole Life Insurance promises to be a steady partner in your financial journey. In this review, we will delve into the key features, benefits, and how it can stack up against your insurance needs.

About iA par whole life at a glance:

Estimated par fund size $69.36 million
Dividend scale interest rate (2025) 6.35%
Policyholder structure Shareholder-owned
Business history 130+ years

What is your Whole Life Insurance worth?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$100K

PolicyAdvisor’s iA whole life insurance rating: (4/5)

Our expert advisors at PolicyAdvisor have given iA a 4 out of 5 rating. The rating is based on early/long-term cash value growth, premium options, bonus stability, fees, riders, and issue ages.

Furthermore, iA has a good fund size of $69.36 million and backs its whole life insurance with a broadly diversified asset allocation, with about two‑thirds of assets allocated to fixed income and just over one‑third to non‑fixed income investments.

Pros and cons of iA’s whole life insurance

iA whole life insurance has several pros, such as multiple dividend options, a variety of riders for both their PAR and non-PAR plans, faster plan approval via accelerated underwriting, and the pioneering iA Large Case Solutions program. However, there are some disadvantages, such as the non-availability of cash surrender value in the T100 plan and limited disability benefit access.

Pros Cons
iA offers flexibility with four dividend options, allowing customization of coverage The disability benefit is available only in the PAR plans.
A variety of riders are available for both traditional and PAR plans to enhance coverage The T100 plan does not offer cash surrender value
Faster insurance approval with an accelerated underwriting process which can reduce wait times
iA provides expert support for advisors and clients through its Large Case Solutions program for complex cases

What are the key features of iA whole life insurance plans?

iA whole life insurance is available in two options: non-participating whole life insurance and participating whole life insurance.

While iA non-participating insurance has a minimum coverage of $10,000, iA PAR options have a starting coverage value of $25,000. Both plans have several additional benefits and riders to provide complete financial protection to insured individuals.

What are the different iA whole life plans I can choose from?

iA Financial offers a range of whole life insurance plans tailored to meet different financial goals, with options for both participating and non-participating whole life insurance.

For participating whole life, there are primarily two plans to choose from: iA PAR Estate and iA PAR Wealth. While the Estate plan focuses on higher death benefits with lesser upfront cash value, the  Wealth plan generates higher cash value for the short-term goals of the insured individual.

1. Non-participating whole life insurance

iA Financial Group’s non-participating whole life insurance is designed for those who seek simple, reliable, and lifelong protection. 

This policy is an excellent solution for anyone looking to safeguard their family’s financial future or preserve their estate, offering guaranteed coverage and a range of benefits that remain in effect for life.

Key features of iA non-participating whole life insurance

  • Guaranteed face amount and premiums: The policy provides a guaranteed face amount, ensuring that your loved ones or estate receives a predetermined benefit upon your passing
  • Paid-up insurance: With the option of paid-up insurance, you can enjoy full coverage without having to pay premiums for life. This provides flexibility and financial relief in later years, making it a highly appealing feature for those planning their retirement
  • Flexible and personalized coverage: You can enhance your coverage with riders and additional benefits, including critical illness coverage, accidental death benefits, and child protection rider

Who can benefit from iA non-participating whole life insurance?

Non-participating policies can benefit:

  • Families looking to ensure their loved ones are financially secure
  • Individuals aiming to leave a clear and structured legacy for their estate
  • Those who prefer a straightforward insurance solution without market-based dividend fluctuations

What are the different coverage options for iA whole life insurance?

iA whole life insurance policy is available in four coverage options to suit different coverage needs. Individual insurance covers only one person, with the face amount paid out upon their death. This type of insurance is also the only option compatible with the Child Life & Health Duo plan.

For shared coverage, there is joint first-to-die insurance, which insures up to two people and pays the face amount upon the death of the first insured, terminating the policy thereafter.

Alternatively, joint last-to-die insurance covers two individuals but pays out only after both have passed, with premiums continuing after the first death. A variation of this, joint last-to-die, paid-up on first death, provides similar coverage but halts premium payments once the first insured dies, ensuring the coverage amount is paid upon the death of the second insured.

What are the riders and available benefits for iA non-participating whole life insurance?

iA Financial Group offers a variety of riders and additional benefits, such as AD&D, Guaranteed Insurability, waiver of premiums, critical illness coverage, and more, to enhance its non-participating whole life insurance policies.

These options allow policyholders to create a comprehensive, tailored plan that aligns with their specific needs, providing extra financial security for unforeseen events.

Additional benefits (riders) of iA non-participating whole life policy

  • Accidental Death and Dismemberment (AD&D): Offers benefits for accidental death or serious injuries, such as loss of a limb or eyesight
  • Accidental fracture (AF): Covers specific payments for fractures caused by accidents.
  • Guaranteed Insurability (GI): Allows the insured to purchase additional coverage at future dates without needing further medical evidence
  • Waiver of premiums in the event of the applicant’s disability (WPDis): Premium payments are waived if the applicant becomes disabled
  • Waiver of premiums in the event of the applicant’s death (WPD): Premium payments cease if the applicant passes away
  • Child module and child module plus: Provide comprehensive protection for children, including coverage for critical illness, death, and other risks
  • Critical Illness: Pays a lump sum benefit if the insured is diagnosed with a covered critical illness
  • Disability credit: Offers financial assistance if the insured becomes disabled
Learn more about how whole life insurance works in Canada

2. Participating whole life insurance

Participating plans from iA Financial Group let policyholders benefit from the company’s performance through annual dividends. These dividends can be reinvested to grow your policy’s cash value or used in other ways, depending on your preferences. iA offers two standout participating whole life plans:

iA PAR Estate

Designed for individuals who want to leave a lasting legacy, iA PAR Estate is focused on maximizing the death benefit for estate planning purposes. This plan helps you efficiently transfer wealth to your loved ones or chosen beneficiaries while benefiting from the policy’s growth over time.

iA PAR Wealth

This plan is tailored for those aiming to build and access cash value during their lifetime. With a focus on wealth accumulation, iA PAR Wealth offers flexibility for personal or business financial needs, making it a popular choice for individuals with long-term growth objectives.

Features of iA PAR Estate and iA PAR Wealth

Feature iA PAR Estate iA PAR Wealth
Primary objective Designed to maximize the death benefit for estate planning Focused on building significant cash value that can be accessed during the policyholder’s lifetime
Target audience Clients prioritizing legacy planning, such as transferring wealth to heirs or charitable organizations Clients aiming for short-term financial accelerated growth and flexibility in accessing policy funds
Death benefit growth Offers consistent growth in the death benefit over time Balances death benefit growth with a primary focus on cash value accumulation
Cash value access Cash value is initially lower and accessible after completion of 5 years of the policy Cash value is initially higher and accessible after completion of 1 year of the policy
Policy liquidity Lower liquidity initially High liquidity initially
Premium payments Annual or monthly payments with a pre-authorized cheque (PAC) Annual or monthly payments with a pre-authorized cheque (PAC)

How can you access dividends in an iA whole life insurance?

iA Financial Group offers four different dividend strategies, including paid-up additions, annual premium reduction, cash payouts and deposits with interest for their participating whole-life insurance plans:

  • Paid-up additions: Dividends are used to purchase additional paid-up insurance, increasing both the policy’s face amount and its cash surrender value
  • Annual premium reduction: Dividends are applied to reduce the amount of the next annual premium payable, lowering the out-of-pocket cost for the policyholder
  • Payable in cash: Dividends are paid directly to the policy owner, providing immediate liquidity. This option may have tax implications 
  • Deposit with interest: Dividends are deposited into a savings account managed by iA Financial Group, where they earn interest. The interest earned is taxable at the end of the year

Additional deposit option

iA Par policies also have an additional deposit option, which means that policy owners can buy additional paid-up insurance. This gets added to the existing paid-up insurance. Please note that this is not applicable to the iA PAR 10-year payment. The additional deposit contribution needs to be specified in the insurance application form.

How are dividends for iA whole life participating policies distributed?

The participating account in iA whole life is managed by the iAGAM team, who are experienced in handling bonds, equities, asset allocation, alternative assets, and risk management. The participating account in an iA whole life policy benefits from different assets. The dividends are distributed amongst the following assets:

  • Short-term investments
  • Government bonds
  • Corporate bonds
  • Preferred shares
  • Commercial mortgages
  • Private debts
  • Private equity and infrastructure
  • Real estate
  • Common shares
Whole life insurance can be affordable!

Get the best whole life insurance rates in Canada today.

How does iA calculate dividends?

Dividends are not guaranteed and may differ from one year to another based on the performance of iA’s participating (PAR) account. Each year, iA’s Board of Directors decides the dividend amount based on the company’s dividend policy, which ensures fair distribution among policyholders.

The dividend amount depends on the dividend scale, which reflects the financial performance of the participating account. This performance is influenced by factors such as investment returns, mortality rates, policy lapses, and expenses related to iA’s participating contracts. 

The dividend scale can go up or down based on these factors. Once dividends are declared, it is paid to the policyholder on the policy’s commencement date.

Taxation of dividends

The taxation of dividends on an iA whole life insurance policy depends on the option you have selected. It will vary if you have opted for paid-up additions, cash, or any other available option. Here’s a breakdown of how taxation applies to each option:

  • Paid-up additions: No tax applies if the full dividend buys paid‑up additions. If any portion is paid to the policyowner, cash payment tax rules apply
  • Payable in cash: Any amount exceeding the adjusted cost base (ACB) is taxed
  • Annual premium reduction: Dividends are used to reduce the premium; the ACB remains unaffected. No tax applies in this case
  • Deposit with interest: Dividends that are held on deposit and earn interest are taxable; the interest credited is taxed annually

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%
Explore the top whole life insurance companies in Canada in 2025

iA whole life with limited pay option

The iA whole life plan comes with limited pay options, which means you can pay your premium for a set number of years. To ensure flexibility, the company offers 10-pay, 20-pay, and pay-to-100 options. Limited-pay policies are popular because they provide long-term financial certainty and are ideal for people who want guaranteed lifetime coverage without lifelong premium obligations.

What are the additional benefits and riders offered by iA participating whole life insurance?

iA Financial Group offers a range of additional benefits and riders, including additional term coverage, waiver of premiums, critical illness coverage and accidental benefits for their participating whole life insurance policies. 

These options allow policyholders to tailor their coverage to meet specific needs and enhance the value of their policy.

1. Term coverage

Policyholders can supplement their permanent life insurance with renewable and convertible term life insurance options, providing extra protection for a set period. Options include:

  • T10 (Renewable and Convertible): Provides coverage for 10 years, with the option to renew or convert to permanent insurance without additional medical exams
  • T20 (Renewable and Convertible): Similar to T10 but offers coverage for 20 years
  • Pick-A-Term Options:
    • T25: Provides coverage for 25 years
    • T30: Offers coverage for 30 years

2. Child benefits

These riders ensure additional protection for children under the policy:

  • Child Module: Child Module covers children to age 25 or parents to age 65, whichever comes first
  • Child Module PLUS: Includes enhanced benefits for children, offering more comprehensive protection with the inclusion of an accidental fracture benefit

3. Accident benefits

Accident riders provide additional financial support in case of accidental injuries or death:

  • Accidental Death (AD): Pays an extra benefit to the beneficiaries if the insured’s death is due to an accident
  • Accidental Death and Dismemberment (AD&D): Offers financial compensation for accidental death or dismemberment, helping cover unexpected expenses
  • Accidental Fracture (AF): Provides a lump-sum benefit in the event of accidental fractures, helping offset medical costs

4. Waiver of premium riders

These riders ensure the policy remains active without requiring premium payments under specific circumstances:

  • Waiver of Premiums in the Event of the Applicant’s Disability (WPDis): If the person who applied for the policy becomes disabled, premiums are waived to keep the coverage intact
  • Waiver of Premiums in the Event of the Insured’s Disability (WPIDis): If the insured individual becomes disabled, the premiums are waived to ease the financial burden
  • Waiver of Premiums in the Event of Death (WPD): If the policyholder passes away, future premiums are waived to ensure the policy benefits remain available to beneficiaries

What is the Child Life and Health Duo plan offered by iA?

The Child Life and Health Duo plan from iA Financial Group is a comprehensive insurance solution designed to provide both life and critical illness coverage for children. This plan ensures financial security for families by addressing potential medical and financial challenges while building a foundation for the child’s future.

Some of the main features of the Child Life and Health Duo plan include:

  • Dual coverage: Combines life insurance and critical illness insurance into one policy
  • Critical illness protection: Provides coverage for a range of critical illnesses, offering a lump-sum benefit to help with medical expenses, recovery costs, or other financial needs
  • Life insurance benefit: Ensures a payout in the event of the child’s passing, providing financial support for the family during a difficult time
  • Convertibility: Offers the flexibility to convert the child’s coverage into an adult policy later in life without requiring additional medical exams
  • Affordable premiums: Designed to offer comprehensive protection at a cost-effective rate
  • Cash value growth: Includes a savings component that builds cash value over time, which can be accessed in the future for various financial needs

Can I get a loan against my iA whole life insurance policy?

Yes, you can take out a loan against your iA whole life insurance policy through two types of policy loan advances: the cash loan advance and the automatic loan advance

Both types of loan advances allow the policyholder to access the cash value of the policy while still maintaining eligibility for dividend payments, though there are some important details and limitations to consider.

  1. Cash loan advance
  • The policy owner can request a cash loan advance at any time in writing
  • The loan amount cannot exceed 90% of the surrender value of the basic coverage (including any reduced paid-up insurance, if applicable) plus 90% of the surrender value of any paid-up insurance, minus any amounts owed to the company
  1. Automatic loan advance
  • This type of loan advance is automatically initiated by the company if premiums are due and have not been paid by the end of the grace period
  • The automatic loan advance cannot exceed the total surrender value of the policy, which includes the surrender value of the basic coverage, any reduced paid-up insurance, the surrender value of the paid-up insurance, and the balance of the dividend deposit account (if applicable)
  • The total outstanding loan balance, including any other amounts owed to the company, cannot exceed the policy’s total surrender value

Who should consider buying iA whole life insurance?

With a 4 rating from PolicyAdvisor, iA whole life insurance plan is a good choice for the following group of people:

  • Those who want life insurance coverage and a financial safety net
  • Those who want estate planning or transfers
  • Those who prefer access to cash value
  • Those who might need to use policy as collateral for business needs
Find out if whole life insurance is worth your moneyLearn more to choose the best life insurance option for you in 2025

How to get iA whole life insurance quote in Canada with PolicyAdvisor?

When searching for the best whole life insurance quotes in Canada, you have a few routes to consider. While you could spend hours browsing various websites and comparing policies on your own, this process can quickly become overwhelming and time-consuming. That’s where PolicyAdvisor comes in and helps you choose iA whole life insurance quote.

  1. Speak with a licensed PolicyAdvisor expert
  2. Review iA whole life insurance plans along with the other options available
  3. Receive a personalized illustration and finalize your application online

What makes PolicyAdvisor stand out isn’t just our competitive pricing and wide range of options, but also our lifetime after-sales support. Once you’ve secured your policy, we don’t leave you on your own. Our team of expert advisors is always available to assist with any questions or adjustments you may need, ensuring you receive continuous support throughout your journey. It’s a seamless, stress-free way to get the best coverage, knowing you’re fully supported now and in the future.

Get whole life insurance for your loved ones

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Can I adjust my iA whole life insurance policy as my needs change?

While whole life insurance is designed to provide lifelong coverage, iA offers flexibility through optional riders and benefit adjustments. 

For example, you can add more coverage, adjust your payment structure, or integrate additional protection like disability benefits. These options ensure that your policy evolves with your lifestyle and financial goals.

Does iA whole life insurance offer tax advantages?

Yes, iA whole life insurance provides significant tax advantages. The cash value grows tax-deferred, meaning you won’t pay taxes on the gains as long as they remain within the policy. 

Additionally, the death benefit is typically paid out tax-free to your beneficiaries, making it an excellent tool for estate planning and wealth transfer.

How does iA ensure that my policy remains affordable long-term?

iA whole life insurance comes with fixed premiums, which means your monthly or annual payments won’t increase over time, regardless of changes in your health or the economy. 

This stability makes budgeting easier and ensures that your policy remains affordable as you age. Additionally, participating policies with dividends can offset costs, offering even greater value over the life of the policy.

Are there any transaction fees applicable to iA whole life insurance?

Yes, iA whole life insurance policy may incur transaction fees, which are calculated per policy, not per insured. If multiple changes are made within the same policy, only the highest fee is charged, unless additional coverage or benefits are requested, in which case all fees are waived.  If the same change is processed on multiple policies, a transaction fee will be applied to each policy. These fees are important to consider when making changes or requests related to your policy.

What are the dividend options available with iA whole life insurance?

With iA whole life insurance policy, policyholders have several flexible options for how their dividends are used. Dividends can be applied to purchase paid-up additions (PUAs), which increase both the policy’s death benefit and cash value over time. They can also be used to reduce or fully pay future premiums, helping lower out-of-pocket costs. Alternatively, policyholders may choose to receive dividends in cash each year or leave them with iA to accumulate with interest. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is limited pay life insurance?

Limited pay whole life insurance is a type of permanent whole life coverage where you pay your premiums for a predetermined, “limited” period, such as 5, 8, 10, 15, 20 years, or up to age 65. When the scheduled limited‑pay period is completed and the policy is paid‑up completely, the coverage is designed to remain in force for life. This differs from traditional life-pay whole life insurance, where premiums are paid every year for as long as the policy is in force. 

This guide explains what limited pay whole life insurance is, how it works, how it differs from traditional plans, and its key features and benefits.

How does limited pay whole life insurance work?

Limited pay whole life insurance lets you pay premiums for a limited period while keeping coverage for life. Once your payment term ends, the policy becomes “paid-up,” meaning no further premiums are required.

Here’s how the process works:

  • Select the whole life insurance plan that meets your coverage and benefit needs
  • Choose your payment term: Select how long you want to pay premiums (e.g., 5-pay, 10-pay, 15-pay, 20-pay, or pay-to-65), locking in guaranteed level payments for that period
  • Apply and complete underwriting: Submit an application and go through underwriting so the insurer can assess your health, risk profile, and final premium rate
  • Pay premiums for the selected term: Pay premiums, annually or monthly, only for the chosen limited period
  • Premiums build value and coverage: Each payment funds the policy’s cash value and activates the permanent death benefit for your beneficiaries
  • Cash value grows over time: As premiums are paid, the cash value increases on a tax-deferred basis if the policy is “exempt” under the Income Tax Act. Non-exempt policies are taxed annually on growth. Participating policies may also receive dividends.
  • Access to cash value: Once enough value has accumulated, you can borrow or withdraw from it (subject to policy rules) for retirement income, emergencies, or other needs. Loans and withdrawals may reduce the death benefit and cash value, and may have tax implications
  • Policy becomes fully paid-up: When the payment term ends, no further premiums are required for life
  • Lifetime protection continues: The policy stays in force for your entire lifetime, and the death benefit is generally paid tax-free to individual beneficiaries. In some corporate or policy loan situations, it may be taxable
Learn about some of the most affordable whole life insurance plans in Canada.

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Key features and benefits of limited pay whole life insurance

Limited pay whole life offers guaranteed lifelong coverage, premiums that end early, and the potential to build cash value for long‑term goals without paying for life. It’s designed for Canadians who want lifetime coverage without paying premiums forever.

Here are its key features and benefits:

  • Short premium payment window: Lifetime protection with a compressed, level premium payment period
  • Guaranteed cash value: Builds steadily every year. Growth is generally tax-deferred for exempt policies, while non-exempt policies are taxed annually on the increase
  • Dividend accumulation: Participating policies earn dividends that enhance coverage or cash value. Dividends are not guaranteed and depend on company’s performance
  • Paid-up additions: Dividends can be used to buy extra insurance for compound growth
  • Tax advantages: Exempt policies enjoy tax-deferred cash value growth and generally tax-free death benefits; non-exempt policies are taxed on growth, and some corporate or policy loan situations may affect death benefits

Types of limited pay whole life insurance in Canada

Limited pay whole life insurance comes in several payment structures, with 10-pay and 20-pay being the most common while 5-pay, 8-pay, and pay-to-65 are less commonly offered by insurance providers. Each defines how long you’ll pay premiums before the policy is fully funded. After that, coverage continues for life with no further payments.

5-pay whole life: 

In 5-pay whole life insurance, you pay premiums for just five years. Although less common, it’s a fast, high-commitment option, best for high earners or those focused on estate and business planning who want quick ownership.

8-pay whole life:

8-pay whole life insurance is offered only by a few carriers, it’s a short-term option that offers quick ownership without the intensity of 5-pay. Best suited for business owners or professionals planning to use the policy for long-term wealth transfer.

10-pay whole life:

10-pay whole life insurance is the most commonly offered limited pay, where payments end in 10 years, giving you lifetime coverage and faster cash value growth. It is ideal for those who want a clear end date before retirement.

15-pay whole life:

15-pay whole life insurance balances affordability and early completion, but offered by a few carriers only. It is a good fit for mid-career professionals who want to manage cash flow but still finish payments before their 50s or 60s.

20-pay whole life:

This is one of the most common limited-pay options available; 20-pay whole life insurance spreads premiums over 20 years, keeping annual costs manageable. It is ideal for younger buyers starting long-term coverage early in life.

Pay-to-65 whole life:

In pay-to-65 whole life insurance, premiums continue until age 65, matching your working years. Once you retire, payments stop, but coverage remains for life. This makes it a practical choice for retirement planners.

Example of a limited pay whole life policy: Limited pay whole life insurance works well for those starting later in life. It guarantees lifetime coverage while allowing cash value growth during your life. To see how these payment terms work in practice, let’s look at a real-life example of a 20-pay policy.

  • Jack, 35, buys a 20-pay whole life policy with $100,000 coverage
  • He pays $1,900 per year for 20 years
  • By age 55, the policy is fully paid-up
  • Dividends continue and can supplement his retirement income
  • Jack keeps guaranteed lifetime coverage without paying any more premiums
Type of limited pay
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Limited pay vs. traditional whole life insurance

The core difference between limited pay and traditional whole life is the payment period. Limited pay plans offer lifelong coverage without having to pay premiums for your entire life. Traditional whole life typically requires premiums to age 100 or for life, though some policies allow earlier cessation of out-of-pocket payments through premium offsets. Since premiums are concentrated into a shorter payment period, limited pay plans have higher premiums than traditional whole life. Cash value growth is typically faster in the early years of a limited pay policy, but actual growth depends on the product and dividend scale.

Difference between limited pay and traditional whole life insurance plans


Feature Limited pay whole life insurance Traditional whole life insurance
Premium payment period Pay premiums for a fixed payment term (5,10 or 20 years) Pay premiums for life (no fixed term)
Premium amount Higher annual premiums due to the shorter payment term Lower annual premiums spread over a lifetime
Cash value growth Builds faster due to front-loaded payments Gradual
Ideal for  Business owners, high-income earners, parents funding policies for children, pre-retirees, and those who are focused on estate planning Those who prefer smaller, ongoing premium payments and those seeking lower-cost lifetime coverage using whole life for final-expense needs

The trade-off is that limited pay plans cost more in the short term but deliver payment-free coverage for life. Traditional plans cost less annually but keep you tied to premiums for decades. For Canadians who value financial independence before retirement, limited pay options often strike the right balance between cost, flexibility, and lifetime protection.

To see how this works, here is an illustration depicting a non-smoking 30-year-old female paying $10k annually in premiums:

Features 10-Pay 20-Pay Life Pay
Annual Premium $10,000 $10,000 $10,000
Total Premiums Paid $100,000 $200,000 $700,000
Years Paying Premiums 10 years 20 years Life Pay
Cash Value at Year 20 $145,524 $227,186 $232,021
Death Benefit at Year 20* $605,336 $992,012 $1,591,999
Cash Value at Year 30 $271,563 $429,421 $549,016
Death Benefit at Year 30* $673,570 $1,065,111 $1,612,803
Cash Value at Year 40 $486,605 $776,676 $1,080,086
Death Benefit at Year 40* $887,092 $1,415,896 $2,110,007

Who should consider limited pay whole life insurance in Canada?

Limited pay whole life insurance is best suited for Canadians who want lifetime coverage without lifelong payments. It appeals to those with stable income and long-term financial goals.

Who benefits most:

  • High-income professionals: Ideal for individuals who want to finish paying premiums early and enjoy retirement without ongoing expenses. Doctors, lawyers, and executives often use 10-pay or 15-pay plans for efficient wealth planning
  • Business owners: Great for entrepreneurs looking to fund policies quickly and use them as corporate assets. Paid-up policies may also support succession or shareholder protection, though tax treatment depends on Capital Dividend Account (CDA), Adjusted Cost Base (ACB), and other factors
  • Parents or grandparents: Useful for those buying policies for children or grandchildren. A 10-pay or 20-pay plan can lock in coverage early, leaving the next generation with fully paid-up lifetime protection
  • Retirement planners: Perfect for anyone aiming to eliminate financial obligations before retirement. Pay-to-65 structures align naturally with working years, ensuring a stress-free transition into retirement
  • Estate planners: Favoured by individuals building long-term legacy plans. Fully funded policies ensure guaranteed coverage and predictable estate value with no premium surprises later in life

Limited pay whole life insurance offers valuable long-term benefits, but it’s not right for everyone. Understanding its limitations helps you make an informed decision. It may not be ideal for the following reasons:

  • Higher short-term costs: Premiums are compressed into fewer years, so annual costs are higher. This can strain cash flow if income is inconsistent
  • Reduced flexibility: Once you choose a payment schedule (10-pay, 20-pay, etc.), most policies don’t allow changes. Some may offer reduced paid-up coverage or premium offsets
  • Commitment required: Missing payments during the funding period can impact cash value and performance. These plans work best for buyers with predictable income
  • Limited early liquidity: Cash value growth is modest in the first few years, especially for shorter pay periods
  • Opportunity cost: Large early premiums may reduce your ability to save elsewhere or manage debt.
benefits of limited pay

How to choose the right limited pay option

  • Choosing the right limited pay option means matching your payment term to your budget, timeline, and financial goals. Consider your age, income, and whether you want to prioritize liquidity, legacy, or retirement planning.Selecting the right option is not about the lowest cost; it’s about the best fit for your financial timeline and long-term goals. A licensed PolicyAdvisor expert can compare limited pay options and select a plan best suited to your needs.
Schedule a call for visitor insurance

Find a plan that fits your goals.

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

What is limited pay whole life insurance?

Limited pay whole life insurance is a permanent policy where you pay premiums for a set number of years, such as  5, 10, 15, 20, or until age 65, instead of for your entire life. Once the payment term ends, the policy becomes fully paid-up, and your coverage continues for life. This structure suits Canadians who want to finish payments early while keeping lifelong protection and building guaranteed cash value.

How does limited pay whole life insurance differ from traditional whole life insurance?

The key difference between limited pay and a whole life insurance plan is how long you pay premiums. With limited pay whole life insurance, payments end after a fixed term, while traditional whole life requires ongoing payments for life. Both offer lifetime coverage and cash value, but limited pay policies cost more annually since you pay them off sooner.

What is paid-up life insurance?

Paid-up life insurance is a policy that no longer requires premium payments but continues to provide lifetime coverage. You can reach paid-up status by completing the limited pay term or electing reduced paid-up status. Some policyholders also use premium offset, where dividends or cash value cover future premiums, though the policy isn’t fully paid-up in that case. It’s a useful option for policyholders who want lifelong coverage without ongoing costs.

Can I convert my existing whole life policy into a limited pay plan?

No, most existing whole life insurance policies cannot be directly converted into limited pay plans. However, some insurers allow premium offset, where dividends cover future premiums, or policy exchanges under certain conditions. It’s best to review your policy terms or consult your advisor to confirm what’s possible with your provider.

What happens after I finish paying premiums on a limited pay plan?

Once you’ve completed your payment term, your policy becomes fully paid-up. You no longer need to make premium payments, but your coverage continues for life. You can also access your policy’s cash value through loans or partial withdrawals, depending on your insurer’s rules.

Who should consider a limited pay whole life policy?

Limited pay whole life insurance is ideal for professionals, business owners, and families who want permanent protection but prefer to pay premiums before retirement. It is also a good fit for those who want to use life insurance for estate planning or tax-efficient wealth transfer.

How can I make limited pay whole life insurance more affordable?

You can make your limited pay plan more affordable by choosing a longer pay term or improving your insurability. You can also use policy features like paid-up additions (PUAs), which let you use dividends to buy extra coverage, boosting your policy’s value without increasing out-of-pocket costs. Some policies also allow additional deposits (ADO), which do require extra payments.

What’s the difference between limited pay and paid-up additions?

Limited pay determines how long you make premium payments, whereas paid-up additions (PUAs) let you use dividends to purchase extra coverage. PUAs may accelerate when a policy reaches paid-up status, but they do not always make the base policy fully paid-up. Instead, they primarily increase your death benefit and cash value without lengthening the payment period.

Can businesses buy limited pay whole life insurance?

Yes, corporations in Canada can use limited pay whole life insurance through corporate-owned life insurance (COLI) to create a valuable corporate asset. The company pays premiums over a set term, and the policy can support buy-sell funding, executive compensation, or long-term financial planning.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Comprehensive Guide to Life Insurance for Diabetics in Canada

As one of the almost 2.5 million Canadians with diabetes (source: Statistics Canada), you may have hit some stumbling blocks or even brick walls on your search for insurance of any kind. Getting life insurance when you are diabetic can be a little less straightforward than for those without it. But, it is possible to obtain life insurance for diabetics, and it may be less expensive than you assumed.

Why does diabetes affect insurance rates?

Diabetes is a disease that affects how your body uses and produces insulin, a hormone produced by your pancreas. There are three types of diabetes: Type-1 diabetes, Type-2 diabetes, gestational diabetes.

Type-1 diabetes

It is also known as insulin-dependent diabetes, is an auto-immune disorder. For Type-1 diabetics, their pancreas no longer produce insulin, a hormone that helps your body convert sugar to the energy you need. You need to administer synthetic insulin to cover for the food you eat

Type-2 diabetes

People with type 2 diabetes produce insulin, but their bodies do not use or recognize it correctly. They can deal with the condition through oral medication or diet. Type-2 diabetes is the most common form of diabetes in Canada, with approximately 90% of diabetics living with Type-2 diabetes.

Gestational diabetes

It is a temporary form of diabetes associated with pregnancy. The body cannot produce an adequate amount of insulin, leading to an increase in the amount of blood sugar. In most cases, gestational diabetes goes away post-pregnancy

So why would diabetes affect life insurance policy premiums? Well, the stress of constantly fluctuating blood sugar levels puts stress on your internal organs, like your heart and kidneys. The added stress means your organs are prone to failure in their older years. Thus, approving your application takes on added risk factors and adds to the cost of life insurance.

More specifically, Type-1 insulin-dependent diabetes is usually diagnosed in childhood and puts a lifetime of stress on one’s body. This is why insurance rates for Type-1 diabetics are higher.

Type 2 diabetes is more prevalent in individuals after the age of 40, and its effects can be quickly remedied by diet; organ stress is not as great of a factor in medical underwriting.

Gestational diabetes does not usually affect insurance rates, as most expecting mothers opt to do any medical underwriting before or after their pregnancy.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Can diabetics get life insurance?

Yes, diabetics in Canada can get life insurance in Canada. Diabetics who are in good health, with consistent medication levels, and who keep their blood sugar levels in control can qualify for standard, medically underwritten life insurance coverage.

In medically underwritten life insurance, the life insurance company will arrange for a blood test and likely request for a physician’s report to evaluate and screen for a pre-existing condition and grant approval for a life insurance policy. This process may provide more a higher death benefit for a lower premium, than no medical life insurance.

Much like anyone with a pre-existing health condition, no medical life insurance is another choice for diabetics. No medical life insurance is a policy that is issued without the insured having to undergo a medical exam. It usually has the added advantage of a simpler and faster issuance process that doesn’t require details for every medical condition one may have.

The two most common types of no medical life insurance are simplified issue and guaranteed issue. Read more about simplified vs guaranteed

What are the types of life insurance available to diabetics?

In Canada, diabetics have several life insurance options, though the specifics can vary based on individual health conditions and insurance providers. Here are the primary types of life insurance policies accessible to diabetics:

Term life insurance

Term life provides coverage for a specific period (e.g., 10, 20, 30 years) and is generally more affordable than permanent life insurance.

Term life insurance may have higher premiums for diabetics depending on how well the condition is managed and overall health factors

Permanent life insurance

A permanent life insurance policy includes whole life and universal life insurance. It offers lifetime coverage with an added savings or investment component and has higher premiums than term life insurance. This may also require more stringent medical exams for diabetics

Simplified issue life insurance

Simplified issue life insurance requires no medical exam but only a health questionnaire, designed for individuals with health issues who might have difficulty qualifying for traditional life insurance. This policy typically has higher premiums and lower coverage amounts and is often easier for diabetics with well-managed conditions to obtain

Guaranteed issue life insurance

A guaranteed issue policy involves no medical exams or health questions and guarantees acceptance up to a certain age (e.g., 75 years). It has higher premiums and lower coverage amounts and often includes a waiting period (e.g., 2 years) before the full death benefit is paid out.

This is suitable for diabetics with significant health issues or those who have been declined other types of insurance

Life insurance for type 1 and type 2 diabetics
Get life insurance even if you're diabetic!

Our advisors will help you get life insurance plans that best suit your needs!

Comparing life insurance options for Type 1 and Type 2 diabetes patients

Securing life insurance as a diabetic can be challenging, but options exist for both Type 1 and Type 2 diabetes. The eligibility, cost, and coverage depend on factors like age, disease duration, treatment stability, and overall health. 

While traditional life insurance requires medical exams and detailed health records, no-medical life insurance offers a quicker, hassle-free alternative, but at a higher premium. Understanding the differences in insurance options for Type 1 and Type 2 diabetes can help individuals find the best coverage for their needs.

Best life insurance for type 1 diabetics

The availability of a life insurance policy for people with type 1 diabetes depends on the age of the applicant, duration of the disease, and degree of control. Traditional life insurance companies that require lab results will also seek a doctor’s statement to establish the stability of the treatment and the condition.

In most cases, a life insurance company may apply a rating (higher premium) when approving life insurance for those with type 1 diabetes. No-medical, questionnaire-based options make for an easier and faster process in such cases, albeit they offer life insurance for diabetics at higher premiums.

For no-medical questionnaires, the focus is primarily on the age of the insured, the stability of the medication, and the risk of complications. If you are older, with no change in your insulin dependence in the last 12 months and no associated complications, you can easily get life insurance with no medical exam or obligation to provide medical records.

Best life insurance for type 2 diabetics

People with type 2 diabetes can get life insurance in Canada with the possibility of standard, competitive pricing. Life insurance companies are usually more accommodating when offering life insurance to people with diabetes who do not require insulin injections.

Traditional insurance companies may even consider granting standard regular-health pricing (even more affordable life insurance) to someone who is:

  • Above the age of 50
  • Controlling their blood glucose levels and providing lab results with A1C levels
  • Undergoes regular medical check-ups with a physician or specialist
  • Is treated with oral medications that have not been increased in the past 12 months
  • Follows a diet
  • And has no diabetes diagnosis associated complications

There are also several options with no medical exam for people with diabetes who may not be able to get standard pricing or those that may want easier and faster access to life insurance.

Most no-medical life insurance questionnaires contain a few questions that seek to assess how long you have had type 2 diabetes, whether your medications have changed recently, and whether you have any complications associated with this type of diabetes. Based on simple binary questionnaires, the eligibility of life insurance for diabetics can be established fairly quickly.

Best life insurance companies for diabetics in Canada

There are several companies in Canada that cater to individuals looking for life insurance in Canada. Here are some of the best ones to look out for:

  • Canada Life
  • Sun Life Assurance Company of Canada
  • Manulife
  • Desjardins Financial Services
  • Industrial Alliance Life Insurance
  • Beneva Inc.
  • Royal Bank of Canada (RBC)

What factors affect insurance rates for diabetes?

Several factors affect insurance rates for diabetics, as insurers evaluate risk based on how well the condition is managed and its impact on overall health. Here’s a collated list of factors that influence insurance rates:

Age

  • Your age when you apply for a policy: Younger applicants generally secure better rates due to lower perceived risk
  • Your age when you were diagnosed with diabetes: Earlier diagnosis can lead to higher rates due to longer potential exposure to complications

Type of diabetes

  • Type 2 diabetes: More common and generally considered less risky compared to Type 1 diabetes but still affects rates
  • Type 1 diabetes: Often associated with higher risk due to its complexity and potential for complications
  • Gestational diabetes: Typically resolves after pregnancy; however, if it leads to Type 2 diabetes later, it can affect rates

Severity of your diabetes or blood sugar control

  • Well-controlled diabetes with stable blood sugar levels is viewed more favorably by insurers
  • Poor control with fluctuating blood sugar levels or complications can increase risk and lead to higher premiums

Other medical conditions

  • Additional health issues can increase risk and affect premiums
  • A family history of diabetes or related health conditions can influence rates
  • Excessive alcohol consumption can impact overall health and increase insurance premiums
Cost of life insurance for diabetics

Tips to lower life insurance rates for diabetics

Lowering life insurance rates for diabetics will require you to take proactive steps to manage your condition effectively and demonstrate overall good health to insurers. Here are some tips to help reduce premiums:

  • Maintain good control of blood sugar levels through regular monitoring and adherence to treatment plans, which shows effective management of diabetes to insurers
  • Adopt a healthy lifestyle with a balanced diet and regular exercise, which can help improve overall health and potentially reduce the risk of diabetes-related complications
  • Avoid smoking and limit alcohol consumption, as these factors can negatively impact health and lead to higher insurance premiums
  • Regularly visit healthcare providers for check-ups and management of diabetes, showing insurers that the condition is being actively monitored and managed
  • Keep detailed records of your diabetes management, including medications, lifestyle changes, and doctor visits, to provide evidence of effective control to insurers
  • Compare quotes from multiple insurance providers, as different companies may have varying criteria and rates for diabetics
  • Work with an insurance expert who specializes in high-risk cases so you can find a policy that suits your specific health conditions
a1c levels affect life insurance price for diabetes

How to get life insurance with diabetes?

Getting life insurance with diabetes can be more challenging, but with the right approach, you can find suitable coverage. Here’s a step-by-step guide to help you:

Gather your medical information

  • Collect recent medical records, including blood sugar levels, HbA1c test results, and any other relevant health information
  • Prepare a list of all medications you are taking
  • Note any lifestyle changes you’ve made, such as diet and exercise routines

Manage your diabetes effectively

  • Regularly monitor and maintain your blood sugar levels within the target range
  • Follow a balanced diet, exercise regularly, avoid smoking, and limit alcohol consumption
  • Visit your healthcare provider regularly for diabetes management and check-ups

Provide accurate information

  • Submit accurate and detailed records of your diabetes management, including medications, lifestyle changes, and doctor visits, to show that you are managing your condition well

Apply for insurance

  • Complete the application process, which may include a medical exam for some types of insurance
  • If a medical exam is required, prepare by fasting if instructed, getting a good night’s sleep, and avoiding strenuous activities beforehand

Review and choose the best policy

  • Policy review: Carefully review the terms, conditions, and exclusions of your policy
  • Cost vs. coverage: Balance the cost of premiums with the coverage provided to ensure it meets your needs and budget
  • Final decision: Choose the policy that offers the best balance of coverage and affordability

Why does timing matter with life insurance for diabetics?

Timing matters when applying for life insurance as a diabetic because your current health status and diabetes management can significantly influence the premiums and coverage options you receive. Here are some reasons why timing is crucial:

  • Stable condition: Applying when your diabetes is well-controlled and stable can result in more favorable premiums.  
  • Recent health improvements: If you’ve recently made positive changes to your lifestyle, such as losing weight, quitting smoking, or improving your diet and exercise habits, waiting until these changes are reflected in your medical records can lead to better rates
  • Medical advancements: If new treatments or medications for diabetes have been effective for you, showing a period of stability and improved health can work in your favor with insurers
  • Age considerations: Life insurance generally becomes more expensive as you age, so, applying when you are younger and your diabetes is under control can help lock in lower rates.
  • Health monitoring: Regular check-ups and maintaining detailed health records over time can demonstrate a consistent pattern of good diabetes management, which can be appealing to insurers
  • Temporary health issues: If you have temporary health issues unrelated to diabetes, waiting until you recover from these conditions can help you avoid higher premiums that might result from a recent illness or medical event
  • Gestational diabetes resolution: If you developed gestational diabetes during pregnancy and it has since resolved, waiting until you have a track record of normal blood sugar levels and stable health can improve your chances of obtaining better life insurance rates

Life insurance and diabetes: What can help or hurt your case

When applying for life insurance with diabetes, several factors can influence your application positively or negatively. Understanding these factors can help you navigate the process and potentially improve your chances of securing favorable rates.

Factors That Can Help Factors That Can Hurt
Stable blood sugar control: Demonstrating consistent management through stable levels can lead to more favorable premiums Poor blood sugar control: Inconsistent or poorly managed diabetes with fluctuating levels can lead to higher premiums
Healthy lifestyle: A balanced diet, regular exercise, and avoiding smoking and excessive alcohol consumption can improve overall health and lower premiums Unhealthy lifestyle choices: Smoking, excessive alcohol use, and poor diet can increase insurance costs
Recent improvements: Showing positive changes in diabetes management or overall health can be beneficial History of recent medical issues: Recent health problems unrelated to diabetes can negatively influence premiums
Regular medical check-ups: Maintaining regular visits with healthcare providers and detailed health records can help prove effective management Presence of complications: Diabetes-related complications, such as neuropathy or retinopathy, can increase perceived risk and affect rates
Age considerations: Applying for insurance while younger and with well-controlled diabetes can result in lower rates Additional health conditions: Other health issues or comorbidities can further increase risk and premiums

What are some questions insurers may ask about your diabetes?

When applying for a policy that requires a health questionnaire or physical exam, insurers will ask about your general health, lifestyle, and family medical history. They will also have specific questions regarding your diabetes, such as:

  • What type of diabetes do you have? Understanding whether you have Type 1, Type 2, or gestational diabetes helps insurers assess risk levels
  • When were you diagnosed? The age of diagnosis can impact perceived risk, with earlier diagnoses potentially affecting rates
  • Do you monitor your glucose levels regularly? Regular monitoring indicates effective management of your condition
  • Are you taking insulin, oral medication, or both? If so, provide details on the number of insulin units per day, types of medications, and dosages
  • What is your current diet and exercise routine? Your lifestyle choices can affect your overall health and diabetes management
  • What is your current A1C level? This provides insight into your long-term blood sugar control
  • What has been your average A1C reading over the past year? Consistency in A1C levels is important for assessing diabetes control
  • Have you had any other tests related to your diabetes? This includes tests for complications or related conditions
  • Who is your primary care doctor and when was your last visit? You may need to provide contact details for your healthcare team, including endocrinologists
  • Do you have any diabetes-related complications? This could include high blood pressure, vision impairment, blackout spells, or kidney issues
  • Have you been diagnosed with any other serious medical conditions? Conditions like coronary artery disease or kidney disease can affect insurance rates
  • Have you ever experienced a diabetic or insulin coma? Such events may impact your risk profile and premiums
  • Are you currently on dialysis? Dialysis indicates severe complications and can significantly affect insurance costs
  • Have you had any recent hospitalizations or emergency room visits related to your diabetes? Recent health events can influence risk assessment
  • Have you made any recent changes to your diabetes medication or treatment plan? Recent changes can affect your current health status and risk profile
  • What is your current weight, and have you experienced any significant changes recently? Weight fluctuations can impact diabetes management and overall health
  • Have you been advised by your doctor to make any lifestyle changes or undergo additional treatments? Shows ongoing medical advice and treatment adjustments
Need additional help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

What is the best type of life insurance for diabetics in Canada? 

The best type of life insurance for diabetics often depends on individual health conditions and needs. Generally, term life insurance may be more affordable, while permanent life insurance offers lifetime coverage and an investment component. Simplified issue and guaranteed issue life insurance policies might also be options for those who prefer not to undergo a medical exam.

Can diabetics get approved for life insurance in Canada? 

Yes, diabetics can get approved for life insurance in Canada. Approval and rates depend on factors such as the type of diabetes, control of blood sugar levels, and overall health. Insurance companies assess these factors to determine eligibility and premiums.

How much does life insurance cost for diabetics in Canada? 

The cost of life insurance for diabetics in Canada varies based on several factors, including the type of diabetes, age, overall health, and the level of coverage required. Premiums may be higher than for individuals without diabetes due to the increased risk associated with the condition.

When is the best time for a diabetic to apply for life insurance in Canada? 

The best time for a diabetic to apply for life insurance is when their diabetes is well-controlled and stable. Applying when you are younger and healthier can also help secure better rates. It is advantageous to apply after recent improvements in diabetes management or overall health.

Do all life insurance companies in Canada offer coverage for diabetics? 

Not all life insurance companies in Canada offer coverage for diabetics. Some insurers specialize in high-risk cases and may provide coverage options tailored to diabetics. It is important to compare policies and work with a broker who can help find insurers willing to offer coverage.

Can diabetics get a life insurance policy if they have been turned down before?

Yes, diabetics can get life insurance if they have been turned down before or denied coverage. Read more about your life insurance options when your application has been declined.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Return of Premium in Critical Illness Insurance: What You Need to Know

A return of premium (ROP) rider in critical illness insurance is an optional add-on that refunds the premiums you’ve paid if you don’t make a claim during the policy term or under specific conditions, such as surviving the term or passing away.

If you’re considering critical illness insurance, adding an ROP rider can help you feel more secure about your investment. This rider ensures that even if you never need to use the coverage, you’ll still benefit financially.

In this article, we’ll explain how the return of premium rider works and benefits your finances.

How does a return of premium work?

In critical illness insurance, return of premium riders are available usually as an add-on. With this rider, you pay your monthly premiums as usual, and the policy provides coverage for critical illness or disability claims.

However, if no claim is made or under specific conditions, the insurance provider refunds a portion or all of the premiums you’ve paid.

There are three common types of ROP:

  • Upon death (Return of premium on death – ROPD): If you pass away while the policy is active, the insurer refunds all eligible premiums to your appointed beneficiary
  • At the end of the contract (Return of premium on expiry): If the policy term ends without a claim, the insurer refunds the premiums paid
  • On cancellation or surrender (Return of premium on cancellation/surrender): Some insurers offer partial or full premium refunds after a set number of years or at specific ages, like 65 or 75

Each provider has unique rules about how premiums are refunded and under what circumstances. To ensure you choose the right option for your needs, we recommend that you schedule a call with our experienced advisors.

How much does Critical Illness Insurance cost?

Get instant quotes from Canada's top critical illness insurance providers and find the perfect coverage for your family.

$100K

What are the benefits of return of premium riders?

Return of Premium (ROP) riders provide peace of mind by refunding premiums, adding value to your insurance, offering flexible refund options, and reassuring risk-averse policyholders.

A return of premium rider:

  • Ensures that you get a refund of premiums if no claim is made
  • Turns your policy into a savings tool with either coverage or a payout
  • Offers reassurance for those worried about losing their investment
  • May offer refunds on expiry, surrender, or death, depending on the rider

What are the disadvantages of return of premium riders?

The disadvantages of return of premium riders are that they come with higher premiums, require long-term commitment, may exclude certain fees from refunds, and could limit potential investment opportunities.

  • Higher premium costs: The rider significantly increases your policy premiums
  • Long-term commitment: Requires maintaining the policy for the full term to benefit
  • Limited returnable premiums: Refundable premiums may exclude certain fees or add-ons
  • Opportunity cost: Extra premiums could be invested elsewhere for potentially higher returns

Which critical illness insurance providers offer return of premium riders?

Many Canadian insurance providers such as Beneva, Sun Life, RBC, Industrial Alliance, Desjardins, Manulife, Canada Life, and Empire Life offer return of premium (ROP) riders.

These riders are offered with different options like Return of Premium on Death (ROPD), Return of Premium on Expiry (ROPX), Return of Premium on Cancellation (ROPC), and other flexible refund features.

Insurers offering return of premium riders with critical illness plans

Insurance Provider ROP Options
Beneva  ROPD, ROPX, ROPC
Sun Life  ROPD, ROPX, ROPC
RBC  ROPD, refunds all premiums if the policyholder dies while the policy is active
Industrial Alliance ROPD and flexible ROP options that vary by term
Desjardins  ROPD, ROPX, ROPC
Manulife  ROPD, ROPX, Return of Premium on Surrender (ROPS), with partial/full refunds based on term
Canada Life Various ROP options included in critical illness plans; specifics depend on the plan
Empire Life Return of Premium on Surrender or Maturity, offering percentage refunds if no claims are made

Learn more about the best critical illness insurance companies in Canada
Looking for the lowest return of premium rates?

Get the best quotes at PolicyAdvisor!

What is the cost of a return of premium rider in critical illness insurance?

The cost of adding a return of premium (ROP) rider in a basic critical illness policy costing $79.65 per month could be $117.99 per month

A return of premium rider significantly increases your critical illness insurance premiums, typically by 30–50%, depending on the rider type, insurer, and your policy details.

These costs also differ based on the type of return of premium rider:

  • Return of premium on death (ROPD): Lower additional cost since it refunds premiums only if the insured passes away during the policy term
  • Return of premium on expiry (ROPX): Higher cost as it guarantees a full refund of premiums if no claim is made by the end of the term
  • Return of premium on surrender (ROPS): Costs are similar to ROPX but allow partial refunds if the policy is canceled early

Additionally, long-term policies like term-75 or lifetime coverage tend to incur higher premiums for ROP riders due to extended refund commitments.

Is a return of premium on critical illness taxable?

No, the return of premium (ROP) benefit on critical illness insurance is generally not taxable in Canada. When you purchase a critical illness insurance policy, you pay your premiums using after-tax dollars, meaning the money you use to pay for the policy has already been taxed.

Therefore, when you receive a refund of those premiums through an ROP rider whether upon expiry, surrender, or death, it is treated as a return of your personal contributions, not as income.

Comparison of return of premium riders with traditional critical illness insurance

Return of premium riders enhance critical illness policies by offering premium refunds, unlike traditional plans that provide coverage only. Here’s how these differ:

Premium refunds:

  • ROP riders: Refund premiums if no claim is made (on expiry, death, or surrender)
  • Traditional CI plans: Do not refund premiums regardless of claims

Cost:

  • ROP riders: Typically 30–50% more expensive
  • Traditional CI plans: More affordable but lack refund benefits

Flexibility:

  • ROP riders: Allow refunds under specific conditions (expiry, death, surrender)
  • Traditional plans: Offer no such options

Best suited for:

  • ROP riders: Ideal for risk-averse individuals seeking financial security
  • Traditional plans: Suitable for those focused on lower premiums
Critical illness riders vs Critical illness insurance: Read more!

How do I get a return of premium coverage?

You can add a return of premium rider to your critical illness insurance policy while purchasing the plan or during eligible upgrade periods.

To get ROP coverage, you need to consult with your insurance provider to explore available rider options. Typically, a return of premium rider is added when purchasing a long-term critical illness policy. The process may involve assessing your eligibility based on age, health, and other criteria.

To qualify for ROP coverage, you must meet specific insurer requirements regarding age, policy type, and health status.

  • Age requirements: Most insurers offer ROP riders to individuals aged 18–65
  • Policy type: ROP is typically available on long-term critical illness policies, not short-term plans
  • Health status: Eligibility may require passing a medical exam or meeting the insurer’s health guidelines
  • Consistent premium payments: Some insurers mandate a history of timely premium payments
  • Insurer-specific rules: Each provider may have unique conditions for adding ROP, such as coverage amount or policy terms
Read more about when to get critical illness coverage.
Need help?

Call us at 1-888-601-9980 or book time with our licensed experts.

Frequently asked questions

What happens to my return as a premium rider if I cancel my policy early?

If you cancel your critical illness insurance policy early, the impact on your return of premium (ROP) rider depends on the specific terms of the rider. Policies with a Return of Premium on Surrender (ROPS) option may provide a partial refund based on how long the policy was active.

For example, you might receive 50% of your premiums back after 20 years, with the percentage increasing the longer you keep the policy. However, not all ROP riders include this option, so it’s important to review your policy details.

Can return of premium riders be added to existing critical illness policies?

In most cases, return of premium (ROP) riders cannot be added to an existing critical illness insurance policy. ROP riders are usually selected at the time of purchase and integrated into the policy from the start. If you are interested in this feature, you may need to apply for a new policy that includes an ROP option.

How does a return of premium rider affect my overall premium rates compared to standard policies?

Adding a return of premium (ROP) rider to your critical illness insurance policy can significantly increase your premium rates—typically by 30–50%. The exact increase depends on the type of ROP rider (e.g., on expiry, death, or surrender), the policyholder’s age, and the duration of the policy.

For instance, a standard premium of $79.65 per month could rise to $117.99 with an ROP rider, reflecting an additional $33.84 monthly. While the cost is higher, the rider offers added financial security and peace of mind.

Are there any age restrictions for purchasing a return of premium rider with critical illness insurance?

Yes, there are generally age restrictions for purchasing return of premium (ROP) riders, and these vary by insurer. Most providers allow ROP riders for policyholders up to a specific age, such as 60 or 65, since the rider often involves long-term commitments or payouts tied to policy maturity.

Additionally, age impacts the cost, as older policyholders typically face higher premiums for adding an ROP rider. Be sure to check the eligibility criteria with your insurer.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Should I get life insurance if I’m covered through work?

Getting individual or private life insurance to supplement your group life insurance plan is usually recommended to ensure you have adequate coverage. Almost 39% of life insurance policies in Canada are through group term insurance. With such a large number of Canadians covered through their work, many are under the impression that it’s enough coverage for their family too.

However, group life insurance plans have limitations and restrictions, and offer limited coverage. Read on to know more about group and individual life insurance plans, their advantages and disadvantages, and more.

What is life insurance?

Life insurance is an agreement between you and an insurance company that in the event of your demise, they will pay a lump sum, tax-free death benefit to someone you choose (your beneficiaries). In exchange, you agree to pay a premium to the insurance company. 

There are two main types of life insurance plans that an individual can choose from:

  • Term life insurance that lasts for a specific period of time, generally 10, 20, or 30 years
  • Permanent life insurance which covers you for your entire life and generates a cash value component. Some policies also pay dividends depending on your plan type

Life insurance can be bought by an individual (personal life insurance) or offered by an employer as part of a group plan. 

Learn more about the different types of life insurance
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is group life insurance?

A group life insurance is  a contract or an agreement that promises to pay an employee’s dependents a tax-free lump sum amount in the event of their demise. It is offered by an employer to a “group” of people—the employees. A group life insurance policy helps soften the financial impact that comes with losing an earning member of a family. 

Most group life benefits are offered as term life insurance that is renewed annually by the insurance provider. Unlike whole life insurance which covers an individual for their entire lifespan, term life policies provide coverage for a certain “term” or fixed period of time. 

Read about group life insurance in our comprehensive guide

Do I need individual life insurance if I am covered through work?

Yes, supplementing your group life insurance with individual life insurance coverage is highly recommended. Group life insurance plans generally payout up to one or two years of your salary. This may not always be enough for your family after you pass away. 

To ensure your family’s living expenses, your funeral fee, your children’s education costs, and other expenses, are covered, you need to get individual life insurance. When you buy an individual life insurance plan, you also get the option to get a participating whole life insurance policy. This type of policy gives you a cash value component and dividends, both of which can be accessed while you’re alive or after your demise. 

how much life insurance do i need?
Check out PolicyAdvisor's life insurance calculator.

What is the difference between group and individual life insurance?

Group life insurance is offered by an employer to a group of people (the employees), while individual life insurance only covers the primary policyholder. Group life insurance plans offer limited coverage and the plan details are designed based on the employer’s budget and recommendations. Individual life insurance policies are customized to fit the needs of the policyholder. It lets policyholders choose their coverage amount, duration, and add additional riders to their core plan. 

Difference between group and individual life insurance

Feature Group life insurance Individual life insurance
Coverage type Usually offered as a term life insurance plan to all group members Individual policyholders can choose between term and permanent life insurance plans depending on their financial requirements
Premiums Lower premiums since the insurer’s risk is spread in a larger pool Typically more expensive since the policies are customized for an individual
Portability Coverage is tied to employment—if you leave your job, you are likely to lose coverage Coverage lasts for as long as you pay your premiums or your policy’s duration
Flexibility Limited Highly flexible 
Tax implications Tax benefits are generally limited to premiums paid by the employer, and employees may not receive additional tax deductions Premiums paid can often be deducted from taxable income under certain conditions, providing potential tax advantages

Life insurance through work
Have group life insurance?

Speak to one of our licensed insurance experts and find a personal life insurance plan that supplements your group coverage!

What type of life insurance do employers offer as a group benefit?

Most employee life insurance is term life insurance. Although other types of permanent life insurance are also sometimes offered.

With group term life insurance plans, the death benefit is offered as a flat dollar amount, as a multiple of an employee’s annual salary (such as one or two times your annual salary), or a mix of both.

Do employers pay for group term life insurance?

Most private employers will pay for a substantial, if not the entire, portion of the premiums for group life insurance. The only thing to note: the coverage offered is typically basic. This means there is no customization or riders built in. The cost of additional supplementary coverage is usually paid for by the employee.

What are the benefits of group life insurance?

There are a number of benefits of group life insurance that make it an attractive option for those who are offered it through work or a professional association.

Affordability: An employer often pays for most – if not all – of the life insurance premium so there is very little or no cost to the member of the plan. If you do need to pay a portion of the premiums, they are usually less expensive. This is because the insurance company prices it on the basis of the underlying risk profile of the entire group as a whole rather than as an individual insurance applicant.

Convenience: It’s easy and convenient to sign up with only a small amount of paperwork and no individual underwriting. The payments are usually through payroll deduction, so no worries about policy lapsing because you missed your premium payments.

Limited underwriting: Most group term life contracts do not require any medical exam to be administered to the individual plan members. Members may be automatically or voluntarily enrolled in the overall group life insurance plan. However, an eligible employee may be required to go through medical underwriting, to establish good health in special circumstances such as when seeking an amount higher than the group coverage or when trying to rejoin the plan, after initially declining coverage.

What is the main disadvantage of group life insurance?

The main disadvantage of group life insurance is the one-size-fits all approach that assumes that every member of the group is likely to need the same amount of coverage. This is not always the case and life insurance coverage should be customized to individual needs. 

Other disadvantages of a group life insurance policy are:

Lack of control: Another disadvantage is that the plan sponsors (i.e. the employer or the organization) or even the insurance company can change the plan anytime they choose or even discontinue it altogether. Because you are sharing a plan among others in a group, it cannot be tailored to meet your own unique needs. There may be exclusions for medical conditions that you may have.

Limited portability: Group life insurance is dependent on an individual’s affiliation with the group. Just because one particular job includes insurance, there’s no guarantee that the next one will. If you find yourself in a position where you need to purchase life insurance once you make a career change, your premiums are likely to be much higher by then as you are a little older and more expensive to insure from an underwriting perspective.

Taxation: Lastly, depending on how your employer structured the benefit fees, you might need to pay taxes on the payout.

What happens to my group life insurance coverage if I leave my employer?

Employer-offered life coverage is linked to your employment. This means it covers you and your dependents until your employment period ends—whether you quit or you’re fired by the employer.

Many employer-offered plans include an option to convert the group coverage to an individual policy, upon leaving the employer. However, the cost of conversion from group to individual coverage is significantly higher and most people tend to get new individual coverage at that time. 

Typically, only those individuals who may have pre-existing health conditions, and may find it hard to get individual coverage based on a medical exam, will take advantage of this conversion option.

More choice. Lower price.

PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!

Frequently asked questions

Does life insurance cover job loss?

No, life insurance does not cover job loss. It pays your beneficiaries a lump sum of money in the event that you, the employee, pass away. Job loss insurance is a separate insurance product. Disability insurance provides income replacement (usually 60-80%) in the event that you are injured or ill and can no longer work. 

Does group life insurance end at retirement?

Yes. Group life insurance is dependent on your continued employment; therefore, at retirement, your group life insurance also expires. However, as mentioned above, you will typically have the ability to convert the group plan into individual coverage, without providing any evidence of good health. The conversion has to be requested within a limited period of time, usually 31 days. The conversion option is much more expensive since no evidence of good health is provided.

Are my dependents covered through employer life insurance?

Sometimes. Most employer-offered life insurance plans will allow an employee to extend coverage to also include their dependents, such as married or common-law spouse and dependent children up to a certain age, such as 21 years. But that’s not always the case, so check your policy documents!

Is group life insurance a taxable benefit?

Yes, employer-paid life insurance is considered a taxable benefit. With group term life insurance paid by the employer in Canada, the premiums appear on your T4 slip and are reported on your tax return as a taxable benefit.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */