Pregnancy travel insurance: Everything you need to know

Travelling can be an exciting adventure, but when you’re expecting a little bundle of joy, it comes with unique considerations. Many parents-to-be opt for a “babymoon” to enjoy a final getaway before their baby’s arrival, while others approach travel more cautiously.

Whichever path you choose, it’s natural to have questions about travelling while pregnant and how to ensure you’re properly covered. In this guide, we’ll explore the ins and outs of pregnancy travel insurance to help you make an informed decision.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

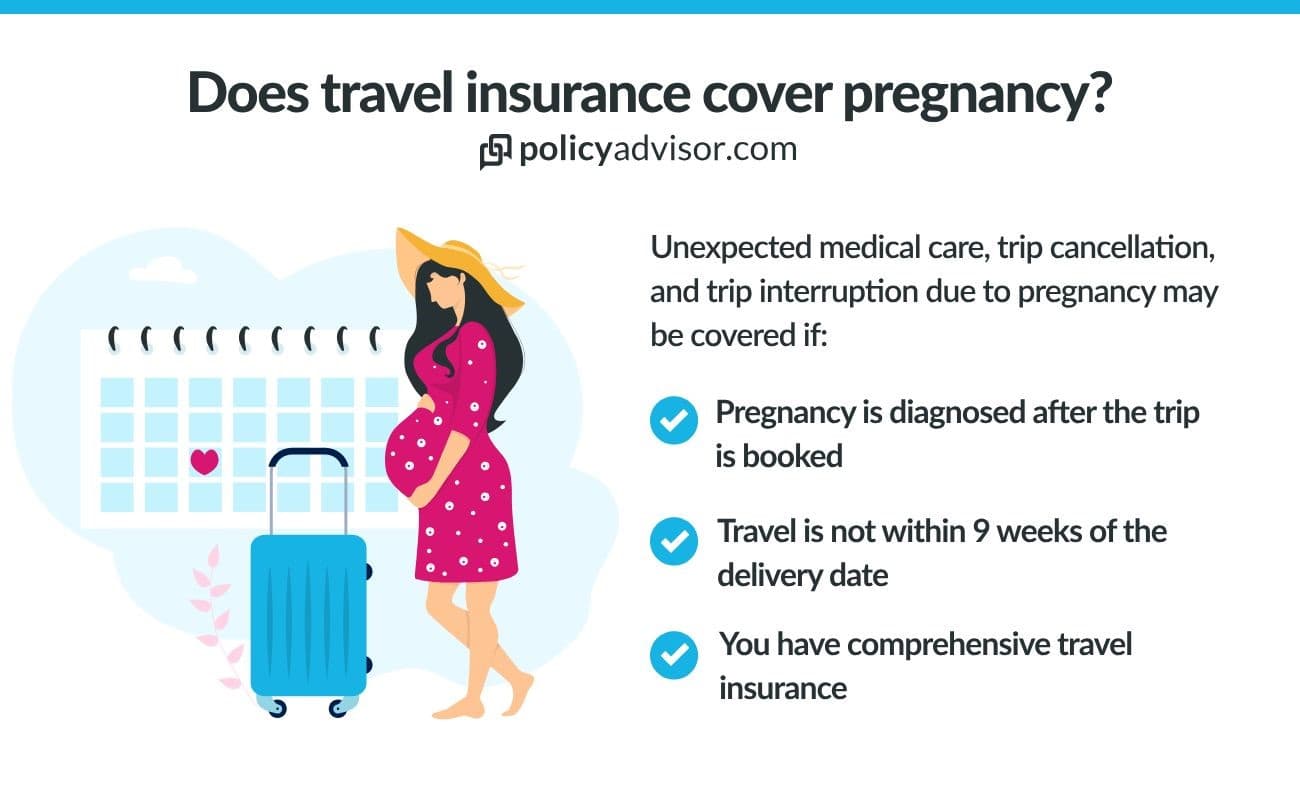
Does travel insurance cover pregnancy?

Yes, travel insurance may cover pregnancy-related medical expenses depending on your specific circumstances and policy.

Most Canadian insurance companies will not cover pregnancy-related medical expenses within nine weeks before or after the expected delivery date. This means if you’re in the late stages of pregnancy or shortly after giving birth, coverage for related complications is typically excluded.

However, if you plan your trip for a time more than nine weeks before your expected delivery date, and you were not pregnant when you booked your travel, most travel insurance policies will cover you for medical emergencies during your trip.

Additionally, most policies do not cover routine pregnancy check-ups or cancellations purely due to pregnancy unless it’s due to an unforeseen medical emergency.
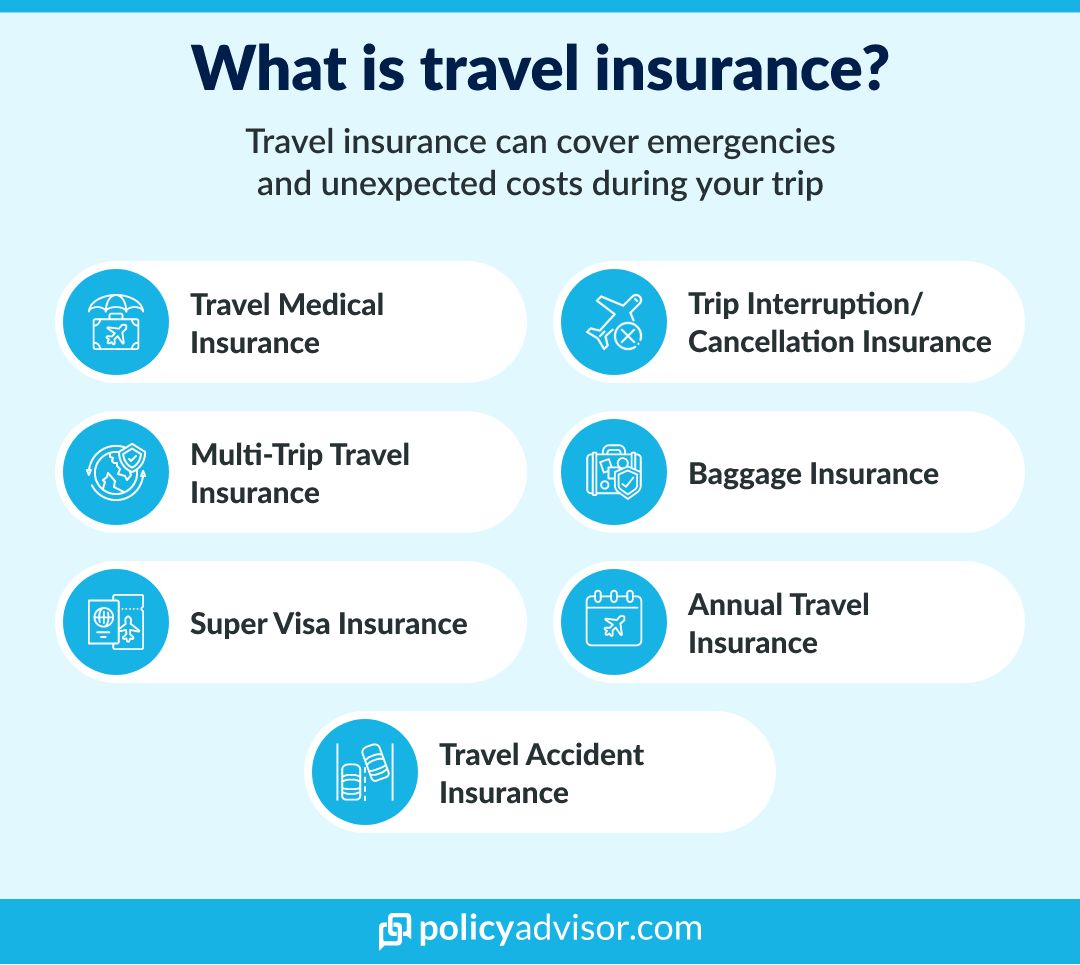
There are many different types of Travel Insurance for students, foreign workers, snowbirds, super visa holders, and others travellers to/from/within Canada.

What is travel insurance?

Travel insurance provides coverage for medical expenses if you become sick or injured during your trip, and can also cover expenses that occur if your trip is cancelled or interrupted due to unforeseen events.

What does travel insurance cover?

Travel insurance covers medical expenses, trip cancellations or interruptions, lost luggage, and other unexpected travel-related costs.
  • Travel medical and dental care
  • Ambulance transportation and repatriation
  • Stable pre-existing health conditions
  • Travel accidents
  • Prescription drugs
  • Trip cancellation
  • Trip interruption
  • Baggage lost/stolen items
Travel insurance can provide some coverage to pregnant travellers.

Do you need travel insurance if you’re pregnant?

Yes, it’s highly advisable to have travel insurance if you’re pregnant. Travelling while expecting can come with unexpected challenges, and having insurance provides peace of mind.

​​For comprehensive coverage, you should consider policies that include trip cancellation, medical expenses, and emergency medical evacuation, as these will ensure you’re protected against unforeseen complications.

Eligibility criteria for pregnancy travel insurance

How many weeks pregnant can you get travel insurance?

Most travel insurance providers in Canada offer coverage for pregnant travellers until nine weeks before their due date, usually around the 28th to 32nd week of pregnancy. Therefore, if you plan to travel, it’s best to do so before reaching this stage to secure appropriate travel insurance coverage.

Is pregnancy considered a pre-existing condition?

A normal pregnancy is considered pre-existing for travel insurance if the insured person was pregnant before they bought the policy, or if they became pregnant before their trip starts.

A pre-existing condition is a health issue the traveller had been diagnosed with before they had their insurance policy. It includes health issues like cancer, diabetes, mental health conditions, etc.

Pregnancy is not considered pre-existing if the traveller becomes pregnant after the date their policy starts, which is usually the first day of their trip. For instance, if you’re halfway through your vacation and suddenly find out you’re pregnant, that will not be considered pre-existing and you could be covered for some unexpected healthcare costs if needed.

For normal pregnancies that are pre-existing, no routine care will be covered. You will not be covered for any emergency medical care within nine weeks before or nine weeks after your delivery date.

High-risk pregnancies are also considered pre-existing health conditions, and will not be covered at all.
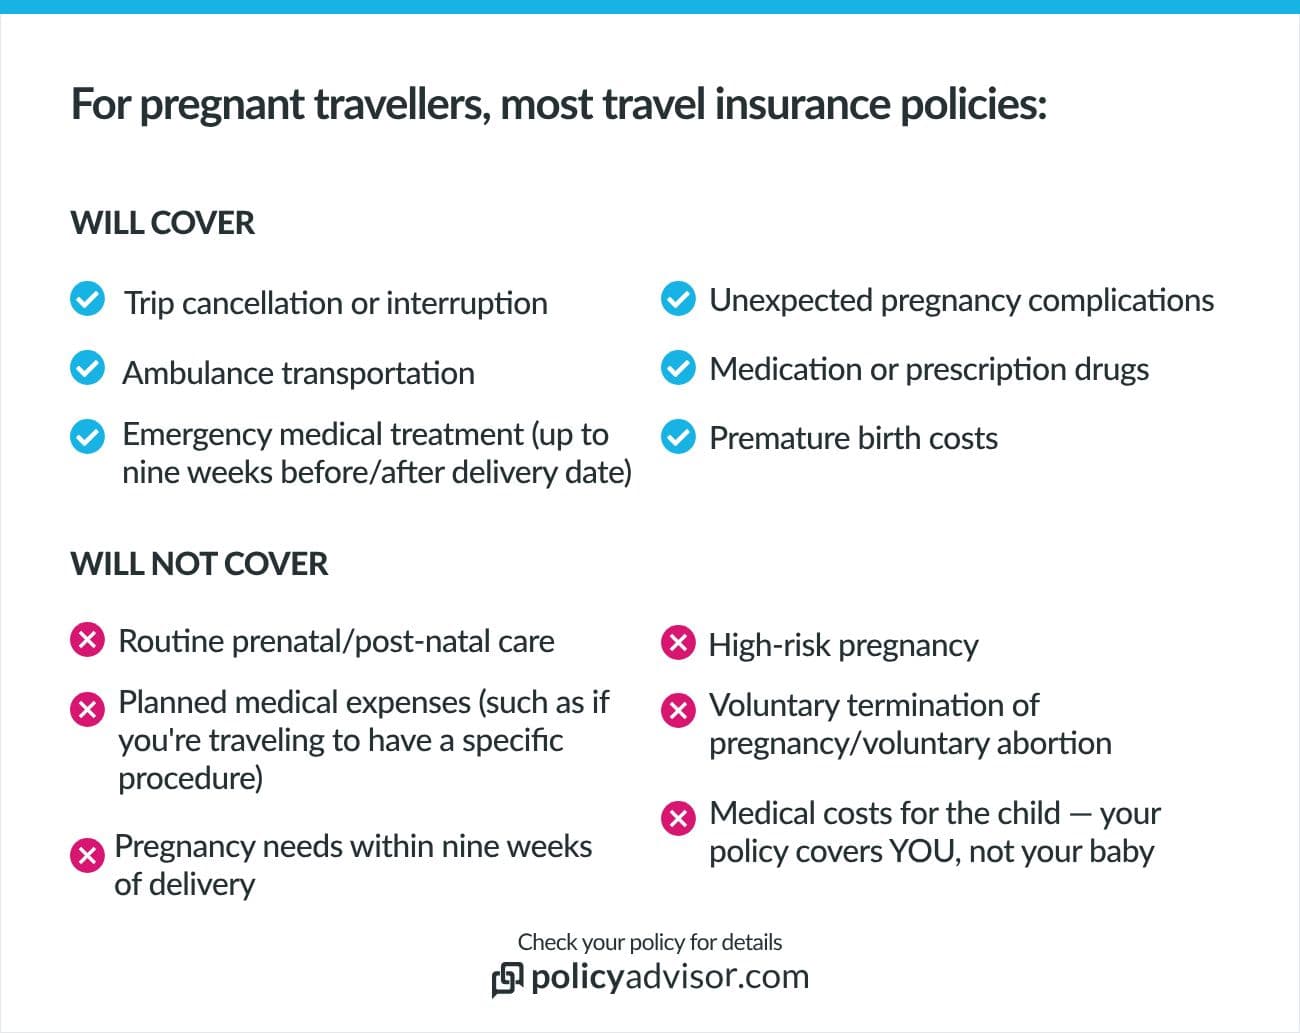
Travel insurance coverage for pregnant travellers depends on several factors.

Does travel insurance cover labour or pregnancy-related issues?

Travel insurance can sometimes cover labour or pregnancy-related issues, but it depends on when the travel was booked, how close is your due date, the date you purchased your travel insurance policy, the type of coverage you’ve chosen, and whether the pregnant person is a Canadian resident travelling abroad or a visitor to Canada.

1 Labour

If you travelled within nine weeks of your expected due date, most policies will not cover any care related to your pregnancy or if you go into labour. This is the case whether you’re a travelling Canadian or a visitor to Canada. However, some providers will still cover labour costs if you become pregnant after you have already purchased the travel insurance policy.

If you unexpectedly give birth more than nine weeks from your expected due date, then travel insurance will cover those costs. In this case, it will be treated as a medical emergency. This is the case whether your pregnancy was pre-existing or not.

However, most providers will not cover costs for your child who is born during the trip, whether for travelling Canadians or visitors to Canada. This means that if your newborn baby needs any neonatal intensive care, common with pre-mature birth, this will not be covered.

2 Pregnancy complications

If a pregnant person has complications during their trip, most travel insurance plans will see it as a medical emergency. But this is only if they still have more than nine weeks until the expected due date.

Travel insurance can cover medical expenses related to unforeseen complications like:

  • Gestational diabetes (when the mother develops diabetes as a result of pregnancy)
  • Preeclampsia (when the mother experiences dangerous high blood pressure and organ damage)
  • Hyperemesis gravidarum (a severe form of morning sickness)
  • Miscarriage (when the pregnancy prematurely ends on its own)

If there are problems with the pregnancy during the trip and you’re close to your due date (within nine weeks), your travel insurance will not pay for the medical care or expenses related to it.

3 High-risk pregnancy

Most travel insurance plans do not cover pregnancies that have additional risks. But if an expecting mother has pre-existing pregnancy complications, doctors often advise them not to travel at all to keep everyone safe.
Protect your trip and your little one!

Let our experts help with choosing the best pregnancy travel insurance.

Can you cancel your trip due to pregnancy?

Yes, you may be eligible to cancel your trip due to pregnancy and receive reimbursement for non-refundable expenses. However, this depends on the following conditions:

  • You have trip cancellation coverage or cancel-for-any-reason insurance
  • The pregnant individual is:
    • You
    • Your spouse
    • A travel companion
    • The spouse or family member of a travel companion
  • The pregnancy occurs after the trip is booked
  • The pregnancy begins after the insurance policy has been purchased
  • The delivery date falls within nine weeks of the scheduled trip
  • A doctor advises against travel for the pregnant individual

If these conditions are met, your travel insurance policy can help recover costs associated with flights, accommodation, and other non-refundable expenses. Depending on the policy, it may cover some or all of these costs that would otherwise be lost.

However, in the case of late-term pregnancy, most policies do not cover costs related to routine pregnancy, such as if a doctor advises against travel during the 8th or 9th month as a precaution.

Can you end your trip early because of a pregnancy? 

Trip interruption coverage may kick in if you’re already on your trip but want to end it early and go home because of a pregnancy. But it depends on your specific situation and your insurance provider’s rules.

Let’s say you’re on vacation when you realize you’re pregnant, so you want to go home immediately. Your travel insurance may not cover this if the pregnancy is not yet formally diagnosed or if it’s considered normal. And unless you’re travelling for months, you likely won’t be that heavily impacted.

On the other hand, if your babymoon to the Caribbean goes south and you start experiencing pregnancy complications, travel insurance could help cover both emergency medical costs and trip interruption costs. It can cover the costs of returning home early, as well as any unused portions of your trip.

Which Canadian insurance providers should pregnant travellers consider?

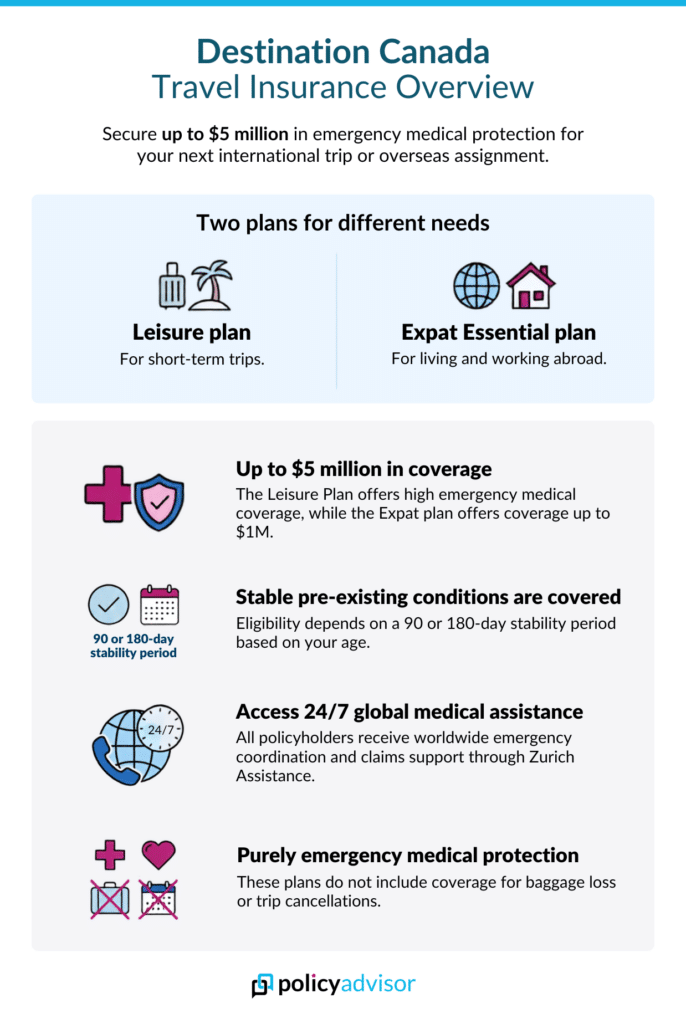
If you’re looking for insurance with pregnancy coverage, you can consider the best Canadian travel insurance companies such as GMS, Destination Canada, Tugo, Allianz Global Assistance, Manulife, etc.

You can compare the best travel insurance quotes from these providers and others right here at PolicyAdvisor!
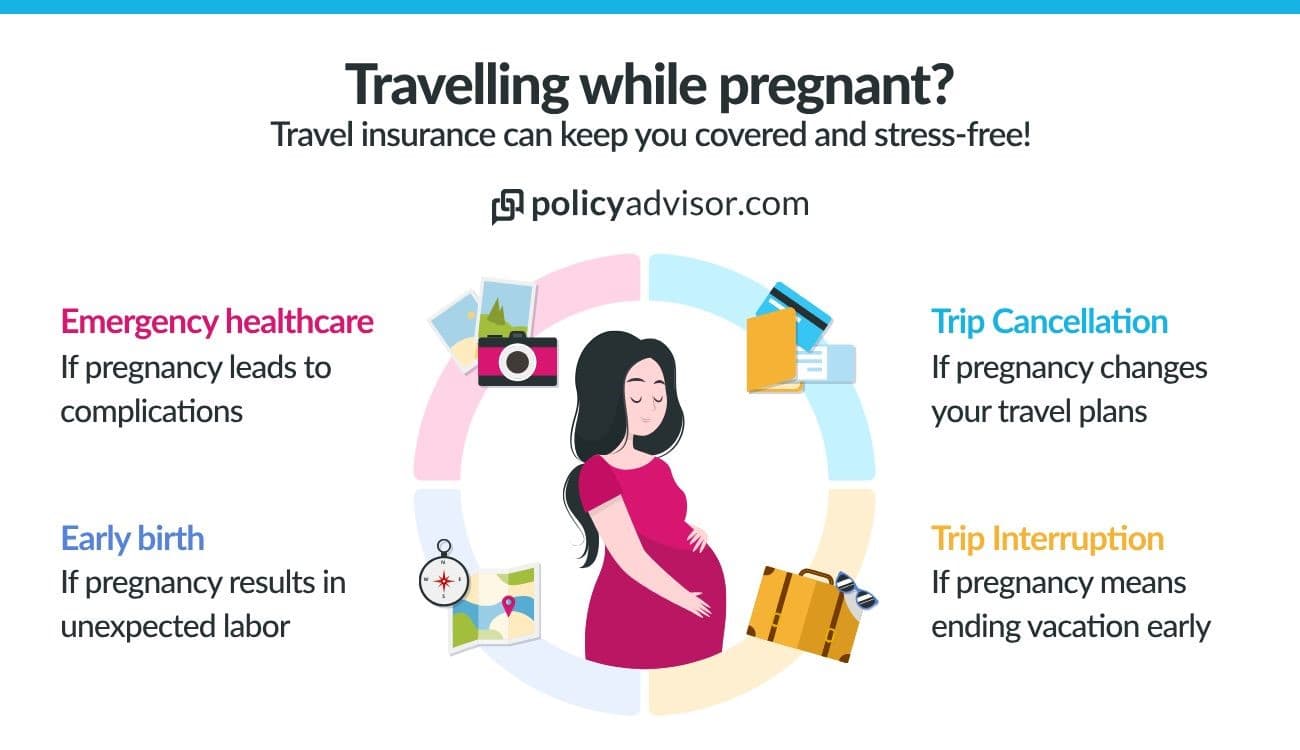
Travel insurance helps you travel with peace of mind, even if you're expecting a baby.

Frequently asked questions

Will travel insurance cover if you deliver a baby in Canada?

No, if you are a visitor you should not come to Canada to deliver your baby. Healthcare costs will not be covered and your travel insurance will not cover your medical expenses or any expenses incurred by your newborn baby.

The same applies to Canadian citizens and residents who deliver babies abroad. Travel insurance does not cover normal deliveries.

How many months pregnant can you travel?

In general, you can travel up to 36 weeks of pregnancy. This is whether you’re travelling by airplane, by boat, or by car. However, you must bear in mind that:

  • Not all travel insurance providers will cover you that close to your expected due date
  • Some airlines may not allow you to travel that close to your expected due date
  • Your doctor may advise you to hold off on travel

It can be tempting to just hop on the next plane out of here if you’re far out from your due date, but you should consider factors like this before making a decision.

What are the flying restrictions for pregnant women?

Most airlines allow pregnant women to fly up to 36 weeks for single pregnancies and up to 32 weeks for multiples, provided there are no medical complications. After 28 weeks, a medical certificate confirming the due date and fitness to fly may be required. Each airline has its own rules, you need to check with the airline before booking. 

Is a newborn covered under insurance?

Many travel insurance policies for infants only begin covering your baby 90 days after birth, leaving a gap that may be crucial in case of hospitalization needs. To ensure safety, opt for a travel insurance policy that allows adding your baby to the cover immediately after birth, providing comprehensive coverage for any medical emergencies during your trip.

Do I need to tell the airline I’m pregnant?

Yes, it’s recommended to inform the airline if you’re pregnant, especially if you’re in the later stages of pregnancy. Some airlines have specific policies regarding air travel during pregnancy, particularly after 28 weeks, and may require a medical certificate from a doctor confirming you’re fit to fly.

Does pregnancy travel insurance cover multiple pregnancies or high-risk pregnancies?

Pregnancy travel insurance typically covers pregnancy-related complications, but coverage for multiple pregnancies (e.g., twins) or high-risk pregnancies may vary depending on the provider and policy.

Many standard policies exclude coverage for pregnancies beyond a certain week (usually 32-36 weeks), and high-risk pregnancies might require specialized coverage. So, it is best to check policy terms and see what is covered and what is not.

When should you avoid travelling during pregnancy?

You should avoid travelling during pregnancy if you have a high-risk pregnancy, such as a history of complications or multiple pregnancies. It’s also advisable to avoid travel if your healthcare provider advises against it, if you’re experiencing severe symptoms like high blood pressure, or if your destination has limited access to proper medical care.
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

TuGo travel insurance review Canada (2026)

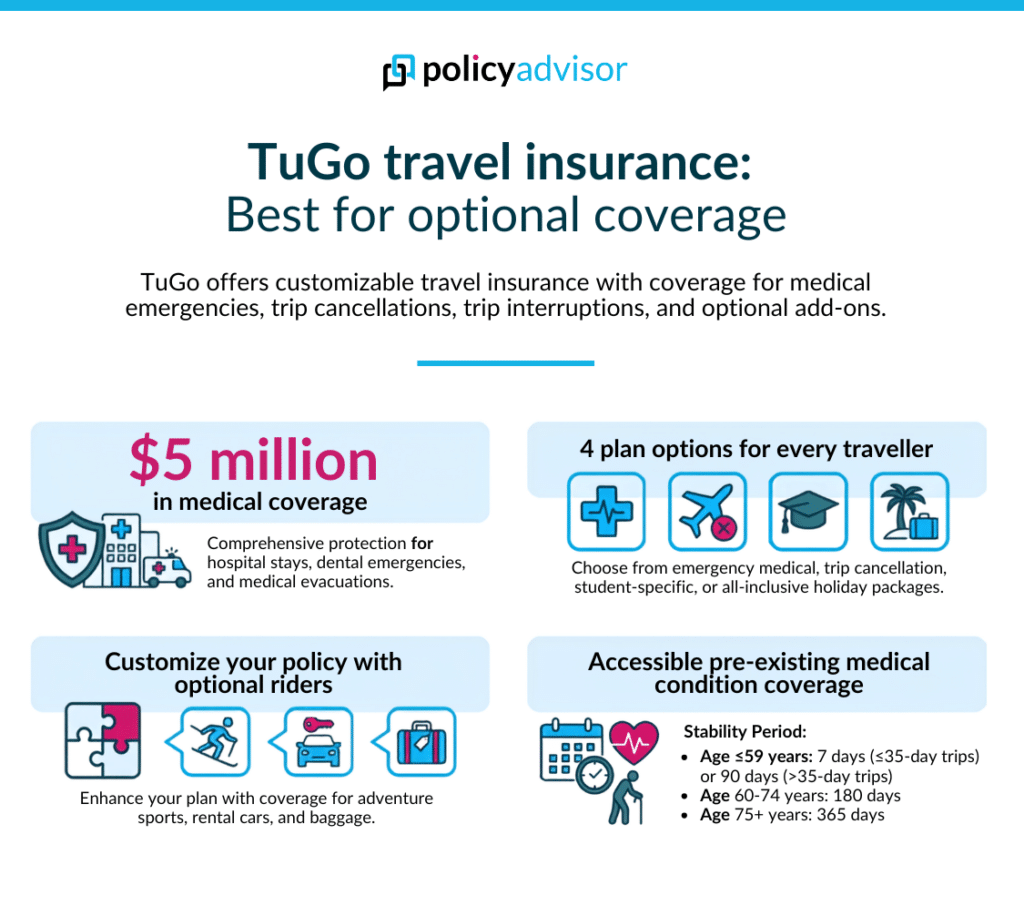
TuGo is one of the few Canadian insurers that lets you add cover for adventure sports and for pre-existing conditions that aren’t fully stable. Its plans include up to $5 million in emergency medical coverage, along with benefits for trip cancellation, trip interruption, baggage loss, travel delays, and more, depending on the plan type. The cost of TuGo travel insurance ranges from $142.56 to $662.02, depending on the traveller’s age, plan type, trip duration, and a few other factors.

Quick review: TuGo travel insurance

  • PolicyAdvisor ratings: 5/5
  • Best for: Optional coverage for adventure sports and unstable pre-existing conditions
  • Skip if: You want baggage coverage included by default with trip interruption plans
Planning a trip soon?

Get a free travel insurance quote now!

What is TuGo travel insurance?

TuGo travel insurance is a customizable travel insurance solution that helps protect you against unexpected expenses before and during your trip. It offers optional coverage like baggage insurance, sports & activities coverage, and a reduced stability rider that helps you tailor your coverage according to your specific travel plans.

North American Air Travel Insurance Agents Ltd., doing business as TuGo, develops and distributes these policies, while OneWorld Assist Inc., operating as Claims at TuGo, is TuGo’s claims and assistance provider and administers all claims on TuGo’s behalf.

Key features of TuGo travel insurance

Plan types
  • Emergency Medical (Single-trip or Multi-trip Annual)
  • Trip Cancellation & Trip Interruption Insurance, or Trip Interruption Insurance Only (Single-trip or Multi-trip Annual)
  • Canadian Student Travel Insurance
  • All inclusive holiday package
Minimum eligibility age  None
Pre-existing coverage
  • Age 59 and under: 7-day stability period for trips of 35 days and less; 90-day stability period for trips over 35 days
  • Age 60 to 74: 180-day stability period for all trip lengths
  • Age 75 and over: 365-day stability period for all trip lengths
  • For the Canadian student plan: 90-day stability period
  • Travel within Canada plans: No stability requirement
Maximum coverage in trip interruption Up to the sum insured
Maximum coverage in emergency medical $5,000,000 & $2,000,000 for Canadian Student Plan
Deductibles $0 / $300 / $500 / $1,000 / $2,000 / $5,000 / $10,000 / $25,000 / $50,000 / $100,000 (Emergency medical only)
Optional riders (except for the Canadian Student Plan)
  • Sports & Activities coverage
  • Baggage Insurance
  • Rental Car Protection (up to $75,000)
  • Reduced Stability Rider
Waiting period A 48-hour waiting period applies if you purchase the policy after departure
Policy extensions Automatically extended when you are medically unfit to travel, you or your travelling companion is hospitalized, or there is a delay by a common carrier

Who is eligible for TuGo travel insurance?

To be eligible for TuGo travel insurance, here are the requirements:

  • You are a Canadian resident
  • You are not travelling against a physician’s or other registered medical practitioner’s advice
  • You have not been diagnosed with a terminal condition
  • You are not receiving palliative care, or palliative care has not been recommended

Types of TuGo travel insurance plans

TuGo offers a range of travel insurance options to protect Canadians before and during their trips. Depending on your travel needs, you can choose Emergency Medical Insurance, Trip Cancellation & Trip Interruption Insurance, Canadian Student Plan, or All Inclusive Holiday Package. Most coverages are available as single-trip or multi-trip annual plans, allowing you to select the option that best matches how often you travel.

Emergency Medical Insurance

This is an emergency medical plan that covers expenses if you become sick or injured while travelling. It is available for all ages as a single-trip or a multi-trip plan. This TuGo travel medical insurance offers coverage for emergency hospitalization, physician services, prescription drugs, emergency dental care, medical evacuation and repatriation, paramedical services, and hospital allowances.

Trip Cancellation & Trip Interruption Insurance

This travel insurance plan in Canada, offered by TuGo, protects your prepaid, non-refundable travel expenses if you need to cancel your trip before departure or return home early due to a covered event. It can also reimburse eligible transportation, accommodation, meals, and other interruption-related expenses. It is also available as both a single-trip and multi-trip plan. TuGo also offers a plan that provides coverage for Trip Interruption only. 

Canadian Student Plan

The Canadian student plan is designed for Canadian students aged 40 and under studying outside their home province or territory. This plan provides coverage for emergency medical expenses, along with student-focused benefits such as emergency dental care, paramedical services, repatriation, tutorial assistance, maternity coverage, annual health examinations, and accidental death & dismemberment benefits. 

All Inclusive Holiday Package

This plan is designed for Canadian residents aged 59 years or younger. This single-trip plan bundles emergency medical insurance, trip cancellation and interruption, accidental death & dismemberment, and baggage insurance into one comprehensive package. It is a convenient option for travellers who want broad protection for both medical emergencies and travel-related disruptions in a single policy. 

Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

What is covered under TuGo travel insurance?

TuGo travel insurance provides comprehensive protection against unexpected medical emergencies and travel disruptions. Depending on the plan you choose, your coverage may include the following benefits:

  • Emergency medical expenses: Covers eligible hospitalization, physician services, diagnostic tests, and emergency treatment while travelling
  • Emergency dental care: Covers eligible emergency treatment for accidental dental injuries
  • Prescription drugs: Reimburses eligible medications required to treat a covered medical emergency
  • Emergency medical evacuation and repatriation: Covers ambulance services, medical evacuation, and repatriation to Canada
  • Trip cancellation and trip interruption: Reimburses eligible travel costs if you need to cancel or cut short your trip due to a covered reason
  • Baggage loss, damage, and delay: Optional baggage coverage reimburses the cost of lost, stolen, or damaged baggage
  • Paramedical services: Covers eligible treatment from licensed healthcare practitioners, such as physiotherapists and chiropractors
  • Hospital allowance and incidental expenses: Covers eligible hospital allowances and certain incidental expenses during a covered medical emergency
  • Accidental death & dismemberment (AD&D): Provides a lump-sum benefit for covered accidental death or permanent injuries

TuGo travel insurance plans coverage at a glance

Features Emergency Medical Insurance Trip Cancellation & Trip Interruption Insurance All Inclusive Holiday Package Canadian Student Plan
Emergency medical (overall limit $5,000,000 NA $5,000,000 $2,000,000
Hospital accommodation Up to the policy limit for in-patient / out-patient emergency medical treatment, physician services,

private duty nursing, x-rays & lab tests, essential medical appliances

NA Up to the policy limit Up to the policy limit for in-patient / out-patient emergency medical treatment, physician services,

private duty nursing, x-rays & lab tests, essential medical appliances

Prescription drugs Up to a 30-day supply following an emergency during the trip; up to $200 for a physician visit to

replace lost, stolen, or damaged prescriptions

NA Up to a 30-day supply following an emergency during the trip; up to $200 for a physician visit to

replace lost, stolen, or damaged prescriptions

NA
Paramedical practitioners Up to $700 for any one incident, per practitioner NA Up to $700 for any one incident, per practitioner $600 per incident per practitioner
Emergency dental Up to $700 for non-blow dental emergencies; up to the Policy limit for an accidental blow to the face NA Up to $700 for non-blow dental emergencies; up to the Policy limit for an accidental blow to the face Up to $6,000 for accidental blow to the face and up to $600 for other emergency dental treatment
Emergency evacuation/repatriation Up to $6,000 burial/cremation at the place of death Up to $5,000 burial or up to $5,000 cremation at the place

of death, only for trip interruptions

Up to $6,000 burial/cremation at the place of death Up to $6,000 burial/cremation at the location 
Baggage loss/delay Optional, up to $1,500 per traveller to a max of $3,000 for family & friends NA $500 NA
Accidental death & dismemberment Optional NA
  • Maximum limit for Air Flight/Common Carrier

Accident: $100,000

  • Maximum limit for 24-hour Accident: $25,000
Included ($10,000); optional upgrade available
Trip cancellation (before departure) NA Up to the sum insured, along with $350 additional accommodation to resume the itinerary and up to $1,000 transportation not part of the tour Up to the

sum insured

NA
Trip interruption (after departure) NA Up to the sum insured and out-of-pocket $350/day to a max of $1,500 Up to the

sum insured

NA
Trip interruption and cancellation (overall maximum) NA Up to $100,000 Up to the

sum insured

NA

Does TuGo cover adventure sports and activities?

Yes, TuGo offers an optional Sports & Activities Rider that extends coverage for many recreational and adventure activities that are not included under the standard policy. With TuGo’s emergency medical insurance, you can get coverage for activities like hiking, ziplining, bungee jumping, parasailing, mountaineering, and a few other activities. When you add this optional coverage, the premiums may increase, but it can also prevent you from financial worries if an adventure activity gets you injured. 

Does TuGo cover skiing, scuba diving or skydiving?

Yes, TuGo can cover skiing, scuba diving and skydiving, but some higher-risk versions of these activities require its optional Sports & Activities Coverage. This includes backcountry skiing and snowboarding, organized downhill freestyle competitions, skydiving and tandem skydiving, as well as scuba diving or free diving beyond 40 metres. The exact coverage depends on the policy’s terms and conditions.

TuGo travel insurance for pre-existing conditions

TuGo covers eligible stable pre-existing medical conditions, provided you meet the applicable stability period before your policy’s effective date. Here’s how the stability period varies depending on the age and trip length:

Traveller’s age Trip length Stability period
59 years and under 35 days or less 7 days
59 years and under More than 35 days 90 days
60-75 years Any trip length 180 days
75 years and older Any trip length 365 days

The condition must also meet TuGo’s definition of stable, and other policy conditions and exclusions may apply.

What does TuGo travel insurance not cover?

Some of the common exclusions under TuGo travel insurance include:

  • Injuries or losses resulting from war, terrorism, or nuclear, chemical, or biological events
  • Medical conditions that worsen because you did not follow prescribed treatment or medication
  • Claims related to the use of illegal or controlled drugs
  • Medical treatment is sought when the primary purpose of the trip is to receive medical care
  • Routine pregnancy care, childbirth, or pregnancy-related complications occurring close to the expected delivery date, unless specifically covered
  • Elective, cosmetic, experimental, or non-emergency medical treatments and any related complications
  • Self-inflicted injuries, suicide attempts, or injuries resulting from criminal or illegal acts
  • Medical conditions or symptoms that were reasonably expected to require treatment during the trip

Pros and cons of TuGo travel insurance

TuGo travel insurance offers flexible coverage options, high emergency medical limits, and optional add-ons, but some benefits must be purchased separately, and baggage coverage is not automatically included.

Pros Cons
Up to $5 million in emergency medical coverage for eligible travellers and $2 million for Student Plan Baggage coverage is optional and not included with Trip Interruption & Cancellation
Flexible plan options, including Emergency Medical, Trip Cancellation & Trip Interruption, and Student plans Trip cancellation and interruption benefits must be purchased separately from emergency medical coverage
Offers optional add-ons such as Sports & Activities, Rental Car Protection, and Reduced Stability Rider
Single-trip and Multi-trip annual options are available for most plans
No age limit to be eligible for the plan

How much does TuGo travel insurance cost?

The cost of the TuGo travel insurance plan ranges between $142.56 and $295 for the trip interruption and cancellation plan. On the other hand, it is between $157 and $662 for a single-trip plan and $149 and $501 for a multi-trip plan $662.02. The actual cost may, however, vary based on the traveller’s age, health condition, plan type, trip duration, trip cost, and a few other factors.

TuGo travel insurance cost (2026):

Age Single-trip Multi-trip (15 days per trip) Trip Interruption and Cancellation plan (Trip cost 2000)
25 $157.22 $149.50 $142.56
35 $157.22 $149.50 $142.56
45 $205.70 $155.25 $142.56
55 $205.70 $155.25 $142.56
65 $274.15 $241.50 $167.40
75 $662.02 $501.40 $295.92

Disclaimer: Illustrative premiums for single-trip and multi-trip annual Emergency Medical plans ($5 million coverage) and a Trip Cancellation & Trip Interruption plan (based on a $2,000 trip cost). Actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

How to make a claim with TuGo travel insurance?

To make a claim with TuGo travel insurance, notify TuGo as soon as possible, complete the required claim form, and submit all supporting documents. Here’s a look at the claim process for TuGo travel insurance:

  • Notify TuGo as soon as possible by contacting the claims department or opening eligible medical, dental, trip cancellation, or trip interruption claims online
  • Complete the claim form and submit all requested supporting documents, including original itemized receipts and any additional documentation required for your claim
  • Provide claim-specific documents, such as medical certificates, travel itineraries, cancellation confirmations, or other records, depending on the type of claim (e.g., emergency medical or trip cancellation)
  • Submit your claim within the specified period; otherwise, the claim may be denied
  • Keep all original receipts and records, as reimbursement is based on original itemized invoices and proof of expenses
  • Track the claim status and upload additional documents if required

Please note that additional documentation may be required depending on the type of claim. Emergency medical claims, trip cancellation, and trip interruption claims each have specific documentation requirements outlined in the TuGo policy.

Can you cancel or get a refund on TuGo travel insurance?

Yes, TuGo allows you to cancel your travel insurance policy, but your refund depends on when you cancel, whether your trip has started, and whether you have submitted a claim.

  • Within 10 days of purchase (free-look period): You can receive a full refund if you cancel within 10 days of the application date, provided no travel has taken place, and the policy has not expired
  • Before your trip begins: If you cancel before the policy’s effective date, you are eligible for a full refund for all plans
  • After your trip starts or if you return early: For single-trip plans, you may qualify for a partial refund (less an administration fee). The refund is based on the date you request cancellation or from your return date, provided you submit acceptable proof of return, and your refund request is received within 90 days after the policy expires
  • Multi-trip annual plans: If no travel has taken place, you can receive a full refund within 10 days of the application date. After that, you may be eligible for a partial refund (less an administration fee) if you request cancellation within 90 days of the policy’s effective date
  • No refund after a claim: Refunds are not available if a claim has been made or will be submitted under the policy. All refund requests made after the policy becomes effective must be submitted in writing 

Does TuGo travel insurance allow automatic extensions?

Yes, TuGo travel insurance automatically extends your coverage in specific situations, such as those listed below:

  • Your return is delayed because of a common carrier, such as an airline, train, or bus delay
  • You or your travelling companion is hospitalized or medically unfit to travel, and you are unable to return home as originally planned
  • You make one unexpected temporary visit to your home province during a single-trip policy. Your coverage remains in effect for the rest of your trip, although no coverage is provided while you are in your home province

What are the deductible options available with TuGo travel insurance?

TuGo offers deductible options of $0, $300, $500, $1,000, $2,000, $5,000, $10,000, $25,000, $50,000, and $100,000 for Emergency Medical coverage only. When you choose a higher deductible with TuGo, it can lower the premium, while a lower deductible means paying less out of pocket if you make an eligible claim. The deductible you select applies to eligible Emergency Medical expenses before TuGo pays the covered portion of a claim.

How does TuGo compare to other travel insurance providers?

TuGo stands out for its customizable travel insurance plans, allowing travellers to enhance their coverage with optional add-ons such as Sports & Activities, Rental Car Protection, Baggage Insurance, and the Reduced Stability Rider for eligible pre-existing medical conditions. 

Unlike many insurers that offer fixed deductibles, TuGo lets you choose from multiple deductible options, helping you balance your premium and out-of-pocket costs. To see how TuGo compares with other leading insurers, explore our guide to the best travel insurance companies in Canada.

TuGo travel insurance

Is TuGo travel insurance worth it in 2026?

Yes, TuGo travel insurance is a good choice for all kinds of travellers, whether they are going for a short trip or a long family vacation. Its range of coverage options and optional benefits can make it suitable for some travellers.

TuGo may be a good fit if: 

  • You plan to participate in certain adventure sports or activities and want the option to add Sports & Activities Coverage
  • You have a stable pre-existing medical condition and meet TuGo’s applicable stability-period requirements
  • You want flexible travel insurance options with different coverage limits, deductibles, and policy types to match your trip

TuGo may not be the best fit if:

  • You want baggage coverage automatically included with your Trip Cancellation & Trip Interruption policy
  • You need coverage for a pre-existing condition that does not meet TuGo’s stability requirements

Our advisor’s take on TuGo travel insurance

Our expert and licensed advisors at PolicyAdvisor help travellers compare travel insurance plans based on their destination, trip duration, medical history, and budget. One of our advisors recently assisted a 38-year-old Canadian planning a week-long adventure trip to the US who wanted emergency medical coverage along with protection for adventure activities. The client was travelling to the US to explore Yellowstone National Park and do skiing and snowmobile expeditions around the area.

Client profile:

  • Age: 38 years old, Canadian resident
  • Trip duration and type: A week-long adventure vacation to the US
  • Primary concern: Emergency medical coverage with protection for adventure activities
  • Our comparison: After comparing travel insurance plans from multiple providers, we recommended TuGo Emergency Medical Insurance with the Sports & Activities Rider. TuGo is one of the very few insurers in Canada that provides optional coverage for many adventure sports at affordable premiums

Why we recommended TuGo:

  • Customization through riders: Along with coverage for the Sports & Activities Rider, TuGo also offers other optional riders such as Reduced Stability, Rental Car Protection, and Baggage Insurance, allowing travellers to tailor coverage based on their itinerary and risk profile
  • Coverage for pre-existing conditions: TuGo, in addition to providing coverage for stable pre-existing medical conditions, also offers a Reduced Stability Rider. This makes it a strong option for travellers whose pre-existing medical conditions may not meet the standard stability requirements
  • Flexible deductible options: With the Emergency Medical Plan, TuGo lets you choose from $0 to $100,000 deductibles. Selecting a higher deductible can help lower your premium, giving you more control over the cost of your coverage

If you are unsure whether TuGo, Allianz, or another travel insurance provider is right for your trip, speak with a licensed PolicyAdvisor expert. We will compare plans from Canada’s leading insurers to help you find the right balance of coverage, flexibility, and price. Schedule a call now!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Can I customize my TuGo travel insurance policy?

Yes, TuGo allows you to customize your policy with optional add-ons, including Baggage Insurance, Rental Car Protection, Sports & Activities coverage, and a Reduced Stability Rider. You can also choose from multiple deductible options to customize your TuGo travel medical insurance.

What is the maximum emergency medical coverage offered by TuGo?

TuGo’s Emergency Medical Insurance provides up to $5 million in emergency medical coverage for eligible travellers. The Canadian Student Plan offers up to $2 million in emergency medical coverage.

Does TuGo travel insurance automatically extend my coverage?

Yes, TuGo travel insurance may be extended automatically. The insurer lets you extend your policy if you are medically unfit to travel, you or your travelling companion is hospitalized, or your return is delayed by a common carrier, subject to the policy terms and conditions.

Can I buy TuGo travel insurance after I have left Canada?

Yes, in many cases you can buy TuGo travel insurance after leaving Canada. But a 48-hour waiting period applies when you buy after departure. That means your coverage won’t begin right away, so buy before you leave to be protected from day one.

How long does a TuGo travel insurance claim take?

It typically takes 2 weeks for TuGo to process travel insurance claims, once all the documents are processed. You should inform TuGo as early as possible about the claim to avoid any delays in the processing of your claim. 

Is TuGo travel insurance good for seniors?

Yes, TuGo travel insurance is a good choice for seniors. Offering coverage of up to $5 million and optional coverage of up to $5 million in emergency medical coverage, along with options such as coverage for eligible pre-existing medical conditions and customizable deductibles, it offers flexibility. However, please note that seniors aged 60 and older are subject to a 180-day stability period.

Does TuGo cover baggage automatically?

No, baggage coverage is not automatically included with TuGo’s Emergency Medical Insurance or Trip Cancellation & Trip Interruption plans. You can purchase Baggage Insurance as an optional add-on, while it is included with TuGo’s All Inclusive Holiday Package and Non-Medical Package.

Can I choose a deductible with TuGo?

Yes, TuGo lets you choose from several deductible options for Emergency Medical Insurance. The available deductible options range from $0 to $100,000, including $300, $500, $1,000, $2,000, $5,000, $10,000, $25,000, and $50,000.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Travel Insurance Companies in Canada (2026) – Rated by Our Experts

At PolicyAdvisor, we have analyzed the best Canadian travel insurance policies to tell you exactly which providers actually deliver when you need them most.

The best travel insurance for Canadians depends on your destination, age, health history, and trip length. Manulife is a strong all-round option, Allianz may suit frequent travellers, TuGo can be relevant for adventure activities or certain pre-existing-condition needs, and GMS may appeal to families seeking bundled coverage.

We personally reviewed the policy terms, key features, and coverage limits of each provider side-by-side to identify exactly what makes each one stand out.

What is the best travel insurance for Canadians?

Manulife is our best overall choice for broad coverage value. Allianz is a strong option for frequent business travellers, TuGo may suit adventure travellers and some older applicants, Destination Canada focuses on senior and pre-existing-condition needs, 21st Century targets affordability, Travelance suits healthier travellers seeking high limits, MSH International is relevant for certain international and smoker profiles, and GMS offers balanced medical and non-medical coverage. Availability, eligibility and benefits vary by plan.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Detailed reviews of the best travel insurance companies in Canada

According to our licensed insurance experts, the providers below are among the best travel insurance companies in Canada for 2026. We reviewed each provider’s policy features, coverage limits, exclusions, digital support tools, and more to help Canadians find the right travel insurance plan for their needs.

1. Manulife

Best for Comprehensive Coverage Value
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Up to $10 million in emergency medical coverage
Offers specific "All-Inclusive" plans
24/7 worldwide emergency travel assistance
A.M. Best Rating
A+
Avg. travel insurance cost
$113.67

Manulife is one of Canada’s largest and most established insurance providers, offering a wide range of travel insurance plans with exceptional medical coverage limits. Whether you’re going on a single trip or travelling frequently, Manulife travel insurance ensures you’re protected with generous benefits and a trusted claims process. Their travel medical insurance plans are particularly ideal for travellers seeking both medical and non-medical coverage, including trip cancellation, interruption, baggage loss, and more.

Key features of Manulife:

  • Provides maximum coverage limits up to $10 million
  • Offers specific “All-Inclusive” plans that bundle emergency medical with trip cancellation/interruption and baggage loss, damage, and delay
  • Offers “Travel Companion Savings” for couples travelling together on the same policy, as well as a broader “Family Coverage” discount for parents/grandparents travelling with children
  • Multi-trip and single-trip plans are available, depending on traveler needs
  • 24/7 worldwide emergency travel assistance as well as through their dedicated “TravelAid” mobile app for direct hospital coordination and claims

The Advisor’s take:

While many other providers expect you to pay out-of-pocket and wait months for reimbursement, Manulife allows for direct billing, meaning you aren’t left footed with a massive medical bill while waiting for a claim to process. They excel in direct hospital coordination through the use of tools like the TravelAid app and StandbyMD. In our opinion, for medical emergencies, having an established player like Manulife to handle the billing directly is the ultimate ‘friction-remover’.

Why PolicyAdvisor recommends Manulife:

  • Extremely high coverage limit for medical emergencies; ideal for international travel
  • Well-rounded protection, combining both medical and non-medical benefits
  • If a traveler’s entire trip is within Canada, Manulife offers a massive 50% savings on the premium for select plans
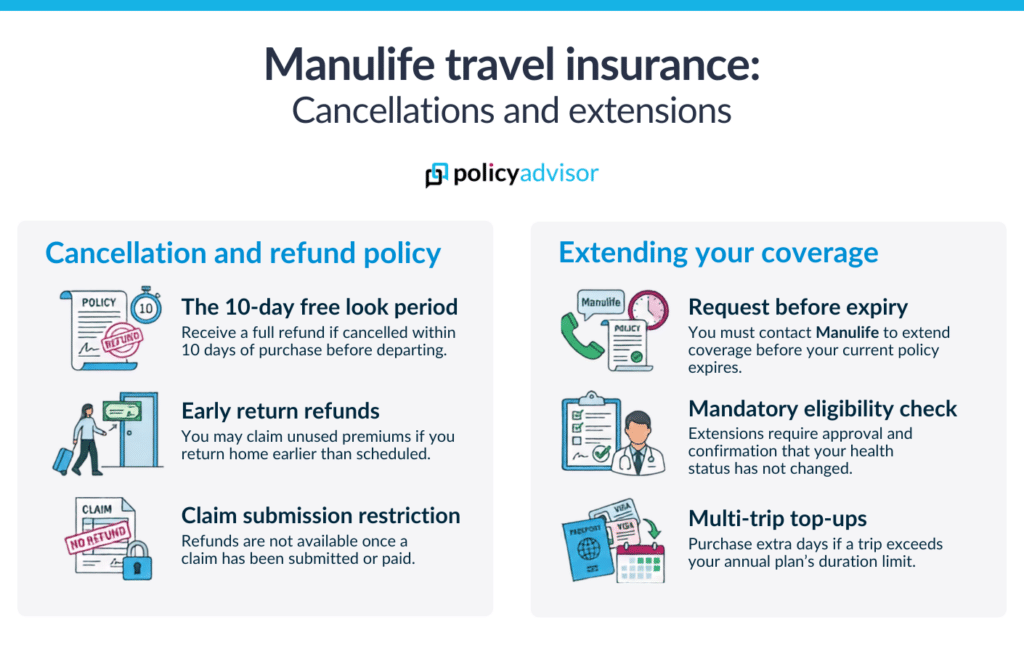
  • They offer a 10-day review window after purchase. If a traveler changes their mind within 10 days (and hasn’t departed or filed a claim), they can get a full refund
  • Offers specialized “TravelEase” Plan for travelers who often were denied coverage
  • TravelAid App allows for online claim submission and provides directions to the nearest medical facilities
  • StandbyMD offers 24/7 teleconsultation and connects travelers to a global network of doctors 

2. Allianz

Best for frequent business travellers
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
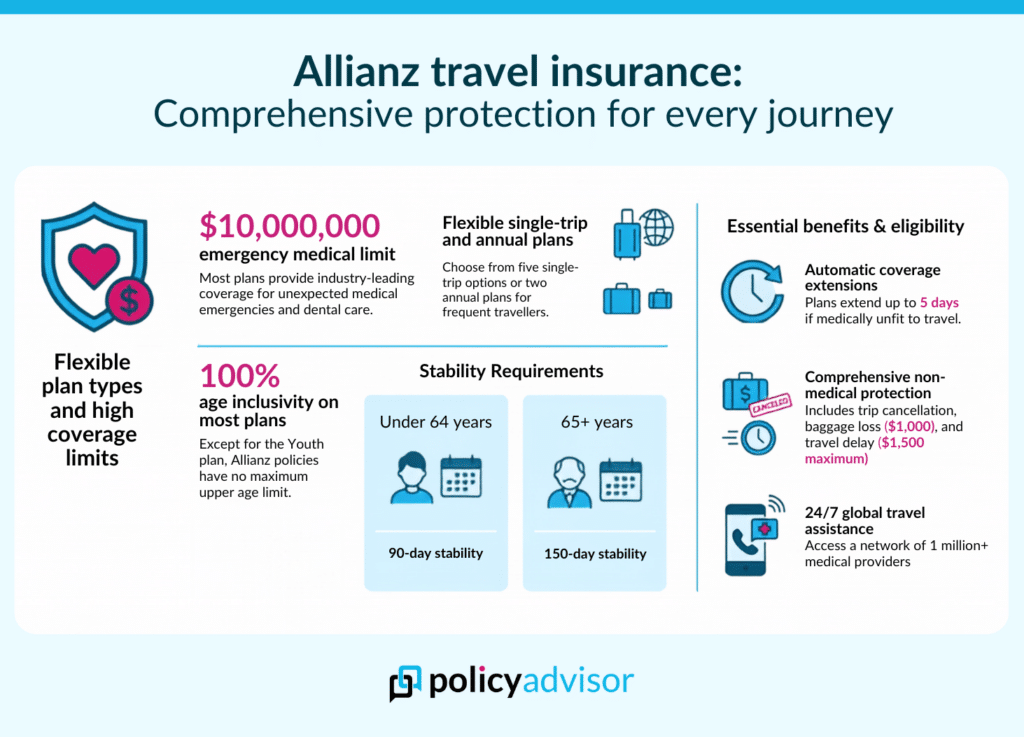
$10 million massive coverage limits
Trip cancellation and interruption coverage
Provides specialized concierge services
A.M. Best Rating
A+
Avg. travel insurance cost
$86.26

Allianz is a global leader in travel insurance, well-known for providing tailored coverage to frequent business travellers. With premium multi-trip plans and one of the best business trip travel insurance cancellation/interruption packages, it’s ideal for professionals who can’t afford delays or disruptions in their travel schedule.

Key features of Allianz:

  • Offers $10 million massive coverage limits for international travel
  • Provides flexible annual multi-trip plans (options for 8, 15, and 35 days trip durations within a single year)
  • Comprehensive trip cancellation and interruption coverage
  • Trip delay & baggage benefits include daily reimbursement for meals and essentials if your travel is unexpectedly stalled
  • Offers specialized add-ons for rental vehicle damage and baggage protection
  • Explicitly provides specialized concierge services, including help with restaurant reservations, activity bookings, and document replacement

The Advisor’s take:

The biggest headache for business travelers isn’t just a medical emergency, it’s the logistical friction of being stranded. Allianz solves this better than almost anyone through their Allyz app. It acts as a digital concierge, giving you real-time flight updates and safety alerts. We particularly recommend their “Doctor Chat” feature; it lets you bypass foreign ER waiting rooms by booking a local doctor virtually, often with no out-of-pocket costs for the initial consultation.

Why PolicyAdvisor recommends Allianz:

  • Their “Annual Multi-Trip” plans are explicitly designed for those traveling two or more times per year, providing “always-on” coverage
  • Some plans trigger reimbursement for meals and essentials after just 3 hours of delay (most competitors require 6–12 hours)
  • The Allyz app allows you to file claims and locate vetted hospitals right from your phone
  • You can book virtual or in-person medical appointments through their app in over 80 countries
  • Their worldwide presence allows for better direct billing coordination and faster claims support through their dedicated online portal

3. TuGo

Best for adventure sports enthusiasts
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Covers most sports and adventures
Most inclusive for seniors
Provides instant airport lounge access
A.M. Best Rating
A+
Avg. travel insurance cost
$98.61

TuGo is renowned for its flexible underwriting and inclusive coverage, especially for adventure travellers and seniors. It’s one of the few providers that covers unstable pre-existing conditions, and it includes coverage for activities like skiing, scuba diving, and ziplining.

Key features of TuGo:

  • Covers most adventures like ziplining, bungee jumping, and parasailing without needing a special rider
  • Offers comprehensive emergency medical coverage for travelers up to age 90
  • Offers a rare optional rider that covers unstable pre-existing conditions (for ages 79 and under) if they have been stable for just 7 days before departure
  • Provides instant airport lounge access or a cash payout if your flight is delayed by 2 hours or more

The Advisor’s take:

When a client tells us they have a medical condition that changed just two weeks ago, most insurers will flat-out deny them coverage for that condition. TuGo’s “Unstable Pre-existing Condition” rider is a massive relief in those scenarios, providing a safety net for conditions that were stable for only a week. We also recommend them for families; their “Family & Friends” plan is highly cost-effective, allowing two adults and up to six children to be covered under one policy at a significant discount.

Why PolicyAdvisor recommends TuGo:

  • Most Inclusive for Seniors. Excellent rates and simplified medical questionnaires for travelers between age 60 and 90
  • Their optional “Sports & Activities Coverage” extends protection to extreme pursuits like backcountry skiing, BASE jumping, and scuba diving over 40 metres
  • The TuGo digital wallet and online claims portal make it incredibly easy to manage your policy and file claims directly from your phone while abroad
  • Coordinates directly with hospitals to handle billing, minimizing the risk of you having to pay large medical tabs upfront.
  • Provides confidential, professional support for travelers experiencing emotional trauma or grief while abroad
  • Eligible policies include a complimentary 3GB mobile data eSIM for 30 days, keeping you connected in over 100 countries

4. Destination Canada

Best for seniors with pre-existing conditions
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Offers plans for travelers aged 60 to 79
Option to purchase after departure
Offers multiple deductible options
A.M. Best Rating
NA
Avg. travel insurance cost
$100.80

Destination Canada specializes in travel insurance plans that are tailored to the unique needs of senior travellers, especially those with pre-existing medical conditions. While they are one of the most established names in the Canadian market, they are particularly renowned for their flexible underwriting and specialized “Destination Snowbird” plans designed to handle the complexities of senior medical histories.

Key features of Destination Canada:

  • Offers tailored medical plans for travelers aged 60 to 79 (and up to 84 for select visitor plans)
  • Best for Seniors with pre-existing diseases and specific chronic conditions that generic “no-questionnaire” plans might exclude
  • Best suited for short-duration travel to the U.S. or visiting family in another province 
  • Option to purchase after departure (a rare feature that allows you to buy a policy after you have already left your home province)
  • Offers multiple deductible options (ranging from $0 to $10,000) to help you lower your premium costs
  • Includes significant inpatient ($25,000) and outpatient ($1,000) mental health coverage, as well as trauma counseling

The Advisor’s take:

We think Destination Canada is the ‘short-trip specialist.’ While giants like Manulife are great for long, multi-month winter escapes, Destination Canada often offers more competitive pricing for short trips (under 30 days) for travelers up to age 74. We also frequently recommend them for their Reduced Stability Period Option; if a client’s health has only just stabilized, paying the extra surcharge is a small price for the peace of mind of having that specific condition covered.

Why PolicyAdvisor recommends Destination Canada:

  • Especially suitable for snowbirds, grandparents, and older travellers
  • Their detailed medical questionnaires allow them to offer coverage for specific chronic conditions that generic “no-questionnaire” plans might exclude
  • They use World Travel Protection Canada for assistance, which is highly experienced in handling senior medical coordination
  • Provides up to $2,500 to return your car or RV home if a medical emergency prevents you from driving back
  • Offers up to $50 per day (max $250) for incidental out-of-pocket expenses like telephone or television rentals while you are hospitalized for at least 48 hours
  • Your coverage is automatically extended for up to 72 hours at no extra cost if your return is delayed by weather, mechanical failure of your vehicle, etc

5. 21st Century

Best for affordability
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Monthly installments available
Provides side trip protection
Extra $50,000 for accidents at no cost
A.M. Best Rating
NA
Avg. travel insurance cost
$39.00

For travellers looking for the most affordable travel insurance without sacrificing essential protection, 21st Century travel insurance offers simple, flexible plans. With options like $50,000 coverage for a $0 deductible or $200,000 with a $500 deductible, it caters to budget-conscious travellers, international students, and working holiday visitors.

Key features of 21st Century:

  • Emergency medical limits range from as low as $15,000 to $200,000, allowing for highly customized budget tiers
  • A standout feature for Super Visa holders, allowing them to manage the high cost of a 365-day policy through monthly installments with only a $50 admin fee
  • Automatically includes an extra $50,000 for accidents at no additional cost if you select the $100,000 coverage option
  • Provides side trip protection (coverage for trips outside of Canada for up to 30 days, as long as 51% of your total policy period is spent within Canada)

The Advisor’s take:

When clients ask for the most “budget-conscious” entry point, we suggest the 21st Century because of their “Disappearing Deductible.” This is a smart tool where you can choose a $2,500 deductible to lower your premium; however, if you have a sickness claim that exceeds $2,500 (or any injury claim), the deductible is waived entirely. It allows you to reap the benefits of a low premium without the fear of a massive out-of-pocket bill for a major emergency.

Why PolicyAdvisor recommends 21st Century:

  • Widely recognized as one of the most cost-effective options in the Canadian market, especially for visitors and visa applicants
  • They offer specific discounts when two or more people are insured on the same policy, which is ideal for couples or families traveling together
  • Their Basic plan has no age limit (covering up to age 111), making it a rare affordable option for seniors over 90
  • While administered independently, policies are underwritten by Manulife, giving travelers the reliability of a major insurer at a lower price point
  • The monthly payment plan is a significant relief for families sponsoring parents or grandparents on long-term visas
  • Offers straightforward, no-frills medical coverage that meets the requirements for international students and working holiday (IEC) visitors
  • If you decide to stay in Canada longer, extending your policy is a simple process compared to some larger corporate providers

6. Travelance

Best for healthy visitors
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Flexible 15 or 30-day annual plans
Offers all-inclusive packages
$4,000 limit for dental emergencies
A.M. Best Rating
NA
Avg. travel insurance cost
$126.90

Travelance offers a highly competitive pricing for individuals without pre-existing medical conditions, providing $10 million emergency medical protection without the added cost of high-risk surcharges. From specialized domestic plans to flexible annual multi-trip options, Travelance delivers a customizable and affordable safety net for most traveler needs.

Key features of Travelance:

  • Provides significantly lower premiums for individuals without pre-existing conditions by removing high-risk pool surcharges
  • Offers $10 million in emergency medical and $10 million in evacuation/return home coverage on all-inclusive plans
  • Features a specialized “All Inclusive Canada” plan with $10 million in medical for travel strictly within the country
  • Flexible 15 or 30-day annual plans with the option for unlimited emergency medical coverage on select tiers
  • All-inclusive packages bundle high-limit medical with $1,500 for baggage, $1,500 for trip delays, and $100,000 for travel accidents

The Advisor’s take:

Travelance is the logical choice for healthy travelers who want the highest level of medical protection, such as the $10 million or unlimited medical caps, without the premium bloat associated with broader plans. Their ability to offer standalone benefits as top-ups is a significant advantage for those who may already have partial coverage. For frequent travelers, the choice between 15 and 30-day annual blocks provides a level of logistical control that is essential for a stress-free travel schedule.

Why PolicyAdvisor recommends Travelance:

  • Explicitly designed to work alongside valid Canadian government or university health insurance, ensuring a seamless fit for residents and students
  • Includes a generous $4,000 limit for accidental dental emergencies, one of the highest in the industry
  • Features a $1,500 trip delay benefit on all-inclusive packages ($1,000 on standalone plans) to manage the costs of unexpected meals and hotels
  • Standalone medical or cancellation plans are available to serve as primary coverage or to “top up” another existing plan

7. MSH International

Best for smokers
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Eliminates the "smoker surcharge"
Offers "Special Risk" plans
Features a duration limit of 100 days per trip
A.M. Best Rating
NA
Avg. travel insurance cost
$75.59

MSH International is a reputed insurance provider that specializes in high-limit medical protection for international travelers. In Canada, they have targeted a unique niche by offering one of the few medical questionnaires that does not penalize travelers for tobacco or nicotine use. This can be a huge advantage for smokers who might otherwise face higher premiums or stricter exclusions.

Key features of MSH International:

  • Does not ask about tobacco or nicotine use on their travel medical applications, eliminating the “smoker surcharge” common with other insurers
  • Offers comprehensive emergency medical coverage with limits up to $7 million
  • Their visitor and Super Visa plans are available to travelers of any age, providing flexibility for older relatives
  • One of the few providers that can cover complex itineraries, high-risk activities, and hostile zones through specialized plans
  • Allows you to customize your policy with non-medical protections like trip cancellation and baggage loss

The Advisor’s take:

For most Canadian insurers, checking the “Yes” box for smoking can instantly hike your premium by 25% to 50%. MSH is the “go-to” for these clients because they focus on your actual medical conditions without the lifestyle surcharge. We also recommend them for long-term expats; their ability to coordinate care across 193 countries with 24/7 multilingual support is vastly superior to smaller, domestic-only providers.

Why PolicyAdvisor recommends MSH International:

  • By removing tobacco-related rate penalties, they offer some of the lowest premiums on the market for this demographic
  • Their medical questionnaires are significantly shorter and less invasive than those of major competitors like Manulife
  • Their rare “Special Risk” plans provide medical, evacuation, and disability coverage even in extreme situations, hostilities, or high-risk locations that are typically excluded by standard Canadian policies
  • Another standout feature of their “Start’Expat” plan is the inclusion of third-party liability coverage (up to €4,500,000), which protects you if you accidentally cause injury or property damage to others while abroad
  • They have a massive international footprint with 6 global claims departments and assistance available in over 50 languages
  • You can manage your entire policy and file claims by simply uploading a photo of your medical receipts through the MSH mobile app
  • Features a duration limit of 100 days per trip, offering unmatched flexibility for frequent, long-term travelers

8. GMS (Group Medical Services)

Best for balanced medical and non-medical coverage
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Key benefits
Medical insurance of up to $5 million
Choice of 15 or 30-day trip lengths
Add-ons for trip cancellation and baggage loss
A.M. Best Rating
NA
Avg. travel insurance cost
$78.30

GMS (Group Medical Services) has been a staple in the Canadian market for over 70 years. They provide well-balanced travel insurance, offering high-limit medical protection alongside robust non-medical benefits like trip cancellation and baggage loss at a highly competitive price point when bundled. Their plans are a good middle ground for those who want well-rounded protection without going overboard on premiums.

Key features of GMS:

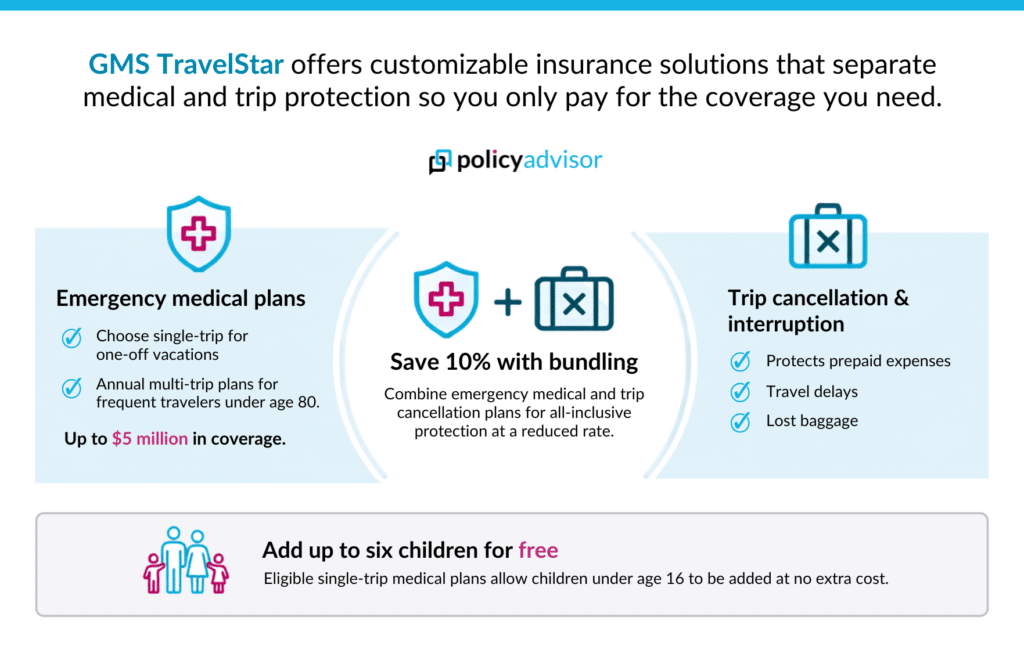
  • Comprehensive emergency medical insurance of up to $5 Million
  • Offers annual plans with a choice of 15 or 30-day trip lengths for unlimited travel throughout the year
  • Save 10% on your Trip Cancellation and Interruption insurance when you purchase it alongside an Emergency Medical plan
  • Medical plans include coverage for one follow-up visit related to your covered emergency treatment
  • Utilizes Robin Assist for a faster, fully digital claims process that can be managed through an online portal

The Advisor’s take:

While some providers focus only on medical caps, GMS strikes a perfect balance by offering a $5 million medical safety net alongside a 10% bundle discount specifically designed to make non-medical perks (like trip cancellation and baggage loss) highly affordable. Plus, while other companies offer family rates, GMS has a standout feature: you can add up to six dependent children (under age 16) for free to a Single Trip Emergency Medical policy, which is great in our opinion.

Why PolicyAdvisor recommends GMS:

  • The “kids for free” benefit makes this often the most affordable policy for families with multiple children
  • Their TravelStar plans are designed to be “easy to choose and easy to use,” avoiding the complex tiered structures of larger insurers
  • Offers protection for pre-existing medical conditions that have been stable for 180 days prior to departure.
  • Offers an additional 5% discount for family members (over age 16) traveling together on the same policy
  • GMS maintains high reliability and has modernized its integration with Robin Assist for a faster, fully digital claims process
  • Their GMS Care Network app gives you 24/7 access to virtual care, allowing you to consult with a medical professional for minor issues without leaving your hotel
Planning a vacation soon?

Get the best travel insurance quotes in Canada before your trip begins.

Travel Insurance in Canada: Top recommendations for seniors, families, students, and frequent travelers

To help you find the provider that actually matches your unique situation, we have moved beyond general ratings to highlight the specific category where each company truly leads the market. Use the breakdown below to find the specific protection that fits your next trip.

1. Best travel insurance for Canadian seniors

  • Destination Canada: Specialized for senior medical histories, it offers flexible underwriting for chronic conditions and a rare option to reduce the stability period for pre-existing diseases.
  • TuGo: A top choice for the oldest travelers, it provides comprehensive emergency medical coverage for applicants up to age 90 and includes a rare rider for unstable conditions.
  • 21st Century: Ideal for budget-conscious seniors, its Basic plan has no maximum age limit (covering up to age 111) and features a “disappearing deductible” to lower upfront premium costs.

2. Best travel insurance companies for students

  • 21st Century: This is the top choice for international students and working holiday (IEC) visitors because it offers straightforward, no-frills medical coverage specifically designed to meet mandatory entry requirements at an affordable price.
  • MSH International: Highly recommended for students on international internships or long-term exchanges through their “Start’Expat” plan, which uniquely includes up to €4,500,000 in third-party liability coverage to protect against accidental damage or injury while abroad.
  • Travelance: A great option for students looking for affordable premiums with high medical coverage limits. Its flexible plans, strong emergency medical protection, and simple digital claims process make it especially suitable for students.

3. Best travel insurance companies for families or groups

  • Allianz: A good option for families and groups due to its comprehensive trip interruption benefits, fast digital claims support, and flexible multi-trip plans. The Allyz app helps families manage delays, medical emergencies, and travel changes easily while abroad.
  • GMS (Group Medical Services): GMS offers a unique benefit where travelers can add up to six dependent children (under age 16) for free to a single-trip emergency medical policy. This makes it often the most affordable policy on the market for families with multiple children.
  • TuGo: Highly recommended for active families or groups through its “Family & Friends” plan, which covers two adults and up to six children under one policy at a significant discount. It is particularly strong for families looking to engage in adventure sports.

4. Best travel insurance companies for pre-existing conditions

  • Destination Canada: This provider is specifically recognized for its specialized “Destination Snowbird” plans and detailed medical questionnaires that allow for coverage of chronic conditions often excluded by other insurers. 
  • Manulife: Offers a specialized “TravelEase” plan designed specifically for travelers who are frequently denied coverage due to their medical history. This plan focuses on covering emergency medical costs directly related to those pre-existing conditions.
  • GMS (Group Medical Services): Provides a balanced approach with clear protection for pre-existing medical conditions that have remained stable for at least 180 days prior to the trip.

5. Best travel insurance company for Super Visa applicants

  • 21st Century: This is a top-rated choice because of its unique monthly payment plan, which allows families to manage the high upfront cost of a mandatory 365-day policy through installments with only a $50 admin fee. 
  • Manulife: A highly reliable option, as their “Visitors to Canada” plans are explicitly designed to be fully Super Visa compliant, meeting all mandatory government requirements for family members arriving in Canada.
  • MSH International: This provider is ideal for older relatives as their Super Visa plans have no maximum age limit, providing essential flexibility for families bringing over elderly parents or grandparents who might be restricted by other insurers.

6. Best travel insurance company for frequent travellers

  • Allianz: Explicitly designated as the premier choice for frequent business travelers, it offers flexible annual multi-trip plans with duration options ranging from 8 to 90 days and features a digital concierge app for real-time updates and virtual medical consultations.
  • GMS (Group Medical Services): A great option for frequent leisure travelers because of its flexible annual multi-trip coverage, bundled trip cancellation savings, and balanced medical and non-medical protection.
  • Manulife: The company offers annual multi-trip plans with elite medical coverage limits of up to $10 million and specialized protection for non-medical disruptions like baggage loss and trip delays.

How we rated the best travel insurance companies

We assessed travel insurance providers based on emergency medical coverage, trip cancellation and interruption benefits, pre-existing-condition rules, deductibles, pricing, assistance services, digital claims tools and suitability for different traveller profiles. Ratings reflect PolicyAdvisor’s editorial comparison of available plans and are not a guarantee that one provider is best for every traveller. Always review the policy wording, exclusions and stability requirements before purchasing.

What does travel insurance cover in Canada?

While specific benefits vary by provider, most travel insurance policies in Canada are divided into three main categories: Emergency Medical, Trip Protection, and Baggage Coverage. Here is a breakdown of the primary benefits included in most top-rated Canadian policies:

  • Emergency medical expenses: Covers the cost of hospitalization, surgery, doctor consultations, dental and emergency medications during your trip
  • Emergency evacuation and repatriation: Pays for transportation to the nearest medical facility, air ambulance or return to Canada in case of severe illness or injury
  • Trip cancellation: Reimburses prepaid travel expenses if you need to cancel your trip due to unexpected events like illness or family emergencies
  • Trip interruption: Covers additional costs if your trip is cut short because of unforeseen circumstances
  • Trip delays: Provides reimbursement for meals, accommodation, and transportation if your travel plans are delayed beyond a specified time
  • Lost, stolen, or delayed baggage: Compensates for lost, stolen, or delayed luggage and essential personal items during travel
  • Accidental death and dismemberment: Offers financial protection to you or your beneficiaries in case of serious injury or accidental death during the trip
  • Psychological & mental health support: Offers trauma counseling or mental health consultations if a crisis occurs during your trip
  • Adventure sports coverage (Optional): Extends protection for high-risk activities like skiing, scuba diving, or mountain biking, often available as an add-on

What travel insurance does not cover

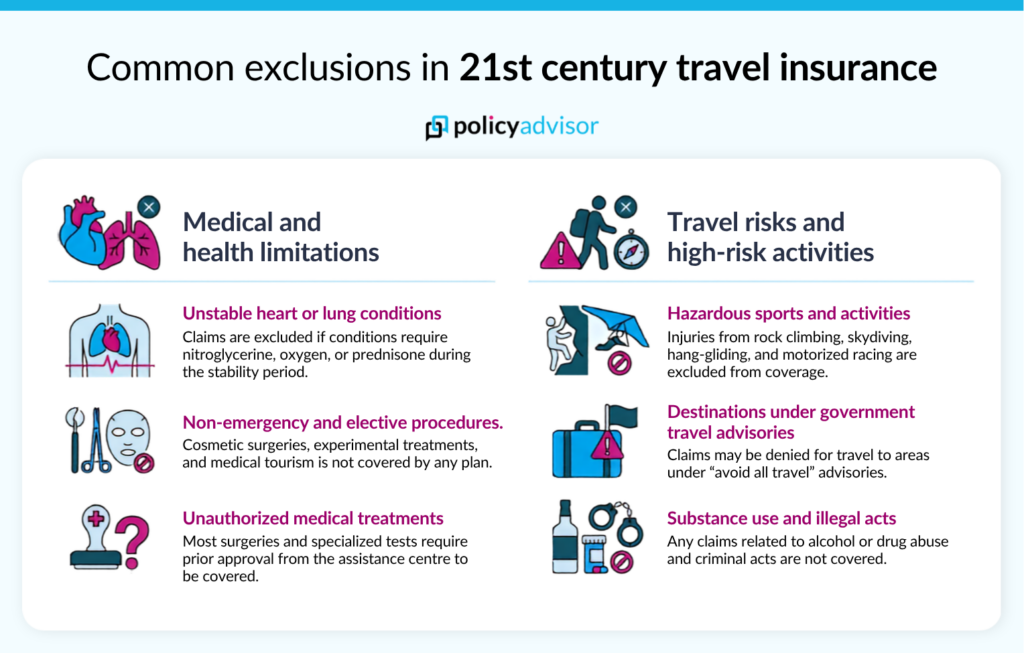
Common exclusions include:

  • Pre-existing conditions that do not meet the policy’s stability definition
  • Medical treatment that was not approved or coordinated as required
  • Routine or elective treatment
  • Travelling against medical advice
  • Intoxication or illegal activity
  • High-risk sports without the required coverage
  • Travel to destinations subject to exclusions or government advisories
  • Claims involving incomplete or inaccurate medical disclosures
  • Trip cancellation for a reason not listed as covered

What is a stable pre-existing medical condition?

A pre-existing condition is generally considered stable only when there have been no changes in symptoms, treatment, medication or medical advice for the period specified in the policy. The required stability period varies by insurer, age, plan, condition and type of claim. Check the exact policy wording before relying on coverage.

What is the cost of travel insurance in Canada?

For a 30-day trip with $100,000 in emergency medical coverage, travel medical insurance costs generally range from $70 to $280 in Canada. Younger travelers in good health tend to pay closer to $70–$100, while older individuals or those requiring pre-existing condition coverage may pay between $180–$280.

The cost generally depends on several key factors, including the traveler’s age, medical history, duration of travel, and whether coverage for pre-existing conditions is needed.

Cost of travel insurance in Canada:

Age Without pre-existing condition coverage With pre-existing condition coverage
25 $70 $100
35 $80 $135
45 $95 $160
55 $130 $180
65 $170 $280

*Illustrative rates for a traveller seeking $100,000 in coverage for a 30-day trip

Is annual multi-trip insurance cheaper?

Annual multi-trip insurance can be more cost-effective than buying separate policies if you take several trips in a year. However, annual plans usually limit the number of days covered per trip, so they may not suit snowbirds or travellers planning a long stay. Compare the total annual premium, trip-duration limit, medical coverage and extension rules before choosing.

How much does travel insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

What are the most common travel insurance claims in Canada?

The most common question our insurance advisors get is: “Is the cost of travel insurance actually worth it?” When you look at the actual cost of medical care for uninsured visitors or out-of-province travelers, the answer is a definitive yes. Here’s a general idea of the most common claims made while travelling and their approximate costs:

  • Heart Conditions (Heart Attack/Irregular Heartbeat): Approximately $46,000 for stabilization and acute care.
  • Stroke & Neurological Emergencies: Approximately $51,000 including initial diagnostic imaging and hospital stay.
  • Gallbladder Issues (Infections/Gallstones): Approximately $51,000 for emergency surgical intervention.
  • Neurological Emergencies (Seizures/Severe Migraines): Approximately $37,000 for ER stabilization and testing.
  • Diabetes-Related Emergencies: Can cost up to $80,000 depending on the length of the ICU stay.

Does provincial health insurance cover you outside Canada?

Provincial health insurance provides very limited or no coverage outside Canada. Reimbursement rules and limits vary by province or territory, and provincial plans may not pay foreign hospitals directly. Travel insurance can help cover eligible emergency medical expenses, subject to the policy’s limits, exclusions and conditions.

Find out if foreign workers need travel insurance in Canada

How to choose the best travel insurance plan in Canada?

Choosing the best travel health insurance in Canada can be overwhelming, but understanding your travel needs and the coverage options available is key. Here are some tips to help guide your decision:

  • Assess your travel needs: Consider factors like the destination, trip duration, and the activities you’ll engage in. If you’re visiting a country with high medical costs, opt for high-limit plans from providers like Manulife or Allianz.
  • Consider your health history: If you have pre-existing conditions, look for insurance policies that cover them, such as those offered by TuGo or Destination Canada, which offer riders to cover unstable conditions or reduced stability periods.
  • Compare coverage options: Check the coverage limits for emergency medical, trip cancellation, and baggage loss. Some plans might offer additional perks like trip interruption coverage or adventure sports protection.
  • Decide between single-trip or annual multi-trip: Single trip is best if you travel once a year. If you plan on traveling two or more times (even for short cross-border trips), an annual plan is almost always more cost-effective. Providers like GMS offer flexible annual durations that provide “always-on” protection.
  • Look for digital tools: Look for plans that offer 24/7 virtual doctor access (standard with Allianz and GMS), digital claims, and perks for flight delays (Available through TuGo).
  • Consult with a travel insurance advisor: It can be beneficial to consult with an insurance advisor, like those at PolicyAdvisor, who can help you compare plans and find the best coverage suited to your specific needs.
Looking for affordable travel insurance?

Call us at 1-888-601-9980 or book some time with our experts to get the best travel insurance rates!

Frequently Asked Questions

Can I get travel insurance for a last-minute trip?

Yes, you can purchase travel health insurance right up until the moment of your departure, and in some rare cases, even after you have left. However, for the best protection, you should purchase coverage as soon as you book your trip. If you’ve already left your home province, look for Destination Canada or TuGo, as they are among the few providers that offer “post-departure” policies.

Can I cancel or modify my travel insurance policy if my plans change?

Yes, many Canadian insurers offer a “10-day free look” period where you can cancel for a full refund, provided you haven’t started your trip or filed a claim. After this window, modifications, such as changing your travel dates or destination may result in a premium adjustment.

How can I find cheaper travel insurance in Canada?

The most effective way to find affordable travel insurance is to compare quotes from multiple providers through PolicyAdvisor. Another tip is to opt for a higher deductible to lower your upfront premium.

Does travel insurance cover flight cancellations due to weather?

Yes, weather-related cancellations are covered if your policy includes “Trip Cancellation and Interruption” benefits and the weather event was unforeseen. Standard “Emergency Medical-only” plans do not cover flight disruptions. If you are traveling during hurricane or winter storm season, prioritize an “All-Inclusive” bundle from GMS or Manulife to ensure both your health and your travel investment are protected.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

MSH International travel insurance review Canada (2026)

MSH International’s Canuck Voyage travel insurance provides up to $7 million in emergency medical coverage for eligible expenses, including hospitalization, physician services, emergency transportation, and any other medical emergencies. MSH travel insurance premiums typically range from approximately $111 to $898.50, depending on the traveller’s age, selected plan, trip duration, and coverage options. It provides coverage for stable pre-existing medical conditions, typically 30-180 days, depending on the age.

Quick review: MSH travel insurance:

  • PolicyAdvisor rating: 4/5
  • Best for: Frequent travellers who want high emergency medical coverage without paying for bundled travel benefits they may not need
  • Skip if: You need trip cancellation, trip interruption, baggage, or travel delay coverage, as MSH focuses primarily on emergency medical insurance
Planning a trip soon?

Get a free MSH travel insurance quote now!

What is MSH International travel insurance?

MSH International travel insurance is an emergency medical insurance offered by MSH International Canada that protects eligible Canadian residents against unexpected medical emergencies while travelling outside their home province, including international travel. It offers travel insurance for Canadians through its Canuck Voyage policy, which includes both single-trip and annual multi-trip plans, allowing travellers to choose coverage based on how often and how long they travel. The coverage is designed for emergency treatment only and is subject to policy terms, eligibility requirements, exclusions, and pre-existing condition stability rules.

Key features of MSH travel insurance

Plan type Single-trip or annual multi-trip
Minimum eligibility age  15 days
Maximum eligibility age Under 80 years of age
Trip duration
  • Single-trip: 365 days (subject to eligibility)
  • Multi-trip: 5, 10, 20, 35, 50, 65, 100 days per trip
Pre-existing coverage (stability period)
  • Age 59 and under (trips up to 35 days): 30 days
  • Age 59 and under (trips over 35 days): 90 days
  • Ages 60-74: 90 days
  • Ages 75-79:180 days
Deductibles $250, $500, $1,000, $5,000, $10,000
Maximum coverage in emergency medical Up to $7,000,000
Optional coverage Top-up coverage for trips that exceed the number of days covered under an MSH annual multi-trip plan or another eligible travel insurance policy
Waiting period
  • No waiting period if purchased before departure
  • 48-hour waiting period for sickness if purchased after leaving your home province or territory
Policy extensions
  • Travel delay: Up to 5 days
  • Medically unfit to travel: Up to 5 days
  • Hospitalization: Coverage extends for the entire hospital stay, plus 5 days after discharge
Claims administered by  Intrepid 24/7™

Who is eligible for MSH International travel insurance?

To get an MSH travel insurance policy, you must:

  • Be a Canadian resident covered by your government health insurance plan for the entire duration of your trip
  • Purchase coverage for the entire duration of your trip
  • Be at least 15 days of age and under 80 years of age
  • Be travelling for no more than 35 days if you are between 60 and 79 years of age

Who is not eligible for MSH travel insurance?

You are not eligible to buy MSH International travel insurance if you are:

  • Travelling against the advice of a physician
  • Diagnosed with a terminal illness
  • If you are between 60 and 79 years of age, have been diagnosed with congestive heart failure or have an unrepaired aneurysm measuring 4.5 cm or more
  • Experiencing new or undiagnosed symptoms or know of any reason to seek medical attention
  • Travelling to obtain medical treatment outside your province or territory of residence, whether or not your attending physician recommends it
  • Using or having been prescribed home oxygen during the 12 months before the effective date
  • Require assistance with the activities of daily living

Types of MSH International travel insurance plans

MSH Travel Insurance offers flexible travel medical coverage through the Canuck Voyage plan, allowing Canadian travellers to choose between single-trip and multi-trip annual coverage based on their travel frequency.

  • Single-trip plan: Covers one trip outside your home province or territory of residence for the duration selected at the time of purchase. Depending on age, travellers can purchase coverage for trips of up to 365 days (up to age 59) or 35 days (ages 60-79)
  • Annual Multi-trip plan: Designed for frequent travellers, this plan covers multiple trips within a 12-month policy period without requiring a new policy for every journey. Travellers can choose trip duration limits of 5, 10, 20, 35, 50, 65, or 100 days per trip, while receiving the same emergency medical benefits available under the single-trip plan
  • Top-up plan: MSH also offers a top-up coverage for travellers whose trip extends beyond the coverage period of an existing MSH multi-trip annual plan or another eligible travel insurance policy. The top-up policy provides additional travel medical coverage for the remaining days of the trip, provided it is purchased before the existing coverage expires and all eligibility requirements are met
Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

What is covered under the MSH International travel insurance policy?

Here are the key benefits included under the Canuck Voyage policy:

  • Emergency medical treatment: Covers eligible emergency medical expenses if you become unexpectedly sick or injured while travelling, with coverage of up to $7 million per insured person, per trip
  • Hospitalization and physician services: Hospital stays, emergency room visits, physician care, nursing, and other eligible medical services
  • Emergency medical transportation: Ambulance, hospital transfers, medical evacuation, and repatriation to Canada
  • Prescription medications: Covers eligible prescription drugs required for emergency treatment, generally up to a 30-day supply, with exceptions while hospitalized
  • Emergency dental treatment: Includes up to $5,000 for accidental dental injuries and up to $500 for emergency dental pain requiring immediate treatment
  • Paramedical services: Eligible physiotherapy, chiropractic care, acupuncture, and other licensed treatments
  • Meals and accommodation: Eligible expenses if your return is delayed due to a covered medical emergency
  • Transportation to bedside: Economy airfare and accommodation for a family member or companion
  • Repatriation of remains: Covers eligible costs to return your remains to Canada or provides a benefit for cremation or burial at the place of death
  • Additional travel assistance benefits: Pet return, vehicle return, return of dependent children, travel companion, and excess baggage return
  • Identity fraud recovery: Provides financial assistance for eligible legal and administrative expenses related to identity fraud during your trip

MSH travel insurance coverage at a glance

Emergency medical expenses $7,000,000
Prescription drugs 30-day supply (limit does not apply while

hospitalized)

Paramedical services Up to $500 per insured person, per

profession

Dental accident Up to $5,000
Dental pain Up to $500
Transportation to the bedside Round-trip economy airfare plus up

to $150 per day to a maximum of

$1,500 each for the cost of meals and

commercial accommodation

Meals and accommodation $150 per day up to $3,000
Emergency air transportation Up to $250,000
Repatriation of remains Up to $15,000
Cremation or burial Up to $5,000
Vehicle return Up to $4,000
Pet return Up to $500
Excess baggage return Up to $500
Hospital allowance Up to $50 per day to a maximum of $500
Return to the original trip destination Up to $5,000
Identity fraud recovery Up to $5,000

What is not covered under MSH International travel insurance?

Here is a list of the common exclusions of the MSH International travel insurance policy:

  • Unstable pre-existing medical conditions that do not meet the required stability period before your policy starts
  • Non-emergency medical treatment, including routine care, elective procedures, cosmetic treatments, and ongoing treatment for chronic conditions
  • Travelling against a physician’s advice or travelling after being diagnosed with a terminal illness
  • Medical treatment that can reasonably be delayed until you return to your home province or territory
  • Symptoms or medical conditions that you ignored or did not seek timely medical treatment for when a reasonable person would have
  • Claims related to alcohol, illegal drugs, or other intoxicants that contributed to the illness, injury, or loss
  • Routine pregnancy care, childbirth, and related complications occurring within nine weeks before or after the expected delivery date
  • High-risk or extreme sports, such as mountaineering, skydiving, hang gliding, bungee jumping, professional sports, motorized racing, and certain scuba diving activities
  • Travel to destinations with a Government of Canada ‘Avoid All Travel or Avoid Non-Essential Travel advisory’
  • Losses resulting from illegal acts, self-inflicted injuries, war, terrorism, or nuclear, chemical, or biological events

Pros and cons of MSH International travel insurance

Pros Cons
High emergency medical coverage of up to $7 million No coverage for trip cancellation or interruption
Travel assistance benefits include pet return, vehicle return, transportation to bedside, return of children or travel companion, and repatriation benefits Certain treatments, diagnostic tests, and medical transportation require advance approval from Intrepid 24/7™
Additional discounts available through family rates and 5% companion savings No coverage for baggage loss, baggage delay, or travel delay expenses
Multi-trip plan coverage extends to a maximum of 100 days
Automatic policy extensions for eligible travel delays, hospitalization, or medical emergencies

How much does MSH International travel insurance policy cost?

MSH travel insurance premiums typically range from $111 to $898.50, depending on your age, trip duration, and whether you choose a single-trip or multi-trip annual plan with coverage for eligible pre-existing medical conditions.

The table below shows sample premium estimates for a Single-Trip plan and an Annual Multi-Trip plan with a 20-day per-trip limit.

Age Single-trip Annual Multi-trip(20 days per trip)
25 $ 117.00 $111.00
35 $ 117.00 $111.00
45 $ 117.00 $111.00
55 $ 180.60 $140.00
65 $ 360.60 $893.00
75 $ 898.50 –

Disclaimer: Premiums shown are sample estimates and may change based on the traveller’s age, trip details, coverage options, destination, deductible selected, and underwriting criteria

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

How to make a claim with MSH International travel insurance?

You need to follow these steps to file a claim against your MSH International travel insurance policy:

  • Notify Intrepid 24/7™ and submit your claim within 30 days of the first medical expense
  • Complete and submit the claim form. Please note that you will have to fill out for each illness or injury
  • Submit all the original documents from the approved medical providers, along with prescription drug receipts and proof of departure and return date
  • Sign and return the authorization form for MSH to coordinate payments with your provincial health insurance plan, if applicable
  • Once all the pending documents and claim forms have been submitted, track the claim status on the MSH website

Can you cancel or get a refund on MSH travel insurance?

Yes, MSH Travel Insurance offers both full and partial refunds, provided you meet the policy conditions.

  • Full refund (10-day free-look period): Cancel within 10 days of receiving your policy, before your trip starts, and provided no claim has been or will be made
  • Full refund before coverage begins: You can receive a full premium refund if you submit a written cancellation request before the policy’s effective date. Refund requests must be submitted in writing within 60 days of the policy’s expiry date
  • Partial refund: If you return home earlier than planned, you may receive a prorated refund, less a $25 administration fee, provided no claims were made during the coverage period
  • Family policies: Refunds are available only if all insured travellers under the policy qualify for a refund.
  • Annual Multi-Trip plans: Refunds are available only if the request is made before the effective date or if no travel has taken place

Does MSH travel insurance allow automatic extensions?

Yes, MSH allows you to extend your Canuck Voyage travel insurance automatically in specific situations if your return is unexpectedly delayed.

Automatic extensions are available if:

  • Your flight or other common carrier is delayed due to circumstances beyond your control
  • You are medically unfit to travel because of a covered sickness or injury before your policy expires
  • You, your immediate family member, or your travel companion is hospitalized at the end of the trip. In this case, coverage continues throughout the hospitalization, plus up to 5 days after discharge

How does MSH International compare to other travel insurance providers?

MSH International Travel Insurance stands out for its up to $7 million in emergency medical coverage, flexible Single-Trip and Annual Multi-Trip plans, and travel assistance benefits that are not commonly included with many travel medical insurance plans, such as identity fraud recovery, vehicle return, pet return, and automatic policy extensions.

Eligible travellers may also qualify for family rates and 5% companion savings. However, if you are comparing travel insurance companies based on pricing, trip cancellation benefits, baggage coverage, or coverage for seniors, it is worth reviewing multiple insurers before choosing a policy. Read our guide to the best travel insurance companies in Canada to compare top providers side by side.

Our advisor’s take on MSH International travel insurance

One of our advisors recently assisted a 55-year-old Canadian traveller planning multiple business and leisure trips throughout the year who wanted high emergency medical coverage with the flexibility of an annual plan.

Client profile:

  • Age: 55-year-old Canadian resident
  • Trip duration and type: Multiple international trips throughout the year for both work and personal travel
  • Primary concern: Finding flexible annual travel medical coverage with high coverage that would cover multiple trips throughout the year
  • Our comparison: We compared travel medical insurance plans from several Canadian providers and recommended MSH’s Canuck Voyage Travel Insurance. While many insurers offer bundled travel insurance with trip cancellation and baggage coverage, MSH stood out for its up to $7 million in emergency medical coverage, multi-trip options ranging from 5to 100 days per trip, and additional travel assistance benefits that go beyond standard emergency medical coverage

Why we recommended MSH Travel Insurance:

  • Offers a top-up coverage option for multi-trip plans
  • Includes automatic policy extensions for eligible travel delays and 24/7 Intrepid 24/7™ emergency assistance with medical coordination and direct billing where available
  • Provides an additional 5% companion savings and family rates to help you save on premiums
  • Includes additional travel assistance benefits such as identity fraud recovery, vehicle return, pet return, and return to your original trip destination

If you are considering MSH Travel Insurance, our licensed PolicyAdvisor experts can compare it with other leading Canadian insurers and recommend the best option based on your destination, trip length, and budget. Schedule a call today!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Is MSH Travel Insurance good?

Yes, MSH Travel Insurance is a good option for Canadians looking for emergency medical coverage while travelling. It offers up to $7 million in emergency medical coverage, flexible Single-Trip and Annual Multi-Trip plans, 24/7 emergency assistance, and coverage for eligible stable pre-existing medical conditions.

Does MSH Travel Insurance cover pre-existing medical conditions?

Yes, MSH Travel Insurance covers eligible stable pre-existing medical conditions. The required stability period ranges from 30 to 180 days, depending on the traveller’s age and, in some cases, trip duration. Any condition that does not meet the stability requirements is generally excluded.

Does MSH Travel Insurance offer annual multi-trip coverage?

Yes, MSH offers an annual multi-trip plan that covers multiple trips during a 12-month policy period. You can choose trip duration limits of 5, 10, 20, 35, 50, 65, or 100 days per trip.

Can I extend my MSH Travel Insurance policy?

Yes, MSH automatically extends coverage for up to 5 days if your return is delayed due to a covered travel delay, a covered sickness or injury that makes you unfit to travel, or hospitalization. Longer trips may also be covered through an eligible top-up coverage if purchased before your existing coverage expires.

Does MSH Travel Insurance cover trip cancellation?

No, MSH’s Canuck Voyage policy is primarily an emergency medical travel insurance plan. It does not include trip cancellation or trip interruption benefits, so travellers who need those coverages should compare other travel insurance plans before purchasing.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

21st Century travel insurance review (2026)

Planning a trip outside your home province or Canada is exciting, but unexpected medical emergencies or travel disruptions can quickly become expensive. 21st Century Travel Insurance offers an array of travel insurance plans designed to protect travellers from unexpected medical expenses, trip cancellations, and other travel-related risks.

Quick Review

  • PolicyAdvisor rating: 4/5
  • Best for: Travellers who want flexible deductible options, ranging from $0 to $10,000, to help lower premiums
  • Skip if: You want Cancel for Any Reason (CFAR) coverage or greater flexibility for cancelling your trip
Planning a trip soon?

Get a free travel insurance quote now!

What is 21st Century Medicare International travel insurance?

21st Century Medicare International travel insurance is a range of travel insurance plans aimed at protecting Canadians travelling outside their home province or Canada from unexpected medical emergencies and travel-related disruptions.

Depending on the policy you choose, coverage may include emergency medical treatment, trip cancellation and interruption, baggage protection, travel accident coverage, and 24/7 emergency assistance services. Additionally, the choice between medical and non-medical plans allows travellers to select a plan that works best for them.

21st Century Medicare International travel insurance: At a glance

Feature Details
Plans available
  • Emergency Medical 
  • All-Inclusive 
  • Trip Cancellation & Interruption 
Age eligibility 30 days and older (no maximum age, subject to eligibility and underwriting)
Maximum emergency medical coverage Up to $10 million (Emergency Medical & All-Inclusive)
Trip cancellation & interruption Available through All-Inclusive and Trip Cancellation & Interruption plans
Travel accident coverage Included with eligible All-Inclusive plans
Pre-existing coverage Eligible stable pre-existing medical conditions (3 or 6 months, depending on the selected rate category and plan)

Types of travel insurance plans offered by 21st Century Medicare International travel insurance

21st Century Medicare International Travel Insurance offers a wide range of plans for travelling Canadians. Depending on how often you travel, you can choose between Single-trip and Multi-trip coverage for your trips. Whether you’re taking a single vacation or travelling multiple times a year, the insurer offers plans that meet different travel needs and budgets.

Additionally, the insurer provides both medical and non-medical plans, allowing applicants to choose what works best for them. Meanwhile, the All-Inclusive plans combine medical and non-medical plans to offer a comprehensive package that includes emergency medical coverage alongside trip interruption, baggage, travel delay, and other non-medical benefits.

Here’s an overview of the different 21st Century travel insurance plans:

Emergency medical plans

Emergency Medical plans protect travellers against unexpected medical emergencies while travelling. Depending on your travel frequency and medical history, 21st Century offers two different plans to choose from:

  • Single-Trip Emergency Medical
  • Multi-Trip Emergency Medical

Here’s a quick comparison of the emergency medical plans offered by 21st Century Medicare International Travel Insurance:

Feature Single-Trip Emergency Medical Multi-Trip Emergency Medical
Emergency medical coverage Up to $10 million Up to $10 million per trip
Best for One vacation or trip Frequent travellers
Trip duration Up to 212 or 365 days (depending on the plan selected) 4, 10, 18, 30, or 60 days per trip
Deductible options $0–$10,000 $0–$10,000
Top-up coverage Available Available
Pre-existing condition coverage Covers eligible stable pre-existing medical conditions (3- or 6-month stability period) Covers eligible stable pre-existing medical conditions (3- or 6-month stability period)

Non-medical plans

Non-medical plans help travellers who already have emergency medical coverage or only want protection for prepaid travel expenses. 21st Century Travel Insurance offers a standalone Trip Cancellation & Interruption plan that reimburses eligible costs if a covered event cancels, interrupts, or delays your trip due to a covered event.

Here’s a quick overview of the Trip Cancellation & Interruption plan offered by 21st Century Travel Insurance:

Feature Stand-alone Trip Cancellation & Interruption
Trip cancellation Reimbursement of eligible expenses up to the covered amount before departure
Trip interruption Reimbursement of eligible expenses after departure
Delayed return Included for covered events
Misconnection insurance Up to $1,000
Repatriation and burial expenses
  • Up to $5,000 for preparation of your body and repatriation or local burial 
  • Up to $5,000 for burial expenses, excluding headstones, flowers, and reception costs, or local cremation with the return of your ashes home
Emergency medical Not included
Trip duration Up to 365 days
Pre-existing condition coverage Not applicable (medical stability requirements apply to covered cancellation claims)

All-inclusive plans

All-Inclusive plans combine emergency medical insurance with trip cancellation, trip interruption,  and travel accident coverage into a single comprehensive policy. These plans are ideal for travellers looking for broader protection throughout their trip. 

21st Century Travel Insurance offers two All-Inclusive plans, depending on how often you travel:

  • Single-Trip All-Inclusive
  • Multi-Trip All-Inclusive

Here’s an overview of the Single-Trip All-Inclusive and Multi-Trip All-Inclusive plans offered by 21st Century Medicare International Travel Insurance:

Feature Single-Trip All-Inclusive Multi-Trip All-Inclusive
Emergency medical coverage Up to $10 million Up to $10 million per trip
Trip cancellation & interruption Up to $3,500 Up to $3,500 per trip (maximum $6,000 per policy)
Baggage loss or damage Up to $1,000 Up to $1,000 per trip (maximum $3,000 per policy)
Baggage delay Up to $500 Up to $500 per trip (maximum $1,500 per policy)
Flight accident Up to $100,000 Up to $100,000
Travel accident Up to $50,000 Up to $50,000
Trip duration Up to 212 or 365 days 4, 10, 18, or 30 days per trip
Pre-existing condition coverage Covers eligible stable pre-existing medical conditions (3- or 6-month stability period, depending on the rate category) Covers eligible stable pre-existing medical conditions (3- or 6-month stability period, depending on the rate category)

Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

Pros and Cons of 21st Century Medicare International Travel Insurance

Pros:
✓Eligible plans provide up to $10 million in emergency medical coverage for unexpected illnesses and injuries while travelling
✓Flexible deductible options from $0 to $10,000 help travellers customize their premiums
✓Single Trip plans cover trips of up to 365 days, making them suitable for extended travel
Cons:
✗Policy extensions must be requested before coverage expires and are only available if there has been no change in health or circumstances
✗Does not offer an optional Cancel for Any Reason (CFAR) rider for travellers who want maximum flexibility
✗Certain medical treatments require prior approval from the Assistance Centre

Does 21st Century offer family travel insurance?

Yes, 21st Century offers family coverage on eligible travel insurance plans for Canadians. The insurer offers a family coverage option on the Single Trip Emergency Medical and the Multi-Trip Emergency Medical plans. Families can insure eligible members under the same policy provided they meet the plan’s eligibility requirements and satisfy the insurer’s underwriting conditions where applicable.

To qualify for family coverage:

  • All family members must be listed on the policy confirmation.
  • Each insured must be at least 30 days old and under 60 years of age.
  • Each traveller must be covered under a valid provincial or territorial Government Health Insurance Plan (GHIP)
  • All family members must have the same coverage start and end dates.
  • All applicable premiums must be paid

Keep in mind that additional plan-specific conditions may apply. Refer to policy documentation for the full list of requirements.

Who is eligible for 21st Century Travel Insurance?

Any Canadian resident with active provincial or territorial health coverage who is travelling outside their home province or outside Canada and who meets 21st Century’s requirements can purchase these travel insurance plans. However, coverage eligibility, age restrictions, medical stability requirements, and policy exclusions vary by plan and chosen riders.

Here’s an overview of the general eligibility requirements for the different 21st Century Travel Insurance plans:

21st Century travel insurance plan Eligibility requirements
Emergency Medical & All-Inclusive Insurance
  • Must be a resident of Canada and covered under a provincial or territorial government health insurance plan for the entire duration of the trip.
  • Must be at least 30 days old.
  • Must not have been advised by a physician to avoid travel.
  • Must not have a terminal illness or metastatic cancer.
  • Must not require kidney dialysis.
  • Must not have been prescribed or used home oxygen within the last 12 months.
  • Must never have had a bone marrow, stem cell, or organ transplant (except a corneal transplant).
Trip Cancellation & Interruption Insurance
  • Must be living in Canada or travelling through Canada.
  • Must have paid the required premium.
  • Coverage also applies to travel within your province or territory of residence

Note: Refer to the policy wording for the full list of eligibility requirements, exclusions, and limitations.

How much does 21st Century travel insurance cost?

The cost of 21st Century Medicare International travel insurance ranges between $46.50 and $1386.30, based on the stability of any pre-existing condition. Additionally, your premium depends on your plan, duration, and the riders you select with your policy.

Here’s a sample travel insurance premium for a traveller on a trip for 15 days:

Age Single-trip plan (basic) Single-trip plan (with stable pre-existing coverage) Multi-trip plan (with stable pre-existing coverage)
25 $46.50 $116.70 $ 122.00
35 $51.90 $126.30 $ 132.00
45 $58.20 $139.50 $ 141.00
55 $61.50 $162.00 $ 154.00
65 $103.50 $244.50 – $621.60* $233.00 – $489.00*
75 $199.50 $546.90 – $1,386.30* $465.00 – $1,155.00*

Disclaimer: Illustrative premiums for single-trip and multi-trip annual Emergency Medical plans ($10 million coverage). Actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

Are there any exclusions or limitations to 21st Century Travel Insurance? 

Yes, there are certain exclusions and limitations to the different plans of 21st Century Medicare International travel insurance. While the plans offer comprehensive emergency coverage, the insurer does not cover certain conditions and situations.

Here’s an overview of the general exclusions and limitations of 21st Century travel insurance:

Exclusion Category What is not covered
Heart and lung conditions
  • Unstable heart or lung conditions may not be covered.
  • Recent nitroglycerine use, oxygen therapy, or Prednisone treatment during the required stability period may result in excluded claims.
Unauthorized medical procedures
  • Certain diagnostic tests require prior approval.
  • Most surgeries and specialized treatments must be authorized by the Assistance Centre before they are performed.
Non-emergency or elective treatment
  • Elective, cosmetic, and experimental procedures are excluded.
  • Chronic care, rehabilitation, and non-emergency treatment are not covered.
Hazardous sports and activities
  • Injuries from high-risk activities such as rock climbing, mountaineering, skydiving, hang-gliding, and motorized racing are not covered.
Medical tourism
  • Trips taken primarily to receive medical treatment, surgery, diagnosis, or alternative therapy are excluded.
Self-inflicted injuries and illegal acts
  • Intentional self-inflicted injuries are generally excluded (subject to policy exceptions).
  • Claims resulting from criminal or illegal acts are not covered.
Alcohol, drug use, and failure to follow treatment
  • Claims related to alcohol or drug abuse are excluded.
  • Withdrawal symptoms are not covered.
  • Failure to follow prescribed treatment or medication may invalidate a claim.
Mental health limitations
  • Minor mental or emotional disorders are generally not covered.
Pregnancy and newborn care
  • Routine prenatal and postnatal care is excluded.
  • Certain pregnancy-related expenses, newborn medical costs, and congenital birth defects are not covered.
Refusal to return home
  • Coverage may end if you refuse to return home or transfer to another facility after the insurer’s medical advisors recommend it.
Policy extension limitations
  • New medical conditions that arise before an approved extension takes effect are not covered.
Government travel advisories
  • Claims related to destinations under a Government of Canada “Avoid all travel” or “Avoid non-essential travel” advisory may be excluded.
  • Exceptions may apply for unrelated medical emergencies

Note: This list summarizes the most common exclusions found across 21st Century travel insurance plans. Coverage varies by plan and policy wording, so it is recommended to refer to your policy for the complete list of exclusions, limitations, and definitions.

How to file a claim with 21st Century Medicare International travel insurance?

If you experience a medical emergency or another covered loss during your trip, contact the 21st Century Assistance Centre as soon as possible to begin the claims process.

Here’s how you can file a claim with 21st Century during your trip:

  • Contact the Assistance Centre immediately: Contact the Assistance Centre in Canada and the United States at 1-855-478-3484, and internationally at +1 (519) 251-7851. You must contact the Assistance Centre before receiving emergency treatment whenever possible. Failure to notify the Assistance Centre within 24 hours may result in you being responsible for 20% of eligible expenses
  • Obtain pre-approval: Certain medical services and benefits require prior authorization through the Assistance Centre. If you do not obtain pre-approval when required, the insurer may deny your claim
  • Submit your claim: After you report your claim, the Assistance Centre will furnish forms for proof of claim within 15 days after receiving notice of claim. You can visit the online portal at https://manulife.acmtravel.ca to submit your claim online or mail the documents to them.
  • Submit proof of claim: Submit all claims within 30 days, and any documentation must be given within 90 days of the illness or injury.

Can you cancel or get a refund on 21st Century travel insurance?

Yes, 21st Century allows policy cancellations and refunds under certain circumstances. Your refund eligibility depends on the type of policy purchased, whether coverage has started, and whether a claim has been made.

Here is the 21st Century Medicare International travel insurance refund policy at a glance:

Situation Refund Eligibility and fees
Within the 10-Day free look period 100% premium refund if you cancel within 10 days of purchase, have not departed, and no claim is in progress.
After the 10-Day free look No premium refund for most plans. Has a $25 fee per policy for eligible refunds or cancellations
Trip Cancellation & Interruption plans After the 10-Day Free Look period, cancellations and refunds are not available.
Return home early (eligible Emergency Medical plans) May qualify for a partial refund of unused coverage if no claim has been made, no assistance services were provided, and a Travel Medical Refund Request form is submitted. Has a $25 fee per policy for eligible refunds or cancellations

Note: Refer to the policy wording for the complete refund terms, conditions, and eligibility requirements. Additionally, the minimum refundable amount is $10. Refunds below this amount are not issued.

Can you extend 21st Century travel insurance coverage?

If your trip lasts longer than originally planned, you may be able to extend or top up your 21st Century travel insurance coverage before your policy expires. However, extensions are subject to approval and must meet all necessary eligibility requirements.

Here’s what you need to know about extending your 21st Century Medicare International travel insurance policy:

  • Apply before your policy expires: Extension requests must be submitted before your existing coverage ends.
  • No lapse in coverage: Your extension request must ensure continuous coverage with no gap between policies
  • No existing or pending claims: Extensions are generally only available if no event has occurred that has resulted in or may result in a claim.
  • No change in health: You must confirm there has been no change in your health since purchasing the policy.
  • Approval is required: All extensions are subject to approval by 21st Century

Additionally, 21st Century travel insurance also offers automatic extensions in certain situations. Your coverage may automatically extend for up to 72 hours if your common carrier is delayed, you are hospitalized on your expiry date, or for up to 5 days if a covered medical emergency prevents you from returning home as scheduled, subject to policy limits.

How does 21st Century compare to other travel insurance providers?

21st Century offers a broad selection of travel insurance plans, including Emergency Medical, All-Inclusive, and Trip Cancellation & Interruption coverage, so travellers can choose the level of protection that best fits their needs.

The plans include up to $10 million in emergency medical coverage on eligible plans, Single Trip coverage for trips of up to 365 days, annual Multi Trip options for frequent travellers, and flexible deductible choices to help customize premiums. These features make 21st Century a strong option for Canadians looking for emergency medical or comprehensive travel insurance.

For a detailed comparison of the best travel insurance plans, check out our list of the Best travel insurance companies in Canada

Our advisor’s take on 21st Century travel insurance

At PolicyAdvisor, we recently assisted a 67-year-old retiree planning a five-month winter vacation in Arizona. The individual was seeking comprehensive travel insurance that would cover emergency medical expenses while also protecting their prepaid travel costs in case their plans changed.

The client profile

  • Age: 67 years
  • Purpose of travel: Five-month winter vacation in the United States
  • Primary concern: Finding affordable travel insurance with high emergency medical coverage and protection for prepaid travel expenses during a longer trip
  • Coverage needed: Single-Trip All-Inclusive travel insurance

Why we recommend 21st Century Travel Insurance

We recommended this plan because it offers:

  • Up to $10 million in emergency medical coverage on eligible plans
  • Single Trip coverage for trips of up to 365 days
  • Comprehensive All-Inclusive options that combine medical and travel-related benefits
  • 24/7 worldwide emergency assistance
  • Flexible deductible options to help manage premiums

How to purchase 21st Century travel insurance in Canada

PolicyAdvisor’s licensed travel insurance advisors can help you compare 21st Century Travel Insurance plans based on your destination, trip duration, age, medical history, and coverage needs.

Whether you are heading abroad for a vacation or planning multiple trips throughout the year, our advisors at PolicyAdvisor can guide you through 21st Century’s coverage options and policy limits to help you purchase the right travel insurance.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

Does 21st Century travel insurance cover pre-existing medical conditions?

Yes, some 21st Century travel insurance plans cover stable pre-existing medical conditions if you meet the applicable stability requirements.

Does 21st Century travel insurance cover trip cancellation?

Yes, trip cancellation coverage is available through 21st Century’s Stand-alone Trip Cancellation & Interruption and All-Inclusive plans. Benefits are payable if you cancel or interrupt your trip for a covered reason as per the policy.

How much travel medical coverage does 21st Century travel insurance provide?

Coverage limits vary by plan. Depending on the policy you purchase, 21st Century offers emergency travel medical coverage of up to $10 million for eligible medical emergencies while travelling.

Does 21st Century travel insurance cover baggage loss or delays?

Yes, but only under plans that include travel benefits, such as the All-Inclusive and Non-Medical Trip Interruption plans.

Does 21st Century travel insurance offer Cancel for Any Reason (CFAR) coverage?

No, 21st Century travel insurance plans do not offer Cancel for Any Reason (CFAR) coverage as a benefit or rider.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Manulife travel insurance review (2026)

Planning an international trip is exciting, but unexpected medical emergencies can quickly derail your plans. Manulife CoverMe travel insurance helps cover those unexpected costs with up to $10 million in emergency medical benefits for single-trip or annual multi-trip travel. 

Quick review

  • PolicyAdvisor ratings: 5/5
  • Best for: Travellers looking for flexible travel insurance with comprehensive coverage and family-friendly pricing
  • Skip if:  You take frequent trips that regularly exceed 30 days, as Manulife’s annual All-inclusive plan has shorter trip duration limits than some competitors.
Planning a trip soon?

Get a free travel insurance quote now!

What is Manulife travel insurance?

Manulife CoverMe travel insurance offers a range of travel insurance plans aimed at protecting Canadians travelling outside their home province or Canada from unexpected medical emergencies and travel-related disruptions. 

Depending on the travel insurance plan you choose, you can receive coverage for emergency medical expenses, trip cancellation and interruption, baggage loss or delay, travel accidents, and other eligible travel-related expenses

Manulife CoverMe travel insurance: At a glance

Feature Details
Plans available
  • Emergency Medical
  • All-Inclusive 
  • Trip Cancellation & Interruption 
  • Non-Medical Inclusive 
Age eligibility 30 days to 84 years for most plans (eligibility varies by plan)
Maximum emergency medical coverage Up to $10 million (depending on plan)
Trip cancellation & interruption Included with All-Inclusive plans or available as a standalone Trip Cancellation & Interruption plan
Travel accident coverage Included with eligible All-Inclusive and Non-Medical Inclusive plans
Family coverage Available on eligible Emergency Medical, All-Inclusive, and Non-Medical plans for qualifying families under age 60
Pre-existing coverage Covered if eligible, subject to 3 to 6 months of stability for Emergency Medical coverage (varies by age and plan)

Types of travel insurance plans offered by Manulife

Manulife CoverMe offers a wide range of travel insurance plans for travelling Canadians. Whether you’re taking a single vacation or travelling multiple times a year, the insurer offers plans designed for different travel needs and budgets. 

Here’s an overview  of different Manulife travel insurance plans:

Medical plans

Medical plans help Canadians protect themselves against emergency medical expenses while travelling. Depending on your travel frequency and medical history, Manulife offers three different plans to choose from:

  • Single-Trip Emergency Medical Plan
  • Multi-trip Emergency Medical Plan
  • TravelEase® Plan for Pre-Existing Conditions

Here’s a quick comparison of the two single-trip medical plans offered by Manulife CoverMe travel insurance:

Feature Single-Trip Emergency Medical Plan Multi-trip Emergency Medical TravelEase Plan for Pre-Existing Conditions
Emergency medical coverage Up to $10 million Up to $10 million Up to $10 million
Pre-existing conditions Covers stable pre-existing conditions (3- or 6-month stability period, depending on your rate category) Covers stable pre-existing conditions (3- or 6-month stability period, depending on your rate category) Covers eligible conditions approved through medical underwriting
Trip duration Up to 365 days Unlimited trips per year (4, 10, 18, 30, or 60 days per trip) Single-Trip (up to 365 days) or Multi-trip (10- or 18- day options)
Accidental dental  Up to $3,000 for accidental dental and $300 for pain relief Up to $3,000 for accidental dental and $300 for pain relief Up to $3,000 for accidental dental and $300 for pain relief
Child care expenses $75/day, up to $500/trip $75/day, up to $500/trip Not available
Meals & accommodation during a medical emergency $350 per day, to a maximum of $3,500 $350 per day to a

maximum of $3,500

$200 per day, to a maximum of $2,000
Government Health Travel Advisory (GHTAC) Rider Available Not available Not available

Non-medical plans

Manulife also offers non-medical plans to travellers who already have medical insurance or only want protection for trip cancellations, baggage, and travel disruptions.

Manulife offers the following plans:

  • Trip Cancellation & Interruption
  • Non-Medical Inclusive

Here’s a quick comparison of the two single-trip non-medical plans offered by Manulife CoverMe travel insurance:

Feature Trip Cancellation & Interruption Non-Medical Inclusive
Trip cancellation Up to the selected insured amount Up to the selected insured amount
Trip interruption $800, $1,500, or Unlimited (depending on the selected plan) Unlimited
Misconnection & travel disruption Up to $1,700 Up to $2,700
Trip duration Up to 365 days Up to 365 days
Delayed return $150/day, up to $1,500 $350/day, up to $3,500
Baggage loss & damage Not included Up to $1,500
Baggage delay Not included Up to $500
Flight & travel accident Not included Up to $100,000 (flight accident) and $50,000 (travel accident)
Cancel for Any Reason (CFAR) Rider Available (up to 50% of the prepaid portion of your trip that is non-refundable) Available (up to 50% of the prepaid portion of your trip that is non-refundable)

All-inclusive plans

All-inclusive plans combine medical and non-medical plans to offer a comprehensive package that covers emergency medical coverage alongside trip interruption, baggage, travel delay, and other non-medical benefits. 

Depending on the frequency of your travel, Manulife offers the following All-Inclusive plans:

  • Single Trip All-Inclusive Plan
  • Multi-Trip All-Inclusive

Here’s a quick comparison of the two All-inclusive plans offered by Manulife CoverMe travel insurance:

Feature Single Trip All-Inclusive Multi Trip All-Inclusive
Emergency medical coverage Up to $10 million Up to $10 million per trip
Trip cancellation & interruption Included Included
Baggage coverage Up to $1,500 up to $1,500
Travel accident coverage Up to $100,000 (flight accident) and $50,000 (travel accident) Up to $100,000 (flight accident) and $50,000 (travel accident)
Emergency dental Up to $3,000 accidental dental Up to $3,000 accidental dental
Trip duration Age 0‑59: Up to 365 daysAge 60‑74: Up to 60 days

Age 75+: Up to 45 days

Multiple trips annually
(4, 10, 18, or 30 days per trip)
Government Health Travel Advisory (GHTAC) Rider Available Not available
Cancel for Any Reason (CFAR) Rider Available Not available

Note: Manulife also offers Youth All-Inclusive and Youth Deluxe All-Inclusive plans for travellers aged 29 and under. The Youth All-Inclusive plan covers trips of up to 365 days, while the Youth Deluxe All-Inclusive plan covers trips of up to 30 days. These plans provide discounted comprehensive travel insurance with emergency medical and non-medical coverage, making them a cost-effective option for eligible young travellers.

Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

Pros and Cons of Manulife CoverMe Travel Insurance

Pros:
✓Up to $10 million in emergency medical coverage
✓TravelEase® plans provide medically underwritten coverage for eligible travellers with pre-existing medical conditions. Family coverage is available on eligible plans, allowing family members to be insured together under a single policy
✓Access to 24/7 emergency assistance through the Manulife Assistance Centre and the TravelAid app, including online claims submission and travel support
✓Optional riders such as Cancel for Any Reason (CFAR) and the Government Travel Advisory Rider are available on eligible plans
Cons:
✗Some medical expenses, diagnostic tests, and transportation services require prior approval from the Assistance Centre
✗Annual Multi-Trip plans have maximum per-trip duration limits, requiring travellers to purchase top-up coverage for longer trips

Does Manulife offer family travel insurance?

Yes, Manulife offers family coverage on eligible travel insurance plans for Canadians. The insurer offers a family coverage option on Single-trip Emergency Medical, Single-trip All-Inclusive, Non-Medical Inclusive, and Multi-trip Emergency Medical plans. You can insure eligible family members under a single policy if they meet the plan’s requirements.

To be eligible for Manulife’s Family Coverage option:

  • All family members must be named on the policy confirmation
  • Insured family members must be under 60 years of age
  • You must meet all of the plan’s eligibility requirements when purchasing the policy
  • The family premium must be paid
  • For Single-trip and Non-Medical Inclusive plans, family members must travel together

Who is eligible for Manulife CoverMe travel insurance?

Canadian residents with active provincial or territorial health coverage, at least 30 days of age, travelling outside their home province or outside Canada, and who meet the requirements for Manulife are eligible for the travel insurance plans. However, coverage eligibility, age restrictions, medical stability requirements, and policy exclusions vary by plan and chosen riders.

Here’s an overview of the general eligibility requirements for the different Manulife CoverMe travel insurance plans:

Plan Medical questionnaire Key eligibility requirements
Emergency Medical
  • Single-trip: Not required if under age 60
  • Multi-trip: Not required if under age 60
  • Single-trip: Covers one trip up to 365 days
  •  Multi-trip: Annual plan with 4-, 10-, 18-, 30-, or 60-day trip options (no trip duration limit for travel within Canada)

 Stable pre-existing conditions may be covered (subject to the applicable stability period)

TravelEase® Plan for Pre-Existing Conditions
  • Single-trip: Required
  • Multi-trip: Required
Medical underwriting required

  • Single-trip: Covers one trip up to 365 days
  • Multi-trip: Annual plan with 10- or 18-day trip options
  • Covers eligible pre-existing medical conditions approved through underwriting
Trip Cancellation & Interruption Not required
  • Covers one trip up to 365 days
  • Can be purchased without emergency medical coverage
Non-Medical Inclusive Not required
  • Covers one trip up to 365 days
All-Inclusive
  • Single-trip: Not required
  • Multi-trip: Not required if under age 60
  • Single-trip: Trip duration varies by age (up to 365 days for travellers aged 0–59)
  • Multi-trip: Annual plan with 4-, 10-, 18-, or 30-day trip options
  • The plan may cover stable pre-existing medical conditions, provided you meet the applicable stability requirements

Note: Refer to the policy wording for the full list of eligibility requirements, exclusions, and limitations.

Who is not eligible for Manulife travel insurance?

While Manulife CoverMe travel insurance is available to many Canadian travellers, certain restrictions related to health and travel can prevent applicants from getting coverage under Manulife travel insurance or require medical underwriting, depending on the plan you choose.

You may not be eligible for Manulife travel insurance under the following circumstances:

  • Have been advised by a physician not to travel.
  • Have been diagnosed with a terminal illness with a life expectancy of less than six months.
  • Have a kidney condition that requires dialysis.
  • Have used home oxygen for a lung condition within the 12 months before applying for insurance.
  • Are 60 years of age or older and do not meet the eligibility requirements in the required medical questionnaire for applicable plans (such as Multi-trip All-Inclusive)

Additionally, medical underwriting plans, such as TravelEase®, have the following restrictions:

  • Awaiting investigative tests or treatment for an unresolved medical condition (excluding genetic tests)
  • Require kidney dialysis or prescribed home oxygen for a lung condition within 12 months before applying
  • Had or are awaiting an organ, stem cell, or bone marrow transplant
  • Have metastatic cancer or a terminal illness with a life expectancy of less than six months

How much does Manulife travel insurance cost?

The cost of Manulife CoverMe travel insurance ranges between $137.10 and $1,455.90, based on the stability of any pre-existing condition. Additionally, your premium depends on your plan, duration, and the riders you select with your policy. 

Here’s a sample travel insurance premium for a traveller on a trip for 15 days:

Age Coverage amount  Single-trip plan (with pre-existing)
25 $10,000,000.00 $137.10
35 $148.50
45 $164.10
55 $188.10
65 $256.80 – $652.80*
75 $574.20 – $1,455.90*

Disclaimer: Illustrative premiums for multi-trip annual Emergency Medical plans ($10 million coverage). Actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

Are there any exclusions or limitations to Manulife travel insurance?

While the plans offer comprehensive emergency coverage, certain conditions and situations like medical tourism, high-risk activities, and substance abuse are excluded or limited under the policy.

Here’s an overview of the general exclusions and limitations of Manulife CoverMe travel insurance:

Exclusion category What you need to know
Unstable pre-existing medical conditions Medical conditions that do not meet the applicable stability requirements or are not approved through Medical Underwriting may not be covered.
Medical tourism & planned treatment Travel undertaken primarily to obtain medical treatment, surgery, or healthcare services is excluded.
Unapproved medical expenses Certain services, including medical evacuations, transportation, surgeries, and some diagnostic tests, require prior authorization from the Assistance Centre.
Alcohol, drugs & substance misuse Claims arising from excessive alcohol consumption, intoxication, illegal drug use, or misuse of medication are not covered.
Mental health Treatment related to mental, emotional, or psychiatric disorders is limited and subject to the terms and exclusions of the policy.
Pregnancy & childbirth Routine prenatal care, normal childbirth, and pregnancy-related expenses beyond the limits specified in the policy are generally excluded.
High-risk activities & sports Injuries resulting from certain hazardous occupations, extreme sports, or high-risk recreational activities may not be covered.
Illegal or intentional acts Claims resulting from criminal acts, intentional self-inflicted injuries, attempted suicide, or participation in unlawful activities are excluded.
Travel against medical advice Coverage is not available if you travel against the advice of a physician or when travel is medically prohibited
Known or foreseeable events Claims arising from situations, medical conditions, or events that were known or reasonably foreseeable before purchasing the policy are not covered.
Government travel advisories Coverage may be limited or excluded when travelling to destinations subject to certain Government of Canada travel advisories unless your policy includes an applicable Government Travel Advisory Rider.

Note: This list summarizes the most common exclusions found across Manulife travel insurance plans. Coverage varies by plan and policy wording, so it is recommended to refer to your policy for the complete list of exclusions, limitations, and definitions.

How to file a claim with Manulife travel insurance? 

If you experience a medical emergency or another covered loss during your trip, contact the Manulife Assistance Centre as soon as possible to begin the claims process. All CoverMe plans offer support through the Manulife TravelAid app, online, or by mail

Here’s how you can file a claim with Manulife during your trip:

  • Contact the Assistance Centre immediately: You can contact the Assistance Centre in Canada and the United States at 1-888-881-8010 and internationally at +1-519-945-8346; failure to notify the Assistance Centre within 24 hours may result in you being responsible for 25% of eligible expenses
  • Obtain pre-approval: You must obtain prior authorization for certain medical services and benefits through the Assistance Centre. If pre-approval is not obtained, your claim may not be covered
  • Submit your claim: You can submit your claim using the Manulife TravelAid mobile app, online at manulife.acmtravel.ca, or by mailing your completed claim form
  • Gather supporting documents: You may need to submit itemized medical bills, payment receipts, and other documents; keep them handy and submit them when requested
  • Submit proof of claim: Submit all claim documentation within 90 days of the illness or injury, and expenses must be submitted to Manulife within 12 months of the date of the last eligible expense

Can you cancel or get a refund on Manulife travel insurance?

Yes, Manulife CoverMe travel insurance allows policy cancellations and refunds under certain conditions. It depends on whether coverage has started, whether a claim has been filed, and the reason for cancellation. 

Here is the Manulife travel insurance refund policy at a glance:

Situation Refund Eligibility
Cancelled within 10 days of purchase Full refund under the 10-day Free Look period if you have not departed on your trip and no claim(s) are in progress
Changed your mind after purchasing Eligible for a full refund if you cancel before the policy’s effective date, provided you have not departed on your trip or incurred a claim.
Return home earlier than planned You may become eligible for a refund of the unused premium if you return home before your scheduled return date, provided no claim has been paid or is pending (subject to the policy terms and minimum retained premium)
Policy is no longer required If coverage has already started, refunds are generally only available under the circumstances specifically outlined in the policy (such as an early return), provided no claim has been made.
Claim submitted or paid Not eligible. Once a claim has been paid or is pending under the policy, no refund of premium is available.
Policy cancelled after coverage begins Refunds are only available for eligible unused coverage as described in the policy. Manulife may request additional documents before processing your refund

Note: Refer to the policy wording for the complete refunds terms, conditions, and eligibility requirements.

Can you extend Manulife travel insurance coverage?

If your trip lasts longer than originally planned, you may be able to extend or top up your Manulife travel insurance coverage before your policy expires. However, extensions are subject to approval and must meet all necessary eligibility requirements.

Here’s what you need to know about extending your Manulife CoverMe travel insurance policy:

  • Request an extension before your policy expires: Contact Manulife before your coverage end date to request an extension. You cannot extend your coverage after your policy expires
  • Remain eligible for coverage: You must still meet the policy’s eligibility requirements at the time of the extension request. Depending on the plan, you may also need to confirm that there has been no change in your health
  • Purchase top-up coverage (Multi-trip plans): If your trip exceeds your plan’s maximum trip duration or extends beyond the policy expiry date, you may purchase top-up coverage for the additional travel days by contacting Manulife
  • Receive confirmation of your new coverage period: Your policy extension is not effective until Manulife approves the request and issues confirmation of the revised expiry date
Manulife Travel Insurance cancellations and extensions

How does Manulife compare to other travel insurance providers?

While many of Canada’s leading travel insurers offer similar emergency medical and trip cancellation coverage, Manulife stands out for its broad range of travel insurance plans, high emergency medical coverage limits, and options for different types of travellers.

With up to $10 million in emergency medical coverage and specialized coverage for eligible travellers with pre-existing medical conditions through its TravelEase® plans, Manulife offers comprehensive coverage options for travellers with different needs. The 24/7 emergency assistance, TravelAid mobile app, and top-up options also offer beneficial support to Canadians visiting different countries.

For a detailed comparison of the best travel insurance plans, check out our list of the Best travel insurance companies in Canada

Our advisor’s take on Manulife travel insurance

At PolicyAdvisor, we recently helped a 45-year-old Canadian planning several international vacations over the next year. They wanted a travel insurance plan that would provide comprehensive emergency medical protection while also covering trip cancellations, baggage issues, and travel delays. Since they were planning multiple trips, they were seeking a plan that offered flexibility and value.

The client profile

  • Age: 45 years old
  • Purpose of travel: Multiple international leisure trips throughout the year
  • Primary concern: Comprehensive coverage for medical emergencies and travel disruptions under one policy
  • Coverage needed: Multi-trip All-Inclusive plan with 30-day coverage per trip

Why we recommend Manulife travel insurance

We recommended the plan because it includes:

  • Up to $10 million emergency medical coverage for eligible unexpected illnesses and injuries while travelling
  • Comprehensive protection for trip cancellations, interruption benefits, baggage loss or delay, and travel accidents
  • 24/7 emergency travel assistance through the Manulife Assistance Centre and TravelAid app
  • Optional top-up coverage for trips exceeding the selected maximum trip duration

How to purchase Manulife travel insurance in Canada?

PolicyAdvisor’s licensed advisors can help you compare Manulife travel insurance plans based on your travel destination, trip duration, age, health history, and coverage needs. Our advisors can help you compare plans from leading travel insurance providers and choose a plan that best fits your travel needs.

Whether you are heading abroad for a vacation or planning multiple trips throughout the year, our advisors at PolicyAdvisor can guide you through Manulife’s coverage options and policy limits to help you purchase the right travel insurance.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

Does Manulife travel insurance cover pre-existing medical conditions?

Yes, some Manulife CoverMe travel insurance plans cover eligible stable pre-existing medical conditions if you meet the applicable stability requirements. Travellers with certain pre-existing medical conditions may also qualify for coverage through Manulife’s TravelEase® for Pre-Existing Conditions plan.

Does Manulife travel insurance cover trip cancellation?

Yes, trip cancellation coverage is available through Manulife’s Trip Cancellation & Trip Interruption and All-Inclusive plans. Benefits are payable if you cancel or interrupt your trip for a covered reason as per the policy.

How much travel medical coverage does Manulife provide?

Coverage limits vary by plan. Depending on the policy you purchase, Manulife offers emergency travel medical coverage of up to $10 million for eligible medical emergencies while travelling.

Does Manulife travel insurance cover baggage loss or delays?

Yes, but only under plans that include travel benefits, such as the All-Inclusive and Non-Medical Inclusive plans.

Does Manulife offer Cancel for Any Reason (CFAR) coverage?

Yes. Manulife offers an optional Cancel for Any Reason (CFAR) Rider with eligible Single-Trip All-Inclusive, Trip Cancellation & Trip Interruption, and Non-Medical Inclusive plans. The rider reimburses up to 50% of your eligible non-refundable prepaid trip costs if you cancel for a reason that is not otherwise covered by the policy.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Secure Travel (RIMI) Travel Insurance Review (2026)

Secure Travel (RIMI) travel insurance provides comprehensive emergency medical coverage for Canadians travelling outside their home province or territory. With up to $7 million in emergency medical benefits, flexible single-trip and multi-trip plans, and 24/7 emergency assistance, it helps protect travellers against unexpected medical expenses, hospital stays, emergency transportation, and other covered travel emergencies.

Quick review: Secure Travel (RIMI) travel insurance:

  • PolicyAdvisor rating: 5/5
  • Best for: High emergency medical coverage
  • Skip if: You are 60 to 79 years old and need emergency medical coverage for trips longer than 60 days
Planning a trip soon?

Get a free travel insurance quote now!

What is Secure Travel (RIMI) travel insurance?

Secure Travel Insurance is an emergency medical policy designed for eligible Canadian residents travelling outside their home province or territory. The policy is underwritten by certain Lloyd’s Underwriters through a Lloyd’s Approved Coverholder and is offered under the Canuck Voyage Travel Medical Insurance plan. 

It is available as a single-trip or multi-trip annual plan, with top-up coverage for additional days of protection. Secure Travel focuses exclusively on emergency medical insurance and does not include trip cancellation or trip interruption coverage.

Key features of Secure Travel’s Canuck Voyage Travel Medical Insurance

Plan name RIMI Canuck Voyage Travel Medical Insurance
Plan type Single-trip or annual-trip
Minimum eligibility age  15 days
Maximum eligibility age Under 80 years of age
Pre-existing coverage (stability period)
  • Under age 60 (trips up to 60 days): 30 days
  • Under age 60 (trips over 60 days): 90 days
  • Ages 60-74: 90 days
  • Ages 75-79: 180 days
Maximum coverage in emergency medical $7,000,000
Optional coverage Top-up coverage for additional days of the trip
Waiting period
  • No waiting period if purchased before departure
  • 48-hour waiting period for sickness if purchased after leaving your home province or territory
Policy extensions
  • Travel delay: Up to 5 additional days
  • Medically unfit to travel: Up to 5 additional days
  • Hospitalization: Coverage extends for the entire hospital stay, plus 5 days after discharge
Underwritten by Certain Lloyd’s Underwriters through a Lloyd’s Approved Coverholder
Claims administered by  Intrepid 24/7™

Who is eligible for Secure Travel Canuck Voyage Insurance?

To be eligible for Secure Travel’s emergency travel insurance plan, you must be:

  • A Canadian resident covered by your government health insurance plan for the entire duration of your trip
  • Purchase coverage for the entire duration of your trip
  • At least 15 days of age and less than 80 years of age
  • Travelling for no more than 60 days (for those aged 60 to 79 years)

Who is not eligible for the Secure Travel Canuck Voyage Insurance?

You are not eligible if you:

  • Have been diagnosed with a terminal illness
  • Are experiencing new or undiagnosed symptoms, or know of any reason to seek medical attention
  • Are travelling to obtain medical treatment outside your province or territory of residence, whether or not recommended by your attending physician
  • Have used, or been prescribed, home oxygen during the 12 months prior to the effective date
  • Have been diagnosed with congestive heart failure
  • Have a diagnosed, unrepaired aneurysm of 4.5 centimetres or more
  • Require assistance with the activities of daily living (dressing, bathing, eating, using the toilet or getting in or out of a bed or chair)

Secure Travel (RIMI) travel insurance plan types

Secure Travel (RIMI) offers the Canuck Voyage Travel Medical Insurance plan for Canadians travelling outside their home province or territory. The plan is available as either a single-trip or multi-trip annual policy, with optional top-up coverage for travellers who need to extend their emergency medical coverage beyond the original policy period.

  • Single-trip plan: Covers one trip outside your home province or territory for the period selected on your policy. Coverage begins on your effective date and ends when you return home, or your policy expires, whichever comes first
  • Multi-trip annual plan: Covers unlimited trips outside your province or territory of residence, up to the maximum trip duration you purchase. It also includes unlimited travel within Canada outside your home province, making it ideal for frequent travellers who take multiple trips throughout the year
  • Top-up coverage: Extends your emergency medical coverage if your trip lasts longer than the number of days covered under your multi-trip annual plan or another eligible travel insurance policy. It must be purchased before your existing coverage expires, and you must not have experienced a change in your health condition
Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

What is covered under Secure Travel’s Canuck Voyage Travel Medical Insurance?

Secure Travel’s Canuck Voyage Travel Medical Insurance provides coverage for eligible emergency medical expenses. Depending on the policy terms and limits, your coverage includes the following benefits:

  • Emergency medical expenses: Covers eligible emergency hospital stays, physician services, emergency outpatient treatment, laboratory tests, X-rays, prescription drugs, private duty nursing, and medically necessary medical appliances
  • Prescription drugs: Reimburses eligible prescription medications required to treat a covered medical emergency, including injectable drugs and sera, when prescribed to treat a covered medical emergency
  • Emergency dental treatment: Covers emergency dental care, including up to $5,000 to repair accidental dental injuries and up to $650 for emergency treatment to relieve dental pain, subject to policy conditions
  • Medical and diagnostic services: Covers treatment by licensed physicians, surgeons, anaesthetists, and registered nurses, along with medically necessary blood products, oxygen therapy, laboratory tests, and physician-ordered X-rays
  • Private duty nursing: Covers medically necessary services of a registered private duty nurse when prescribed by a physician and approved by Intrepid 24/7™ during hospitalization or as an alternative to hospitalization
  • Emergency medical transportation and evacuation: Covers licensed ground and air ambulance services, emergency medical evacuation, repatriation to Canada when medically necessary, transportation between hospitals, and evacuation from remote locations, subject to policy limits and prior approval where required
  • Paramedical services: Covers eligible treatment provided by licensed practitioners, including physiotherapists, chiropractors, osteopaths, podiatrists, chiropodists, acupuncturists, and optometrists
  • Meals and accommodation: Reimburses eligible accommodation, meals, transportation, essential phone and internet charges, and childcare expenses if your return home is delayed due to a covered medical emergency
  • Repatriation of remains: Covers eligible expenses for preparing and returning your remains to Canada or for cremation or burial at the place of death, subject to the policy limits
  • Hospital allowance: Provides a daily hospital allowance for incidental hospital charges and covers eligible expenses incurred while hospitalized during a covered emergency
  • Psychological support: Covers eligible visits to a licensed psychiatrist, psychologist, or social worker for acute symptoms when deemed medically necessary, up to the applicable policy limit
  • Return to your trip destination: Covers up to $5,000 for one-way economy airfare to return you and one travel companion to your original trip destination after you recover and are medically cleared to resume your trip
  • Excess baggage return: Covers up to $1,000 to return your excess baggage if you are medically transported back to Canada

Secure Travel’s Canuck Voyage Travel Medical Insurance coverage details at a glance

Coverage type Maximum coverage offered
Emergency medical expenses Up to $7,000,000
Prescription drugs 30-day supply per prescription (except during hospitalization)
Emergency dental treatment Accidental blow to the face: up to $5,000; dental pain relief: up to $650 (treatment within 48 hrs, completed within 90 days)
Emergency medical transportation and evacuation Ground transportation: Up to $10,000; 

Air transportation: Up to $250,000; Mountain evacuation: Up to $5,000

Paramedical services Up to $500 per insured person, per profession
Meals and accommodation Up to $150 per day, to a maximum of $3,000
Repatriation of remains Up to $15,000 (preparation and transport) or $5,000 for cremation or burial
Hospital allowance Up to $50 per day, to a maximum of $500
Psychological support Up to $5,000
Return to your trip destination Up to $5,000 for one-way economy airfare
Excess baggage return Up to $1,000

What is not covered under Secure Travel’s Canuck Voyage Travel Medical Insurance?

The Canuck Voyage Travel Medical Insurance policy does not cover the following:

  • Medical conditions that do not meet the policy’s pre-existing condition or stability requirements
  • Symptoms ignored after your policy takes effect when a reasonable person would have sought medical attention
  • Non-emergency, elective, or cosmetic treatments
  • New conditions before a top-up or policy extension take effect
  • Travel against a physician’s advice or terminal illness
  • Treatment that can safely wait until you return to Canada
  • Ongoing or routine treatment for chronic conditions
  • Medical treatment without the required prior approval (except in life-threatening emergencies)
  • Alcohol- or drug-related injuries or illnesses
  • Routine pregnancy care, childbirth, and related complications
  • Injury due to involvement in illegal acts, criminal activities, or self-inflicted injuries
  • High-risk activities (e.g., mountain climbing, skydiving, professional sports) resulting in injuries
  • Loss or damage to hearing devices, eyeglasses, sunglasses, contact lenses, or prosthetic teeth, limbs, or devices, and any resulting prescriptions

Pros and cons of Secure Travel Insurance

Pros Cons
Up to $7 million in emergency medical coverage No trip cancellation, interruption, or baggage coverage
Optional top-up coverage for longer trips Not available for travellers 80 years of age or older
Automatic coverage extension for eligible travel delays and hospitalization
Includes additional psychological support benefits

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

How to make a claim under Secure Travel’s travel insurance policy?

If you need to make a claim under your Secure Travel Canuck Voyage Travel Medical Insurance policy, follow these steps:

  • Contact Intrepid 24/7™:  You must contact Intrepid 24/7™ as soon as you experience a medical emergency. If you are admitted to a hospital, you must contact them within 24 hours before any surgery. Failure to do so may reduce your eligible benefits unless it is a life-threatening emergency
  • Complete the claim form: Fill out a separate claim form for each new illness or injury
  • Gather supporting documents: Submit original itemized medical bills, prescription receipts, proof of your departure and return dates, and any additional documents required
  • Provide proof of claim: Send written proof of your claim within 90 days of receiving the covered medical services
  • Complete the authorization form: Sign and return the authorization form so the insurer can coordinate benefits with your provincial or territorial health insurance plan, where applicable
  • Submit your claim request: Send all completed forms and supporting documents to Intrepid 24/7™ for processing

Can you cancel or get a refund on Secure Travel Insurance?

Yes, Secure Travel’s Canuck Voyage Travel Medical Insurance offers refunds in certain situations. The exact refund amount depends on when you cancel your policy and whether you have started your trip or made a claim.

  • Cancel within 10 days: You can receive a full refund if you cancel within 10 days of receiving your policy, provided you have not departed on your trip, no claim has been or will be made, and you notify the insurer in writing within the 10-day period
  • Return home early: You may qualify for a partial refund if you return to your home province, territory, or Canada before your scheduled return date, provided no claim has been made, and the policy is terminated. All insured travellers under the same policy must return together to be eligible
  • Multi-trip annual plans: Refunds or cancellations are available only before the policy’s effective date or if no travel has taken place during the policy period

Please note that a $25 administration fee may apply to partial refunds, and no refund is issued if the refundable amount is less than $20 per policy. Also, all refund requests must be submitted in writing within the policy’s required timeframe.

Does Secure Travel’s travel insurance allow automatic extensions?

Yes, Secure Travel’s Canuck Voyage Travel Medical Insurance automatically extends your emergency medical coverage at no additional premium in certain situations. 

  • Travel delay: Coverage extends for up to 5 days if your return is delayed because of a vehicle or common carrier delay, as long as the delay occurs before your policy expires
  • Medically unfit to travel: Coverage extends for up to 5 days if medical evidence confirms you were unable to travel on or before your policy’s expiry date.
  • Hospitalization: If you are hospitalized when your policy expires, your coverage continues for the entire period of hospitalization, plus an additional 5 days after your discharge

How does Secure Travel compare to other travel insurance providers?

Secure Travel stands out for its high emergency medical coverage of up to $7 million and straightforward emergency travel medical plans. However, unlike many other Canadian travel insurance providers, it does not offer trip cancellation, trip interruption, or baggage coverage. If you are comparing coverage limits, plan features, pricing, and optional benefits, explore our guide to the best travel insurance companies in Canada to find the policy that best suits your travel needs.

Our licensed advisors at PolicyAdvisor can compare coverage, premiums, and policy features from top Canadian insurers to help you find the plan that best fits your trip and budget. Book your free consultation today!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

Does Secure Travel’s travel insurance cover travellers with pre-existing conditions over 60?

Yes, travellers aged 60 to 79 may qualify for coverage if their pre-existing medical conditions have remained stable for the required period before the policy’s effective date. The required stability period is 90 days for ages 60–74 and 180 days for ages 75-79.

Can I extend my Secure Travel policy if my trip is longer than planned?

Yes, you can purchase top-up coverage to extend your emergency medical protection. This is applicable if your trip exceeds the number of days covered by your multi-trip annual plan or another eligible travel insurance policy. The top-up must be purchased before your existing coverage expires, and your health condition must remain unchanged.

Does Secure Travel insurance cover emergency dental treatment?

Yes, Secure Travel covers emergency dental treatment, including up to $5,000 for accidental dental injuries and up to $650 for emergency treatment to relieve dental pain, subject to the policy’s terms and limits.

What is the waiting period for Secure Travel’s Canuck Voyage travel medical insurance?

It depends on when you purchase your policy. There is no waiting period if you buy your coverage before leaving your home province or territory. If you purchase it after departure, a 48-hour waiting period applies to sickness claims.

Do I need to contact Intrepid 24/7 before receiving medical treatment?

Yes, you should contact Intrepid 24/7™ immediately if you experience a medical emergency and before receiving medical treatment whenever possible. If you are admitted to a hospital, Intrepid 24/7™ must be notified within 24 hours, and prior approval is required for certain treatments and procedures. Failing to contact Intrepid 24/7™ may reduce your eligible benefits, except in life-threatening emergencies.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

GMS travel insurance review (2026)

Planning a trip outside your home province or Canada is exciting, but unexpected medical emergencies, flight disruptions, or trip cancellations can quickly become expensive. GMS TravelStar travel insurance offers flexible travel insurance plans designed to protect Canadians against emergency medical expenses and travel-related financial losses. 

Whether you are travelling once a year or taking multiple trips throughout the year, GMS offers emergency medical and trip cancellation coverage with customizable deductibles, optional trip delay upgrades, and annual plans for frequent travellers.

Quick review

  • PolicyAdvisor ratings: 4/5
  • Best for: Travellers looking for flexible travel insurance while travelling with family members and children
  • Skip if:  You are seeking comprehensive baggage and Cancel for Any Reason (CFAR) protection while traveling
Planning a trip soon?

Get a free travel insurance quote now!

What is GMS TravelStar travel insurance?

GMS TravelStar travel insurance is a series of policies offered by Group Medical Services (GMS), designed to protect Canadians travelling within Canada or internationally against unexpected medical emergencies and travel-related disruptions.

Depending on the plan selected, coverage can include emergency medical treatment, hospitalization, trip cancellation, and baggage protection. One of the key offerings is the ability to bundle the Emergency Medical Insurance with Trip Cancellation & Interruption Insurance for broader protection. Eligible travellers can also purchase top-up coverage or apply to extend their emergency medical coverage, subject to the policy terms.

GMS TravelStar travel insurance: At a glance

Best for Canadians looking for flexible emergency medical and trip cancellation coverage
Plans available
  • Emergency Medical
  • Trip Cancellation & Interruption
Age Eligibility Single-Trip: No maximum age (medical questionnaire required for travellers over 60).

Multi-Trip Annual: Ages 0–79 (not available for applicants aged 80+)

Maximum emergency medical coverage Up to $5 million
Waiting Period None. Coverage begins on the departure date (or policy effective date for Multi-Trip Annual). 
Trip cancellation & interruption Available as a standalone policy or bundled with Emergency Medical
Trip delay coverage Included with Trip Cancellation & Interruption, with optional Trip Delay Upgrade
Annual plans available Yes
Pre-existing conditions covered Covered only if stable for 180 days before departure (or before the top-up effective date, where applicable).

Types of travel insurance plans offered by GMS travel insurance

GMS TravelStar offers travel insurance solutions for different travel needs, whether you are taking a single vacation or travelling several times throughout the year. Travellers can choose between medical and non-medical plans, with a wide range of benefits.

Unlike many insurers that package everything into one all-inclusive policy, GMS separates the medical and non-medical coverage. This offers travellers the flexibility to purchase only the protection they need or combine policies for broader coverage that includes emergency medical coverage alongside trip interruption, baggage, travel delay, and other non-medical benefits.

Here’s an overview of the different GMS travel insurance plans:

Emergency medical plans

Emergency medical plans are designed for travellers who want protection against unexpected medical emergencies while away from home. Depending on your travel frequency and medical history, GMS offers two plans to choose from:

  • Single-Trip Emergency Medical
  • Multi-Trip Annual Emergency Medical

Here’s a quick comparison of the emergency medical plans offered by GMS travel insurance:

Feature Single-Trip Emergency Medical Multi-Trip Annual Emergency Medical
Emergency medical coverage Up to $5 million Up to $5 million per trip
Best for One vacation or extended trip Frequent travellers
Eligible age No maximum age (medical questionnaire required for travellers over 60) Under age 80 (medical questionnaire required for travellers over 60)
Trip duration Up to 365 days Unlimited trips with 15-day or 30-day options
Emergency Dental Services
  • Up to $2,000 for dental treatment
  • Up to $250 for pain relief
  • Up to $2000 for dental treatment
  • Up to $250 for pain relief
Health Practitioners Up to $300 for each emergency service Up to $300 for each emergency service
Private Duty Nursing Up to $5,000 Up to $5,000
Air Ambulance Up to $20,000  Up to $20,000 
Return of Remains Up to $7,000 Up to $7,000
Deductible options $0, $250, $1,000, $5,000 $0, $250, $1,000, $5,000
Top-up coverage Available Available
Virtual healthcare services Included Included
Travel assistance 24/7 multilingual assistance 24/7 multilingual assistance
Family coverage Add up to six children under age 16 at no additional cost Not available

Trip Cancellation & Interruption plan

Travellers who want protection for prepaid travel expenses can purchase GMS TravelStar Trip Cancellation & Interruption Insurance. This plan reimburses eligible expenses if your trip is cancelled, interrupted, delayed, or your baggage is lost, damaged, or delayed due to a covered event.

The plan is available as a Single-Trip policy. A Multi-Trip Annual option is also available when purchased with a GMS Multi-Trip Annual Emergency Medical plan.

Here’s a quick overview of the Trip Cancellation & Interruption plan offered by GMS travel insurance:

Feature Trip Cancellation & Interruption
Trip interruption coverage Up to $10,000
Trip cancellation coverage Up to the insured trip value (Single-Trip) or the selected annual option (Multi-Trip Annual)
Trip delay Included
Baggage loss, damage & delay Up to $1,500 per trip ($500 per item)
Eligible age No maximum age
Available plans Single-Trip and Multi-Trip Annual
Emergency medical Not included
Trip cancellation benefits
  • Prepaid transportation
  • Prepaid travel arrangements
  • Cancellation penalties
  • Difference between double and single occupancy 
Trip interruption benefits
  • Return transportation home
  • Unused prepaid travel arrangements
  • Transportation to rejoin your trip
  • Up to $3,000 for return of remains or local burial/cremation 
Optional rider Trip Delay Upgrade (available for an additional premium)

Additionally, applicants can purchase a Trip Delay upgrade rider for an additional premium that increases their coverage for eligible travel delays lasting 12 hours or longer. 

Here are the benefits offered by the rider:

Benefit Coverage
Out-of-pocket expenses Up to $500 per day (maximum $1,500) for accommodations, meals, essential telephone calls, Wi-Fi service fees, and taxi or rideshare costs
Event tickets Up to $200 for ticketed events such as concerts, sporting events, or movies
Rejoin transportation Covers the additional cost of same-class transportation to rejoin your tour, group, or trip

Bundling your GMS travel insurance coverage

GMS does not offer a traditional all-inclusive travel insurance plan. However, travellers can achieve similar protection by combining the Emergency Medical Insurance and Trip Cancellation & Interruption Insurance plans into a single policy. 

Purchasing both plans together provides coverage for medical emergencies and travel-related financial losses while allowing eligible travellers to save 10% on Trip Cancellation & Interruption Insurance. This option suits travellers seeking both emergency medical and trip-related protection without paying for benefits they do not need.

While the All-Inclusive and Annual All-Inclusive plans support international travel, the All-Inclusive Canada plan is designed only for travel within Canada.

GMS Travel insurance flexible plans and savings
Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

Pros and Cons of GMS TravelStar Travel Insurance

Pros:
✓Eligible plans provide up to $5 million in emergency medical coverage with four deductible options to help manage premiums
✓Offers 24/7 multilingual travel assistance and access to virtual healthcare services
✓Families can add up to six children under age 16 at no additional cost on eligible Single-Trip Emergency Medical plans
✓10% savings when bundling Emergency Medical with Trip Cancellation & Interruption coverage
Cons:
✗Coverage for pre-existing medical conditions must meet an 180-day stability requirement for all ages
✗No traditional all-inclusive travel insurance plan; medical and non-medical coverage must be purchased separately
✗The optional Trip Delay Upgrade must be purchased separately as an add-on

Does GMS offer family travel insurance?

Yes, GMS TravelStar offers family coverage on eligible travel insurance plans for Canadians. The insurer offers several family-friendly features that can help reduce insurance costs for parents travelling with children. Eligible travellers purchasing a Single-Trip Emergency Medical plan can add up to six dependent children under the age of 16 to the policy at no additional cost.

Additionally, families travelling with a spouse or dependents under the same policy may qualify for a 5% savings on eligible coverage. Together, these family-friendly features make GMS a practical option for families looking to protect their trips while keeping insurance costs manageable.

Who is eligible for GMS TravelStar travel insurance?

Any Canadian resident with active provincial or territorial health insurance who is travelling outside their home province or outside Canada and who meets GMS’s requirements is eligible for these travel insurance plans. However, coverage eligibility, age restrictions, medical stability requirements, and policy exclusions vary by plan and chosen riders.

Here’s an overview of the general eligibility requirements for the GMS travel insurance plans:

Plan Eligibility requirements
Emergency Medical (Single-Trip & Multi-Trip Annual)
  • Purchase the policy before departing on your trip (unless buying an eligible top-up).
  • Meet GMS medical eligibility requirements.
  • For Multi-Trip Annual plans, be under 80 years of age at the time of application.
Emergency Medical Top-up (Non-GMS policy)
  • Apply before your contracted departure date.
  • Purchase coverage for all additional days not covered by your existing policy.
Emergency Medical Top-up (GMS policy)
  • Apply at least two business days before your current GMS policy expires.
  • Have no claims during your trip or required medical treatment during your trip.
  • Purchase coverage for all additional travel days.
Trip Cancellation & Interruption
  • Purchase the policy before your departure date.
  • Travel to a destination without an active Government of Canada “Avoid non-essential travel” or “Avoid all travel” advisory at the time of purchase.
  • Insure a trip valued at no more than $20,000 per person.
  • Multi-Trip Annual plans must be purchased with a GMS Multi-Trip Annual Emergency Medical plan.

Note: Refer to the policy wording for the full list of eligibility requirements.

Who is not eligible for GMS travel insurance?

While the plans cover eligible travellers, certain health and travel restrictions may prevent applicants from obtaining coverage under GMS travel insurance. 

You are not eligible for GMS travel insurance under the following circumstances:

Emergency Medical coverage

  • Are not a Canadian resident with a valid provincial or territorial government health plan.
  • Are awaiting tests or treatment for a heart condition
  • Have a surgically untreated vascular aneurysm, an implantable cardioverter defibrillator (ICD), or have been diagnosed with congestive heart failure (CHF)
  • Have had certain heart, vascular, liver, or other serious medical conditions diagnosed or treated within the last 12 months
  • Have insulin-treated diabetes and also take prescription medication for a heart condition (excluding cholesterol or blood pressure medication)
  • Use home oxygen or oral steroids for a lung condition
  • Are currently being treated for cancer (except certain hormone-treated breast or prostate cancers) or have undergone valve surgery, kidney dialysis, or an organ, stem cell, or bone marrow transplant within the last 12 months
  • Are aged 70 or older and require assistance with activities of daily living (ADLs)

Trip Cancellation & Interruption coverage

  • Travel to a destination with an active Government of Canada “Avoid non-essential travel” or “Avoid all travel” advisory when you buy the policy
  • Have a trip value exceeding $20,000 per person
  • Purchase a Single-Trip Trip Cancellation plan for a trip valued at $12,000 or more per person while having certain serious medical conditions or recent treatments

How much does GMS travel insurance cost?

The cost of GMS travel insurance depends on your plan, duration, and the riders you select with your policy. 

Here’s a sample travel insurance premium for a traveller on a trip for 15 days:

Age Coverage amount Multi-trip plan 

(15 days per trip)

Trip Interruption and Cancellation Plan 

(Trip cost $2,000)

25 $5,000,000.00 $76.00 $103.68
35 $78.00 $104.76
45 $78.00 $104.76
55 $103.00 $106.92
65 $266.00 – $556.00* $125.28
75 $598.00 – $1,047.00* $209.52

Disclaimer: Illustrative premiums for multi-trip annual Emergency Medical plans ($5 million coverage) and a Trip Cancellation & Trip Interruption plan (based on a $2,000 trip cost). Actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

Are there any exclusions or limitations to GMS travel insurance? 

While GMS TravelStar provides comprehensive emergency medical and trip cancellation coverage, certain situations like medical tourism and high-risk activities are excluded or limited under the policy.

Here’s an overview of some of the common exclusions and limitations of GMS TravelStar travel insurance

Exclusion category What you need to know
Pre-existing medical conditions Conditions that do not meet the applicable stability requirements may not be covered
Non-emergency treatment Routine, elective, cosmetic, or experimental treatments are excluded
Medical tourism Treatment or travel primarily intended to receive medical care is not covered
Alcohol and drug use Claims arising from alcohol or drug misuse are not covered
Failure to follow medical advice Failure to seek appropriate medical treatment or follow prescribed medical advice may result in reduced or denied benefits
High-risk activities Injuries resulting from excluded hazardous sports or activities may not be covered
Pregnancy and childbirth Routine pregnancy care and childbirth-related expenses are generally excluded, except where specifically covered
Government travel advisories Coverage may be limited for destinations subject to certain Government of Canada travel advisories
Illegal or intentional acts Claims arising from criminal acts or intentional self-inflicted injuries are excluded
Policy extension limitations Coverage cannot be extended for a medical condition that began before the approved extension takes effect.
Non-common carrier air travel No coverage or reimbursement for expenses resulting from air travel unless riding as a passenger on a common carrier.
Unapproved treatment No coverage for medical treatment prohibited by the provincial laws of residence or the federal laws of Canada

Note: This list summarizes the most common exclusions found across GMS travel insurance plans. Coverage varies by plan and policy wording, so it is recommended to refer to your policy for the complete list of exclusions, limitations, and definitions.

How to file a claim with GMS TravelStar travel insurance?

If you experience a medical emergency or another covered loss during your trip, contact GMS Travel Assistance as soon as possible to begin the claims process.

Here’s how you can file a claim with GMS during your trip:

  • Call the assistance centre immediately: You can contact the assistance centre in Canada and the United States at 1-800-459-6604, and internationally at 905-762-5196. Failure to contact Travel Assistance within 24 hours may reduce benefits to the lesser of 70% of eligible expenses or $50,000.
  • Submit a notice of claim: Once you have contacted GMS Travel Assistance, you must provide written notice of claim within 30 days. 
  • Gather supporting documentation: You will need to provide medical records, proof of treatment expenses (including itemized bills and payment receipts), and travel documents such as your passport, visa, or airline ticket. 
  • Submit proof of claim: Submit all claim documentation within 90 days of the illness or injury.

Can you cancel or get a refund on GMS travel insurance?

Yes, GMS TravelStar travel insurance allows policy cancellations and refunds under certain circumstances. Refund eligibility and amount depend on the type of policy purchased, whether coverage has started, and whether a claim has been made.

Here is the GMS travel insurance refund policy at a glance:

Situation Refund Eligibility and fees
Within the 10-day free look period 100% premium refund if you cancel within 10 days of purchase, have not departed, and no claim is in progress. Only for Single-Trip plans greater than 190 days and all Multi-Trip Annual plans with emergency medical coverage.
After the effective date No premium refund after coverage takes effect
Return home early (eligible Emergency Medical plans) May qualify for a partial refund of unused coverage if no claim has been made and no assistance services were provided
Trip Cancellation & Interruption plans The policy is generally non-refundable. However, if the premium exceeds $20, you may qualify for a refund if your travel supplier cancels the trip or changes the travel dates and waives all cancellation penalties.
Claim submitted or paid No refund is available once a claim has been submitted or paid

Note: Refer to the policy wording for the complete refunds terms, conditions, and eligibility requirements.

Can you extend GMS travel insurance coverage?

If your trip lasts longer than originally planned, you may be able to extend or top up your GMS emergency medical coverage before your policy expires. However, extensions are subject to approval and must meet all necessary eligibility requirements.

Here’s what you need to know about extending your GMS emergency medical travel insurance:

  • You can extend your Single-Trip plan while travelling by purchasing additional coverage at least two business days before your policy expires.
  • Extensions are only available if you have not made a claim or required medical treatment during your trip.
  • You must purchase coverage for all additional travel days beyond your original policy period.

As for Multi-trip Annual and Trip Cancellation & Interruption plans, coverage cannot be extended. However, GMS offers automatic extension of all plans under certain situations. Coverage may automatically extend if your common carrier is delayed, you are hospitalized on your expiry date, or a covered medical emergency prevents you from returning home as scheduled, subject to policy limits.

How does GMS compare to other travel insurance providers?

While many of Canada’s leading travel insurers offer similar emergency medical and trip cancellation coverage, GMS TravelStar stands out for its flexibility, high emergency medical limits, and family-friendly benefits. 

With up to $5 million in emergency medical coverage, annual multi-trip options, and free coverage for up to six children under eligible plans, GMS provides a well-rounded solution for travellers and families travelling together. The ability to bundle medical and non-medical plans alongside a 10% saving makes it attractive for travellers seeking well-rounded coverage solutions.

For a detailed comparison of the best travel insurance plans, check out our list of the Best travel insurance companies in Canada.

Our advisor’s take on GMS travel insurance

At PolicyAdvisor, we recently assisted a 62-year-old retiree planning a three-week vacation to Spain. They were seeking comprehensive travel insurance that would cover emergency medical expenses while also protecting the cost of prepaid flights, hotels, and guided tours.

Client profile

  • Age: 62 years
  • Destination: Spain
  • Trip length: 21 days
  • Primary concern: Paying out of pocket for emergency medical care and non-refundable travel bookings

Why we recommend GMS TravelStar travel insurance

We recommended this plan because it offers:

  • Up to $5 million in emergency medical coverage on eligible plans 
  • A 10% savings when both plans (Emergency Medical and Trip Cancellation & Interruption) are purchased together in a bundle
  • Multiple deductible options to help tailor coverage and premiums
  • Coverage for trip delays and an optional Trip Delay Upgrade for additional out-of-pocket expenses

How to purchase GMS travel insurance in Canada

PolicyAdvisor’s licensed travel insurance advisors can help you compare GMS travel insurance plans with other leading Canadian insurers based on your destination, trip duration, age, medical history, and coverage needs.

Whether you are heading abroad for a vacation or planning multiple trips throughout the year, our advisors at PolicyAdvisor can guide you through GMS coverage options, bundle solutions, and other add-ons and riders you may need.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

Does GMS travel insurance cover pre-existing medical conditions?

Yes, some GMS travel insurance plans may cover stable pre-existing medical conditions, provided you meet the applicable eligibility and 180-day stability requirements.

Does GMS travel insurance cover trip cancellation?

Yes. GMS offers Trip Cancellation & Interruption Insurance as a standalone plan. It can also be purchased alongside an Emergency Medical plan for broader travel protection. Benefits are payable if you cancel or interrupt your trip for a covered reason, subject to the policy terms.

How much travel medical coverage does GMS travel insurance provide?

Coverage limits vary by plan. Depending on the policy you purchase, GMS offers emergency travel medical coverage of up to $5 million for eligible medical emergencies while travelling.

Does GMS travel insurance cover baggage loss or delays?

Yes, but only under plans that include travel benefits, such as the TravelStar Trip Cancellation & Interruption, or as part of a bundle with the Emergency medical plan.

Does GMS TravelStar travel insurance offer Cancel for Any Reason (CFAR) coverage?

No, GMS travel insurance plans do not offer Cancel for Any Reason (CFAR) coverage as a benefit or rider.

Does GMS offer annual travel insurance?

Yes, GMS offers Multi-Trip Annual Emergency Medical plans that provide unlimited trips during the policy year, with coverage options of up to 15 or 30 days per trip.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Allianz travel insurance review (2026)

Allianz travel insurance offers flexible coverage for occasional and frequent travellers through its single-trip and annual multi-trip plans. Depending on the plan you choose, Allianz provides up to $10M in emergency medical coverage, trip cancellation and interruption protection, baggage coverage, and other travel benefits. With five single-trip plans and two annual multi-trip plans, Allianz offers coverage options tailored to different travel needs and budgets.

Quick review: Allianz travel insurance

  • PolicyAdvisor ratings: 5/5
  • Best for: High medical emergency coverage up to $10M
  • Skip if: You have a complex heart condition or recent cardiac treatment, as eligibility and coverage are subject to specific heart-related requirements
Planning a trip soon?

Get a free Allianz travel insurance quote now!

What is Allianz travel insurance?

Allianz Travel Insurance Canada offers a range of travel insurance plans that protect travellers against unexpected events before and during their trip. Travellers can choose from travel insurance plans that provide comprehensive protection or focus on specific needs, such as emergency medical expenses, non-medical travel disruptions, or multi-trip coverage for frequent travel.

Key features of Allianz travel insurance

Plan types
  • Single-trip: Comprehensive, Youth, Emergency Medical, Trip Cancellation & Interruption, Non-medical
  • Multi-trip: Comprehensive and Annual Emergency Medical
Minimum eligibility age 
  • Minimum age: 15 days (for all plans)
  • Maximum age: Youth Plan, up to 29 years; and all other plans: maximum age subject to insurer eligibility requirements
Pre-existing coverage Yes, subject to plan, eligibility, and stability requirements:

  • Age 64 or younger: 90-day stability
  • Age 65 or older: 150-day stability
Maximum coverage in trip interruption Up to the sum insured
Maximum coverage in emergency medical Up to $10 million (Comprehensive, Emergency Medical, Annual Emergency Medical); Up to $1 million (Youth Plan) 
Waiting period None, if purchased before departure
Automatic extensions
  • Medically unfit to travel: 5 days
  • Transportation delay: 72 hours (where applicable)
Administered by  Allianz Global Assistance
Underwritten by CUMIS General Insurance Company

Allianz travel insurane

Who is eligible for Allianz travel insurance?

Eligibility requirements vary depending on the Allianz travel insurance plan you choose. Generally, travellers must meet the insurer’s eligibility requirements, which may include:

  • Be at least 15 days old on the effective date of your policy
  • Be a Canadian resident covered under a Canadian government health insurance plan throughout your coverage period
  • You have not been advised by a physician to avoid travel during your planned trip
  • Not travelling for the purpose of receiving medical treatment or alternative therapy
  • Not require assistance with activities of daily living, if you are age 65 or older on the effective date

Types of Allianz travel insurance plans

Allianz offers two main types of travel insurance plans: single-trip plans for one specific journey and annual (multi-trip) plans for travellers who take two or more trips throughout the year. Within these plan types, you can choose from different options based on the level of coverage you need, including trip cancellation and interruption, emergency medical coverage, baggage protection, and travel delay benefits.

1. Single trip

Single-trip travel insurance covers one specific journey from your departure date until you return home. Allianz offers five single-trip plans: Comprehensive travel insurance, Youth travel insurance, Emergency medical travel insurance, Trip Cancellation & Interruption, and Non-medical travel insurance, allowing travellers to choose a plan based on their budget and coverage needs.

  • Comprehensive travel insurance: A comprehensive travel insurance plan provides all-in-one protection for a single trip, including emergency medical coverage, trip cancellation and interruption, travel delays, baggage loss or delay, and other travel-related benefits. It is best suited for travellers who want broad financial protection against a wide range of unexpected travel disruptions
  • Youth travel insurance: A travel insurance plan designed for travellers aged 29 and under that offers affordable protection for a single trip. It also lets you insure up to four eligible travellers under one policy, making it a cost-effective option for friends or young families travelling together
  • Emergency medical travel insurance: A travel insurance plan that covers eligible emergency medical expenses if you become sick or injured while travelling. It is best suited for travellers who already have trip cancellation coverage or only need protection against unexpected medical emergencies during their trip
  • Non-medical travel insurance: A travel insurance plan that protects you against non-medical travel disruptions, including trip cancellation and interruption, travel delays, and lost, stolen, or delayed baggage. It is best suited for travellers who already have emergency medical coverage and only need protection for unexpected travel-related expenses
  • Trip Cancellation & Interruption: A travel insurance plan to cover eligible expenses related to trip cancellation and interruption. It has almost the same coverage as non-medical travel insurance, except that it does not include coverage for baggage loss or delay and accidental death and dismemberment 

2. Annual/multi-trip plans

Annual or multi-trip plans cover multiple trips throughout the year, making them ideal for frequent leisure or business travellers. Allianz offers two annual multi-trip plans with different levels of protection depending on your travel needs.

  • Annual comprehensive travel insurance: This plan helps you save money if you travel two or more times a year by providing emergency medical coverage, trip cancellation and interruption, baggage protection, travel delay coverage, and other travel-related benefits. Travellers can choose between 15-day or 35-day per-trip coverage, with the option to extend the coverage for longer trips if needed
  • Annual emergency medical travel insurance: An annual multi-trip travel insurance plan that provides emergency medical coverage for unlimited trips within a 12-month policy period. Travellers can choose between 4-day, 8-day, 15-day, or 35-day emergency multi-trip plan
Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

What is covered under Allianz travel insurance?

Here is a list of things that are typically covered under Allianz travel insurance Canada, depending on the plan you choose:

  • Trip cancellation and trip interruption: Reimburses eligible prepaid, non-refundable trip expenses if you need to cancel or cut your trip short due to a covered reason, such as illness, injury, or certain unforeseen events. The maximum coverage is up to the sum insured
  • Emergency medical and dental expenses: Covers eligible emergency medical treatment and urgent dental care if you become sick or injured while travelling, up to the plan’s coverage limit. The maximum emergency medical is up to $10M on most plans (up to $1 million under the Youth Plan), and emergency dental coverage goes up to $5,000, depending on the plan type.
  • Emergency medical transportation and evacuation: Pays for medically necessary transportation to the nearest appropriate medical facility or emergency evacuation when required due to a covered medical emergency.
  • Baggage loss and delays: Reimburses the cost to repair or replace lost, stolen, or damaged baggage and covers the purchase of essential items if your baggage is delayed for a covered period. The maximum coverage for baggage loss is up to $1,000
  • Travel delays: Covers eligible additional expenses, such as meals, accommodation, and transportation, when your trip is delayed, or you miss a connection because of a covered reason
  • Pre-existing medical conditions coverage: Allianz travel insurance plans cover pre-existing medical conditions if the plan’s eligibility requirements and policy conditions are met

Allianz single-trip travel insurance plan coverage at a glance

Features Comprehensive plan Youth plan Emergency medical plan Trip Cancellation & Interruption Non-medical plan
Emergency medical Up to $10,000,000 Up to $1000,000 Up to $10,000,000 Not included Not included
Emergency dental Up to $5,000 Up to $5,000 Up to $5,000 Not included Not included
Emergency medical transportation Included Included Included Not included Not included
Paramedical practitioners Up to $500 per profession Up to $500 per profession Up to $500 per profession Not included Not included
Return of vehicle/watercraft Up to $5,000 $Up to 5,000 Up to $5,000 Not included Not included
Pet return Up to $500 Up to $500 Up to $500 Not included Not included
Trip cancellation Up to the sum insured Up to the sum insured Not included Up to the sum insured Up to the sum insured
Trip interruption Unlimited Unlimited Not included Up to the sum insured Up to the sum insured
Travel delay Up to $350 per day (maximum of $1,500) Up to $350 per day (maximum of $1,500) Not included Up to $350 per day (up to a maximum of $1,500) $350 per day up to a maximum of $1,500
Baggage loss Up to $1,000 Up to $1,000 Not included Not included Up to $1,000
Baggage delay Up to $400 Up to $400 Not included Not included Up to $400
Travel accident Up to $100,000 Up to $100,000 Not included Not included Up to $100,000

Allianz multi-trip travel insurance plan coverage at a glance

Features Comprehensive plan Emergency medical plan
Trip duration (per trip) 15 or 35 days 4, 8, 15, or 35 days
Age limits No age limit No age limit
Emergency medical Up to $10,000,000 Up to $10,000,000
Dental Up to $5,000 Up to $5,000
Emergency medical transportation Included Included
Return of Vehicle/Watercraft Up to $5,000 Up to $5,000
Pet return Up to $500 Up to $500
Trip cancellation Up to the sum insured Not included
Trip interruption Up to the sum insured Not included
Travel delay Up to $350 per day (maximum $1,500); 3-hour minimum delay Not included
Baggage loss Up to $1,000 Not included
Baggage delay Up to $400 Not included
Travel accident Up to $100,000 Not included

What is not covered under Allianz travel insurance?

Coverage exclusions vary depending on the Allianz travel insurance plan you purchase. Some common exclusions include:

  • Pre-existing medical conditions that do not meet the plan’s eligibility requirements
  • Medical treatment is sought outside Canada if you are travelling primarily to receive medical treatment or alternative therapy.
  • Claims arising from high-risk or hazardous activities unless specifically covered
  • Intentional self-inflicted injuries or illegal acts
  • Expenses that exceed the policy’s coverage limits or are otherwise excluded under the policy terms and conditions

Pros and cons of Allianz travel insurance Canada

Pros Cons
Offers five single-trip and two annual multi-trip plans for different travel needs Trip cancellation is not included in every plan, such as Emergency Medical 
Provides up to the maximum sum insured in trip interruption coverage and up to $10,000,000 in emergency medical coverage, depending on the plan type Youth travel insurance is only available to travellers aged 29 and under, and with a lower emergency medical limit
Includes coverage for eligible pre-existing medical conditions Some benefits, such as travel delay, baggage, and travel accident coverage, are only available on select plans
Broad age eligibility on most plans, subject to insurer eligibility requirements. (except for the Youth plan)
Allyz TravelSmart app that lets travellers manage their files and track insurance claims

How much does Allianz travel insurance cost?

The premiums with pre-existing condition coverage start at $135.90 for a 25-year-old traveller and increase with age, as shown below. Allianz travel insurance costs vary based on factors such as your age, destination, trip duration, coverage amount, and the plan you choose.

Allianz travel insurance cost (2026):

Age (in years) Single-trip Annual Multi-trip plan (15 days per trip) Trip Cancellation and Interruption Plan (Trip cost $2000)
25 $135.90 $135.49 $150.84
35 $135.90 $135.49 $150.84
45 $156.81 $135.49 $150.84
55 $227.00 $169.37 $165.34
65 $308.46 $202.27 $201.25

Disclaimer: Illustrative rates for single-trip, multi-trip, and trip cancellation and interruption. Actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

How to claim Allianz travel insurance?

You can file an Allianz travel insurance Canada claim online through the secure claims portal. Here are the steps you need to file an Allianz travel insurance claim:

  • Notify Allianz as soon as possible: If you have a medical emergency while travelling, contact Allianz’s emergency assistance team before receiving treatment whenever possible. For non-medical claims, begin the claims process promptly after the covered event
  • Access the online claims portal: Create an account or sign in to the online Claims Portal to start a new claim
  • Complete the claim form: Provide your policy details, trip information, and a description of the incident. Ensure all information is accurate to avoid processing delays and upload supporting documents
  • Track your claim status: Use the Allyz TravelSmart app to monitor your claim, upload additional documents if requested, and view updates throughout the review process.
  • Receive your claim decision and payment: Once your claim has been assessed, Allianz will issue an Explanation of Benefits outlining the decision. If your claim is approved, any eligible payments will be made by Allianz

Can you cancel or get a refund on Allianz travel insurance?

Yes, Allianz allows you to cancel your travel insurance policy, but the refund you receive depends on when you cancel and whether you have travelled or filed a claim.

  • Within 10 days of purchase: You can receive a full premium refund if you cancel your policy within 10 days of purchase, provided you have not started your trip and have not experienced an event that could result in a claim
  • More than 10 days after purchase: You may be eligible for a partial premium refund if you have not departed on your trip and have not submitted a claim under the policy
  • No refund for unused trip days: If you end your trip early, Allianz does not provide partial refunds for the unused portion of your coverage

Please note that refunds of less than $20 are not issued.

Does Allianz travel insurance allow automatic extensions? 

Yes, Allianz Travel Insurance automatically extends your coverage at no additional premium if your trip is delayed due to a covered reason.

Automatic extensions are available if:

  • You or your travelling companion is medically unfit to travel due to a covered illness or injury. For plans with emergency medical coverage, your policy is extended until you are fit to travel, plus up to an additional 5 days to allow you to return home.
  • Your travel is delayed by up to 72 hours because your travel carrier is delayed, or your vehicle is involved in a traffic accident or mechanical breakdown
  • You temporarily return to your home province or territory during your coverage period without your policy expiring. However, expenses for the temporary return are your responsibility, and no premium refund is available
  • Trip Interruption coverage also extends until you are fit to travel, plus up to 5 additional days, or for up to 72 hours if your return is delayed due to covered transportation issues

How does Allianz travel insurance compare to travel insurance providers?

Allianz stands out for its five single-trip and two annual-trip plans, offering flexible coverage for occasional, frequent, and business travellers. Compared with Destination Canada, Allianz provides a higher emergency medical coverage limit of up to $10 million, while Destination Canada offers up to $5 million. Most of the plans that Allianz offers have higher age limits, making them suitable for older travellers. To help you make an informed decision, compare Allianz with other top providers in our guide to the best travel insurance companies in Canada.

Our advisor’s take on Allianz travel insurance

At PolicyAdvisor, we help travellers compare travel insurance plans based on their destination, trip duration, medical needs, and budget. We recently helped a 42-year-old Canadian who was going on a trip to Europe and was looking primarily for high emergency medical coverage.

Client profile:

  • Age: 42-year-old Canadian
  • Trip duration and type: Three-week vacation to Europe
  • Primary concern: Comprehensive emergency medical coverage 
  • Our comparison: After comparing travel insurance plans from multiple providers, we recommended Allianz Comprehensive single-trip insurance because it offered emergency medical coverage of up to $10M along with trip cancellation and interruption benefits, baggage protection, and travel delay coverage 

Why we recommended Allianz:

Beyond the high emergency medical coverage, here’s why the Allianz travel insurance Canada plan stood out:

  • Comprehensive protection: Maximum coverage up to the sum insured for trip cancellation and trip interruption coverage, along with travel delay and travel accident benefits
  • Emergency medical transportation: Emergency medical transportation is covered, which means that coverage will be provided for transportation to the nearest appropriate medical facility, if required
  • Global reach: Allianz has a presence in 70+ countries and access to a global network of more than 1 million medical providers, helping you receive assistance and access medical care almost anywhere you travel

If you are still not sure, speak with a licensed expert at PolicyAdvisor to compare Allianz with other leading providers. Our advisors will help you find the plan that offers the right coverage, benefits, and price for your travel needs. Schedule a call now!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Does Allianz travel insurance Canada cover pre-existing medical conditions?

Yes, Allianz travel insurance plans cover eligible pre-existing medical conditions, provided you meet the policy’s eligibility requirements and stability conditions. If you are under 65 years old, your pre-existing medical condition must generally be stable for 90 days before departure, while travellers 65 and older must meet a 150-day stability period to qualify for eligible coverage.

What does Allianz travel insurance cover?

Depending on the plan you choose, Allianz travel insurance Canada may cover trip cancellation and interruption, emergency medical and dental expenses, emergency medical transportation, baggage loss or delays, travel delays, travel accidents, epidemic-related covered losses, and eligible pre-existing medical conditions.

How do I file an Allianz travel insurance claim?

You can submit a claim online through Allianz’s Claims Portal by providing your policy details, completing the claim form, and uploading supporting documents such as receipts, medical reports, or proof of travel. You can also track your claim status through the portal.

Does Allianz travel insurance Canada cover trip cancellations?

Yes, Allianz travel insurance covers trip cancellations, but only under select plans. Trip cancellation coverage is included with the Comprehensive, Youth, Non-medical, Trip Cancellation & Interruption, and Annual Comprehensive travel insurance plans, and, where eligible, cancellation costs are covered up to the sum insured.

Does Allianz travel insurance include emergency medical coverage?

Yes, Allianz travel insurance includes emergency medical coverage under most of its plans. The Comprehensive, Emergency Medical, Annual Comprehensive, and Annual Emergency Medical plans provide up to $10M in eligible emergency medical coverage, while the Youth Plan provides up to $1 million.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Destination Canada travel insurance review (2026)

Destination Canada’s travel insurance offers two plans tailored to different travel needs: the Leisure Plan for Canadians travelling outside their home province or internationally, and the Expat Essential Plan for Canadians living or working abroad. The Leisure Plan provides up to $5 million in emergency medical coverage and is available as both single-trip and annual multi-trip plans, while the Expat Essential Plan offers up to $1 million in emergency medical coverage.

Quick review

  • PolicyAdvisor ratings: 4/5
  • Best for: Travellers who want strong emergency medical coverage with up to $5 million in benefits, plus an option for Canadians living or working abroad 
  • Skip if: You need coverage beyond medical emergencies, such as trip cancellation or baggage
Planning a trip soon?

Get a free Destination Canada travel insurance quote now!

What is Destination Canada travel insurance?

Destination Canada travel insurance is an emergency medical travel insurance plan that helps protect Canadians against unexpected medical expenses while travelling. The policy covers eligible emergency medical expenses caused by sudden illnesses or injuries, including hospitalization, physician services, emergency medical transportation, prescription medications, and medical evacuation. 

Travellers also receive access to 24/7 Zurich Assistance, which helps coordinate emergency medical treatment, hospital admissions, emergency evacuations, and claims administration worldwide.

Key features of Destination Canada travel insurance:

Plan types
  • Leisure
  • Expat Essential
Minimum entry age 15 days old for both plans
Maximum entry age
  • Leisure: Under 80 years
  • Expat Essential: Under 65 years
Maximum emergency medical coverage
  • Leisure: Up to $5 million
  • Expat Essential: Up to $1 million
Pre-existing condition stability period
  • Leisure: Age 59 and under: 90-day stability period; Age 60-79: 180-day stability period
  • Expat Essential: 180-day stability period before the effective date, with additional stability requirements that may apply after coverage begins
Waiting period
  • No waiting period for policies purchased before departure. 
  • A 48-hour waiting period may apply if coverage is purchased after departure or after an existing policy expires.
Maximum coverage duration
  • Leisure: Up to 365 consecutive days
  • Expat Essential: Up to 52 consecutive weeks
Automatic policy extensions
  • Travel delay: Up to 72 hours
  • Medical emergency: Up to 5 days
  • Hospitalization: Until discharge and up to 72 hours after discharge (subject to policy terms)
Underwritten by Zurich Insurance Company Ltd (Canadian Branch)
Claims administered by Global Excel Management, operating as Zurich Assistance
Managed by The Destination: Travel Group Inc.

Destination Canada Travel Insurance

Who is eligible for Destination Canada travel insurance?

To be eligible for Destination Canada travel insurance, you must be:

  • Age eligibility depends on the plan selected: Leisure (15 days to under 80 years) or Expat Essential (15 days to under 65 years)
  • Covered by your provincial or territorial Government Health Insurance Plan (GHIP) for the entire duration of your trip
  • Medically fit to travel and not travel against a physician’s advice

Who is not eligible for Destination Canada travel insurance?

You may not be eligible for Destination Canada travel insurance if you:

  • Have been diagnosed with a terminal illness
  • Have been diagnosed with or treated for pancreatic, liver, bone, or metastatic cancer
  • Have used or been prescribed home oxygen within the past 12 months
  • Have undergone a major organ, bone marrow, or stem cell transplant
  • Have kidney disease requiring dialysis 
  • Have an unrepaired aneurysm measuring 4 cm or larger
  • Have been advised by a physician not to travel

Types of Destination Canada travel insurance plans

Destination Canada offers its travel insurance for Canadians through the Leisure Plan and Expat Essential Plan. Both plans provide almost the same coverage, except that the maximum limits can differ. 

Leisure Plan

It is available for Canadian residents travelling outside their home province or internationally for vacations, business trips, or other temporary travel. Offered as single-trip and annual multi-trip coverage, it provides up to $5 million in emergency medical coverage.

Expat Essential

This plan is available for Canadians living, working, or studying abroad who require long-term emergency medical coverage outside Canada. It provides up to $1 million in emergency medical coverage and includes hospitalization, outpatient physician services, prescription drugs, ambulance transportation, emergency medical evacuation, home nursing, emergency dental treatment, and more.

Travel insurance can be affordable!

Find the best travel insurance rates to stay protected on your upcoming trips!

What is covered under Destination Canada travel insurance?

Here’s what will be broadly covered under Destination Canada travel insurance:

  • Emergency medical expenses: Covers eligible emergency medical treatment if you become unexpectedly sick or injured while travelling outside your home province or Canada
  • Emergency medical transportation and evacuation: Covers medically necessary transportation to the nearest appropriate medical facility or, when medically necessary and approved, transportation back to Canada
  • Emergency dental treatment: Covers eligible emergency dental expenses to relieve acute pain or repair accidental damage to natural teeth, subject to your plan’s terms and limits
  • Meals and accommodation: Covers eligible meals and accommodation expenses when a covered medical emergency results in an unexpected delay or requires additional travel arrangements, subject to your plan’s limits.
  • Hospital allowance: Reimburses eligible incidental expenses, such as telephone calls and television rentals, if you are hospitalized for 48 hours or more due to a covered medical emergency. This is not included in the Expat Essential Plan
  • Paramedical practitioner services: Covers eligible outpatient treatment provided by licensed paramedical practitioners, such as chiropractors, physiotherapists, osteopaths, and podiatrists, up to the limits specified under your plan
  • Emergency return home: This provides coverage for economy transportation back to your home province or territory if a covered medical emergency requires you to end your trip early

In the table below, we have provided a closer look at the coverage amount offered under Destination Canada travel insurance.

Destination Canada travel insurance coverage details:

Features Leisure Expat Essential
Emergency medical expenses Up to $5,000,000 per insured Up to $1,000,000 per injury or sickness
Emergency hospital Eligible hospital accommodation up to the sum insured Semi-private hospital accommodation up to the sum insured
Private duty nurse Private duty nurse up to $5,000 Nursing at home for up to 12 weeks, maximum $10,000
Paramedical practitioner Up to $350 per practitioner for outpatient

treatment

Up to $500 per profession, per injury or sickness
Drugs or medications 30-day supply up to $1,000 Included under Outpatient Services (combined maximum $10,000 per sickness or injury)
Dental emergencies Accidental dental injury up to $3,000; emergency dental pain up to $500 Accidental dental injury up to $5,000 
Meals and accommodation Up to $150 per day to a maximum of $1,500 –
Hospital accommodation Up to sum insured (semi-private / private) Semi-private accommodation
Hospital allowance Up to $50/day to a max of $250 –
Emergency evacuation/repatriation Up to $5,000 (Eligible expense when medically necessary and approved) Evacuation 80% up to $25,000; repatriation / local burial $10,000
Compassionate emergency travel / Bedside companion Bedside companion: Up to $150 per day to a maximum of $1,500 Round-trip economy airfare plus meals & accommodation up to $150/day, maximum $3,000
Complicated maternity
Up to $5,000

What is not covered under Destination Canada travel insurance?

Here are some of the exclusions of Destination Canada travel insurance:

  • Unstable pre-existing medical conditions
  • Non-emergency medical treatment or elective procedures
  • Travelling against medical advice
  • Injury due to high-risk or hazardous activities
  • Alcohol or drug-related incidents
  • Self-inflicted injuries or injuries sustained while committing a criminal offence, acts of war, or military service (subject to policy terms)
  • Any rehabilitation or convalescent care

Pros and cons of Destination Canada travel insurance

Pros Cons
Offers two travel insurance plans: Leisure for short-term travellers and Expat Essential for Canadians living or working abroad Does not include trip cancellation or trip interruption benefits
Up to $5 million in emergency medical coverage under the Leisure Plan Expat Essential has a lower $1 million coverage limit
Covers eligible pre-existing medical conditions, subject to the applicable stability period Requires continuous provincial GHIP coverage throughout your trip
Covers a wide range of emergency medical benefits, including hospitalization, medical evacuation, emergency transportation, and dental emergencies Hospital allowance is available only under the Leisure Plan, not the Expat Essential Plan
Provides 24/7 Zurich Assistance for emergency medical coordination and claims support worldwide

How much does Destination Canada travel insurance cost?

The cost of Destination Canada travel insurance ranges from $116.10 to $240.60. The exact premium depends on factors such as your age, destination, trip duration, coverage amount, chosen plan type, and more.

Destination Canada travel insurance cost (2026):

Age (in years) Leisure Plan: Single-trip Leisure Plan: Multi-trip (16-day trip)
25 $116.10 $113.00
35 $116.10 $113.00
45 $136.20 $124.00
55 $153.60 $121.00
65 $240.60 $226.00

Disclaimer: Illustrative rates for a non-smoking traveller, the actual premiums may vary based on age, destination, trip duration, health, deductible, and other factors.

How much does Travel Insurance cost?

Get instant quotes from Canada's top travel insurance providers and find the perfect coverage for your trip.

$100K
✓ $0 Deductible
--
✓ $250 Deductible
--
✓ $500 Deductible
--

How to make a claim with Destination Canada travel insurance?

If you experience a medical emergency while travelling, seek medical attention immediately. For hospitalizations or other serious emergencies, you or someone acting on your behalf should contact Zurich Assistance within 24 hours of hospital admission. 

To file a claim, follow these steps:

  • Seek emergency medical care and visit the nearest hospital or medical facility if you require immediate treatment
  • Contact Zurich Assistance as soon as possible, as the team will coordinate your medical care and advise you on the next steps
  • Keep all supporting documents and submit your claim along with the completed claim form to Zurich Assistance
  • Cooperate with the claims process by providing any additional information or documentation requested by the claims administrator, and track the claim status

Please note that if you don’t contact Zurich Assistance before seeking medical treatment without a reasonable cause, you will be responsible for 20% of the eligible medical expenses that would otherwise be covered under your policy.

Documents required for the claim process

  • A completed claim form
  • Original itemized medical bills and invoices
  • Proof of payment for all claimed expenses
  • Proof of payment from any other insurance or benefit plan, if applicable
  • Medical records, including the physician’s diagnosis, hospital records, and confirmation that treatment couldn’t safely be delayed until you returned home
  • A referral letter from the attending physician, if specialist treatment was recommended
  • Proof of the accident for claims involving accidental dental treatment
  • Proof of travel, such as your itinerary, boarding passes, or travel tickets

Can you cancel or get a refund on Destination Canada travel insurance?

Yes, Destination Canada travel insurance allows policy cancellations and premium refunds in certain situations. A full refund is available if you cancel your policy within 10 days of purchase, as long as your coverage has not started.

Refund scenario Leisure Plan Expat Essential Plan
10-day free look period Full refund if cancelled within 10 days of purchase, provided coverage has not started
Trip cancelled before departure Eligible for a full refund if the trip is cancelled before the policy’s effective date
Early return from your trip A partial refund may be available for the unused portion of your coverage
Annual Multi-Trip Plan cancellation Can be cancelled before the policy’s effective date only Not applicable
Administration fee $25 deducted from eligible refunds
Minimum refund amount $15 $50
Refund after a claim Not available if a claim has been incurred, paid, or is pending
Deadline to request a refund Refund requests must generally be submitted within 90 days after the policy expires Refer to the policy terms for applicable refund conditions*

Does Destination Canada travel insurance allow automatic extensions?

Yes, Destination Canada travel insurance automatically extends your coverage in certain situations when circumstances beyond your control prevent you from returning home as planned.

Coverage is automatically extended in the following situations:

  • Travel delays: Your coverage is automatically extended for up to 72 hours if your scheduled airline, train, bus, ferry, or other mode of transportation is delayed for reasons beyond your control, provided the delay occurs before your policy expires
  • Medical emergency: If you are medically unfit to travel because of a covered illness or injury on or before your policy’s expiry date, your coverage is automatically extended for up to 5 days.
  • Hospitalization: If you are hospitalized due to a covered medical emergency when your policy expires, your coverage continues for the duration of your hospital stay and for 72 hours after you are discharged to allow you to return home. This extension also applies to one insured travelling companion who remains with you if necessary

How does Destination Canada compare to other travel insurance providers?

Destination Canada focuses primarily on emergency medical protection, making it a strong option for travellers who want high medical coverage and emergency assistance. With separate plans for short-term travellers and Canadians living or working abroad, it offers flexibility for different travel needs while also covering eligible pre-existing medical conditions. 

However, unlike some travel insurance providers, these plans do not include benefits such as trip cancellation, trip interruption, baggage protection, or flight delay coverage. Before purchasing, it is worth comparing its benefits, exclusions, and premiums with other best travel insurance companies in Canada to ensure you are getting the protection that best fits your destination and travel plans.

Our advisor’s take on Destination Canada travel insurance

At PolicyAdvisor, we help travellers compare travel insurance plans based on their destination, trip duration, age, medical history, and budget. We recently helped a 58-year-old Canadian planning a one-month trip to the United States who wanted comprehensive emergency medical coverage while ensuring their stable pre-existing medical condition would be covered.

Client profile:

  • Age: 58-year-old Canadian
  • Trip duration and type: One-month vacation to the United States
  • Primary concern: High emergency medical coverage with protection for a stable pre-existing medical condition
  • Our comparison: After comparing several travel insurance providers, we recommended Destination Canada’s Leisure Plan because it aligned well with the traveller’s priorities. It offered up to $5 million in emergency medical coverage, coverage for eligible pre-existing conditions that met the required stability period, and valuable travel assistance benefits at a competitive premium

Why we recommended Destination Canada:

Beyond its high emergency medical coverage, here’s what made Destination Canada stand out:

  • Coverage for stable pre-existing conditions: Eligible pre-existing medical conditions are covered if they meet the required 90-day (ages 59 and under) or 180-day (ages 60-79) stability period before departure
  • Strong travel assistance benefits: Includes emergency return home, meals and accommodation, hospital allowance, vehicle return, pet return, search and rescue, and 24/7 Zurich Assistance to coordinate medical care and emergency support while travelling

How to buy Destination Canada travel insurance with PolicyAdvisor?

Choosing the right travel insurance depends on factors such as your destination, trip length, age, existing medical conditions, and the level of coverage you need. A licensed PolicyAdvisor advisor can compare Destination Canada with other leading travel insurance providers to help you select the most suitable plan.

With PolicyAdvisor, you can:

  • Compare Destination Canada with multiple Canadian travel insurance providers
  • Find the most suitable coverage based on your destination, travel duration, and medical history
  • Get guidance on pre-existing medical condition eligibility and stability requirements

Book a free consultation with a licensed PolicyAdvisor advisor to compare quotes and find the travel insurance plan that best fits your needs. Schedule a call now!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

What travel insurance plans does Destination Canada offer?

Destination Canada offers two travel insurance plans: the Leisure Plan and the Expat Essential Plan. The Leisure Plan is designed for Canadians travelling outside their home province or internationally, while the Expat Essential Plan is intended for Canadians living or working abroad who need long-term emergency medical coverage.

Does Destination Canada travel insurance cover pre-existing medical conditions?

Yes, both the Leisure Plan and Expat Essential Plan cover eligible pre-existing medical conditions, provided they meet the required stability period. The Leisure Plan requires a 90-day or 180-day stability period, depending on your age, while the Expat Essential Plan requires a 180-day stability period before the effective date, subject to policy terms.

Who underwrites Destination Canada travel insurance?

Destination Canada travel insurance is underwritten by Zurich Insurance Company Ltd. (Canadian Branch). Emergency assistance and claims are administered by Global Excel Management, operating as Zurich Assistance.

Does Destination Canada travel insurance cover trip cancellation?

No, Destination Canada travel insurance does not cover trip cancellation. It is primarily an emergency medical travel insurance policy. Hence, travellers looking for those benefits may need to purchase a separate travel insurance policy with a different insurer. 

Does Destination Canada travel insurance include emergency medical evacuation?

Yes, both plans offered by Destination Canada include emergency medical evacuation when it is medically necessary and approved. Coverage includes transportation to the nearest appropriate medical facility and, when medically required, repatriation in accordance with the policy terms.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */