 1-888-601-9980

Disability insurance in Canada typically costs more as you get older, earn a higher income, or work in an occupation with greater disability risk. Your premiums also depend on the coverage amount, waiting period, benefit period, and policy features. With Statistics Canada reporting that 8 million Canadians aged 15 and older, or 27% of the population, had at least one disability, understanding these cost factors can help you choose coverage that fits your budget and income needs.
What is disability insurance and how does it work?
Disability insurance in Canada is a type of insurance that replaces part of your income if you are unable to work due to an illness, injury, or disability. There are two main types of disability insurance you should know about: short-term disability and long-term disability coverage. The two are not mutually exclusive, as long-term disability insurance usually follows short-term coverage.
- Short-term disability insurance: This policy temporarily (typically 17-26 weeks) covers the loss of income due to accident or illness.
- Long-term disability insurance: This provides protection from loss of income for longer-lasting health problems. Long-term disability insurance begins after the short-term coverage period ends and continues for an extended period or until age 65
Disability insurance works in a simple manner in which you receive 60%-70% of your pre-disability income. The payouts will happen only if you have met the policy’s disability definitions. You also need to complete the waiting period, or elimination period, submit a claim, and provide medical evidence before benefits begin. The disability insurance payments will continue as long as you remain eligible under the policy’s terms.
What is the cost of disability insurance?
The cost of disability insurance varies based on several factors, including your age, occupation, coverage amount, waiting period, and benefit period. The sections below explain how each factor affects your premiums while you are buying disability insurance in Canada.
Cost of disability insurance by occupation
The disability insurance cost for a 35-year-old male non-smoker in good health: a $5,000 monthly benefit costs $83.83 for a doctor and $191.45 for a truck driver, while a $3,000 monthly benefit starts at $50.30 per month for a doctor and $143 for a truck driver, with a 90-day waiting period and coverage until age 65. The lower the risk of workplace injuries, illness, and the ability to return to work, the lower the disability insurance premiums will be.
Monthly premiums by occupation class:
| Class | Occupation example | $5000 monthly benefit premium | $3000 monthly benefit premium |
| 4A | Doctor | $83.83/month | $50.30/month |
| 3A | Office administrator | $112.35/month | $67.41/month |
| 2A | Nurse (Clinical nurses) | $148.93/month | $89.36/month |
| B | Retail Managers, Cashiers | $177.32/month | $106.39/month |
| B | Truck driver | $191.45/month | $143.59/month |
*Illustrative cost for a 35-year-old male, non-smoker, in good health, with a $5000 and $3000 monthly benefit, 90-day waiting period, and coverage to age 65.
Cost of disability insurance premiums by age
The disability insurance premium for a male non-smoker in good health with a 90-day waiting period and coverage until age 65, a $5000 monthly benefit, costs $57.71 at age 25, rising to $224.57 at age 55. Premiums generally increase with age because the risk of illness or disability rises. On the other hand, the same profile but with a monthly benefit of $3000 will cost $34.62 for a 25-year-old and $134.74 for a 55-year-old male non-smoker.
Monthly premiums for $5,000 and $10,000 benefits by age (90-day waiting period):
| Age (in years) | $5000 monthly benefit | $3000 monthly benefit |
| 25 | $57.71/month | $34.62/month |
| 35 | $83.83/month | $50.30/month |
| 45 | $134.97/month | $80.98/month |
| 55 | $224.57/month | $134.74/month |
* Illustrative cost for a 35-year-old male (4A), non-smoker, in good health, with coverage to age 65 and a 90-day waiting period.
Cost of disability insurance premiums by waiting period
The monthly disability insurance premiums for a $5,000 benefit range from $68.86 to $268.10 with a 60-day waiting period, $57.71 to $224.57 with a 90-day waiting period, and $55.96 to $217.83 with a 120-day waiting period, depending on age. A longer waiting period usually lowers your premium, but it also means you need more savings to cover the gap before benefits start.
Monthly premiums for $5,000 benefit by waiting period:
| Age (in years) | 60-day waiting period | 90-day waiting period | 120-day waiting period |
| 25 | $68.86/month | $57.71/month | $55.96/month |
| 35 | $104.04/month | $83.83/month | $81.33/month |
| 45 | $164.06/month | $134.97/month | $130.94/month |
| 55 | $268.10/month | $224.57/month | $217.83/month |
* Illustrative cost for a 35-year-old male (4A), non-smoker, in good health, with a $5,000 monthly benefit and coverage to age 65.
Cost of disability insurance by benefit period
The disability insurance costs for a $3,000 monthly benefit range from $25.99 to $48.80 per month for males and $43 to $80.72 per month for females, depending on the benefit period. For a 35-year-old accountant in occupation class 4A, a policy that pays benefits for two years costs less than one that provides coverage until age 65.
Cost of disability insurance by benefit period:
| Benefit period | Male | Female |
| 2 years | $25.99/month | $43/month |
| 5 years | $35.28/month | $58.41/month |
| To age 65 | $48.80/month | $80.72/month |
*Illustrative premium estimates for a 35-year-old accountant in occupation class 4A with a $3,000 monthly benefit.
How do insurance companies decide disability insurance premiums?
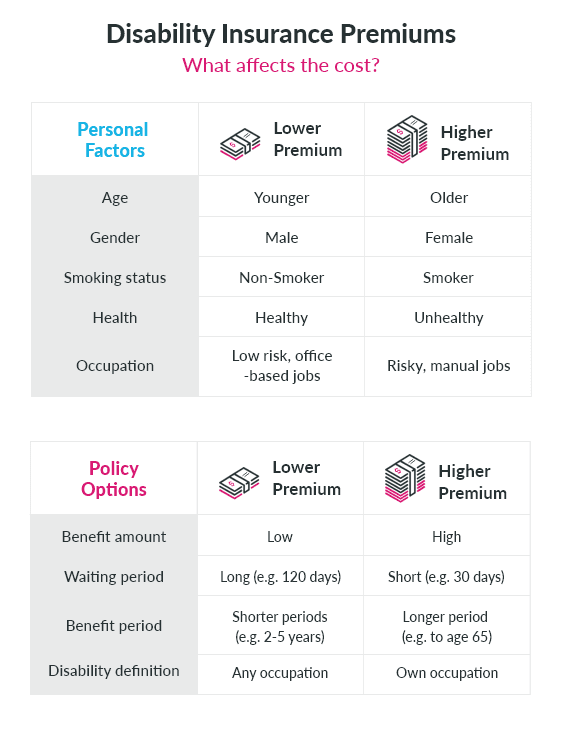
For an individual disability insurance policy, the cost of premiums varies depending on several factors, such as age, gender, health, smoking status, and occupation. On the other hand, there are policy factors such as waiting period, benefit amount, policy type, definition of disability, and riders that affect the disability costs.
Personal factors:
- Age: Age is one of the strongest factors affecting disability insurance cost. Younger applicants usually pay less because they are seen as lower risk, while premiums rise as you get older
- Gender: Gender can also influence pricing, and in some cases, women may pay slightly more than men due to higher life expectancy
- Occupation and risk class: Your line of work has a direct impact on your disability insurance premiums. Office-based professionals are usually charged lower rates. However, physically demanding or high-risk jobs, such as trades, healthcare, or manual labour, tend to pay higher premiums because insurers see them as more likely to file a claim
- Health and lifestyle: Your personal health history and lifestyle habits heavily influence premiums. Smokers, individuals with chronic illnesses, or those engaging in high-risk hobbies such as rock climbing usually pay more. Applicants with a clean medical record and healthy habits are rewarded with lower premiums
Policy factors:
- Definition of disability: Your policy’s definition of disability affects the disability insurance costs. Own-occupation coverage costs more than any-occupation because it offers broader protection
- Waiting period: Also known as the elimination period, this is the time between when you become disabled and when benefits start. Shorter elimination periods, like 30 days, increase premiums, while longer ones, such as 90 or 120 days, reduce them because you are taking on more initial financial risk
- Benefit amount: The amount of income you choose to insure also shapes the cost. Disability insurance typically covers 60 to 70 percent of your pre-tax income. This means higher-income earners, or anyone opting for a larger monthly benefit, will face higher premiums compared to those insuring a modest amount
- Benefit period: The benefit period refers to how long your policy will pay out if you become disabled. A shorter period, such as two to five years, results in lower premiums. However, a policy that pays until age 65 provides stronger protection but comes at a significantly higher cost
- Riders and add-ons: Optional features known as riders can make your policy more robust but also raise costs. Popular add-ons include cost-of-living adjustments, own-occupation coverage, and future purchase options. While these improve protection, they also increase monthly premiums
- Type of policy: The type of plan you choose also matters. Employer-provided group coverage is often more affordable and may even be subsidized by your company. In contrast, individual policies give you more flexibility and customization but generally come with higher premiums
How much does short-term disability insurance cost per month?
The cost of an STD insurance policy is highly dependent on your salary. Because disability insurance pays out a portion (between 50% and 100%) of your income, premium costs vary significantly. Among the cheapest options for short-term disability insurance are injury-only policies (which exclude illnesses) that can start around $10/month. However, it will truly depend on what your employer offers; your work may have set up a specific group rate with the insurance provider. For private policies, it’s best to get an individual quote based on your income replacement needs.
How much does long-term disability insurance cost per month?
Long-term disability premiums tend to range between 1% and 3% of your income, making it one of the most affordable and effective insurance products for income protection.
Thus, a person making $40,000 (before taxes) can buy a long-term disability insurance policy for a monthly benefit of $2,500 per month for as little as $24/month (2-year benefit period) or $43 per month (coverage to age 65). At $100,000, premiums will be upwards of $80/month. In short, the higher the monthly benefit, the higher the premiums will be.
How much of your income does disability insurance cover?
The amount of income you receive while unable to work depends on your disability insurance policy, coverage period, and eligibility for government benefits.
- Short-term disability insurance: Replaces part of your income for 6 to 26 weeks, although some policies provide benefits for up to 52 weeks
- Long-term disability insurance: Usually replaces 60%-70% of your income after short-term disability insurance ends and the policy’s waiting period is satisfied
- Employment Insurance (EI) sickness benefits: This provides benefits for up to 26 weeks, with a maximum of $729 per week in 2026. This may provide sufficient short-term support for some people earning less than $30,000 annually, but higher earners may need supplemental coverage
- Canada Pension Plan (CPP) disability benefits: Eligible individuals under age 65 with a qualifying long-term disability and sufficient CPP contributions may receive monthly benefits. The maximum monthly amount in 2026 is $1,741.20, although the amount received depends on individual eligibility and contributions
If your employer or government benefits do not provide enough income replacement, you can supplement them with an individual policy. This lets you choose coverage based on your income, financial obligations, and budget.
Is a disability insurance benefit paid monthly?
Yes, unlike critical illness insurance, which pays out a one-time lump sum, disability insurance issues monthly payments. This is because the benefit payments replace your regular income even if you are not able to work. The idea is that monthly disability payments will ensure stability and enable you and your family to maintain your cost of living prior to losing the ability to work.
How does the cost of disability insurance differ in various Canadian provinces?
The base cost of disability insurance stays fairly consistent even if you move from Alberta to Ontario or any other province in Canada. Even if you change the province, the premiums will still be primarily determined by factors such as your age, occupation, health, income, coverage amount, and policy features rather than your province of residence. However, premiums and available plans may vary between insurers, and provincial regulations can affect certain policy terms.
Does age affect disability insurance premiums in Canada?
Yes, age has a direct impact on disability insurance premiums in Canada. Insurers view younger applicants as lower risk because they are generally healthier and less likely to file a claim. As a result, someone in their late 20s or early 30s will usually pay much lower premiums compared to someone in their 40s or 50s for the same coverage.
Premiums typically rise as you get older, especially after age 40, since the chances of developing a disability increase with age. For example, a healthy 30-year-old professional might pay around $83 per month for a $5000 benefit amount, while a 45-year-old in the same occupation could pay $134 or more for similar protection. Applying earlier not only locks in lower premiums but also makes approval easier, since health issues that come with age can further increase costs or limit coverage options.
How can you save on disability insurance premiums in Canada?
At PolicyAdvisor, we focus on the coverage you genuinely need rather than choosing a policy based on price alone. Our licensed advisors help clients balance monthly premiums with the financial protection they would need if an illness or injury prevented them from working. Here are the strategies we recommend to keep disability insurance costs lower:
- Choose a longer waiting period: We suggest considering a 90-day or 120-day waiting period if you have enough emergency savings to cover your expenses before benefits begin. These options cost less than policies with shorter waiting periods
- Be selective with riders and add-ons: We recommend prioritizing riders that address your risk and enhance policy coverage. For example, an own-occupation extender rider may be particularly valuable for professionals whose income depends on performing specialized duties, while a future insurability option may help if you expect your income to grow
- Apply while you are younger and healthy: We suggest exploring coverage early, when you may qualify for lower premiums and have fewer health-related underwriting concerns. Waiting until you develop a medical condition could make coverage more expensive or limit your options.
- Choose a benefit amount that matches your needs: We recommend calculating your essential monthly expenses, existing employer benefits, savings, and other income sources before deciding how much coverage to buy. This helps you avoid paying for more coverage than you need while ensuring you can manage essential expenses if you become disabled
- Compare quotes from multiple insurers: We encourage you to look beyond premiums and compare policy definitions, exclusions, benefit periods, and available riders. At PolicyAdvisor, we will help you explore options from 30+ insurers to find coverage that suits your circumstances and budget
How to get the best disability insurance quotes in Canada?
If you want the best disability insurance quotes in Canada, the first step is to compare options from different providers to find coverage that fits your financial needs.
PolicyAdvisor makes this simple by partnering with Canada’s leading disability insurance companies, giving you access to a wide selection of competitive plans all in one place.
With just a few quick questions online, you can get personalized disability insurance quotes in Canada. Once you have found the right plan, our licensed experts provide proper advice and ongoing support, so you fully understand your policy and remain protected over the long term.
Schedule a call with us today to safeguard your income against life’s uncertainties!
Frequently asked questions
What happens if I stop paying premiums?
If you stop paying your disability insurance premiums, your coverage will lapse, and you will no longer be protected. This means you won’t receive benefits if you become disabled in the future. In most cases, insurers allow a short grace period for missed payments, but if you don’t resume payments in time, the policy is cancelled. Reapplying later may require medical underwriting and could result in higher premiums or exclusions, especially if your health has changed since your original application.
How much does disability insurance cost for a 4A occupation class?
Disability insurance premiums for a 4A occupation class, which typically includes physicians and other low-risk professionals, depend on age, health, benefit amount, and policy features. For example, a 35-year-old male non-smoker in good health may pay around $83.83 per month for a $5,000 monthly benefit, with a 90-day waiting period and coverage until age 65.
Is disability insurance tax-deductible in Canada?
In most cases, disability insurance premiums are not tax-deductible in Canada if you pay them personally. The benefit is that any income you receive from a personally paid policy is usually tax-free. However, if your employer pays the premiums for group disability insurance, the benefits you receive are considered taxable income.
Can I get disability insurance after a health issue diagnosis?
Yes, it’s still possible to get disability insurance after being diagnosed with a health issue, but your options may be limited. Insurers may charge higher premiums, exclude coverage for your specific condition, or offer reduced benefit amounts.
The outcome depends on the type and severity of the diagnosis, your treatment history, and overall health. If traditional policies aren’t available, simplified or guaranteed issue disability insurance may be an option, though they often come with higher costs and limited coverage.
Is disability insurance worth the cost in Canada?
Disability insurance can be worthwhile if you rely on your employment income to cover your mortgage, household expenses, debts, or dependants’ needs. Government benefits and employer plans may not replace your full income. An individual policy can help fill the gap, depending on your existing coverage, savings, and financial obligations.
At what age should I buy disability insurance?
It is worth considering disability insurance early in your career, particularly once you depend on your income to meet financial obligations. Younger applicants may qualify for lower premiums, provided they meet the insurer’s underwriting requirements. Buying coverage while you are healthy may also reduce the risk of medical conditions limiting your options later.