 1-888-601-9980
Sun Life offers a wide range of whole life insurance options for Canadians seeking lifelong coverage alongside value-added benefits. Its lineup includes the non-participating SunSpectrum Permanent Life II and two participating policies, Sun Par Protector II and Sun Par Accumulator II.
SunSpectrum Permanent Life II offers a guaranteed death benefit and guaranteed cash values without policy dividends. Meanwhile, Sun Par Protector II and Sun Par Accumulator II are two participating whole life policies that provide lifelong coverage for you and your beneficiaries while building cash value over time.
Quick review
- PolicyAdvisor ratings: 4.5/5
- Best for: Canadian individuals and business owners looking for participating whole life coverage with flexible dividend options
- Skip if: You want participating whole life coverage below $50,000
Sun Par Accumulator II
SunSpectrum Permanent Life II
15-pay
20-pay
Life Pay
About Sun Life
Sun Life Financial is one of Canada’s largest financial services companies, founded in 1865. The insurer has been offering life insurance in Canada since 1871, with a long history of participating whole life policies with dividends every year since 1877. As of 2026, Sun Life has maintained a 6.25% Dividend Scale Interest Rate (DSIR) across its participating whole life policies.
Sun Life’s financial strength (As of 2026)
| AM Best Rating | A+ (Superior) |
| Participating account fund size | $24.2 billion |
| LICAT ratio | 157% |
| Dividend scale interest rate (DSIR) | 6.25% |
Here’s why Sun Life stands out in Canada’s whole life market:
- Strengthens long-term performance through global diversification and multi-market earnings stability
- Supports long-term guarantees with exceptional capital strength and a 152% LICAT ratio
- Offers flexibility through multiple par product designs, including estate, accumulation, and multiple premium payment schedules
- Provides scalable planning advantages for affluent and corporate clients seeking tax-efficient wealth transfer and surplus management
See how much whole life insurance coverage you can get
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by

What is Sun Life whole life insurance?
Sun Life whole life insurance is permanent life insurance that offers lifelong coverage as long as premiums are paid. Sun Life’s Sun Par Protector II and Sun Par Accumulator II are participating whole life policies, offering guaranteed cash value and non-guaranteed dividends during the policy period. Meanwhile, the SunSpectrum Permanent Life II is a non-participating permanent insurance policy.
A key strength of Sun Life’s whole life insurance is its Participating Account, which holds approximately $24.2 billion in assets and supports over 400,000 active policies and represents one of the strongest par fund structures in Canada. The policies offer single-life, joint first-to-die, and joint last-to-die options, which provide enhanced flexibility for Canadians.
Key features of Sun Life whole life insurance
| Plan names |
|
| Policy issue age |
|
| Minimum coverage amount |
|
| Coverage options |
|
| Payment options | Sun Par Protector II and Sun Par Accumulator II
SunSpectrum Permanent Life II
|
| Guaranteed cash value | Protector II: typically begins at the end of year 5.
Accumulator II: typically begins at the end of year 1. |
| Dividend options | Paid-up additional insurance, enhanced insurance, annual premium reduction, dividends on deposit, cash payment |
| Premium offset | Available. Uses the policy’s built-up value to help pay future premiums |
| Riders |
|
Who is eligible for Sun Life whole life insurance?
Sun Life whole life insurance is available to applicants who meet the insurer’s eligibility and underwriting requirements. Issue ages and minimum coverage amounts vary by product and payment option.
- Sun Par Protector II: Minimum coverage of $25,000 for ages 0-17 and $50,000 for adults
- Sun Par Accumulator II: Minimum coverage of $250,000.
- SunSpectrum Permanent Life II: Minimum coverage of $25,000 for ages 0-64 and $10,000 for ages 65-85
What is covered under Sun Life whole life insurance?
Sun Par Protector II and Sun Par Accumulator II offer permanent life insurance while building cash value over the years. Beyond this core role of financial protection, the policy offers several valuable features that make it more flexible than many traditional whole life insurance products.
Here are the primary benefits included with Sun Life whole life insurance:
- Guaranteed premiums: Premium payments stay fixed throughout the selected premium-pay period
- Guaranteed cash value: Your policy builds guaranteed cash value over time, which may be accessed while the policy is in force
- Dividend potential (for participating plans): Eligible policies may receive non-guaranteed annual policyholder dividends
- Access to cash value: Policyholders may access available cash through policy loans and eligible withdrawals
- Lifetime coverage: Your policy remains in force for life
- Tax-advantaged death benefit: Beneficiaries receive the death benefit tax-free
- Optional riders: Enhance coverage with riders such as accidental death, child term, disability waiver, or guaranteed insurability
- Flexible payment terms: Choose from life-pay, 10-pay, 20-pay, or life-pay options (depending on the plan)
Types of Sun Life whole life insurance
Sun Life offers both participating and non-participating whole life insurance policies, allowing policyowners to choose between lifelong coverage and greater long-term growth potential.
Here’s an overview of the different plans offered by Sun Life whole life insurance:
SunSpectrum Permanent Life II Insurance: Best for long-term guaranteed coverage
SunSpectrum Permanent Life II is ideal for Canadians who prefer predictable costs and steady value accumulation. It offers guaranteed lifelong coverage and stable premiums, without the variability of dividends. It is Sun Life’s non-participating whole life insurance option.
- Fixed premiums: Payments remain constant throughout your chosen payment period
- Cash value accumulation: Cash value grows at a guaranteed rate, typically starting in year three of coverage
- Coverage range: $25,000 to $25,000,000 for individuals ages 0-64, with a lower minimum coverage amount available from age 65
- Premium payment options: Life-pay, 20-pay, 15-pay, or 10-pay
- Optional riders: Term riders, accidental death, child term, and disability waiver
- Best for: Canadians seeking long-term coverage with guaranteed costs and no exposure to dividend fluctuations
Sun Par Protector II: Best for long-term estate growth
Sun Par Protector II is a participating whole life insurance policy ideal for Canadians who want lifetime protection with conservative, reliable cash value growth. It focuses on building guaranteed coverage and steady long-term value.
- Coverage: $50,000 (adults), $25,000 (children) to $15 million. Premium rates for illustrations over $15 million are subject to reinsurance and underwriting review. Special quotes are available for cases over $25 million.
- Cash value: Typically begins at the end of year 5
- Premium options: Life-pay, 10-pay, or 20-pay
- Dividend options: Paid-up additions, enhanced insurance, annual premium reduction, cash payment, or dividends on deposit
- Optional riders: Accidental death, child term, guaranteed insurability, disability waiver, owner waiver, business value protection
- Best for: Estate planners or families focused on preserving wealth for future generations while maintaining lifelong coverage
Sun Par Accumulator II: Best for early cash access
Sun Par Accumulator II is a participating whole life insurance policy designed for those who want to build cash value early and maintain flexibility. It offers faster accumulation and easier access to funds without sacrificing lifetime protection.
- Coverage: $250,000 to $15 million. Premium rates for illustrations over $15 million are subject to reinsurance and underwriting review. Special quotes are available for cases over $25 million.
- Cash value: Typically begins at the end of year 1
- Premium options: Life-pay, 10-pay, or 20-pay
- Dividend options: Paid-up additions, enhanced insurance, annual premium reduction, cash payment, or dividends on deposit
- Riders available: Accidental death, child term, guaranteed insurability, disability waiver, owner waiver, business value protection
- Best for: Professionals and business owners who want access to policy value sooner, or who plan to use the cash value strategically
These whole life policies can be used to insure a single person or two individuals. For two individuals, such as couples or partners, the following coverage structures are available:
- Joint first-to-die: Pays the death benefit after the death of the first insured
- Joint last-to-die, premiums to second death: Pays the death benefit after the death of the second insured. Premiums continue until the applicable paid-up date
- Joint last-to-die, premiums to first death: Pays the death benefit after the death of the second insured. Premiums end after the first insured dies. Premiums for certain optional benefits may continue.
Here’s a comparison of Sun Par Protector II, Sun Par Accumulator II, and SunSpectrum Permanent Life II whole life insurance policies by Sun Life:
| Category | Sun Par Protector II | Sun Par Accumulator II | SunSpectrum Permanent Life II |
| Ideal for | Wealth transfer or estate planning | Policy flexibility and liquidity | Guaranteed but simpler lifetime coverage |
| Cash value accumulation | Starts accumulating at the end of year 5 | Starts accumulating at the end of year 1 | Guaranteed cash value accumulation can begin as early as year 3 |
| Premium type | Life Pay, 10 Pay, and 20 Pay | Life Pay, 10 Pay, and 20 Pay | Fixed premiums with 4 payment options: Pay to age 100, 20 Pay, 15 Pay, and 10 Pay |
| Coverage amount range | ● $25,000 to $15,000,000 for children aged 0-17
● $50,000 to $15,000,000 for individuals aged 18 and older. Higher coverage up to $25M available, subject to reinsurance and underwriting review |
$250,000 to $25,000,000
Higher coverage up to $25M available, subject to reinsurance and underwriting review |
● $25,000 to $25,000,000 for individuals aged 64 and younger
$10,000 to $25,000,000 for individuals aged 65 and older |
| Dividend options | ● Paid-up additions
● Annual premium reduction ● Cash payment ● Dividends on deposit |
● Paid-up additions
● Annual premium reduction ● Cash payment ● Dividends on deposit |
No dividends |
| Policy loan availability | From $250, up to 100% of the total cash value minus one year’s interest | From $250, up to 100% of the total cash value minus one year’s interest | Available up to net cash value less one year of interest on the guaranteed cash value |
| Payment flexibility | Monthly or annually | Monthly or annually | Monthly or annually |
| Living benefits | ● Withdrawable premium fund (interest subject to taxation)
● Policy loans ● Payment equal to 50% of the basic insurance amount in case of terminal illness in the form of an advanced death benefit |
● Withdrawable premium fund (interest subject to taxation)
● Policy loans ● Payment equal to 50% of the basic insurance amount in case of terminal illness |
● Withdrawable premium fund (fully taxable)
● Policy loans Payment equal to 50% of the basic insurance amount in case of terminal illness |
| Death benefit guarantee | Guaranteed for life | Guaranteed for life | Guaranteed for life |
| Additional riders |
|
|
|
Sun Life Go Guaranteed Life Insurance: Best for easy, no-medical exam coverage
Sun Life also offers guaranteed issue whole life insurance through the Go Guaranteed policies. It provides guaranteed acceptance for Canadians aged 30 to 74, with no medical exams or health questions required. It is designed for those seeking simple, accessible protection, especially for final expenses or smaller coverage needs.
However, the limited coverage amount and higher premiums make it untenable for Canadians seeking comprehensive coverage. For individuals needing higher coverage amounts, it is recommended to purchase Sun Par Protector II, Sun Par Accumulator II, or SunSpectrum Permanent Life II.
Pros and cons of Sun Life whole life insurance
The pros and cons of Sun Life whole life insurance show its mix of lifetime stability and growth potential. With two participating plans and one non-participating plan, Sun Life’s whole life lineup offers something for every financial need. Here’s a quick look at the overall pros and cons:
How much does Sun Life whole life insurance cost?
The cost of Sun Life whole life insurance for a 20-pay whole life insurance policy with $100,000 in coverage ranges from $1013 to $4906 per month. Your premiums depend on the coverage amount and personal factors, such as gender, age, smoking status, and health.
Cost of Sun Life whole life insurance (2026)
| Age (in years) | Male | Female |
| 20 | $1,013 | $894 |
| 30 | $1,269 | $1,138 |
| 40 | $1,847 | $1,677 |
| 50 | $2,968 | $2,467 |
| 60 | $3,549 | $3,088 |
| 70 | $6,055 | $4,906 |
*Sample monthly cost of $100k coverage for a non-participating whole life insurance for 20-pay
What riders are available with Sun Life whole life insurance?
Sun Life whole life insurance can be customized with multiple optional riders, including accidental death benefit, child term benefit, total disability waiver, and others. These add-ons provide additional protection and benefits for individuals and families, offering well-rounded coverage.
Here is an overview of the riders available with a Sun Life whole life insurance policy:
| Optional benefit | What it does |
| Accidental death benefit | Pays additional insurance if the insured dies from a qualifying accident |
| Child term benefit | Provides term insurance for eligible children and can preserve their ability to buy additional insurance later |
| Total disability waiver | Waives qualifying premiums if the insured becomes totally disabled |
| Owner waiver – death | Can waive premiums if an eligible policyowner who is different from the insured dies |
| Owner waiver – disability | Can waive premiums if an eligible policyowner becomes totally disabled |
| Guaranteed insurability benefit | Allows additional life insurance to be purchased at specified dates or qualifying events without new medical evidence |
| Business value protection benefit | Helps business owners increase coverage without new medical evidence as the value of their business interest grows, subject to financial evidence |
| Term insurance benefit | Adds renewable and convertible temporary coverage alongside the permanent policy |
| Guaranteed return of premium on death benefit
(Available with SunSpectrum) |
Adds qualifying premiums paid to the death benefit |
Which limited-pay whole life insurance plans are available from Sun Life?
Sun Life offers limited pay options across its whole life plans, letting policyholders finish premiums early while keeping lifetime coverage.
Here’s a quick overview of the limited-pay options under each Sun Life whole life insurance plan:
SunSpectrum Permanent Life II
- 10 Pay
- 15 Pay
- 20 Pay
Sun Par Protector II and Sun Par Accumulator II
- 10 Pay
- 20 Pay
Where does Sun Life invest the participating account?
Sun Life has structured its investments across each asset class to meet the long-term objectives, liabilities, and liquidity requirements of its participating policies.
Here’s how the investment is spread out:
| Asset type | Allocation (As of Dec. 31, 2025) |
| Government bonds | 27.42% |
| Corporate bonds | 11.30% |
| Private fixed income | 15.27% |
| Commercial mortgages | 9.93% |
| Equities | 19.45% |
| Real estate | 14.47% |
| Cash and short-term assets | 2.16% |
What dividend options does Sun Life offer?
Sun Par Protector II and Sun Par Accumulator II offer five dividend options to policyholders, allowing them to use their dividends in many ways, such as purchasing additional paid-up insurance, placing them on deposit or receiving them in cash.
Here are the dividend options available with Sun Life whole life insurance:
| Dividend option | How it works |
| Paid-up additional insurance | Uses dividends to buy additional permanent insurance |
| Enhanced insurance | Uses dividends to fund a combination of yearly term insurance and paid-up additions |
| Annual premium reduction | Applies dividends toward the following year’s premium |
| Dividends on deposit | Leaves dividends on deposit with Sun Life to earn interest |
| Cash payment | Pays the annual dividend directly to the policyowner |
What is the Plus premium benefit in Sun Life Whole Life insurance?
The Plus premium benefit for participating policies like Sun Par Protector II and Sun Par Accumulator II lets policyowners make additional premium payments that can be used to purchase additional paid-up insurance. In addition, it can be used to accelerate cash-value accumulation, making it particularly useful for policyholders seeking to maximize a return on their investment.
The benefit is only available when the policy uses either paid up additional insurance or enhanced insurance dividend option. Availability also depends on the selected premium payment option.
Does Sun Life whole life insurance offer premium offset?
Yes, Sun Par Protector II and Sun Par Accumulator II policies may qualify for premium offset. With this feature, policyholders can use the dividends to help cover required premiums. However, this feature is not guaranteed. If future dividends decline, the insured may have to resume making regular premium payments. Additionally, premium offset may also rely on surrendering paid-up additional insurance after years of required premiums.
How does Sun Life compare to other whole life insurance providers?
Sun Life whole life insurance stands out for its variety of whole life products and a series of benefits and value-added features. With the choice between participating and non-participating policies, policyholders can choose a plan that aligns with their financial requirements.
Within the participating lineup, Protector II offers affordable permanent protection and longer-term value, while Accumulator II emphasizes high early cash values. The multiple joint-life structures, a substantial range of riders, premium offsets, and multiple dividend options make it a comprehensive and flexible choice for Canadian families, business owners, and individuals.
Dividend Scale - Participating Whole Life Insurance
Compare dividend rates from top Canadian insurers
| 2022 | 2023 | 2024 | 2025 | 2026 | |
|---|---|---|---|---|---|
| Equitable | 6.05% | 6.25% | 6.40% | 6.40% | 6.40% |
| Manulife | 6.10% | 6.35% | 6.35% | 6.35% | 6.35% |
| iA Financial Group | 5.75% | 6.00% | 6.25% | 6.35% | 6.35% |
| Desjardins Insurance | 5.75% | 6.20% | 6.30% | 6.30% | 6.30% |
| RBC Insurance | 6.00% | 6.00% | 6.25% | 6.30% | 6.30% |
| Sun Life | 6.00% | 6.00% | 6.25% | 6.25% | 6.25% |
| Empire Life | 6.00% | 6.00% | 6.00% | 6.25% | 6.25% |
| Foresters Financial | 5.50% | 5.50% | 5.50% | 6.25% | 6.25% |
| Co-operators | 5.90% | 5.90% | 6.00% | 6.00% | 6.00% |
| Assumption Life | 5.75% | 5.75% | 5.75% | 5.75% | 5.80% |
| Canada Life | 5.25% | 5.50% | 5.50% | 5.75% | 6.00% |
Powered by
Our advisor’s take on Sun Life whole life insurance
At PolicyAdvisor, we recently helped a 42-year-old business owner compare Sun Life’s permanent life insurance options. They were seeking lifelong coverage for estate and family protection, alongside building accessible policy value earlier in the policy. Based on these goals, Sun Par Accumulator II was the stronger fit since it combines participating whole life protection with higher early cash values.
Client profile
- Age: 42
- Family: Married with two children
- Primary concern: Estate protection and building long-term policy value
- Coverage goal: $500,000 in permanent life insurance
- Additional priority: Access to cash value for future personal or business needs
Why we recommended Sun Life’s Sun Par Accumulator II:
- Higher early cash values, making it suitable for the policyholder’s financial goals
- 20-year premium payment option, allowing them to complete the basic policy premiums within a defined period while maintaining lifetime coverage
- Plus premium benefit, offering the option to make additional payments toward paid-up additional insurance and accelerate cash-value accumulation
How to buy Sun Life whole life insurance in Canada
Ready to explore Sun Life whole life insurance? Get a personalized Sun Life whole life illustration and compare it to top Canadian insurers with PolicyAdvisor’s licensed experts.
Get covered in three easy steps:
- Speak with a licensed PolicyAdvisor expert
- Review Sun Par Protector II, Sun Par Accumulator II, and SunSpectrum alongside top competitors
- Receive a personalized illustration and finalize your application online
Whether you are looking to protect your family or secure affordable coverage, our advisors at PolicyAdvisor can help you choose the right coverage amount, premium term, and optional riders to fit your financial needs.
Frequently Asked Questions
Is Sun Life whole life insurance worth it?
Yes, Sun Life whole life insurance can be worth considering, especially if you are focused on estate planning, lifelong protection, or building tax-deferred cash value. It provides guaranteed lifetime coverage and stable long-term growth. Whole life insurance is a long term commitment, so it is important to consider whether the premiums, coverage amount, and cash value features fit your financial goals and budget.
Can I borrow against my cash value?
Yes, you can borrow against the cash value of your Sun Life whole life insurance policy, when sufficient cash value is available. Minimum and maximum loan limits vary by plan. Loans accrue interest and reduce your cash value and death benefit. If the loan balance plus interest exceeds your cash value, the policy may lapse and could trigger tax implications, so it is important to review your statements regularly.
This feature allows policyholders to access funds for short-term needs without surrendering their policy. However, any outstanding balance plus interest will reduce your death benefit if not repaid.
What happens if I stop paying premiums?
If you stop paying premiums, your Sun Life whole life policy will not immediately lapse. You can choose to activate the Automatic Premium Loan (APL) option, which uses your policy’s cash value to cover missed payments and keep coverage in force. The APL must be elected at issue or added later by request.
If the loan balance ever exceeds the total cash value, your Sun Life whole life insurance policy could lapse. To avoid lapse, you’ll need to repay or resume regular premium payments.
Does Sun Life offer participating policies with dividends?
Yes, Sun Life offers two participating whole life insurance plans, such as Sun Par Protector II and Sun Par Accumulator II. These plans may pay annual dividends, depending on the performance of Sun Life’s participating account. Par Accumulator has cash value growth as early as the first year, whereas Par Protector II begins in year five.
Dividends may include paid-up additions (to increase coverage and cash value), premium reduction, cash withdrawals, or interest on deposit. Dividends are not guaranteed and may change over time, and available options vary by plan.
What is Sun Par Protector II Life Insurance?
Sun Par Protector II is a participating whole life plan designed for affordable, long-term protection. It offers lifetime coverage, fixed premiums, and a guaranteed death benefit. The plan’s cash value starts building at the end of year 5, and policyholders can choose flexible payment options such as life-pay, 10-pay, or 20-pay. It also offers five dividend options: paid-up additional insurance (PUA), enhanced insurance, annual premium reduction, dividends on deposit, and cash payment.
What is Sun Par Accumulator II Life Insurance?
Sun Par Accumulator II is a participating whole life insurance plan built for faster cash value access and long-term growth. It offers lifetime coverage with premiums payable through life-pay, 10-pay, or 20-pay structures. Cash value begins accumulating at the end of year 1, and policyholders can benefit from annual dividends through options like paid-up additional insurance (PUA), enhanced insurance, annual premium reduction, dividends on deposit, and cash payment. This makes the Accumulator II ideal for those seeking both protection and early access to policy value.
What is SunSpectrum Permanent Life II Insurance?
SunSpectrum Permanent Life II is a non-participating whole life insurance plan that provides guaranteed lifetime coverage and steady cash value growth. Unlike participating policies, it doesn’t pay annual dividends. Premiums are fixed and can be paid through multiple structures, such as life-pay, 10-pay, 15-pay, or 20-pay. The plan’s cash value builds gradually over time and can be accessed through withdrawals or policy loans. It is a good fit for those who want predictable costs and long-term stability without dividend fluctuations.
Are par account investments affected by market conditions?
Yes, par account investments are affected by market conditions. While Sun Life employs a long-term investment strategy and diversifies across various asset classes to stabilize returns, fluctuations in interest rates and stock prices can still affect the account’s earnings.
Which Sun Life policy builds cash value fastest?
Sun Par Accumulator II generally provides the earliest guaranteed cash values, typically beginning at the end of year 1. Meanwhile, the SunSpectrum and Protector II typically begin accumulating cash value later on.
Does Sun Life offer joint whole life insurance?
Yes, Sun Life’s SunSpectrum Permanent Life II, Sun Par Protector II, and Sun Par Accumulator II offer joint-life options, including joint first-to-die and joint last-to-die structures.
Empire Life whole life insurance review (2026)
Empire Life offers whole life insurance with guaranteed lifetime protection, level premiums, and options for building cash value. Its portfolio includes both non-participating and participating whole life insurance plans. Empire Life’s non-participating plans include Solution 100 and Term to 100, while its participating portfolio includes EstateMax and Optimax Wealth, which offer the potential for dividends and additional wealth accumulation opportunities.
Quick review:
- PolicyAdvisor ratings: 4.5/5
- Best for: Limited-pay coverage, including the relatively uncommon 8-pay option available with Optimax Wealth
- Skip if: You want additional wellness benefits
About Empire Life
Empire Life is one of Canada’s most established insurers, recognized for consistent performance, client-focused service, and strong financial strength, including an A rating from A.M. Best. Founded in 1923, Empire Life’s whole life insurance offers lifetime coverage through participating and non-participating plans.
A key feature of Empire Life’s is its participating whole life insurance plans, EstateMax and Optimax Wealth, which are supported by a disciplined $1.32 billion par fund. With nearly a century of experience, Empire Life offers coverage that balances predictable growth, reliable cash value accumulation, and flexible options for long-term financial goals.
Empire Life’s financial strength:
| AM Best Rating | A |
| Participating account fund size | 1.32 billion |
| LICAT ratio | 159% |
| Dividend scale interest rate (DSIR) | 6.25% |
Disclaimer: Figures and ratings are based on the latest available information and may change over time
What is Empire Life whole life insurance?
Empire Life whole life insurance is a type of permanent life insurance designed to provide lifetime protection. Its portfolio includes non-participating policies, which provide guaranteed benefits and cash values, and participating policies, which provide guaranteed benefits while also giving policyholders the potential to receive dividends based on the performance of the insurer’s participating account.
Empire Life offers two participating plans, EstateMax and Optimax Wealth, and two non-participating plans, Solution 100 and Term to 100. Both EstateMax and Optimax Wealth offer coverage of up to $20 million, with limited-pay options including 10-pay, 20-pay, and life-pay. Optimax Wealth also offers an 8-pay option, giving policyholders an additional way to pay premiums over a shorter period.
Among the non-participating plans, Term to 100 is suited for those seeking permanent insurance protection without cash value benefits, while Solution 100 is designed for those who want permanent protection with access to cash values. Both plans can also be customized with riders, including waiver of premium, guaranteed insurability, accidental death and dismemberment, and others.
Key features of Empire Life whole life insurance:
| Plan names |
|
| Policy issue age (min & max) |
|
| Coverage range (maximum) | $20,000,000 (for all plan types) |
| Coverage options | Term 100 & Solution 100
EstateMax & Optimax Wealth: Single-life and joint coverage |
| Premium payments |
|
| Dividend options (participating plans only) |
|
| Riders |
|
Who is eligible for Empire Life whole life insurance?
Empire Life whole life insurance is designed for:
- Canadian residents who meet Empire Life’s underwriting requirements
- Individuals within the applicable issue ages: 18-75 for Term to 100; 0-75 for Solution 100; and 0-75 for EstateMax and Optimax Wealth under single-life coverage. Joint coverage for EstateMax and Optimax Wealth is available from ages 18-75
- Applicants seeking at least $ 10,000 in coverage (can vary depending on the age)
Key benefits of Empire Life whole life insurance
Empire Life whole life insurance offers lifelong protection with options for growth, stability, and estate planning. It combines guaranteed lifetime coverage with dividend-earning potential or guaranteed cash values, depending on the plan type. Here are its key benefits:
- Lifetime coverage: Your policy remains in force for life
- Death benefit: Provides a tax-free death benefit to beneficiaries when the insured person dies, provided the policy remains in force
- Fixed level premiums: Premium payments stay the same throughout your chosen premium-pay period
- Dividend potential (for participating plans): Eligible policies may receive annual dividends, which can be used to buy paid-up additions, reduce premiums, withdraw as cash, or earn interest
- Cash value: Cash values are available for all types, except Term 100 may depending on the circumstances
- Flexible payment choices and riders: Choose shorter pay options (10-pay or 20-pay) or life-pay for flexibility. Add riders such as accidental death, child term insurance, or disability waiver for customized coverage
- Living benefit: This is a non-contractual benefit that is approved on a case-by-case basis. It provides up to 50% of the death benefit, to a maximum of $50,000, if the insured is diagnosed with a terminal illness and has 12 months or less to live
Types of Empire Life whole life insurance
Empire Life offers four whole life insurance plans, including two participating plans and two non-participating plans. These plans are designed to meet different financial goals and payment preferences.
Participating whole life plans by Empire Life:
- EstateMax
- Optimax Wealth
Non-participating whole life insurance by Empire Life:
- Solution 100
- Term to 100
About Empire Life’s participating whole life insurance plans
Empire Life’s participating whole life plans provide lifetime protection, guaranteed premiums, and the potential for steady long-term cash value growth. Like all participating policies, they may earn annual dividends based on the performance of Empire Life’s participating account, which invests in a mix of bonds, equities, and real estate. While dividends aren’t guaranteed, they offer an opportunity to enhance coverage and overall policy value.
Currently, Empire Life offers two participating whole life plans:
EstateMax: Best for long-term estate and wealth transfer
EstateMax is built for Canadians who want strong long-term cash value growth. It’s ideal for those focused on estate planning or leaving a larger legacy. Coverage starts at $10,000 for ages 0-17 and 66-75, and $25,000 for ages 18-65. It offers 10-pay, 20-pay, and life-pay options, with dividend choices including paid-up additions, premium reduction, cash, enhanced coverage, and interest on deposit. The guaranteed cash value starts accumulating from year 5.
Optimax Wealth: Best for early cash value access
Optimax Wealth is designed for those who want faster early cash value build-up and lifetime coverage. It emphasizes liquidity and flexibility, allowing policyholders to access value early through loans or withdrawals to fund opportunities such as education, business expansion, or wealth-building goals.
It offers the same coverage range and limited-pay options as EstateMax, with the addition of an 8-pay option. Optimax Wealth also offers riders such as accidental death, child term, guaranteed insurability, and disability waiver, along with the optional Additional Deposit Option (ADO) for accelerated growth.
Key differences between EstateMax and Optimax Wealth:
| Feature | EstateMax | Optimax Wealth |
| Cash value accumulation | Starts from the 5th year of the policy | Starts after completing one year of the policy |
| Maximum issue age | 75 years for both individual and joint coverage plans | 75 years for both individual and joint coverage plans |
| Minimum coverage |
|
|
| Premium payment options | 10-pay, 20-pay, life-pay | 8-pay, 10-pay, 20-pay, life-pay |
| Maximum coverage | $20,000,000 | $20,000,000 |
| Coverage options |
|
|
| Dividend options |
|
|
About Empire Life’s non-participating whole life plans
Empire Life’s non-participating whole life plans provide straightforward lifetime protection with fixed premiums and guaranteed death benefits. No dividends are payable on non‑par plans. These plans are built for Canadians who want simple, predictable coverage without market fluctuations or dividend variability.
Non-participating plans can help meet goals such as estate preservation, funding final expenses, or leaving a small legacy for children, grandchildren, or charities. Currently, Empire Life offers two non-participating whole life plans:
Solution 100: Best for guaranteed value and flexibility
Solution 100 provides permanent coverage with fixed premiums and guaranteed cash surrender values that begin in policy year 10. It’s ideal for Canadians who want lifelong protection but also appreciate some accessible policy value if their needs change. The policy can be customized with riders such as waiver of premium, guaranteed insurability, AD&D, children’s life, and children’s critical illness riders, among others.
Term to 100: Best for simple, low-cost lifetime protection
Term to 100 offers permanent coverage with fixed premiums and no cash value. It’s a lower-cost option focused purely on lifetime protection, ideal for those who want straightforward coverage for estate or final-expense needs. It offers life pay, with guaranteed level premiums to age 100, and a 20-pay option, with guaranteed level premiums for 20 years. Like Solution 100, Term to 100 can also be customized with riders at an additional premium.
Key differences between Solution 100 and Term to 100:
| Feature | Solution 100 | Term to 100 |
| Primary focus | Cost-effective insurance option for kids, estate planning, and intergenerational wealth transfer or final debt payouts | Estate preservation, wealth for children and grandchildren, corporate legacy builder |
| Issue age | 0-75 | 18-75 |
| Minimum coverage | $25,000 up to age 65
$10,000 for ages 66 to 75 |
$25,000 up to age 65
$10,000 for ages 66 to 75 |
| Cash value growth | Cash value growth available, and cash can be accessed from the 10th year of the policy | Cash value growth not available |
| Payment options | Guaranteed premium level up to age 100 | Life-pay and 20-pay |
| Annual policy fee | $50 policy fee on the base plan | $50 policy fee on the base plan |
| Insurance riders |
|
|
| Additional benefits |
|
|
Pros and cons of an Empire Life whole life insurance policy
Empire Life whole life insurance offers several advantages, from flexible coverage options to unique wealth-building features, along with a few limitations depending on your age and plan type. Let’s take a closer look at the pros and cons of Empire Life Whole Life insurance below:
| Pros | Cons |
| EstateMax policy features prepayment solutions through Empire Life’s Side Account feature | The 8-pay option is only available with the Optimax Wealth plan |
| Living benefit available if a terminal illness is diagnosed | Maximum issue age is 75 (availability varies by product and underwriting) |
| Joint first-to-die coverage includes survivor and policy exchange options, offering 90 days of temporary insurance after the first death | |
| EstateMax and Optimax Wealth have policy features and prepayment solutions through Empire Life’s Side Account feature | |
| Kid-start wealth transfer helps grandparents secure their grandchildren’s financial future |
How much does Empire Life whole life insurance cost?
The cost of Empire Life whole life insurance for a male or female seeking $100,000 in coverage under a 20-pay participating whole life insurance plan ranges from $1,321 to $7,401 per month. The actual premium may vary based on factors such as your age, gender, coverage amount, payment option, and a few other factors.
Cost of Empire Life whole life insurance (2026):
| Age (in years) | Male | Female |
| 20 | $1,538/month | $1,321/month |
| 30 | $1,976/month | $1,735/month |
| 40 | $2,595/month | $2,300/month |
| 50 | $3,479/month | $3,079/month |
| 60 | $4,819/month | $4,221/month |
| 70 | $7,401/month | $6,381/month |
*Illustrating monthly cost of $100k coverage for a participating whole life insurance for 20-pay
See how much whole life insurance coverage you can get
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
Empire Life’s Dividend Scale Interest Rate (DSIR) history
The DSIR reflects Empire Life’s internal expectation of net returns after taxes, claims, and expenses. It is not a return paid directly to policyholders but drives dividend projections. Dividends depend on investment results, policyholder experience, and participating account surplus, and are approved annually by the Board. While dividends are not guaranteed, Empire Life’s narrow 6.0–6.25% band over the past decade showcases its disciplined approach.
Dividend Scale - Participating Whole Life Insurance
Compare dividend rates from top Canadian insurers
| 2022 | 2023 | 2024 | 2025 | 2026 | |
|---|---|---|---|---|---|
| Equitable | 6.05% | 6.25% | 6.40% | 6.40% | 6.40% |
| Manulife | 6.10% | 6.35% | 6.35% | 6.35% | 6.35% |
| iA Financial Group | 5.75% | 6.00% | 6.25% | 6.35% | 6.35% |
| Desjardins Insurance | 5.75% | 6.20% | 6.30% | 6.30% | 6.30% |
| RBC Insurance | 6.00% | 6.00% | 6.25% | 6.30% | 6.30% |
| Sun Life | 6.00% | 6.00% | 6.25% | 6.25% | 6.25% |
| Empire Life | 6.00% | 6.00% | 6.00% | 6.25% | 6.25% |
| Foresters Financial | 5.50% | 5.50% | 5.50% | 6.25% | 6.25% |
| Co-operators | 5.90% | 5.90% | 6.00% | 6.00% | 6.00% |
| Assumption Life | 5.75% | 5.75% | 5.75% | 5.75% | 5.80% |
| Canada Life | 5.25% | 5.50% | 5.50% | 5.75% | 6.00% |
Powered by
Which limited pay whole life insurance plans are available from Empire Life
Empire Life’s EstateMax and Optimax Wealth plans offer predictable long-term growth through a disciplined, conservative investment approach. These participating plans provide lifetime protection with 8-pay, 10-pay, 20-pay, and life-pay options. The 8-pay option is available only with the Optimax Wealth plan. Limited-pay options allow policyholders to pay premiums over a set period while keeping their coverage in force for life.
What is Empire Life’s side account?
Empire Life’s EstateMax and Optimax Wealth plans include a side account that can hold money for future premiums, policy fees, and rider costs. The account earns interest set by Empire Life, but because it is held outside the policy, the interest earned is taxable. Funds can be withdrawn at any time and are paid to the policyowner on surrender or to beneficiaries upon death. Funds in the side account can be used to pay future base premiums, policy fees, and premiums for eligible riders and additional benefits.
Can I get any living benefits with Empire Life?
Yes, Empire Life offers a Living Benefit Advance on all its life insurance policies as a non-contractual benefit. This benefit means that if the insured is diagnosed with a terminal illness with a prognosis of 12 months or less, they may receive 50% of the death benefit, up to $50,000. The advance plus interest is deducted from the death benefit when the claim is paid.
What is Empire Life’s Kid Start strategy?
Empire Life’s Kid Start is a whole life insurance strategy that uses the tax advantages of individually owned life insurance to help give children or grandchildren a financial head start. It involves purchasing EstateMax or Optimax Wealth when the child is young and healthy, allowing the policy to build cash value that can later be accessed through policy loans or cash value withdrawals. The policy can also be fully paid-up in 8, 10, or 20 years, while ownership can be transferred to the child at the age of majority or later.
What is Empire Life’s Additional Deposit Option?
Empire Life’s Additional Deposit Option (ADO) is available on eligible EstateMax and Optimax Wealth 10-pay, 20-pay, and life-pay participating whole life plans. It allows policyholders to make additional deposits to accelerate cash surrender value growth and increase life insurance. ADO is available for issue ages 0 to 75 and can be used with either paid-up additions or enhanced coverage dividend options. ADO deposits are optional and can be stopped anytime, at the will of the policyholder.
How does Empire Life compare to other whole life insurance providers?
Empire Life stands out for offering both participating and non-participating permanent life insurance, giving Canadians a choice between dividend potential and straightforward guaranteed protection. Its participating plans, EstateMax and Optimax Wealth, offer lifetime coverage, multiple premium-payment options, and the potential to earn dividends, while Optimax Wealth is one of the few plans to offer an 8-pay option. Its non-participating plans, Solution 100 and Term to 100, provide guaranteed lifetime protection, with Solution 100 also offering guaranteed cash values. To see how Empire Life compares with other leading insurers, read our guide to the best whole life insurance companies in Canada.
Our advisor’s take on Empire Life whole life insurance
At PolicyAdvisor, one of our expert advisors helped a 40-year-old client looking for permanent life insurance that could provide family protection while also building cash value over time. The client was particularly interested in participating whole life insurance, with the potential to earn dividends and access cash value during their lifetime.
Client profile:
- Age: 40-year-old non-smoking Canadian
- Coverage need: $500,000 in permanent life insurance for family protection and long-term financial planning
- Primary concern: Building cash value while maintaining guaranteed lifetime protection and flexible premium-payment options
- Our comparison: We compared Empire Life’s EstateMax and Optimax Wealth with participating whole life products from other leading Canadian insurers, focusing on dividend potential, cash value growth, limited-pay options, and policy flexibility
Why Empire Life stood out:
- Choice of participating plans: Empire Life offers EstateMax for long-term estate and wealth planning and Optimax Wealth for those who prioritize earlier cash value growth
- Flexible premium-payment options: Empire Life offers 10-pay, 20-pay, and life-pay options on both participating plans, while Optimax Wealth also offers an 8-pay option for those who want to complete premium payments sooner
- Multiple ways to use dividends: Policyholders can choose from several dividend options, including paid-up additions, premium reduction, cash payouts, and leaving dividends on deposit to accumulate
How to buy Empire Life whole life insurance with PolicyAdvisor?
Ready to buy Empire Life whole life insurance? Get a personalized Empire Life whole life illustration and compare it to top Canadian insurers with PolicyAdvisor’s licensed experts.
Get covered in three easy steps:
- Speak with a licensed PolicyAdvisor expert
- Review Empire Life non-participating and participating plans, EstateMax and Optimax Wealth, alongside plans from other top Canadian insurers
- Receive a personalized illustration and finalize your application online
PolicyAdvisor’s licensed experts help you compare options and find the perfect plan for your lifetime coverage and financial goals.
Frequently asked questions
Can I pause premiums if I face financial hardship?
You generally cannot simply pause premiums without affecting your policy. However, if your policy has sufficient cash value or dividends, you may be able to use them to help cover premiums temporarily. A policy loan may also be available, but interest applies, and outstanding loans can reduce the policy’s cash value and death benefit.
Does Empire Life offer coverage options for couples under a single policy?
Yes, Empire Life offers joint first-to-die and joint last-to-die coverage options, allowing couples to share a policy that provides benefits either after the first death or after both insured individuals die.
How can I use the cash value of my Empire Life policy without surrendering it?
You can access your policy’s cash value through a policy loan or by withdrawing dividends. This allows you to tap into your policy’s value for financial needs, such as education, a home purchase, or business investments, without losing coverage.
Does Empire Life’s Term to 100 have a cash surrender value (CSV)?
No. Empire Life Term to 100 does not include a cash surrender value. Premiums are applied to maintain lifelong coverage, keeping the plan more affordable.
Are dividends guaranteed on Empire Life’s EstateMax and Optimax Wealth plans?
No. Dividends are not guaranteed. They are declared each year and depend on the performance of Empire Life’s participating account, including factors like investment returns, expenses, and mortality experience.
What are the whole life insurance coverage types available for Empire Life?
Empire Life offers three coverage types for its life insurance policies: single life, joint first death, and joint last death. Single life covers one individual and pays the death benefit to beneficiaries when the insured dies. Joint first death covers two individuals, such as spouses or business partners, and pays the death benefit after the first insured person dies. Joint last death also covers two individuals, but the death benefit is paid after both insured individuals have died, making it particularly useful for estate planning and wealth transfer.
Can I get a loan against my Empire Life whole life insurance policy?
Yes, you can take a policy loan on Empire Life whole life insurance policies, provided the policy has accumulated enough cash value. The minimum loan amount is $250, allowing policyholders to access funds for personal or financial needs while keeping their policy active.
Policy loans are an attractive feature because they offer quick access to cash without the need for external credit checks. The loan amount is borrowed against the policy’s cash value, and interest is charged on the outstanding balance. Any unpaid loan balance, including interest, will be deducted from the policy’s death benefit or cash value if the loan is not repaid. However, policy loans can be subject to taxes, so it is better to go through your policy documentation before applying for a loan.
Why should I get Empire Life whole life insurance for my grandchildren?
Empire Life whole life insurance can help grandparents build lasting financial security for their grandchildren. Through the Kid-Start Wealth Transfer feature, they can gift a paid-up participating policy that grows in value over time, offering lifelong protection and a foundation for future goals like education or home ownership.
Are there any administrative fees associated with an Empire Life whole life insurance policy?
Yes, most individual Empire Life whole life insurance policies include an annual administrative fee of $50 as part of the base plan. This fee applies to both participating and non-participating plans and helps cover the cost of managing and servicing the policy, including maintaining records, processing dividends, and providing customer support. Some group or legacy policies may differ.
RBC Whole Life Insurance Review (2026)
RBC Insurance, backed by one of Canada’s largest banks, offers participating whole life insurance policies that build cash value, provide guaranteed lifelong protection, and the potential to receive policyholder dividends. RBC provides two whole life plans: Growth Insurance and Growth Insurance Plus, each with distinct features. While the former offers coverage starting at $25,000, Growth Insurance Plus starts at $250,000.
Quick review:
- PolicyAdvisor ratings: 4/5
- Best for: Parents seeking permanent coverage for children with a Juvenile Guaranteed Insurability Benefit
- Skip if: You want a 10-pay policy with the option to make additional deposits
About RBC Insurance
Recognized as Canada’s largest bank-owned life insurance company by total revenue, RBC Insurance serves almost 5 million clients globally. In addition to whole life insurance, RBC Insurance also specializes in offering health, home, auto, travel, wealth, and reinsurance advice and solutions to individual, business and group clients. Moreover, with a LICAT ratio of 132%, RBC demonstrates strong financial strength. Its estimated par fund size is $51.39 million, and it has maintained a stable dividend rate over the past few years.
RBC Insurance’s financial strength:
| AM Best Rating | A |
| Participating account fund size | $51.39 million |
| LICAT ratio | 132% |
| Dividend scale interest rate (DSIR) | 6.30% |
Disclaimer: Figures and ratings are based on the latest available information and may change over time
What is RBC whole life insurance?
RBC whole life insurance provides permanent life insurance coverage with guaranteed cash value growth. It has two participating whole life plans: Growth Insurance and Growth Insurance Plus; both offer limited pay options: 10-pay, 20-pay, or Life pay to age 100 and the flexibility to choose the coverage option from single life, joint first to die, and joint last to die.
RBC Growth Insurance is available with guaranteed cash value starting at the end of the fifth policy year. RBC Growth Insurance Plus is designed to accelerate tax-deferred growth and provides access to guaranteed cash value from the end of the first policy year. Both plans offer five dividend options, including paid-up additions, cash, premium reduction, dividends on deposit, and enhanced insurance.
Key features of RBC whole life insurance:
| Plan names |
|
| Policy issue age (min & max) |
|
| Coverage range |
|
| Coverage options |
|
| Payment options |
|
| Dividend options |
|
| Deposit options | Only available for 20-pay and life-pay policies with paid-up additions or enhanced insurance dividend options |
| Additional benefits |
|
| Riders |
|
Who is eligible for RBC whole life insurance?
RBC whole life insurance is designed for:
- Canadian residents who satisfy RBC Insurance’s underwriting guidelines
- Individuals aged 0 to 80 for single-life coverage and 18-80 years for joint-life policies, with specific eligibility for the Juvenile Guaranteed Insurability Benefit for children aged 0 to 17
- Applicants seeking a minimum of $25,000 in coverage for RBC Growth Insurance or $250,000 for RBC Growth Insurance Plus
What is covered under RBC whole life insurance?
RBC’s Growth Insurance and Growth Insurance Plus whole life insurance plans include the following:
- Death benefit: Provides a tax-free death benefit to beneficiaries when the insured person dies, as long as the policy remains in force
- Guaranteed cash value: Builds cash value over time, which can be accessed through policy loans or withdrawals, subject to the policy terms
- Dividend potential: Participating policies may earn dividends based on the insurer’s performance. The available dividend options include cash, premium reduction, dividends on deposit, paid-up additions, and enhanced insurance. Dividends are not guaranteed
- Optional coverage: Policyholders can add optional benefits and riders to customize their coverage based on their financial and protection needs
What are the different types of RBC whole life insurance?
RBC offers two participating whole life plans with lifetime coverage, guaranteed cash value growth, and the potential to earn dividends: RBC Growth Insurance and RBC Growth Insurance Plus. The premiums from participating policyholders are pooled in RBC’s participating account, and dividends may be paid based on the account’s experience.
- Growth Insurance: Coverage ranges from $25,000 to $25 million. This option is designed for individuals seeking permanent life insurance with long-term cash value growth. Guaranteed cash value becomes available at the end of the fifth policy year. It also includes the Juvenile Guaranteed Insurability Benefit, which allows the policyholder to purchase additional insurance after the child turns 18 without providing additional evidence of insurability
- Growth Insurance Plus: Offers almost the same core benefits of permanent coverage, cash value accumulation, and dividend potential, but is designed for faster cash value growth. Coverage ranges from $250,000 to $25 million, and guaranteed cash value is available from the first policy year, providing earlier access to guaranteed cash value compared with Growth Insurance
RBC Grow Insurance vs Grow Insurance Plus:
| Category | RBC Growth Insurance | RBC Growth Insurance Plus |
| Cash value accumulation | Accessible after 5 years | Accessible after the first year |
| Premium type | Fixed with flexible payment options:
Life Pay, 10 Pay, 20 Pay |
Fixed with flexible payment options:
Life Pay, 10 Pay, 20 Pay |
| Maximum issue age | Up to 80 years | Up to 80 years |
| Coverage amount range | $25,000 to $25,000,000 | $250,000 to $25,000,000 |
| Dividend options |
|
|
| Policy loan availability | Yes, you can borrow against your policy’s cash value if it’s not in the grace period | Yes, you can borrow against your policy’s cash value if it’s not in the grace period |
| Living benefits |
|
|
What are the dividend options available with RBC whole life insurance?
The dividend options for Growth Insurance and Growth Insurance Plus are the same. Annual dividends can be issued as:
- Cash: You can receive your dividends as cash, though they may be taxable
- Premium reduction: Dividends are applied to your premiums for the following year. Any excess dividends are paid to you directly
- Dividends on deposits: Dividends are deposited into an interest-bearing account, which you can access anytime. Any interest earned is taxable
- Paid-up additions: This option uses dividends to buy additional insurance coverage. The added coverage can earn dividends and build its own cash value over time
- Enhanced insurance: Your dividends can also be used to buy a mix of paid-up additions and one-year term insurance. The insurance purchased using paid-up additions can earn dividends and build cash value in the future
Pros and cons of RBC’s whole life insurance
RBC’s whole life insurance plans offer several advantages: multiple payment and dividend options, flexible use of cash value. However, there are also some downsides, like restricted deposit-option eligibility and delayed guaranteed cash value in Growth Insurance.
| Pros | Cons |
| Offers 5 dividend options | The deposit option is available only if the premium payment period is 20 Pay or Life Pay |
| Allows deposit option payments to purchase additional insurance | Growth Insurance Plus requires a higher minimum coverage amount of $250,000 |
| Provides a $25,000,000 coverage limit, subject to approval requirements | Juvenile Guaranteed Insurability Benefit is not available with Growth Insurance Plus or policies with substandard risks |
| Includes a juvenile guaranteed insurability benefit at no additional cost for insureds under 18 | |
| Flexible payment options: life pay, 10-pay, and 20-pay |
How much does RBC whole life insurance cost?
The cost of RBC whole life insurance for a male or female seeking $100,000 in coverage for participating whole life insurance for 20-pay ranges between $184 and $619 per month. The actual premium you pay, however, may vary based on factors such as your age, gender, coverage amount, payment option, and underwriting profile.
Cost of RBC whole life insurance (2026):
| Age (in years) | Male | Female |
| 20 | $198.54/month | $184.04/month |
| 30 | $236.41/month | $220.77/month |
| 40 | $285.39/month | $267.24/month |
| 50 | $349.34/month | $326.87/month |
| 60 | $442.64/month | $408.38/month |
| 70 | $619.31/month | $549.38/month |
*Illustrates the monthly cost of $100,000 in participating whole life insurance coverage with a 20-pay option and paid-up additions dividends
What is your Whole Life Insurance worth?
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
What riders are available with RBC whole life insurance policy
Listed below are some of the riders that you can include in your RBC whole life insurance policy to enhance its coverage:
- Guaranteed insurability benefit: This lets you get additional life insurance coverage without updating any health or lifestyle information. It can be exercised up to six times within 31 calendar days following your marriage or the birth or adoption of a child, or within 31 calendar days following every third policy anniversary
- Payor death and disability: It is only applicable to the payor of the life insurance policy and is helpful in waiving the premium if the payor dies or suffers disability. For disability, the waiver begins after six months and continues until the payor reaches age 60
- Children’s term rider: It provides term insurance coverage to all children of the life insured. The coverage continues until each child’s 25th birthday. Each insured child can convert the coverage to a permanent policy without providing new evidence of insurability
- Total disability waiver of premium rider: This rider will waive the premium in the event of permanent disability of the life insured. The protection continues until age 60, provided the policy remains in force
- Accidental death benefit rider: This provides additional death benefit if the life insured dies due to an accident. Coverage continues until the life insured reaches age 65
- Term insurance rider: Add RBC YourTerm 10, 15, 20, or 25 to your policy for affordable temporary life insurance coverage when you have additional short-term protection needs
How much dividend does RBC pay?
RBC’s dividend payments depend on its dividend scale, which changes annually. While the dividends in a par account are not guaranteed, historically, RBC has maintained a dividend scale interest rate of 6.00%. This was recently increased to 6.30%, effective April 2025, and remains the same for 2026. Policyholders can expect their dividends to be paid according to this new rate until March 31, 2027.
What factors affect the dividends of RBC whole life policy
Each year, dividends are determined based on the performance of the participating account backing RBC Growth Insurance and Growth Insurance Plus. The factors that affect the performance include investments, policy cancellations, mortality rates, and administrative costs.
- Investment returns: Premiums from all participating policyholders are combined into a shared fund called the participating account. Managed by RBC portfolio managers, this fund is then diversified across assets like bonds, equities, and real estate to achieve long-term, stable growth. The returns earned directly influence the level of dividends distributed
- Policy cancellations: Dividends also reflect experience with policy cancellations. These assumptions support stability and sustainability for policyholders
- Administrative costs: RBC’s ability to control administrative and operational costs also impacts the dividends. Efficient management means fewer expenses and more funds that can potentially be allocated to dividends
- Claims experience: The number and timing of death claims compared with the assumptions used by RBC can affect the participating account’s financial performance
Dividend Scale - Participating Whole Life Insurance
Compare dividend rates from top Canadian insurers
| 2022 | 2023 | 2024 | 2025 | 2026 | |
|---|---|---|---|---|---|
| Equitable | 6.05% | 6.25% | 6.40% | 6.40% | 6.40% |
| Manulife | 6.10% | 6.35% | 6.35% | 6.35% | 6.35% |
| iA Financial Group | 5.75% | 6.00% | 6.25% | 6.35% | 6.35% |
| Desjardins Insurance | 5.75% | 6.20% | 6.30% | 6.30% | 6.30% |
| RBC Insurance | 6.00% | 6.00% | 6.25% | 6.30% | 6.30% |
| Sun Life | 6.00% | 6.00% | 6.25% | 6.25% | 6.25% |
| Empire Life | 6.00% | 6.00% | 6.00% | 6.25% | 6.25% |
| Foresters Financial | 5.50% | 5.50% | 5.50% | 6.25% | 6.25% |
| Co-operators | 5.90% | 5.90% | 6.00% | 6.00% | 6.00% |
| Assumption Life | 5.75% | 5.75% | 5.75% | 5.75% | 5.80% |
| Canada Life | 5.25% | 5.50% | 5.50% | 5.75% | 6.00% |
Powered by
How can I access my RBC whole life cash value?
You can access the cash value of your RBC whole life policy in several ways:
- Policy loans: You can borrow up to 90% of your policy’s cash value, provided it’s not in the grace period. The minimum policy loan is $500, and interest applies
- Use policy as collateral: You can request to use your policy as collateral for a loan from a financial institution
- Cash withdrawal: You can withdraw a portion of your guaranteed net cash value by reducing your base life insurance coverage. This will decrease the death benefit your beneficiary could receive
- Premium offset: If your policy has sufficient cash value, you can use it to pay premiums. This option is not guaranteed and is available only once your policy reaches the earliest offset date, with no outstanding loans
Does RBC whole life insurance offer life limited-pay options?
Yes, both RBC Growth Insurance and RBC Growth Insurance Plus are available with limited-pay options. These plans let you choose from the available premium-paying options, including 10-pay and 20-pay. Limited-pay options can help you complete your premium payments over a set period while keeping the policy in force for life. You can choose a suitable premium pay option and enjoy coverage for life with RBC whole life plans.
What is the Juvenile Guaranteed Insurability Benefit?
The Juvenile Guaranteed Insurability Benefit is available only with RBC Growth Insurance and is automatically included at no additional cost. It is available to insured children aged 0 to 17 who are assessed as a standard risk when applying. This feature allows the insured to purchase additional term or permanent life insurance in the future without providing updated health or lifestyle information.
The Juvenile Guaranteed Insurability benefit can be exercised three times. Options become available after the child’s 18th birthday and within 31 days following marriage, the birth or adoption of a child, or every third policy anniversary. The benefit expires on the policy anniversary nearest the insured’s 40th birthday or once the maximum number of elections has been used.
Does RBC whole life insurance offer a deposit option?
Yes, RBC whole life insurance offers a deposit option with 20-pay or life pay premium payment options. The deposit option allows policyholders to make additional payments beyond their required premiums to purchase paid-up additional insurance. These optional payments can help increase the policy’s non-guaranteed cash value over the long term and are not part of the policy’s guaranteed premium.
How are premiums invested for RBC Growth Insurance and Growth Insurance Plus?
Premiums from Growth Insurance and Growth Insurance Plus policies are invested in a diverse mix of assets, including corporate and government bonds, private fixed income, commercial mortgages, common shares, and commercial real estate. RBC’s experienced portfolio managers invest these assets, so policyholders do not have to manage the investments themselves. These managers have more than 100 years of collective asset management experience and use the same investment philosophy as RBC Capital Markets and RBC Global Asset Management.
- Corporate bonds: RBC invests in high-quality corporate bonds to generate stable income while managing credit risk. These bonds help enhance the participating account’s long-term returns through diversification across sectors
- Government bonds: These include government bonds, which provide steady, low-risk returns and long-term financial stability for policyholders
- Private fixed income: These are debt investments issued through private agreements (e.g., corporate loans or infrastructure debt)
- Commercial mortgages: These are long-term loans secured by commercial properties such as office buildings, retail spaces, and industrial complexes
- Common shares: Investments are also made in stocks, with a portion linked to major equity indices like the S&P/TSX Composite Index
- Commercial real estate: RBC also invests in diversified commercial real estate funds holding retail, office, multi-residential, and industrial properties across major Canadian markets. These investments can provide relatively stable returns through the pooled funds’ diversified property holdings
Please note that while RBC uses “smoothing” techniques to manage short-term market fluctuations and maintain stable returns, changes in stock prices and interest rates can still influence the participating account’s surplus.
How does RBC Insurance compare to other whole life insurance providers?
RBC whole life insurance stands out for its participating plans, flexible premium payment options, and five dividend strategies. Growth Insurance includes a Juvenile Guaranteed Insurability Benefit for eligible children, while Growth Insurance Plus starts at $250,000 and is designed for faster cash value growth. Both plans offer single-life, joint-first-to-die, and joint-last-to-die coverage options, with 10-pay, 20-pay, and life-pay structures. To see how RBC compares with other leading insurers, read our guide to the best whole life insurance companies in Canada.
Our advisor’s take on RBC whole life insurance
At PolicyAdvisor, one of our advisors recently worked with a 52-year-old client who wanted permanent life insurance with cash value growth and a participating policy supported by a stable dividend scale history. The client’s priority was to choose a policy where dividend performance had remained relatively consistent over time, while still benefiting from the guarantees built into the whole life policy.
Client profile:
- Age: 52-year-old non-smoking Canadian
- Coverage need: $750,000 in permanent life insurance for family protection and future financial planning
- Primary concern: Stable dividend scale performance and predictable long-term policy growth
- Our comparison: We compared RBC’s Growth Insurance and Growth Insurance Plus with participating whole life products from other leading Canadian insurers, focusing on dividend scale history, cash value growth, dividend options, and limited-pay options
Why RBC stood out:
- Stable dividend scale history: RBC maintained a 6.00% DSIR from 2022 to 2023 before increasing it to 6.25% in 2024 and 6.30% in 2025 and 2026, giving the client a relatively consistent dividend scale history to consider
- Guaranteed policy values: Alongside potential dividends, RBC whole life policies provide guaranteed benefits and cash values
- Flexible rider options: RBC offers multiple riders, including the guaranteed insurability benefit, children’s term rider, accidental death benefit, waiver of premium, and YourTerm riders, allowing the client to customize their coverage as their protection needs change
How do you apply for RBC’s whole life insurance?
Choosing the right whole life insurance involves several important decisions, such as selecting the right plan, coverage level, and premium structure, that might become overwhelming. Here is how you can buy RBC whole life insurance policy with PolicyAdvisor:
- Speak with a licensed PolicyAdvisor expert
- Review RBC whole life insurance plans along with the other options available
- Receive a personalized illustration and finalize your application online
PolicyAdvisor offers free quotes at the best market rates and lifetime after-sales support to address any questions or adjustments you may need in the future. Schedule your free consultation with our licensed advisors today!
Frequently asked questions
Does RBC offer participating policies with dividends?
Yes. Both Growth Insurance and Growth Insurance Plus are participating policies that may earn dividends based on the participating account’s surplus. Dividends are credited on the policy anniversary and are not guaranteed. The available dividend options include cash payments, reduced premiums, interest-earning deposits, paid-up additions, and enhanced insurance.
What is the difference between RBC Growth Insurance and Growth Insurance Plus?
RBC Growth Insurance and RBC Growth Insurance Plus differ mainly in terms of their starting coverage amount and cash value accessibility. Growth Insurance offers lifetime coverage starting at $25,000, with cash value access after 5 years. Growth Insurance Plus requires a higher minimum coverage of $250,000 but offers cash value access after just one year.
What happens if I miss a premium payment for my RBC whole life policy?
If your policy has accumulated enough cash value, RBC may use it to cover premiums through an automatic premium loan. If the total loan balance, including interest, exceeds the policy’s net total cash value, the policy will lapse after 31 days unless the full outstanding balance is repaid.
Does RBC offer deposit option payments?
Yes, RBC offers a deposit option that lets you make payments in addition to the required premiums. These extra payments help increase the non-guaranteed cash value of your policy in the long term. The deposit option is available only if your chosen dividend option is paid-up additions or enhanced insurance and the premium payment period is 20-pay or life pay.
What is RBC’s current dividend scale interest rate?
RBC’s Dividend Scale Interest Rate (DSIR) is 6.30% for 2026. However, the DSIR is not a guaranteed return, and actual dividends can change based on the experience of RBC’s participating account.
Can I add riders to my RBC whole life insurance policy?
Yes, RBC offers several optional riders and benefits. Some of the riders that you can include in your policy are guaranteed insurability, children’s term insurance, accidental death benefit, waiver of premium, payor death and disability, and term riders.
Can I access the cash value of my RBC whole life policy?
Yes, you can access available cash value through policy loans, collateral, or withdrawals, subject to the policy terms. RBC also offers a premium offset option for eligible policies, allowing sufficient cash value to be used toward premium payments once the policy reaches the applicable offset date and other requirements are met.
Manulife whole life insurance review (2026)
Manulife offers permanent life insurance through Manulife Par, a participating whole life insurance policy designed to provide lifetime protection while building cash value over time. The policy combines guaranteed premiums, a guaranteed death benefit, and cash value growth with the potential to earn annual dividends. Manulife whole life insurance plans also come with limited pay options such as pay 10, pay 20, pay-to-90, and pay-to-100. Eligible applicants can also choose Manulife Par with Vitality Plus, which adds Manulife’s wellness rewards program and additional Vitality-related benefits to the core Manulife Par coverage.
Quick review
- PolicyAdvisor ratings: 5/5
- Best for: Added wellness rewards through the Vitality program
- Skip if: You want a broader range of dividend options than cash or paid-up insurance
See how much whole life insurance coverage you can get
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
About Manulife
Manulife operates as one of Canada’s largest participating life insurance platforms, supported by a $15.98 billion participating account. Its participating whole life insurance policies allow policyholders to share in the performance of the participating account through annual policy dividends, subject to the insurer’s dividend scale. For 2026, Manulife has maintained a 6.35% DSIR for participating whole life insurance policies.
Manulife’s financial strength
| AM Best Rating | A+ |
| Participating account fund size | $15.98 billion |
| LICAT ratio | 136% |
| Dividend scale interest rate (DSIR) | 6.35% |
Disclaimer: Figures and ratings are based on the latest available information and may change over time
What is Manulife whole life insurance?
Manulife whole life insurance is permanent life insurance that stays in place for life as long as the policy remains in force. Manulife’s core plan name is Manulife Par, and there is an option to opt for Manulife Par with Vitality Plus, which provides access to Manulife’s Vitality program. Both options offer cash value growth and guaranteed access to cash value in the early years. For 10-pay, 20-pay, and pay to age 90 plans, the coverage starts at $100,000. For pay to age 100, the coverage starts at $500,000.
Manulife Par with Vitality Plus™ gives the policyholder individual access to the maximum-value benefits of Manulife Vitality, the company’s flagship rewards program. Manulife Par with Vitality Plus™ offers only single life coverage, while Manulife Par offers single life and joint-last-to-die coverage options.
Key features of Manulife whole life insurance
| Policy issue age (min & max) |
|
| Coverage range (min) |
|
| Coverage options |
|
| Payment options |
|
| Policy fee | None |
| Dividend options | Cash or paid-up insurance (PUI) |
| Deposit option | Available with the paid-up insurance dividend option, subject to limits and administrative rules |
| Premium offset | Available. Uses the policy’s built-up value to help pay future premiums |
| Monthly Vitality charges |
– $15 for pay 10 years – $10 for pay 20 years – $6 for pay to age 90 – $4 for pay to age 100 |
| Riders |
|
Who is eligible for Manulife whole life insurance?
Manulife whole life insurance is available to those who meet the following requirements:
- Canadians who meet Manulife’s underwriting requirements
- Individuals aged between 0 and 80 years and 18-80 years for Manulife Par with Vitality Plus
- Individuals seeking at least $100,000 in coverage, although minimum coverage varies by payment option
What is covered under Manulife whole life insurance?
Manulife whole life insurance provides lifelong financial protection, with the policy’s key benefits including:
- Lifetime coverage: A guaranteed death benefit is paid to beneficiaries when the insured dies, or after the last death for joint last-to-die coverage
- Guaranteed cash value: The policy builds guaranteed cash value over time that can be accessed through withdrawals or policy loans
- Potential dividends: Participating policies may receive non-guaranteed dividends that can be taken as cash or used to purchase additional paid-up insurance
- Optional riders: Additional protection can be added through riders such as term insurance, total disability waiver, guaranteed insurability, and child protection riders
- Vitality benefits: Eligible policyholders can access wellness features and rewards through Manulife Vitality, depending on the policy and the insured person’s Vitality Status
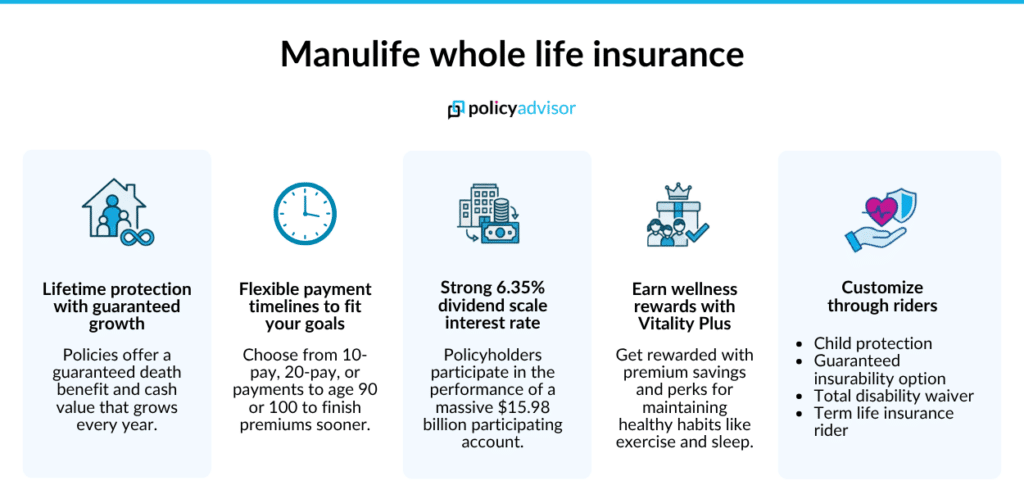
Types of Manulife Par whole life insurance
Manulife’s core participating whole life insurance product is Manulife Par, with an enhanced version that has Vitality Plus built in.
- Manulife Par: A participating whole life insurance plan that provides lifetime coverage, guaranteed premiums, guaranteed cash value growth, and a guaranteed death benefit. Policyholders may also receive annual dividends, which can be used to enhance the policy’s cash value and insurance coverage. The available coverage options are single life or joint last-to-die and include Vitality Go™ at no additional cost. The Vitality Go™ rewards you for leading a healthy lifestyle. Also, note that Vitality Go members can upgrade to Manulife Par with Vitality Plus anytime before the policy’s third anniversary
- Manulife Par with Vitality Plus: This version keeps the core participating whole life features of Manulife Par while building the Vitality Plus wellness program into the policy. With this policy, policyholders can earn rewards for participating in activities that promote healthier living, while the policy continues to provide guaranteed benefits and the potential for annual dividends. Manulife Par with Vitality Plus is available as single life coverage only
Manulife Par and Manulife Par with Vitality Plus:
| Features | Manulife Par | Manulife Par with Vitality Plus |
| Coverage amount | Starts at $100,000 for 10-year, 20-year, and pay-to-age-90 durations; $500,000 for pay-to-age-100 | Starts at $100,000 for 10-year, 20-year, and pay-to-age-90 durations; $500,000 for pay-to-age-100 |
| Payment duration options | 10 years, 20 years, to age 90, or to age 100 | 10 years, 20 years, to age 90, or to age 100 |
| Coverage options | Single life or joint last-to-die | Single life only |
| Eligibility for Vitality benefits | Access to Manulife Vitality Go™ benefits at no added cost | Access to maximum-value Manulife Vitality benefits |
| Upgrade option | Upgrade to Manulife Par with Vitality Plus before the 3rd anniversary (no underwriting required) | Not applicable |
| Issue age | 18-80 years | 18-80 years |
| Monthly Vitality® charge | Not applicable | – $15 for pay 10 years
– $10 for pay 20 years – $6 for pay to age 90 – $4 for pay to age 100 |
| Dividend options | Paid-up insurance or cash | Paid-up insurance or cash |
Pros and cons of Manulife whole life insurance
Manulife’s participating whole life policies offer a range of benefits such as immediate cash value growth, the option to choose the frequency and duration of premiums, and access to riders. Manulife also offers deposit option payments where the insured individuals can make direct premium payments and increase their protection.
A downside of Manulife’s whole life insurance is that Manulife does not offer non-participating plans, and some policy owners may find the dividend and returns structure complex.
| Pros | Cons |
| Choose from 10-pay, 20-pay, pay-to-90, and pay-to-100 options to match different financial goals | They offer only two dividend options, while other insurers typically offer more |
| Deposit option payments are available where policy owners can make additional premium payments to increase protection | Pay to age 100 requires at least $500,000 in coverage |
| Variety of riders offered by Manulife for different life events and needs | Joint coverage is not available with Vitality Plus |
| Manulife Par with Vitality Plus can provide wellness rewards and benefits in addition to life insurance coverage | |
| Available as single-life or joint-last-to-die coverage, depending on the policy type | |
| Immediate cash value growth and guaranteed cash value in the early years |
How much does Manulife whole life insurance cost?
The cost of Manulife whole life insurance for a 20-pay whole life insurance policy with $100,000 in coverage ranges from $246.20 to $620.71 per month. In the table below, we have listed the cost for a male and a female and how they vary with age.
Cost of Manulife whole life insurance (2026):
| Age (in years) | Male | Female |
| 20 | 246.20/month | 226.04/month |
| 30 | 291.59/month | 266.35/month |
| 40 | 331.71/month | 319.26/month |
| 50 | 394.61/month | 380.76/month |
| 60 | 459.84/month | 441.20/month |
| 70 | 678.46/month | 620.71/month |
*Illustrative monthly premiums for $100k of participating whole life insurance with a 20-pay premium period
What riders are available with Manulife whole life insurance?
Manulife offers several optional benefits with its whole life insurance, including waiver of premium, guaranteed insurability, child coverage, and additional term insurance.
- Total disability waiver rider: This rider can waive Manulife Par premiums if the insured becomes totally disabled for six months or longer. If the disability begins before age 60, premiums can be waived for as long as the disability continues. If total disability begins after age 60, premiums are waived until age 65, subject to the rider’s terms and conditions
- Guaranteed insurability option rider: This option allows you to purchase additional life insurance in the future without providing new medical evidence of insurability. The option can generally be exercised up to eight times on specified option dates in the policy contract or following qualifying life events, such as marriage or the birth or adoption of a child
- Child protection rider: This rider provides $10,000 of life insurance coverage for an eligible child of an insured person covered by the policy. When the child reaches age 25, they can purchase up to $250,000 of new life insurance coverage without additional underwriting, including up to $100,000 of critical illness coverage
- Term insurance rider: This option adds temporary term life insurance coverage to the permanent whole life policy. The coverage is available on a 10-year or 20-year renewable basis and can be structured on a single-life or combined basis. Through this, policyholders can convert the term coverage to a permanent Manulife life insurance plan available at the time of conversion up to age 75 without providing evidence of insurability
What factors affect the performance of Manulife’s participating account?
Manulife’s participating account is influenced by four key factors that can affect its performance and, ultimately, policy dividends:
- Claims experience: Higher-than-expected death claims can reduce the account’s funds, while lower claims can have a positive effect
- Policy cancellations: The number of policies cancelled or surrendered can affect the account’s expected cash flow and performance
- Expenses and taxes: Underwriting, administration, policy servicing, operating costs, and taxes affect the account’s overall performance
- Investment returns: Investment performance is a major factor. Returns above expectations can strengthen the account, while lower-than-expected returns can negatively affect it
Factors that influence Manulife’s participating accounts
| Factor | Predictability | Stability | Impact on performance |
| Claims experience | High | High | Low |
| Cancellations | Medium | Medium | Medium |
| Expenses & Taxes | High | High | Low |
| Investment Returns | Medium | Medium | High |
Does Manulife Par offer a disability benefit?
Yes, Manulife Par includes a built-in Disability Benefit that allows policyholders to access a portion of their policy’s cash value. The benefit can provide financial support if the insured becomes disabled.
To qualify, the insured must generally meet the definition of total disability or catastrophic disability:
- Total disability (ages 18 to 65): The insured is unable to perform their regular occupation or, if unemployed, their regular daily activities
- Catastrophic disability (from age 18): The insured is unable to perform an activity of daily living or experiences the total and permanent loss of sight, hearing, speech, or use of their hands or feet, or suffers qualifying cognitive impairment
This benefit comes with a 30-day elimination period, and only one payment can be made in any 12-month period. Since payments are taken from the policy’s cash value, each payment will also reduce the policy’s death benefit.
What is Manulife Vitality?
Manulife Vitality is a wellness-enhanced insurance program that rewards policyholders for maintaining healthy habits. It’s designed to encourage better lifestyle choices and make wellness a part of your insurance experience.
When you are enrolled, you earn Vitality Points for completing everyday health activities like walking, exercising, getting a flu shot, sleeping well, or meditating. As your points increase, your Vitality Status improves from Bronze to Silver, Gold, and Platinum, unlocking greater rewards and premium savings. These can include discounts on leading brands, fitness devices, and even travel or entertainment perks.
There are two versions of the program: Vitality Go™, which is included at no cost with all eligible plans, and Vitality Plus™, which offers enhanced benefits and exclusive rewards, such as the opportunity to earn a free Apple Watch®, for a small monthly fee. Manulife Vitality is also available with health and dental insurance to help members integrate wellness into both their financial and physical health goals.
What premium options does Manulife offer?
Manulife Par offers four payment schedules: 10-pay, 20-pay, pay to age 90, and pay to age 100. Each one lets you finish paying for the policy on a different timeline.
- 10-pay: Premiums are payable for 10 years, after which the policy becomes paid-up for life
- 20-pay: Premiums are payable for 20 years, and the policy is fully paid-up once that period ends
- Pay to age 90: Level premiums continue until the insured reaches age 90, with lifetime coverage following the final payment
- Pay to age 100: Level premiums continue until age 100. This option typically includes a higher minimum coverage amount, often $500,000 or more
For 10-pay, 20-pay, and pay to age 90, the coverage starts at $100,000, while for pay to age 100, the minimum coverage is $500,000.
Can a Manulife Par joint last-to-die policy be replaced with a single-life policy?
Yes, a Manulife Par joint last-to-die policy can be replaced with one or two single-life Manulife Par policies. This can be done without new evidence of insurability if their marriage or business partnership ends. This can help each policyholder maintain individual permanent life insurance coverage after the relationship or partnership is dissolved. The replacement option is available before the fifth policy anniversary, provided the policyholders are 65 or younger, and the original joint policy has a standard joint rating. Manulife must approve the replacement.
Can you change the premium payment period on a Manulife Par policy?
Yes, Manulife Par policyholders may be able to change their premium payment period to a longer duration, subject to Manulife’s administrative rules and policy conditions. The available changes include:
- 10-pay → 20-pay: Change from paying premiums for 10 years to paying them for 20 years. Request must be received before the 5th policy anniversary
- 10-pay → Pay-to-90: Extend the premium payment period from 10 years to payments up to age 90. Request must be received before the 5th policy anniversary
- 20-pay → Pay-to-90: Change from a 20-year premium period to payments up to age 90. Request must be received before the 10th policy anniversary
This option can help policyholders spread their premium payments over a longer period, potentially making the ongoing premium commitment more manageable. Moreover, you cannot change to a shorter premium duration, switch to Pay to age 100, or change only part of the policy’s premium duration. Changing the premium duration will also reduce the policy’s guaranteed cash value, with the released amount refunded to the policy owner.
Does Manulife Par offer compassionate assistance?
Yes, Manulife Par includes a complimentary, non-contractual Compassionate Assistance Program. If the insured person becomes terminally ill and death is imminent, the policy owner may request early access to a portion of the death benefit through a collateral loan from Manulife.
The loan is provided on a tax-free basis, subject to applicable tax laws, with the policyholder responsible for the loan interest and any physician fees required to complete the application. The policy remains in force after the loan is provided, but the outstanding loan amount plus accrued interest is deducted from the death benefit payable to beneficiaries. Once a Compassionate Assistance loan has been issued, no further withdrawals can be made from the policy under this benefit.
Compare dividend rates from top Canadian insurers
| 2022 | 2023 | 2024 | 2025 | 2026 | |
|---|---|---|---|---|---|
| Equitable | 6.05% | 6.25% | 6.40% | 6.40% | 6.40% |
| Manulife | 6.10% | 6.35% | 6.35% | 6.35% | 6.35% |
| iA Financial Group | 5.75% | 6.00% | 6.25% | 6.35% | 6.35% |
| Desjardins Insurance | 5.75% | 6.20% | 6.30% | 6.30% | 6.30% |
| RBC Insurance | 6.00% | 6.00% | 6.25% | 6.30% | 6.30% |
| Sun Life | 6.00% | 6.00% | 6.25% | 6.25% | 6.25% |
| Empire Life | 6.00% | 6.00% | 6.00% | 6.25% | 6.25% |
| Foresters Financial | 5.50% | 5.50% | 5.50% | 6.25% | 6.25% |
| Co-operators | 5.90% | 5.90% | 6.00% | 6.00% | 6.00% |
| Assumption Life | 5.75% | 5.75% | 5.75% | 5.75% | 5.80% |
| Canada Life | 5.25% | 5.50% | 5.50% | 5.75% | 6.00% |
Powered by
How does Manulife compare to other whole life insurance providers?
Manulife whole life insurance stands out for its participating Manulife Par product, multiple premium payment options, and guaranteed cash value growth. Its 10-pay, 20-pay, pay-to-90, and pay-to-100 options give you flexibility to match premium payments with your long-term financial goals. It also offers Manulife Par, with Vitality Plus adding wellness features and rewards to your whole life insurance plan. To see how Manulife compares with other leading insurers, read our guide to the best whole life insurance companies in Canada.
Our advisor’s take on Manulife whole life insurance
At PolicyAdvisor, one of our advisors recently helped a client, aged 45, who was looking for permanent life insurance with a clear premium payment timeline. The client’s primary goal was to finish paying for the policy before retirement while keeping lifelong coverage in place.
Client profile:
- Age: 45-year-old non-smoking Canadian
- Coverage need: $500,000 in permanent coverage to support family protection and long-term estate planning
- Primary concern: Finishing premium payments before retirement while keeping lifelong coverage in place
- Our comparison: We compared Manulife Par with participating whole life products from other leading Canadian insurers, focusing on premium payment periods, guaranteed values, dividend potential, and available riders and benefits
Why Manulife stood out:
- Multiple premium payment periods, including 10-pay, 20-pay, pay-to-90, and pay-to-100, allowing the client to choose a premium schedule that fits their long-term financial goals. For this client, the shorter payment options made it possible to structure the policy so premiums could be completed before retirement while the coverage stayed in force for life.
- Lifetime coverage with guaranteed values, providing permanent protection along with guaranteed cash value growth
- Manulife Vitality Plus option, providing wellness features and rewards that encourage healthy living while adding value to the permanent life insurance policy
- Flexible policy enhancements, including the Guaranteed Insurability Option, Term Insurance Rider, Total Disability Waiver, and Child Protection Rider, allowing the client to adapt coverage to changing needs
How to buy Manulife whole life insurance?
To apply for a Manulife whole life plan, you would need to choose the plan type (Manulife Par or Manulife Par with Vitality Plus™), choose your coverage options, fill in an application form, and submit it. Your policy may also require medical underwriting based on your plan specifics.
For the best Manulife whole life insurance policy quotes, speak to our experts at PolicyAdvisor. Our licensed advisors will help you choose a plan and coverage options that best suit your needs and budget. We will also support you with the application, making the entire process seamless and easy for you!
Frequently asked questions
Does Manulife offer participating policies with dividends?
Yes, Manulife offers participating whole life policies with dividends. Dividends can either be used to buy more insurance, or they can be withdrawn as cash. In case policy owners choose to withdraw the dividends, there may be some tax implications.
Is Manulife whole life worth it?
Yes, Manulife’s whole life insurance can be worth it, especially for people looking for a policy that builds cash value and provides long-term protection at affordable rates. Their policies are designed to help build wealth with dividend options that can be used to either buy more insurance or be withdrawn as cash. Manulife also offers exclusive benefits with its Vitality program, making its whole life insurance plans an ideal option for those looking for complete protection.
Can you borrow against the cash value?
Yes, you can request a cash loan, which is typically subject to Manulife’s administrative rules. The maximum amount you may borrow is 90% of the total available cash value minus any outstanding policy loan balance.
What are the premium payment options for Manulife whole life insurance?
Manulife Par offers four premium payment options: 10-pay, 20-pay, pay-to-90, and pay-to-100. This allows policyholders to select a payment schedule based on their financial goals and how quickly they want to complete premium payments.
What riders are available with Manulife whole life plan?
Manulife Par offers optional benefits such as the term insurance rider, total disability waiver, guaranteed insurability option, and child protection rider. These options can provide additional protection or help policyholders increase their coverage as their needs change, but they come with additional premiums.
What is Manulife Par with Vitality Plus?
Manulife Par with Vitality Plus combines participating whole life insurance with a wellness program that rewards eligible policyholders for healthy-living activities. It provides the same core whole life insurance features of Manulife Par while adding wellness-related benefits and rewards. It is available on a single life basis only.
What dividend options does Manulife offer?
Manulife offers paid-up insurance and cash that can be taken out or used for premium reduction. If you choose the paid-up insurance option, your annual dividends are used to automatically buy additional, fully paid-up insurance. This means that once your dividends have been used to purchase additional coverage, you do not need to make any further premium payments for the paid-up insurance. If you choose the cash option as your dividend strategy, the annual dividends you receive are paid directly to you. In this case, there may be some tax implications.
How are Manulife’s whole life insurance dividends distributed?
Dividends are allocated to Manulife Par policyholders using a dividend scale. A dividend scale is a formula used by all insurance companies to fairly and equitably distribute the dividends among all the policy owners. The dividend scale is not guaranteed and usually increases or decreases based on the participating account’s performance.
Where does Manulife invest the participating account’s premiums?
Manulife invests the participating account’s funds in public bonds, real estate, public and private equities, mortgages, and private debt. This diversified portfolio helps generate steady long-term returns while maintaining stability for policyholders.
Best whole life insurance companies in Canada (2026)
Choosing among Canada’s whole life insurers is genuinely difficult: dozens of companies sell participating policies, and each markets strong dividends, long-term cash value growth, and flexible coverage. At PolicyAdvisor, our team compared leading Canadian insurers to determine the best whole life insurance companies across different needs and profiles.
Quick glance
Here are the top 15 whole life insurance companies in Canada that stand out for their combination of strong performance and flexible plans.
| Insurance company | Key strength / Best known for |
| Equitable Life | Mutual company |
| Manulife | Overall performance |
| Empire Life | Balanced performance |
| Sun Life | High-net-worth individuals |
| Foresters | Smokers |
| BMO Insurance | Non-participating plans |
| Canada Life | Charitable giving |
| Canada Protection Plan | Non-medical coverage |
| Desjardins | Early and flexible pay-off |
| iA (Industrial Alliance) | Health accommodation |
| RBC Insurance | Children’s plans |
| Assumption Life | Quick-issue coverage |
| Beneva | Complimentary built-in features |
| UV Insurance | Long-term growth |
| Wawanesa | Guaranteed benefits |
Discover why these companies earned their place in our top 15 below.
Best whole life insurance companies in Canada for 2026
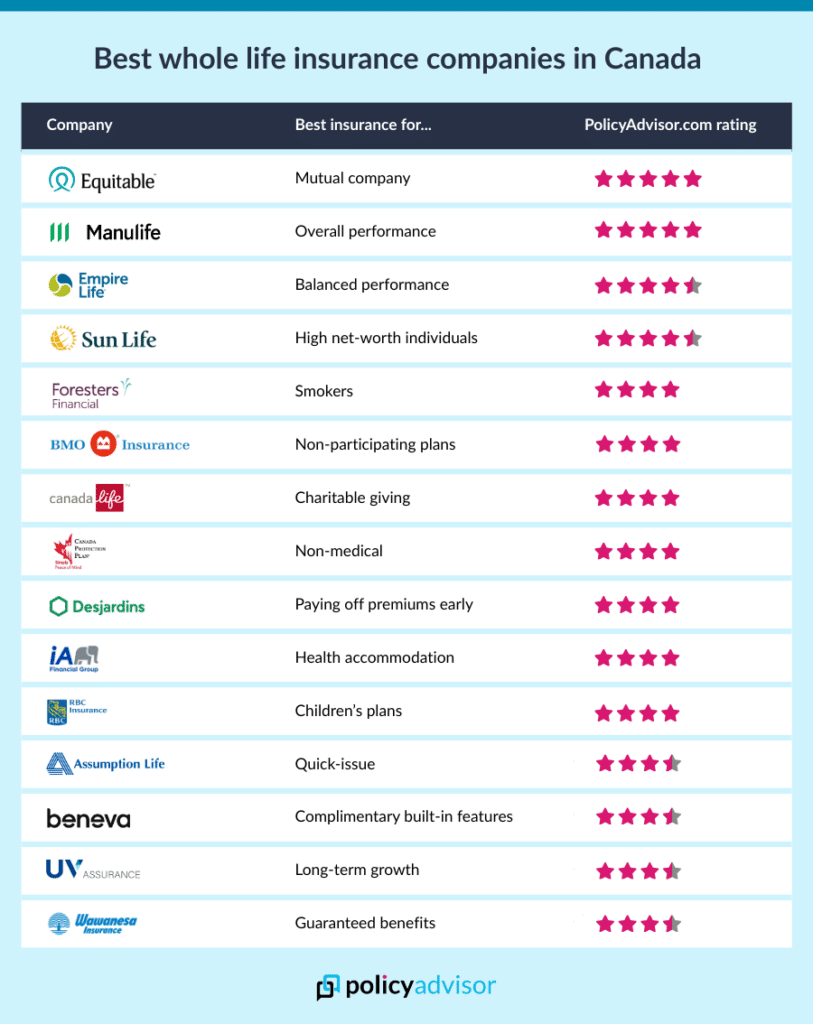
1. Equitable Life: Best for mutual company
Equimax Wealth Accumulator
20-pay
Life-pay
Our advisor’s take:
We give Equitable Life 5/5 because it stands out as one of Canada’s strongest whole life providers, particularly for Canadians who value the long-term security of a true mutual company.
The company supports its participating plans, Equimax Estate Builder and Equimax Wealth Accumulator, with a growing $3.2 billion par fund, demonstrating its financial strength and commitment to stable, long-term results. Both plans offer 10-pay, 20-pay, and Life Pay options.
Equimax Wealth Accumulator is built for earlier cash value access, making it ideal for clients who want flexible liquidity for education, business needs, or retirement planning. Conversely, Equimax Estate Builder emphasizes long-term value and supports estate planning by helping cover taxes and fees at death.
Equimax participating whole life policies include Equitable’s built-in KIND program. It provides compassionate advances (up to 50% of the base coverage amount, maximum $100,000) and snap advances (up to $25,000), a living benefit that gives a lump sum payment from the policy cash value in cases of severe mental or physical disability, and bereavement counselling benefits (up to $1,000).
Equitable Life’s key financial strengths:
- $3.2 billion participating fund
- 6.40% dividend scale interest rate, held above 6% for more than 12 consecutive years
- 30-year average return of 7.35% to 7.72%
- Very low volatility. A 1.74% standard deviation over 30 years, among the steadiest in Canada
- Par fund asset mix: 49% fixed income, 38% non-fixed income, 2% cash, 11% policy loans
Why choose Equitable Life
- Stable long-term returns with low volatility
- A diversified par-fund portfolio supporting long-term growth
- Participating policyholders can share in the earnings of the participating account through dividends
- Conservative, disciplined fund management
Unique selling point (USP): Equimax Estate Builder and Equimax Wealth Accumulator suit buyers who want stable long-term value, potential dividends, and accessible cash value from a trusted mutual insurer.
Equimax Estate Builder: Slower early growth; strong long-term value
Equimax Wealth Accumulator: Faster early growth; accessible sooner
Paid-up additions (PUA), enhanced protection, cash, premium reduction, and on deposit
2. Manulife: Best for overall performance
Manulife Par with Vitality Plus
20-pay
pay-to-90
pay-to-100
Our advisor’s take:
Manulife earns a 5/5 as the strongest all-around pick for buyers who want capital strength, global diversification, and disciplined risk management behind their policy.
Manulife Par and Manulife Par with Vitality Plus plans provide lifetime coverage with 10-pay, 20-pay, Pay to Age 90, and Pay to Age 100 options. A multi billion dollar participating account backs the plans, supporting long-term guarantees, stable dividends, and reliable performance for policyholders.
Manulife Par focuses on stable long-term growth with guaranteed premiums, immediate cash value buildup, and annual dividend payouts. Manulife Par with Vitality Plus offers strong early guaranteed cash values while also providing access to the Manulife Vitality program, which rewards healthy living with perks and member benefits.
Program features vary by eligibility and do not reduce premiums for participating whole life, but achieving higher Vitality status (like Gold or Platinum) can result in an additional Vitality Dividend.
Manulife’s key financial strengths and performance:
- Multi‑billion‑dollar participating account
- 6.35% dividend scale interest rate
- 136% LICAT ratio, among the highest capital-strength levels in Canada
- Diversified global operations across Canada, the U.S., and Asia
- Global operations spanning Canada, the U.S., Asia, and asset management
- Strong balance sheet supported by investment-grade assets
- Disciplined risk-management framework supporting long-term stability
Why choose Manulife
- Exceptionally strong capitalization supports long-term dividend stability
- Global diversification reduces performance volatility
- Consistent profitability from core earnings and disciplined risk management
- Vitality wellness program and underwriting analytics add ongoing value
Unique selling point (USP): Manulife Par and Manulife Par with Vitality Plus, suit buyers who want affordable lifetime coverage, flexible payment terms, and steady cash value.
Manulife Par: Cash value starts after 1 year (for most age and payment structures)
Manulife Par with Vitality Plus: Cash value begins after year 1; includes Vitality benefits
Paid-up additions (PUA), term additions (enhanced coverage), cash, premium reduction, and dividends on deposit
3. Empire Life: Best for balanced performance
Optimax Wealth (plus non-participating Solution Series)
10-pay
20-pay
Life-pay (varies by plan)
Our advisor’s take:
We give Empire Life 4.5/5 because its whole life plans offer balanced, steady performance, making it a top choice for Canadians seeking reliable long-term value. The company backs its participating plans, EstateMax and Optimax Wealth, with a disciplined $1.32 billion par fund renowned for stability and long-term results.
EstateMax focuses on estate growth, offering steady dividend performance and strong long-term accumulation. In comparison, Optimax Wealth provides stronger early cash value accumulation.
Optimax Wealth offers 8 Pay, 10 Pay, 20 Pay and Life Pay to age 100 options, while EstateMax offers 10 Pay, 20 Pay and Life Pay options. Empire Life also offers the Solution Series, which includes a permanent non-participating plan called Solution 100 with level premiums payable to age 100.
Empire Life’s key financial strengths:
- $1.32 billion participating fund
- 6.25% dividend rate
- 30-year average return of 6.97%
- Par fund asset mix: 64% bonds, 37% in commercial mortgages, equities, and cash
- A long-duration bond structure with smoothing to reduce volatility
Why choose Empire Life:
- Stable historical participating account returns with relatively low volatility
- A consistent dividend track record that supports confident planning
- Solid cash-value access over time
- Well suited to conservative estate planning
Unique selling point (USP): EstateMax and Optimax Wealth suit buyers who want steady cash accumulation and consistent dividend performance.
EstateMax: Focuses on steady long-term growth and estate planning
Optimax Wealth: Focuses on higher early cash value accumulation
Paid-up additions (PUA), enhanced coverage, cash payment, annual premium reduction, and cash accumulation (deposit)
4. Sun Life: Best for high-net-worth individuals
Sun Par Accumulator II
SunSpectrum Permanent Life II
20-pay
Life Pay (varies by plan)
Our advisor’s take:
We give Sun Life 4.5/5 for being a leading choice for high-net-worth Canadians who want whole life insurance backed by exceptional global diversification and long-term financial strength. Sun Life backs its Par Protector II, Par Accumulator II, and Par Accelerator with a $21.2 billion par fund. This fund supports more than 400,000 active participating policies, making it one of the strongest par structures in Canada.
The Protector II and Accumulator II provide flexible payment options, including Life Pay, 10-pay, and 20-pay, while Accumulator II emphasizes early cash-value growth, allowing easier access to funds for investments, business needs, or other financial goals through policy loans or withdrawals.
Meanwhile, Sun Par Protector II focuses on maximizing long-term death benefit growth for estate and legacy planning. SunSpectrum Permanent Life II also offers Life Pay, 10-pay, and 20-pay payment structures.
Sun Life’s key financial strength
- $21.2 billion participating account backing 400,000+ active policies
- 6.25% dividend scale interest rate
- 145% LICAT ratio, among the strongest of the major Canadian insurers
- Earnings diversified across Canada, the U.S., and Asia
- Consistent profitability from both insurance and wealth-management operations
Why choose Sun Life
- Global diversification supports long-term performance stability
- Exceptional capital strength backs long-term guarantees
- Participating whole life options designed for both estate planning and cash value accumulation
- Strong fit for affluent and corporate tax-efficient planning
Unique selling point (USP): Sun Par Protector II, and Sun Par Accumulator II suit buyers who want lifetime protection paired with strong cash-value potential and estate-planning power.
Sun Par Protector II: Cash value begins after year 5
Sun Par Accumulator II: Cash value begins after year 1
Paid-up additions (PUA), enhanced insurance, cash payment, annual premium reduction, and dividends on deposit
5. Foresters Financial: Best for smokers
Advantage Max
Non-Par Whole Life
20-pay
pay-to-100
Our advisor’s take:
We give Foresters Financial 4/5 for being a top choice for smokers and former smokers, who need more flexible underwriting. The insurer leverages a strong Canadian capital position, including a Life Insurance Capital Adequacy Test (LICAT) ratio of 188% and $2.3 billion in surplus. This robust financial strength enables Foresters to accept higher-risk applicants while actively maintaining dependable long-term guarantees and stable dividends.
Advantage Plus offers early cash value accessibility, dependable long-term guarantees, and dividend-driven growth, making it an attractive option for Canadians who may face stricter underwriting at larger insurers. Foresters also offer permanent plans that feature guaranteed cash values. Advantage Max offers coverage from $50,000 to $20,000,000 and 10-Pay, 20-Pay and Pay to 100 premium payment plans.
Foresters’ key financial strengths:
- 188% LICAT ratio, indicating excellent capital adequacy
- $2.3 billion in surplus / net assets
- Member-owned (fraternal) structure
Why choose Foresters:
- Flexible underwriting for smokers and former smokers
- Strong financial resilience backing long-term guarantees
- A member-first model that directs value back to policyholders
- Added perks: wellness rewards, scholarships, community grants, family support programs
Unique selling point (USP): Advantage Max is a strong fit for smokers due to its quit smoking incentive plan.
Advantage Plus II: Cash value begins after year 1
Foresters Non-Par Whole Life: Guaranteed cash values; slower growth
Advantage Max: Guaranteed cash value with an option to purchase more paid-up insurance
Paid-up additions (PUA), dividends on deposit, cash payment, enhanced insurance, and annual premium reduction
6. BMO: Best for non-participating whole life insurance
Wealth Accelerator
20-pay
pay-to-100
Our advisor’s take:
BMO is a 4/5 for buyers who want guaranteed values and predictable premiums without dividend-related ups and downs. The company offers two plan options, Estate Protector and Wealth Accelerator, both of which exclude a participating account or dividends. These plans set themselves apart with a Performance Bonus (6.00% effective for the 2026/2027 period, updated from 5.75%), increasing both the death benefit and cash value without relying on traditional dividends.
Estate Protector is designed for long-term estate planning, offering strong guaranteed cash value growth and a steadily increasing death benefit to help preserve wealth and offset taxes at death (e.g., deemed disposition and probate fees). Wealth Accelerator provides faster guaranteed cash value accumulation and higher early liquidity, making it an attractive option for business owners and high-income earners who want accessible long-term value. Both plans are available with 10-pay, 20-pay, and pay to 100 premium options.
BMO’s key financial strengths
- $88 million in net insurance income for Q3 2026
- 6% performance bonus, enhancing both the death benefit and cash value
- Backed by BMO Wealth Management’s broader risk management and diversified earnings
Why choose BMO
- Consistently growing insurance profitability
- A competitive guaranteed bonus rate strengthens policy values
- Diversified revenue sources add stability
- Benefits from BMO’s operational scale and risk oversight
Unique selling point (USP): Estate Protector and Wealth Accelerator suit buyers who want lifetime coverage with guaranteed values and additional growth through the performance
Estate Protector: Strong guaranteed values; long-term estate growth
Wealth Accelerator: Faster liquidity; quicker cash-value access
Not applicable. A performance bonus purchases paid-up additions instead of a traditional dividend
7. Canada Life: Best for charitable giving
Wealth Achiever
Balanced Achiever
My Par Gift
20-pay
pay-to-100
Our advisor’s take:
We give Canada Life 4/5 for being the leading choice for buyers who want to structure their whole life around charitable giving. Its My Par Gift plan is specifically designed for charitable contributions, with a single premium and cash value building in the early years.
Canada Life’s participating lineup, Estate Achiever, Wealth Achiever, Balanced Achiever, and My Par Gift, is backed by one of the largest and most stable participating accounts in the country. It’s anchored by a $61.9 billion par fund, the largest in Canada.
Estate Select focuses on long-term growth, helping maximize the death benefit for estate planning. Wealth Select, on the other hand, is designed for earlier cash value access, allowing for withdrawals or policy loans when needed. Both plans come with flexible payment options, including 10-pay, 20-pay, and pay to 100, while My Par Gift requires a single premium.
Canada Life’s key financial strengths
- $62.8 billion participating fund (the largest in Canada) backing roughly 1.4 million in-force policies
- 6.00% Dividend Scale Interest Rate
- Formal governance covering liability matching, liquidity, tax considerations, and interest-rate risk
- Cash-flow-matched asset-liability management
- Asset mix: 60.5% fixed income, 30.5% non-fixed income (real estate, public and private equity)
Why choose Canada Life
- Deep diversification and scale support exceptional long-term stability
- A balanced asset mix aims for steady returns across market cycles
- Disciplined asset-liability management reduces volatility
- Strict governance protects long-term policyholder value
Unique selling point (USP): My Par Gift suits buyers who want charitable giving handled through single-premium simplicity.
Estate Achiever: Cash value starts in year 1, with a focus on long-term growth and maximizing the death benefit for estate planning
Wealth Achiever:Cash value from year 1; earlier access via withdrawals or loans
Balanced Achiever: Cash value from year 1; earlier access via withdrawals or loans
My Par Gift: Builds over time; accessible to the designated charity
Paid-up additions (PUA), enhanced coverage, cash payment, annual premium reduction, and dividends on deposit
8. Canada Protection Plan: Best for non-medical whole life insurance
Preferred Elite
Simplified Elite
Deferred Life
Guaranteed Acceptance Life
Deferred
Deferred Life
Life-pay
Our advisor’s take:
We give Canada Protection Plan (CPP) 4/5 for being a leading choice for Canadians who want life insurance without medical exams, offering fast approvals and guaranteed lifetime coverage. Its lineup of non-participating permanent and term plans, including Express Elite (Term), Simplified Elite, Guaranteed Acceptance Life, and Deferred Life, provides predictable premiums, stable cash values, and simplified underwriting for applicants with various health profiles. As part of Foresters Financial, Canada Protection Plan is backed by a Life Insurance Capital Adequacy Test (LICAT) ratio of 188% and consolidated surplus of $2.3 billion, giving policyholders confidence in the company’s long-term financial strength and the security of their coverage.
A 4/5 as the top pick for buyers who want whole life coverage without a medical exam, with fast approvals and guaranteed-acceptance options. CPP operates as part of Foresters Financial.
Canada Protection Plan’s key financial strengths:
- Backed by parent company Foresters Financial: 188% LICAT ratio and $2.3 billion consolidated surplus
- $662 million in claims paid in 2025 in North America
- A member-focused structure that reinvests surplus into member programs, scholarships, and community support
Why choose Canada Protection Plan
- Canada’s largest provider of no-medical life insurance
- Accepts a wide range of health profiles, including smokers and higher-risk applicants
- Guaranteed, non-participating pricing with no dividend risk
- Higher maximum issue ages and a Quit Smoking incentive
- Fast digital application process with e-signatures
Unique selling point (USP): CPP is the strongest fit for buyers who want no-medical whole life with fast approval and guaranteed lifetime coverage.
Across the plan lineup: Cash values on Guaranteed Acceptance, Deferred, Deferred Elite, Simplified Elite, Preferred, and Preferred Elite generally begin at after policy year 5
None
9. Desjardins: Best for early and flexible pay-off
Estate Enhancer
Accelerated Growth
10-pay
20-pay
pay-to-100 (varies by plan)
Our advisor’s take:
Desjardins is a 4/5 for buyers who want to pay off a whole life policy quickly. It is one of the only insurers offering a genuine 5-pay participating option alongside the standard 10-pay, 20-pay, pay to 100 structures across its par lines.
The company backs its participating lineup with one of the strongest capital positions in Canada, maintaining a Tier 1A capital ratio of 23.2% (as of Q1 2026).
The flagship 5-Pay PAR plan completes premiums in just five years while still building strong early cash values. Desjardins serves millions of members and clients across its extensive cooperative financial and insurance portfolio.
Its participating lineup includes three plans: 5-Pay PAR, Estate Enhancer, and Accelerated Growth. Estate Enhancer focuses on long-term estate value and strong future growth, while Accelerated Growth prioritizes earlier cash value access with long-term accumulation potential.
Desjardins’ key financial strengths and performance
- 6.30% Dividend Scale Interest Rate (DSIR)
- 23.2% Tier 1A capital ratio, well above regulatory requirements
- $3.81 billion in annual surplus earnings and $960 million in Q1 2026 surplus earnings before member dividends
- Millions of policyholders across its life and health portfolio
- A co-operative ownership model that reinvests profit into members
Why choose Desjardins
- One of the only 5-pay participating whole life plans in Canada
- Co-operative structure reinvests profit into member value
- Strong capital ratios safeguard dividend durability
- A flexible product range spanning fast-pay to long-term accumulation designs
Unique selling point (USP): The 5-Pay PAR plan delivers fully paid-up coverage in five years while still building early cash value.
5-Pay PAR: Steady long-term growth
Estate Enhancer: Steady long-term growth
Accelerated Growth: Fastest cash-value access, concentrated in years 10–15
5-Pay PAR: Enhanced insurance
Estate Enhancer and Accelerated Growth: Paid-up additions (PUA), annual premium reduction, cash payment, deposits at interest, and enhanced insurance
10. Industrial Alliance (iA): Best for health accommodation
iA PAR Estate
iA PAR Wealth
Life and Serenity 65
20-pay
pay-to-100
Our advisor’s take:
A 4/5 for who need whole life insurance with more flexible underwriting, making it especially appealing for clients with health conditions or non-standard risk profiles.
iA also offers Canadians whole life solutions for different needs: Child Life and Health Duo combines life and critical illness coverage for children and provides non participating coverage with early protection and gradual long-term growth, while Life and Serenity 65 delivers non-participating coverage with disability and illness benefits, with cash values beginning in later policy years.
Additionally, iA PAR Estate and iA PAR Wealth are backed by a $330 million par account and offer flexible premium options, including 10-pay, 20-pay, and pay to 100. iA PAR Estate focuses on long-term growth of total surrender value and death benefit, while iA PAR Wealth prioritizes short-term growth by maximizing total cash surrender value in the early years, alongside long-term estate growth.
iA’s key financial strengths
- $330 million participating fund
- 15.1% return on equity (17.5% core ROE)
- 137% solvency ratio
- A diversified business spanning Individual Insurance, Group Benefits, Wealth, and U.S. operations
Why choose Industrial Alliance (iA)
- Delivers strong and growing earnings, contributions broadly across Individual Insurance, Wealth, Group, and U.S. operations
- Supports reduced volatility with a highly diversified business model and multiple profit streams beyond life insurance
- Demonstrates robust financial strength, boasting a 132% solvency ratio and strong organic capital generation that sustains long-term par stability
- Leads market position, ranks number one in segregated fund sales and strong momentum in Individual Insurance
- Consistently generates profitability, reflected in a 16.1% core ROE, demonstrating durable earning power for sustaining long-term guarantees
- Strategically expands through acquisitions, which strengthens distribution and recurring revenue sources
Unique selling point (USP): iA PAR Estate and iA PAR Wealth suit buyers with health conditions who need underwriting flexibility.
Child Life and Health Duo: Gradual long-term growth with early protection
iA PAR Estate: Long-term cash value accumulation
iA PAR Wealth: Early access to cash value
Life and Serenity 65: Cash values begin in later policy years
Paid-up additions, premium reduction, cash, deposit with interest (Child Life and Health Duo, iA PAR Estate, iA PAR Wealth)
11. RBC Insurance: Best for children’s plans
RBC Growth Insurance Plus
20-pay
pay-to-100
Our advisor’s take:
We give RBC Insurance 4/5 as the top choice in Canada for families who want whole life insurance designed specifically to protect a child’s long-term future. RBC backs its participating plans, Growth Insurance and Growth Insurance Plus, with a growing participating account backed by RBC’s institutional strength. Both plans feature the Juvenile Guaranteed Insurability Benefit, which lets a child buy additional coverage later without a medical exam.
Growth Insurance focuses on tax-deferred accumulation and a steadily increasing death benefit, making it ideal for long-term family legacy planning. Growth Insurance Plus accelerates cash value access with cash values accessible after the first policy year, giving families greater flexibility for education, investment opportunities, or liquidity needs through policy loans or collateral.
Growth Insurance focuses on tax-deferred accumulation and a steadily increasing death benefit, making it ideal for long-term family legacy planning. Growth Insurance Plus accelerates cash value access, giving families greater flexibility for education, investment opportunities, or liquidity needs through policy loans or collateral.
RBC’s key financial strengths
- $51.39 million participating fund
- 6.30% dividend rate (officially maintained for the April 1, 2025 to March 31, 2026 period)
- Stable long-term DSIR history
- Serves more than 5 million clients across diversified segments
- A 50/50 target asset mix between fixed income and non-fixed income (including commercial real estate)
Why choose RBC
- Smoothing techniques help stabilize returns and support consistent dividends
- Scale across a large client base supports long-term stability
- A balanced 50/50 allocation aligns growth with risk control
- Disciplined oversight aims to maximize policyholder value
Unique selling point (USP): RBC Growth Insurance and Growth Insurance Plus suit families who want guaranteed cash values, long-term growth, and early access to funds when needed.
RBC Growth Insurance: Cash values accessible after policy year 5
RBC Growth Insurance Plus: Faster early cash value accumulation with liquidity accessible after year 1
Paid-up additions (PUA), cash payments, reduced premiums, interest-earning deposits, and enhanced insurance
12. Assumption Life: Best for quick-issue policies
ParPlus Junior
Non Par (Golden Protection, Platinum Protection, Silver Protection, Bronze Protection)
pay-to-100
Our advisor’s take:
We give Assumption Life 3.5/5 for offering some of Canada’s strongest fast-approval permanent insurance options, making it an excellent fit for clients who want lifetime coverage without medical exams or long underwriting queues. Backed by a 167% solvency ratio and more than 120 years as a Canadian mutual insurer, Assumption Life provides a highly stable foundation for its quick-issue non-participating including Golden Protection, Platinum Protection, etc).
These plans pair simplified, primarily digital applications with streamlined underwriting and rapid decisions, and are available with flexible payment options such as pay to 100 and select limited-pay structures, giving clients guaranteed premiums, level lifetime coverage, and predictable long-term costs.
Assumption Life’s key financial strengths:
- 5.75% dividend rate (applicable to their ParPlus participating line, as Golden Protection and FlexOptions are non-par/universal life products)
- 167% solvency ratio
- $12 million in net earnings
- $2.6 billion in total assets
- $212 million in policyholder’s equity
- Mutual ownership structure
Why choose Assumption Life:
- A mutual model that prioritizes long-term policyholder value
- High surplus and solvency levels back long-term guarantees
- A largely digital, streamlined underwriting and application process
- Disciplined balance between growth and risk
- Simplicity and speed for buyers who want guaranteed, no-exam coverage
Unique selling point (USP): Assumption Life is the strongest fit for fast approvals and simplified underwriting on guaranteed, no-exam whole life.
ParPlus: Dividend‑based cash accumulation with guaranteed cash values
ParPlus Junior: Guaranteed cash value growth plus annual dividends
Platinum Protection Whole Life: Guaranteed cash surrender values beginning after year 5
Golden Protection Whole Life: Guaranteed cash values with steady growth
Silver Protection: Guaranteed cash values with gradual buildup
Bronze Protection: Guaranteed cash values with graded accumulation
Paid-up additions, enhanced coverage, cash, premium reduction, and deposits at interest
13. Beneva: Best for complementary additional features
Whole Life Superior Value 100
Enhanced Term 100
20-pay
pay-to-100
PolicyAdvisor Rating
We give Beneva 3.5/5 for being an excellent choice for Canadians who want non participating whole life insurance. Beneva is a mutual company, which often aligns with participating policies, but mutual status alone doesn’t guarantee a par product exists. In Beneva’s case, their whole life line is structured as non‑par, with value delivered via builtin features and cash values rather than dividends.
Supported by a $29.2 billion asset base and a 163% solvency ratio, Beneva’s whole life plan offers lifetime protection with complimentary benefits designed to enhance coverage, service, and long-term value.
Beneva’s key financial strengths:
- $29.2 billion in total assets
- $673.8 million in consolidated net income
- 14.9% return on equity
- $4.9 billion in consolidated equity
- 163% solvency ratio
Why choose Beneva
- A mutual, member-first model that reinvests profit into members
- A large asset base supporting long-term financial stability
- Strong ratings and governance behind its claims-paying credibility
- Bundled benefits that add value without extra rider costs
Unique selling point (USP): As Canada’s largest mutual insurer, Beneva reinvests profit into member benefits and product improvements rather than shareholder returns.
Beneva Participating Whole Life: Cash values available in later years
Beneva Non-Participating Whole Life: Guaranteed cash value
None
14. UV Insurance: Best for long-term growth
Adaptable Whole Life
Whole Life Pay to 100
20-pay
8-pay
pay-to-100 (varies by plan)
Our advisor’s take:
We give UV Insurance 3.5/5 for being an excellent choice for Canadians who want long-term, reliable whole life growth backed by a mutual company with over 135 years of operations. Supported by a strong 172% solvency ratio, UV delivers the kind of financial stability that long-term policyholders depend on. Its non-participating whole life plans focus on steady, predictable cash value accumulation with conservative investment management and policyholder-first governance.
UV Insurance’s key financial strengths
- 135+ years as a mutual insurer, operating under a policyholder-owned structure
- $7.9 million in net income for 2025
- 172% solvency ratio
- $281.3 million in mutual members’ equity as of 2025
- A fully digital underwriting platform (My Universe)
Why choose UV Insurance
- Reinvests profit into members rather than external shareholders
- A high solvency ratio protects long-term guarantees
- A digital-first underwriting and application experience
- Directs more than 10% of profits to health, education, and social initiatives
- Over a century of mutual-model stewardship
Unique selling point (USP): UV prioritizes long-term growth with high cash-value potential (up to 50% of the coverage amount by age 65 in select plans) plus digital simplicity.
Whole Life High Values: High long-term growth; cash values can reach up to 50% of the coverage amount by age 65 or after 20 payments for those aged 46 and older
Adaptable Whole Life: Cash value begins in later policy years; high surrender values available from the 10th policy anniversary
Non‑participating whole life (Whole Life Pay to 100) : Cash value begins from the 5th contract anniversary
Not applicable as UV primarily offers a non-participating lineup
15. Wawanesa: Best for value and guaranteed benefits
Whole Life Pay to Age 100
pay-to-100
Our advisor’s take:
We give Wawanesa 3.5 / 5 for being a leading choice for Canadians who want whole life insurance with dependable guarantees, conservative investment management, and long-term affordability. The Wawanesa Life Par offering provides both 20-Pay and Pay to Age 100 premium options. Wawanesa backs this participating plan with a strong financial foundation, including solid capital backing across its life division. The plan delivers predictable, steady cash value growth and consistent dividend performance, supported by a disciplined bond-focused investment strategy.
Wawanesa’s key financial strengths
- 6.00% Dividend Scale Interest Rate (DSIR)
- $1.9 billion life insurance asset base
- $4.7 billion in group equity / surplus supporting the wider mutual group
- $311 million in life division equity
Why choose Wawanesa:
- Conservative asset management supports dependable dividend performance
- A high-quality, low-volatility bond portfolio limits swings
- Strong surplus reserves from a leading Canadian mutual insurer
- Profits flow to policyholders rather than shareholders
- Competitive, affordable pricing with reliable guarantees
Unique selling point (USP): Wawanesa Life Par delivers predictable, steady cash-value growth and consistent dividend performance through a disciplined, bond-focused strategy.
Wawanesa Life Par: Guaranteed cash values; dividend-eligible (with cash values typically beginning as early as policy year 5)
Paid-up additions (PUA), annual premium reduction, cash payment, or accumulation at interest (left on deposit)
Methodology: How we determined the best whole life insurance companies in Canada
We selected the best whole life insurance companies in Canada by evaluating the following:
- Financial Strength & Metrics: LICAT ratios, par fund sizes, surplus, solvency ratios, and net income figures.
- Dividend Scale Interest Rates (DSIR): Current board-approved rates (e.g., 6.40% for Equitable, 6.00% for Canada Life, etc.) and their active dates.
- Policy Details & Payment Options: Exact premium payment terms (10-pay, 20-pay, Pay to Age 100, Life Pay) and product types.
- Cash Accumulation Timelines: Whether cash value starts in year 1, year 5, or later.
- Dividend Options: Available payout choices like Paid-up Additions (PUAs), cash payments, and deposits at interest.
- Underwriting Flexibility: Specializations such as no-medical/simplified issue, smoker-friendly programs, and alignment with estate, juvenile, or high-net-worth planning.
Cost of whole life insurance in Canada
Whole life insurance costs vary by age, health, coverage amount, plan type, and payment term. Younger applicants and non-smokers get lower premiums; higher death benefits and shorter payment terms (e.g., 10-pay) raise the annual cost.
Illustrative cost of $100,000 whole life insurance by insurer
| Insurer | Annual premium | Cash value: year 20 | Cash value: year 40 | Death benefit: year 40 |
| BMO | $1,230 | $21,482 | $116,483 | $246,237 |
| Canada Life | $800 | $13,419 | $68,267 | $121,507 |
| Empire Life | $689 | $14,574 | $67,845 | $132,540 |
| Equitable Life | $818 | $21,481 | $90,510 | $163,023 |
Figures illustrate a $100,000 life-pay participating whole life policy for a healthy 30-year-old female non-smoker. Cash values and death benefits are not guaranteed and depend on dividends, insurer performance, and policy design; actual premiums and results vary by underwriting and product options.
How to choose the best whole life insurance in Canada
Choosing the best whole life insurance policy comes down to comparing costs, features, flexibility, and the insurer’s financial strength. Here are the key factors to review before you decide:
- Premiums and charges: Compare premium levels across companies and check for extra fees such as admin charges or rider costs
- Customer support: Look for strong service ratings, easy policy management, and responsive support
- Claims handling: Favor insurers known for fast, low-friction claims during critical times
- Policy flexibility: Prioritize plans with useful riders and customization so coverage can be tailored
- Underwriting requirements: Weigh medical-exam vs. no-exam trade-offs — no-exam is more convenient but may cost more
- Company standing: Check financial strength ratings and long-term performance for stability and reliability
Licensed PolicyAdvisor advisors will help you compare options, answer questions, and ensure your coverage aligns with long-term goals.
Frequently Asked Questions
Does term life insurance cover disability in Canada?
If you become disabled and can no longer work, term life insurance will not replace your lost income. Term life insurance pays a death benefit to your beneficiaries, while disability insurance provides monthly income benefits if an illness or injury prevents you from working. Understanding these options can help you determine whether your existing coverage is enough to protect your income.
Understanding disability and term life insurance
Term life insurance and disability insurance protect against two different financial risks. Term life insurance can help your loved ones manage financial obligations such as a mortgage, debts, and living expenses after your death.
Disability insurance, on the other hand, helps you maintain your financial commitments while you are alive but unable to earn your regular income. It works as income protection insurance. While both policies can be tailored to your financial needs, they differ in their coverage periods, benefit triggers, and payout structures.
Does term life insurance cover disability?
Term life insurance does not cover you if you are dealing with long-term disability, as the policyholder has to be deceased before the death benefit can be paid. However, some life insurance companies in Canada offer optional disability riders. These life insurance riders can be added to your coverage at the time of application and provide options and coverage for the future, should you find yourself dealing with disability. The disability riders, however, are available at additional premiums.
Disability waiver of premium rider
Under this rider, life insurance premiums are waived if the life insured suffers a total disability. A total disability waiver of premium covers disabilities caused by accidents as well as illnesses. To claim under this rider, the life insured must:
- Not be able to perform essential duties of their occupation
- Not be engaged in any other occupation
- Need ongoing medical care, depending on the policy wording
Generally, disability waiver riders only pay out after the individual has been totally disabled for at least 4 or 6 consecutive months. The rider is valid until a certain age of the person to be insured, most often up to the age of 60 or 65.
Disability income rider
A disability income rider provides monthly payments to the life insured in the event they become disabled and unable to work. The policyholder will need to choose the time period for which the payments are to be made and the monthly payment (which is usually capped). This rider typically has a 30- or 90-day waiting period, with retrospective payments that start after the waiting period is over.
Disability credit rider
A disability credit rider covers all or part of the life insured’s line of credit or monthly mortgage payments in the event of their temporary or permanent disability. The payments are made for a specified period of time, such as 2 years from disability, 5 years from disability, or up to the age of 65. Credit riders typically have a waiting period of 90 days, although they can be retroactive to 31 days in the event of disability from an accident. Proof of the outstanding loan is usually required at the time of the claim.
What is an extreme disability benefit?
An extreme disability benefit is a built-in feature that lets you access a portion of your life insurance death benefit while you are still alive and experience a permanent and severe disability that meets the insurer’s definition. Instead of waiting for the life insurance policy to pay after your death, you can receive part of the benefit early to help manage significant expenses associated with your disability.
Both Beneva and Assumption Life offer an extreme disability benefit with their life insurance policies. Beneva includes the benefit and provides an advance of up to 50% of the initial insurance amount, subject to a $250,000 maximum, if the insured remains extremely disabled for six consecutive months. Assumption Life also offers an advance of up to 50% of the insured amount. The maximum benefit is $250,000 for insureds aged 18 to 59 and $125,000 for those aged 60 to 70.
Standalone disability insurance vs. disability insurance riders
The main difference between disability insurance and a disability insurance rider is that disability insurance is a standalone policy, while a disability insurance rider is an optional feature attached to a life insurance policy.
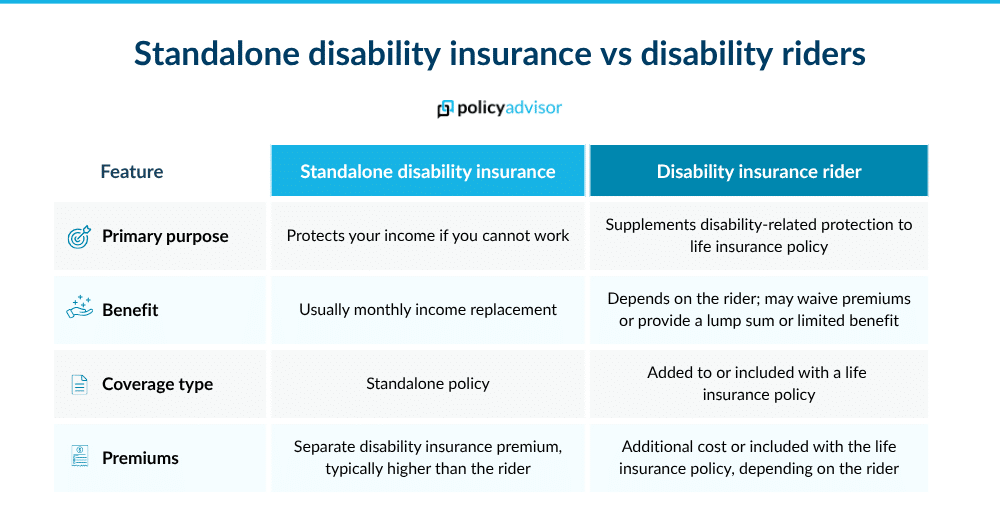
Life insurance companies offering disability riders in Canada
Examples of insurers that offer these riders include:
- Disability waiver of premium rider: Assumption Life, Beneva, Canada Life, Empire Life, Manulife, Wawanesa, and a few other insurers offer disability waiver of premium riders. Most of these insurers have a 4-6 month waiting period
- Disability income rider: Assumption Life offers a disability income rider. It provides an income benefit of up to $3,500 per month, subject to policy limits
- Disability credit rider: Beneva, Empire Life, and iA are the top companies offering this rider
What if your term life insurance policy doesn’t offer a disability rider?
Listed below are the options available if your term life insurance doesn’t offer a disability rider:
- Buy standalone disability insurance: A separate disability insurance policy is the most direct way to replace lost income during a disability
- Add a rider later: Some insurers may allow certain riders after issue, but often require new medical evidence, age eligibility, and insurer approval
- Switch policies: You may be able to apply for a new policy with the rider you want, then replace the old one if the new coverage is approved and in force
What should I choose between disability vs life insurance?
Comparing disability insurance with life insurance is not quite an apples-to-apples comparison. Both are valuable protection products with very different use cases, and each can shield you or your loved ones from financial hardship.
Choose disability insurance if:
- You need protection when illness or injury prevents you from working
- Your family relies on your regular income
- Your employer provides little or no disability protection
Choose life insurance if:
- Your family would need financial support if you pass away
- You want to help cover a mortgage, loans, or other liabilities after your death
Instead of choosing between them, we would recommend having both. You can have both disability and life insurance to protect your income during your lifetime and your loved ones after your death.
Why is a standalone disability policy the better choice for income protection?
A standalone disability insurance policy is generally a better choice for income protection because it is specifically designed to replace a portion of your income if an illness or injury prevents you from working. Disability riders, on the other hand, usually provide more limited protection and may only waive life insurance premiums or provide a specific lump-sum or monthly benefit.
A standalone disability policy can provide ongoing monthly payments for a longer period, helping you cover essential expenses and everyday living costs while you are unable to work. With a standalone policy, you can also choose coverage based on your income, occupation, waiting period, and benefit period, making it more adaptable to your financial needs.
What happens to your term life insurance if you become disabled?
Becoming disabled does not normally affect or cancel your term life insurance policy. As long as you continue paying your premiums and meet the policy’s requirements, your life insurance coverage generally remains in force.
If your policy includes a qualifying waiver-of-premium rider, you may be able to stop paying premiums while disabled without losing your coverage. Without such a rider, you would still be responsible for paying your life insurance premiums even if your disability prevents you from working.
How to buy disability and term life insurance in Canada?
Our advisors can help you compare term life insurance and disability insurance based on your income, financial responsibilities, existing coverage, and protection needs. They can also help you understand the differences between standalone disability coverage and disability riders available with life insurance.
With PolicyAdvisor, you can compare quotes from leading Canadian insurers and get expert guidance on choosing the right coverage for your situation. This can help you build a combination of life and disability insurance that protects both your family and your income. Schedule a call to get started!
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
Frequently asked questions
Does term life insurance cover disability in Canada?
No, standard term life insurance does not provide income replacement if you become disabled. It pays a death benefit if you die while the policy is active. Some policies may offer disability-related riders for additional protection.
Is a disability rider the same as disability insurance?
No, a disability rider and disability insurance are not the same. A disability rider provides a specific benefit attached to a life insurance policy, while standalone disability insurance is designed primarily to replace a portion of your income when you cannot work because of a qualifying illness or injury.
Can you add disability coverage to a term life insurance policy?
Some insurers offer disability-related riders that can be added to a life insurance policy. Depending on the rider, it may waive premiums, provide a limited benefit, or allow you to access part of your death benefit after a qualifying disability.
Does a disability waiver of premium rider replace your income?
No, a disability waiver of premium does not replace your income. A waiver of premium rider generally helps keep your life insurance policy active by waiving premiums during a qualifying disability. It does not normally provide monthly income replacement.
Is disability insurance worth it if I already have life insurance?
Yes, having disability insurance is worth it even if you have a life insurance policy. This is because life insurance does not normally protect your income while you are alive and disabled. If losing your ability to work would create financial difficulties, disability insurance can provide an additional layer of protection.
Can self-employed Canadians get disability insurance?
Yes, self-employed individuals can purchase individual disability insurance to protect their income. This can be particularly important if they do not have access to employer-sponsored disability benefits.
What should you check before relying on a disability rider?
Review the definition of disability, waiting period, benefit cap, expiry age, exclusions, and whether benefits are paid monthly, as a lump sum, or through waived premiums. Doing so will help you get adequate coverage through disability riders.
Is Whole Life Insurance a bad investment in Canada? 2026 Guide
Whole life insurance is a popular kind of life insurance in Canada, offering lifelong coverage while building cash value over time. Participating whole life policies may also provide non-guaranteed dividends, providing additional opportunities to grow the policy value. Since whole life combines permanent financial protection with additional benefits, it can be a valuable tool for long-term financial planning.
Is whole life insurance a bad investment?
No, whole life insurance is not a bad investment option. It is primarily a permanent life insurance option that provides guaranteed lifelong coverage while building cash value. Whether it is a good choice or not depends on your financial goals and the duration of protection you are seeking for your beneficiaries.
Essentially, if you are only looking to temporarily replace income or secure a short-term financial obligation, a term policy will provide a basic, temporary safety net. However, if you are seeking to leave an inheritance or planning a tax-free inheritance for your family, a whole life policy may be a better fit for your needs.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
Common misconceptions about whole life insurance
Many people view whole life insurance as a bad investment because of common misconceptions around its higher premiums, slower cash value growth, and lower returns compared with market-based investments. Let’s separate the myths from the facts and look at what whole life insurance actually offers:
Myth #1: Whole life insurance is a bad investment
Whole life insurance is sometimes compared directly with investment options like stocks, mutual funds, or ETFs. However, this comparison fails to consider that whole life is primarily an insurance product.
Whole life insurance is purchased to provide a guaranteed death benefit, while also building cash value in the process. Essentially, it is better to regard whole life insurance as a long-term insurance and financial-planning tool rather than as a direct alternative for investment-focused options like stocks or other conventional methods.
A whole life insurance policy offers a guaranteed death benefit when you pass away, providing your beneficiaries with funds for financial protection and to cover final expenses. This makes it a great tool for leaving an inheritance or for tax-advantaged estate planning. Alongside this, the policy also grows cash value and non-guaranteed dividends over the years.
This cash value can be used as a policy loan, withdrawn, or even used as collateral in an eligible third-party loan. Additionally, if the policyholder receives dividends, they can use them to purchase additional paid-up insurance or reduce premiums.
Myth #2: Whole life insurance is too expensive
Permanent life insurance policies are indeed more expensive than term life insurance. In fact, whole life insurance premiums can be as much as 5 to 15 times more expensive than term policies. This difference can be significant for those looking for a more budget-friendly life insurance policy or higher coverage amounts at lower premiums.
However, this difference in premium cost is not without reason. Whole life insurance offers lifelong coverage, cash value, and an investment component in participating policies. Unlike term insurance, whole life coverage is designed to last a lifetime. It is also worth noting that many whole life policies offer guaranteed and level premiums. If you apply when you are younger and healthier, you essentially qualify for more reasonable rates.
With term life insurance, your premiums may increase with each term renewal or new application, since the cost is based on attained age and other underwriting criteria. Therefore, comparing term and whole life based on the initial premium alone does not provide a complete picture.
Myth #3: You have to surrender your policy to access the cash value
You do not necessarily have to surrender your whole life insurance policy to benefit from its cash value. While surrendering your policy gives you access to the accumulated cash value, you can also use that value in other ways. Depending on your policy and the terms, you may also be able to:
- Make a partial withdrawal
- Take a policy loan against the cash value
- Use the policy as collateral for a loan
This flexibility can be useful for business owners and corporate-owned policies. A business owner can borrow against the policy or use it as collateral and reinvest the borrowed funds into the business for expansion, acquisition, or other expenses without having to surrender the policy. As long as the policy remains in force, the coverage continues.
Is term life insurance better than whole life insurance?
Neither is universally better since the two policies solve different financial needs. While term is meant to offer protection for temporary financial obligations such as mortgages or loans, whole life policies are meant for lifelong coverage and wealth preservation.
Let’s say you purchase a ten-year term life insurance policy with $50,000 in coverage. The cost of term life premiums will be less than those for a whole life policy with the same coverage of $50,000. If you die during those 10 years, the term policy provides the same $50,000 death benefit at a lower premium cost. However, if you outlive the term and allow the policy to expire, your coverage ends.
On the other hand, whole life stays in force for life and provides a guaranteed death benefit whenever you die, as long as the premiums are paid. The major difference is that term life insurance protects against the possibility of passing away during a selected term, whereas whole life insurance is designed to provide coverage until the policyholder passes away.
If you are seeking to protect outstanding debts or short-term obligations like mortgages, term life insurance is the way to go. However, if you are looking for permanent protection while also building cash value, whole life insurance may be more aligned with your financial needs.
Should you use whole life insurance for retirement planning in Canada?
Whole life insurance can complement retirement and estate planning, particularly when you already need lifelong coverage. A participating life insurance policy can build cash value on a tax-advantaged basis and may provide non-guaranteed dividends.
However, whole life insurance should generally complement conventional savings options such as RRSPs and TFSAs. The key to this balance is structuring the policy so that the premiums and future policy value support your retirement goals.
Here are some factors you should keep in mind while using whole life insurance for retirement planning in Canada:
- Budget whole life premiums before retirement: If you expect to continue paying premiums after you retire, it is important to factor those payments into your projected retirement expenses
- Consider a limited-pay whole life policy: Limited-pay whole life policies allow you to complete your scheduled premium payment over a much shorter period, while maintaining lifelong coverage. This can help you finish paying premiums before retirement.
- Use participating policy dividends: If you receive dividends from participating policies, you can use them to purchase additional paid-up insurance or reduce premiums, making it great for retirement planning.
For a detailed overview, check out our guide on Whole life vs. RRSP vs. TFSA: Which builds more wealth in Canada?
What is your Whole Life Insurance worth?
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
Who should buy whole life insurance in Canada?
Whole life insurance is particularly valuable if you are seeking lifelong protection or want to use it as part of a broader strategy involving estate planning or wealth transfer to your beneficiaries, owing to the tax-free payout and tax-deferred growth.
Here are situations when whole life insurance in Canada makes sense:
You need permanent life insurance
Whole life insurance can provide coverage for final expenses, lifelong dependants, estate obligations, or other permanent needs. It is designed for broader protection, rather than covering temporary financial obligations like home loans or debts.
You are a high net worth individual
Whole life insurance is a great tool for high net worth Canadians who have already made effective use of conventional savings and investment strategies. The policy can help in broader estate and tax-deferred wealth-transfer planning. It offers an efficient way of transferring wealth to beneficiaries while providing permanent life insurance protection.
You want to leave an inheritance
Whole life insurance can create a guaranteed inheritance or fund for your beneficiaries such as children and grandchildren, provided you continue to pay your premiums until your death or until the end of the specified policy period.
You are a business owner
If you are a business owner, you can use whole life insurance to provide liquidity after you pass away. The death benefit can be used as a cash flow injection that can also help in funding shareholder agreements or to help address operational or structural challenges the business may face after the owner’s passing.
Who may want to skip whole life insurance?
While whole life is great for those seeking extended coverage for the duration of their lives, it might not be the perfect fit for individuals seeking affordable coverage or short-term protection. If you have temporary or reducing financial obligations, such as a mortgage or outstanding loans, a term life policy will offer you a higher coverage amount at similar premiums.
Similarly, if investment growth is your priority and you do not need permanent life insurance, whole life insurance may not be the right fit for you. Instead, you can invest in traditional options such as mutual funds, stocks, or ETFs.
Final verdict: Is whole life insurance actually bad?
No, whole life insurance is not inherently bad. It provides lifelong protection while building cash value, making it a good investment for Canadians planning long-term coverage. It is particularly well-suited for individuals planning to leave an inheritance or transfer wealth to their beneficiaries in a tax-advantaged manner.
For Canadians protecting a short-term financial liability, term life insurance is usually the most cost-effective option since it provides a large amount of coverage when it is needed the most.
On the other hand, if you are a high net worth individual or you have maxed out your RRSPs or TFSAs, you can consider whole life insurance to leave behind an inheritance or cover final expenses and other costs.
Still confused about whether whole life insurance is right for you? Speak to our advisors and compare quotes from leading Canadian insurers to see what best fits your financial situation and needs.
Frequently Asked Questions
Is whole life insurance worth it in Canada?
Whole life insurance can be worth it if you need permanent coverage and want to build cash value in the process. It may be particularly useful for Canadians seeking to leave an inheritance, transfer wealth, or cover permanent estate obligations.
How long does whole life insurance take to build cash value?
Whole life insurance begins building policy value according to the policy’s contractual schedule, but the cash value growth is usually slower in the earlier years. This is because most of your premiums go to administrative costs and paying for your death benefit.
Do beneficiaries receive the cash value of a whole life policy when you die?
No, beneficiaries only receive the death benefit when the policyholder passes away. However, the cash value can be used to take policy loans or pay future premiums.
Is whole life insurance a good investment for business owners?
Whole life insurance may be a good investment for business owners who are seeking permanent coverage, while protecting beneficiaries if the owner passes away suddenly. It is especially useful as corporate-owned life insurance, since it may provide liquidity after you pass away.
Can I own both term and whole life insurance?
Yes, you can own both. Canadians generally use term insurance for larger temporary needs such as mortgage protection or income replacement, while a whole life policy helps protect beneficiaries or leave behind an inheritance.
Best life insurance for couples in Canada (2026 guide)
As a couple, managing finances means sharing major responsibilities, such as a mortgage, raising children, paying off debts, or planning for retirement. For most Canadian couples, two separate term life insurance policies are considered the best default choice because they provide two death benefits, flexible coverage amounts, and separate beneficiaries.
While separate life insurance policies are the best fit for most couples due to their flexibility, joint life insurance can be a more suitable and cost-effective option for couples who want to protect shared financial obligations, simplify policy management, or reduce policy fees.
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
What is the best life insurance for couples in Canada?
The best life insurance for couples in Canada depends on a couple’s financial goals, family situation, and long-term plans. Policies from leading insurers such as BMO, Empire Life, RBC Insurance, and Manulife offer unique features that make them well-suited for couples seeking financial protection.
While many assume a joint policy is the best choice, separate life insurance policies can provide greater flexibility, personalized coverage, and better long-term value.
Here’s a quick overview of life insurance for couples in Canada:
| Feature | Details |
| Types of coverage |
|
| Best for |
|
| Best insurance companies |
|
| Can unmarried couples apply? | Common-law partners can purchase life insurance individually or jointly if they meet the insurer’s eligibility requirements |
Types of life insurance available for couples in Canada
In Canada, couples can choose between joint life insurance policies that cover both partners under a single plan or individual policies that provide separate coverage for each person. Based on the type you choose, the following options are available:
- Joint first-to-die life insurance
- Joint last-to-die (survivorship) life insurance
- Two separate life insurance policies
- Combined or multi-life insurance policy
Here’s a quick overview of the different policy types:
Joint first-to-die life insurance
A joint first-to-die life insurance policy covers two people under a single contract and pays the death benefit after the first insured person passes away. Once the benefit is paid, the policy ends, and the surviving partner no longer has coverage.
This option is commonly chosen by couples who want to ensure the surviving spouse has financial protection for living expenses, debts, child care, or mortgage payments. While it is comparatively less expensive than two separate policies, note that joint first-to-die life insurance only provides one death benefit.
Joint last-to-die (survivorship) life insurance
A joint last-to-die policy insures two people under one contract but pays the death benefit only after both insured individuals have passed away. Since the insurer does not pay until the death of both partners, premiums are often lower than buying two separate policies.
This option is great for parents or partners who wish to protect their children and other beneficiaries from debts and to support estate planning and wealth transfer.
Two separate life insurance policies
In this case, each spouse owns an individual policy with their own coverage amount, beneficiaries, and policy features. Each policy pays its own death benefit when the insured passes away, offering beneficiaries two separate payouts over time.
This is the most flexible option, working well for couples with different incomes, debts, health conditions, or long-term financial goals. Additionally, separate policies are easier to maintain in the event of a divorce or separation. Since they are not under a joint policy, the individuals continue to be insured without any complications or reassessment.
Combined or multi-life insurance policy
A combined or multi-life insurance policy allows two people to have two coverage within a single insurance contract. It combines features of joint policies while offering personalized and individual solutions under one policy.
Each insured person has their own benefit, but the policy is offered under one application and one premium payment schedule. Beneficiaries receive two death benefits, one for each policyholder. Despite being combined, the death benefits are separate for each individual. Since everything is under one policy, couples can save on policy or administration fees, reducing the overall costs.
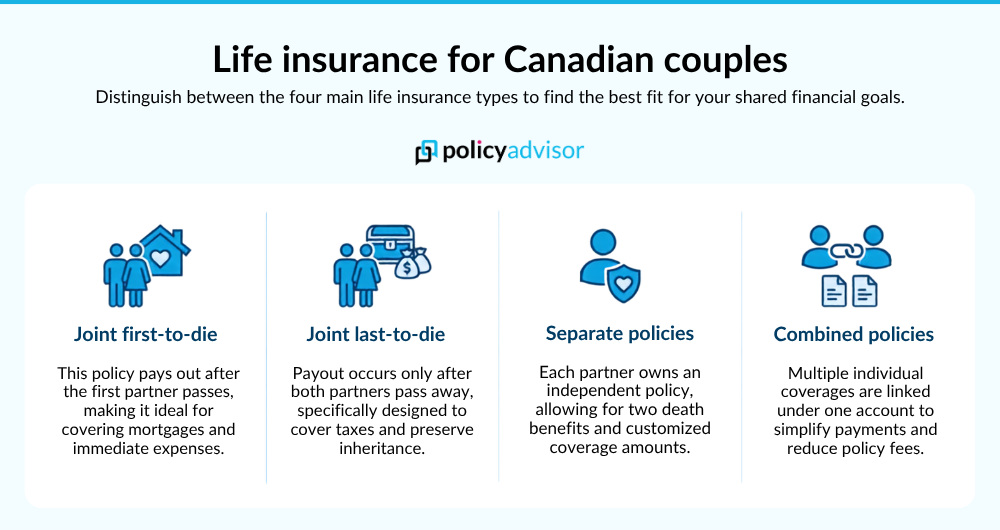
Comparing life insurance options for couples in Canada
Each policy type has its own series of benefits and features. Two separate term life policies are ideal for families, while joint first-to-die life insurance is ideal for individuals seeking protection for mortgages and other major expenses. Meanwhile, a joint last-to-die policy is well suited for estate planning and creating a legacy.
Here’s a comparison of the major life insurance options available for couples in Canada:
| Feature | Joint first-to-die life insurance | Joint last-to-die (survivorship) life insurance | Two separate life insurance policies | Combined or multi-life insurance policy |
| Who is covered? | Two people under one policy | Two people under one policy | Two people have two separate policies their own policy | Two individual policies linked under one account |
| When is the death benefit paid? | After the first insured person dies | After both insured individuals have passed away | When each insured person dies, according to their own policy | Single payout based on the policy type |
| Number of payouts | One | One | Two (one per policy) | Two (one per coverage) |
| Policy ends when | After the first claim is paid | After the second insured dies and the claim is paid | Each coverage ends independently according to its terms | Each coverage ends independently according to its terms |
| Best suited for | Income replacement, mortgage protection, and covering shared debts | Estate planning, wealth transfer, and leaving an inheritance | Couples who want flexible, personalized coverage | Couples who want separate coverage with simplified administration |
| Coverage flexibility | Low | Low | High | High |
| Premiums | Often lower than two comparable permanent policies | Often lower than two comparable permanent policies | Based on each individual’s age, health, and coverage needs | Similar to separate policies, though some insurers may offer administrative discounts |
| If one partner dies, does the surviving partner remain insured? | No, the policy ends after the payout. | Yes, but no benefit is paid until the surviving partner also passes away | Yes, the surviving partner’s policy remains active | Yes, the surviving partner’s policy remains active |
It is also worth noting that many insurers offer a conversion or survivor privilege when couples purchase life insurance. This allows the surviving partner to purchase a new individual policy within a short window (usually 30 to 90 days) without undergoing a medical exam or answering new health questions.
How much does life insurance cost for couples in Canada?
The cost of a life insurance policy for couples ranges from $224.10 to $615.15. The premiums depend on the plans chosen and the coverage, as well as personal factors such as age, smoking status, and health.
Here is a sample life insurance rate for two 35-year-olds for Term100 from Beneva:
| Feature | Individual life (Male) | Individual life (Female) | Combined/ Multi-life | Joint First to Die | Joint Last to Die |
| Beneva/ Monthly prem | $332.1 | $288.45 | $615.15 | $457.2 | $224.1 |
| Life covered | Single | Single | Both | Both | Both |
| Coverage Amount | 500k | 500k | 500k + 500k | 500k | 500k |
| Saving | – | – | 1% | 26% | 64% |
Cost of life Insurance for couples
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
Should couples buy joint or separate life insurance?
For most Canadian couples, it is recommended to obtain separate life insurance policies, as this allows each partner to customize their coverage and modify riders or terms independently. However, two individual policies for couples could cost as much as $620.55, whereas a joint policy costs as little as $224.1 per month.
Separate policies provide two death benefits and have customised features, making it easier to maintain coverage if the partners divorce or separate. On the other hand, joint policies can be a good option for couples seeking lower premiums or fewer complications.
Pros and cons of purchasing a joint policy and individual policies in Canada:
Pros and cons of purchasing a joint policy for couples
Pros and cons of purchasing individual policies for couples
Top 5 best life insurance companies for couples in Canada
Choosing the right life insurance company for couples is just as important as choosing the right type of policy. While many insurers offer great benefits, the following companies offer greater flexibility, built-in benefits, and features that make them particularly suitable for partners with shared financial goals.
Here’s an overview of the five best life insurance companies for couples in Canada:
BMO Insurance
BMO Insurance is an excellent choice for couples who want their coverage to remain stable even after a life-changing event. Even if one insured person in a joint policy passes away, the surviving insured member can continue coverage at the same premium, provided the coverage amount remains unchanged.
This feature is great for couples seeking hassle-free coverage, especially at older ages when premiums are higher. In addition, BMO also offers the Empathy service, which provides emotional and logistical support to the policyholder’s beneficiaries.
Beneva
Beneva is well suited for couples who want more than just a death benefit. The policies include valuable built-in features such as the Extreme Disability Benefit and Guaranteed Insurability Option, ensuring policyholders can increase coverage later on without additional medical underwriting (under qualifying circumstances).
Additionally, eligible policies also have the option to add valuable riders such as child coverage and accidental death benefits, allowing couples to customize their protection and help ensure the financial safety of their beneficiaries.
Empire Life
Empire Life has one of the most seamless application processes, combining a streamlined online application process with competitive policy features. Couples can benefit from policy fee savings, strong term conversion options, and the ability to choose from a wide selection of term and permanent life insurance plans.
Policyholders can also add critical illness insurance under the same policy, making it easier for them to build a comprehensive financial protection plan. Additionally, the joint first-death plan offers temporary insurance to the surviving partner for an additional 90 days. This gives the spouse time to figure out their next steps without suddenly being unprotected.
RBC Insurance
RBC Insurance stands out for its Pick-a-Term feature, which lets partners choose a customized term length rather than selecting only standard options such as 10 or 20 years. This flexibility allows them to match coverage with major financial obligations like mortgages, education, or even retirement planning.
Many eligible policies also feature a seamless conversion option, allowing couples to transition from term to whole life without additional medical underwriting. Couples can also benefit from policy fee savings when purchasing joint coverage.
Manulife
Manulife is an excellent option for couples who want to combine life insurance with wellness incentives. Through the Manulife Vitality program, policyholders can earn points and receive rewards for maintaining healthy lifestyle habits, such as exercising, participating in activities, and completing health assessments.
Additionally, Manulife life insurance offers a Waiver of Premium option for couples. If either partner becomes totally disabled due to injury or illness, the premiums for the entire joint policy are waived, ensuring coverage remains active while household income is impacted.
Quick overview of the five best insurance companies for couples in Canada:
| Insurer | Best for | Standout feature |
| BMO Insurance | Long-term flexibility | Surviving insured can continue coverage at the same premium (subject to policy conditions) |
| Beneva | Built-in policy benefits | Extreme Disability Benefit and Guaranteed Insurability Option |
| Empire Life | Fast digital applications | Digital underwriting, policy fee savings, Critical Illness integration |
| RBC Insurance | Custom term lengths | Pick-a-Term feature and joint policy fee savings |
| Manulife | Wellness-focused couples | Manulife Vitality rewards program and Waiver of Premium |
How much life insurance coverage do couples need?
For many Canadian families, a rule of thumb is to purchase life insurance worth 7 to 15 times your annual income. However, this is just a baseline and should be adjusted based on your financial situation.
A great method of calculating how much coverage you need is to use the Debt, Income, Mortgage, and Education (DIME) method. It is a simple way to estimate how much life insurance you may need by considering four key financial obligations your beneficiaries could face.
Use our life insurance calculator to estimate how much coverage you need.
What mistakes do couples make when buying life insurance in Canada?
Many couples purchase life insurance to protect their loved ones, but choosing the wrong policy, waiting too long, or having insufficient coverage can leave their family financially vulnerable.
Here are some of the common mistakes you should avoid as a couple while purchasing life insurance in Canada:
- Waiting too long: Many couples postpone buying life insurance until they have children or purchase a home. Purchasing coverage early protects you from higher premiums later on due to age and health conditions
- Buying too little coverage: Some couples choose the lowest premium without considering how much coverage their family would actually need. Ensure the policy amount sufficiently covers debts, future income replacement, and living expenses
- Choosing the wrong type of policy: Many couples automatically choose a joint policy because it appears simpler or less expensive. However, a term life policy or a joint last-to-die policy might offer better estate planning and coverage in certain situations
- Forgetting the Stay-at-Home Partner: Many couples think they only need insurance on the person who earns the most money. If a stay-at-home partner passes away, the surviving partner must pay for child care, cleaning, and cooking.
- Not reviewing coverage after major life events: Many couples forget to review their coverage amount or duration after major events like child birth, starting a business, purchasing a home, or taking on significant debt. This can leave them without sufficient coverage or term in the future.
Can you change or cancel your life insurance policy as a couple in Canada?
Yes, most life insurance policies in Canada can be changed or cancelled. However, your available options depend on the type of policy you own and the rules specific to your insurer and policy. Common changes include increasing coverage, converting term coverage to permanent coverage, or replacing a joint policy with individual policies.
Here are some of the most common changes couples make to their life insurance coverage:
| Option | What it means |
| Increase your coverage | Purchase additional life insurance if your financial responsibilities grow |
| Replace your policy | Switch to a new policy with a different insurer or coverage amount |
| Convert a term policy | Many insurers allow you to convert eligible term life insurance into permanent coverage before a specified age or deadline |
| Replace a joint policy | Couples who have different goals, or who divorce or separate, may replace a joint policy with individual policies |
| Cancel your policy | Stop paying premiums and end your coverage if you no longer need life insurance |
It is also worth noting that most policies include a “free-look” period to review and cancel for a refund. As a couple, you should review your life insurance coverage and goals after major life events, such as purchasing property, having children, or planning for retirement. Contact our advisors today for a comprehensive plan based on your needs.
Our advisor’s take on the best life insurance for couples
At PolicyAdvisor, we recently helped a married couple in their early thirties secure life insurance after purchasing their first home and welcoming their first child. They were seeking coverage to ensure the surviving spouse could continue paying the mortgage, replace lost income, and support their child.
Client profile
- Ages: 32 and 34 years
- Family: Married with one young child
- Primary concern: Income replacement and mortgage protection
- Existing debt: $620,000 mortgage
- Coverage goal: $1.5 million in total life insurance
- Approximate monthly premiums: $332.1 (Male) and $288.45 (Female), respectively
Why we recommended separate term life insurance
- Each spouse required a different coverage amount based on their income and financial responsibilities
- Separate policies ensured both partners remained insured even if one policy paid a death benefit
- The policies included the option to convert to permanent life insurance if their long-term financial goals changed
- Affordable monthly premiums allowed them to get higher coverage without exceeding their budget
How to purchase life insurance for couples in Canada?
PolicyAdvisor’s licensed life insurance advisors can help couples compare life insurance quotes from leading Canadian insurers based on their ages, budget, coverage needs, and financial goals. They can help you estimate your coverage and decide between joint and separate policies.
Whether you are newly married, raising a family, or planning your estate, PolicyAdvisor can help you compare quotes and apply online with licensed advisors. We will compare policy types, term lengths, and riders to help you choose the right protection for you and your loved ones.
Frequently Asked Questions
What is the best life insurance for couples in Canada?
For most Canadian couples, two separate term life insurance policies are the best option. They offer better flexibility and allow each partner to choose their own coverage, beneficiaries, and riders with ease.
Is joint life insurance cheaper than separate policies?
Joint life insurance can sometimes have lower premiums than purchasing two comparable individual policies because both partners are insured under a single contract. However, it only pays one death benefit. Once it is paid, coverage ends.
Can common-law couples purchase life insurance together?
Yes, most Canadian insurers allow common-law partners to purchase either separate or joint life insurance policies if they meet the insurer’s eligibility requirements. Coverage options are usually the same as those available to married couples.
Can couples have different coverage amounts?
Yes, if you have separate life insurance policies. Since each policy is its own contract, you can choose to customize it based on your needs. Additionally, you can choose separate beneficiaries.
Can couples buy life insurance online?
Yes, couples can buy life insurance online. Our trusted advisors at PolicyAdvisor can help you compare quotes.
Can we name a minor child as beneficiary?
In most cases, appoint a trustee for any minor’s share so funds can be managed for the child’s benefit until they reach the age of majority in your province.
What if one of the partners has a health condition?
You can consider separate policies so one partner’s health does not influence the other’s pricing or approval. Consider exploring fully underwritten, simplified issue, or guaranteed issue options, depending on your situation.
What happens to joint life insurance after divorce or separation?
This depends on the policy terms and agreement between the policyholders. Some joint life insurance policies can be split into separate policies or transferred to one partner, while others may need to be cancelled.
What is whole life insurance in Canada? (2026 guide)
Whole life insurance is a type of permanent life insurance policy available in Canada. Unlike term life insurance with a fixed term, whole life offers guaranteed coverage for your entire lifetime while building cash value.
As long as you continue paying the required premiums, your policy continues to be in effect till you stop or pass away. It comes as no surprise that many Canadians choose it for lifelong protection and tax-advantaged cash growth.
What is whole life insurance in Canada?
Whole life insurance is a type of permanent life insurance that provides coverage for your entire life rather than a limited term. In exchange for regular premium payments, the insurer guarantees a generally tax-free death benefit (unless they exceed the policy’s adjusted cost basis) to your beneficiaries when you pass away.
Unlike term life policies, whole life insurance also includes a guaranteed cash value component that accumulates over time. Depending on the policy you select, the plan may also earn annual dividends that can further supplement your death benefit and cash value. As a result, premiums are typically 5 to 10 times higher than those of comparable term life policies.
For example, a healthy 35-year-old parent may be able to purchase $500,000 in term life coverage for somewhere between $25 and $40 per month. The same amount of coverage for whole life insurance could cost around $250 to $400 per month. While whole life insurance costs significantly more, the higher premiums reflect its lifelong coverage, guaranteed cash value, and potential dividend growth.
Whole life insurance in Canada: At a glance
| Feature | Details |
| How it works | Pay premiums to receive guaranteed lifetime coverage while building cash value |
| Coverage period | Lifetime |
| Cash value | Guaranteed cash value grows over time and may be accessed through policy loans or withdrawals |
| Death benefit | Generally tax-free payment to your beneficiaries |
| Dividends | Available on participating whole life policies (dividends are not guaranteed) |
| Premiums | Usually fixed for life or for a limited payment period |
| Typical coverage amounts | $25,000 to $10 million or more |
Types of whole life insurance in Canada
While whole life insurance provides permanent coverage to policyholders as long as premiums are paid, many insurers offer the policy in different structures to suit different financial goals. The most common options are participating whole life insurance, non-participating whole life insurance, and limited-pay whole life insurance.
Here’s a quick overview of the different types of whole life insurance in Canada:
| Type of whole life insurance | How it works | Best for |
| Participating whole life insurance | Builds guaranteed cash value and may pay annual dividends that can increase your policy value | Long-term wealth accumulation and estate planning |
| Non-participating whole life insurance | Offers guaranteed premiums, guaranteed cash value, and a fixed death benefit without dividends | Canadians seeking predictable lifelong coverage |
| Limited-pay whole life insurance | Premiums are paid over a fixed period (such as 10, 15, 20 years, or to age 65), while coverage lasts for life | High-income earners who want to finish paying premiums before retirement |
Participating whole life insurance
Participating whole life insurance is one of the most popular permanent life insurance policies in Canada. Alongside guaranteed lifetime coverage and cash value growth, eligible policies may also receive annual dividends based on the insurer’s financial performance.
These dividends can be used to purchase additional paid-up insurance, increase the policy’s cash value, reduce future premiums, or even repay policy loans. While the dividends are not guaranteed, most major Canadian insurers have historically paid them.
Non-participating whole life insurance
Non-participating whole life insurance provides guaranteed lifetime protection with fixed premiums and guaranteed cash value growth. However, unlike participating whole life policies, it does not pay dividends.
Since there is no dividend component, these policies are simpler and more predictable. The returns and death benefit are guaranteed when the policy is issued, providing greater certainty over the life of the policy.
Limited-pay whole life insurance
Limited-pay whole life insurance policies allow you to complete all premium payments within a predetermined period while keeping coverage for life. Common payment schedules include:
- 10 Pay
- 20 Pay
- Pay to Age 65
Although the premiums are higher since they are paid in a shorter period, policyholders no longer need to make payments once the policy becomes fully paid up. As the premiums are paid, the cash value increases on a tax-deferred basis if the policy is “exempt” under the Income Tax Act.
Once enough cash value has accumulated, you can borrow or withdraw from it (subject to policy rules) for retirement income, emergencies, or other financial needs. However, this may reduce the death benefit and cash value.
Pros and cons of whole life insurance
How does whole life insurance work in Canada?
Whole life insurance combines lifelong financial protection with a built-in savings component. As long as you continue paying your premiums, you remain covered for the entirety of your life. Additionally, a portion of your premiums contributes to your policy’s guaranteed cash value, which grows over time.
Here’s how a whole life insurance policy usually works:
Step 1: Choosing the right coverage amount
Choose a coverage amount that would secure the financial future of your family and protect your loved ones from outstanding debts or other costs. Many applicants choose anywhere between 7 and 15 times their annual income.
Step 2: Choose your policy type
Next, you will select the type of whole life insurance that best aligns with your financial goals.
Your options may include:
| Policy type | Key feature |
| Participating whole life | Guaranteed coverage with the potential to earn annual dividends |
| Non-participating whole life | Guaranteed premiums, guaranteed cash value, and no dividends |
| Limited-pay whole life | Finish paying premiums after a set period while keeping lifetime coverage |
Step 3: Complete your application and pay your premiums
Once you have chosen your coverage amount and payment period, you will need to complete your application and name the beneficiary. Most applicants choose their close relatives, such as their spouse, children, or parents, as the beneficiary. Additionally, they can choose one or more beneficiaries.
Step 4: Your policy builds cash value
One of the defining features of whole life insurance is the cash value. Each premium payment contributes toward a guaranteed cash value that grows over time on a tax-advantaged basis. Additionally, if you choose a participating whole life policy, you may earn dividends based on how the insurer performs financially.
Step 5: Your beneficiaries receive the death benefit
If you pass away while your policy is active, your beneficiaries submit a claim to the insurance company. Once the claim is approved, the insurer pays the death benefit as a tax-free lump sum.
How much whole life insurance coverage do you need?
Choosing how much life insurance your family would need to protect their financial future if you were to pass away unexpectedly is an important aspect of purchasing a whole life policy. The coverage amount should be sufficient to help your loved ones maintain stability while replacing the lost income and support you currently provide.
For many families, a common rule of thumb is to choose coverage between 7 and 15 times their annual income. This offers a sizable amount that can cover most future expenses with ease.
Using the DIME method to estimate whole life insurance
Another method of calculating how much coverage you need is to use the debt, income, mortgage, and education (DIME) method. It is a simple way to estimate how much term life insurance you may need by considering four key financial obligations your family could face.
Let’s assume Michael, a 45-year-old business owner, wants to ensure his family is financially secure while also leaving an inheritance.
Here’s a projection of whole life insurance coverage using the DIME method:
| DIME factor | Amount |
| Debt (credit card balance and personal loan) | $75,000 |
| Income replacement (10 years of annual income at $180,000) | $1,800,000 |
| Mortgage (remaining mortgage balance) | $600,000 |
| Education (future education savings for one child) | $150,000 |
| Total estimated life insurance needed | $2,625,000 |
Based on the DIME method, Michael may consider approximately $2.6 million in life insurance coverage. However, because he also wants to leave an inheritance and reduce the tax burden on his estate, he may choose a higher coverage amount through a whole life insurance policy.
While it is a handy index, your ideal coverage amount may differ based on factors such as savings, investments, and long-term financial goals.
Do you need a medical exam for whole life insurance?
In many cases, yes. Most traditional whole life insurance policies in Canada require medical underwriting, particularly if you are applying for a higher coverage amount. Depending on your age, health, and smoking status, insurers may require you to take tests to assess your health conditions.
However, many insurers also offer simplified issue and guaranteed issue whole life insurance with little or no medical underwriting. It is worth noting that simplified issue and guaranteed issue whole life insurance policies will typically have lower coverage limits and higher premiums, compared to traditional policies with medical underwriting.
How much does whole life insurance cost?
The cost of a whole life insurance policy ranges between $264.15 and $1952.10. The premium depends on the policy type, coverage amount, and personal factors, such as gender, age, smoking status, and health.
Here is a sample whole life insurance rate for $500,000 in coverage for a male non-smoker:
| Age | Participating whole life (Paid Up additions) Life Pay | Non-participating whole life Life Pay | Limited pay whole life (20-pay) – participating | Limited pay whole life (20-pay) – non. participating | Limited pay whole life (pay to 65) – non-participating |
| 25 | $349.20 | $209.25 | $677.25 | $366.30 | $264.15 |
| 35 | $489.60 | $322.20 | $887.85 | $540.90 | $442.80 |
| 45 | $713.70 | $522.00 | $1,155.60 | $812.25 | $825.30 |
| 55 | $1,054.80 | $830.70 | $1,489.05 | $1,232.10 | na |
| 65 | $1,635.30 | $1,462.95 | $1,952.10 | $1,774.80 | na |
* Illustrative monthly premiums for a 20-year life insurance policy with a death benefit of $500,000
Cost of whole life Insurance
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
How are whole life insurance premiums calculated?
Life insurance companies calculate your premium by assessing how likely you are to make a claim over the life of the policy. It is primarily based on your age, smoking status, health conditions, coverage amount, and other related factors.
Here’s a brief overview of the factors that may affect whole life insurance premiums in Canada:
| Factor | How it affects your premium |
| Age | Younger applicants generally qualify for lower premiums. |
| Health | Good overall health can help you secure more favourable rates. |
| Smoking status | Smokers and tobacco users typically pay significantly more than non-smokers. |
| Coverage amount | Higher death benefits result in higher premiums. |
| Gender | Women often pay slightly lower premiums because they generally have longer life expectancies. |
| Policy type | Participating whole life policies usually cost more than non-participating policies because of their dividend potential. |
| Payment period | Limited-pay policies often have higher annual premiums than lifetime-pay policies since payments are compressed into fewer years |
| Occupation | High-risk occupations may increase premiums depending on the insurer. |
| Lifestyle and hobbies | Activities such as skydiving, scuba diving, or motor racing may result in higher rates. |
| Policy riders | Optional add-ons, such as critical illness, child, or disability riders, increase the overall cost of your policy. |
| Payment frequency | Some insurers offer modest savings if you pay annually instead of monthly. |
When should you purchase whole life insurance?
The best time to purchase whole life insurance is before you have significant financial responsibilities or while you are still young and healthy. Purchasing a policy earlier gives you access to lower premiums, which scale accordingly based on your age and other factors.
You can also consider purchasing whole life insurance before major milestones like starting a family or buying a house. The death benefit and cash value can protect your beneficiaries from financial hardships should you pass away unexpectedly.
Learn the best time to buy life insurance in Canada
Should you buy whole life insurance for your child?
Many Canadian parents and grandparents purchase whole life insurance for children to give them lifelong coverage at a young age. Buying coverage while a child is young can lock in lower premiums for life, guarantee their future insurability regardless of changes in health, and begin building cash value that they can access later in life, subject to the policy terms.
One of the most popular options is a 20-pay whole life policy. With this payment option, premiums are paid for only 20 years, but the child keeps lifelong coverage without making any further premium payments once the policy is fully paid up.
What is the cash value of whole life insurance?
One of the biggest advantages of whole life insurance is that it builds cash value in addition to providing a guaranteed death benefit. Cash value in life insurance is essentially an accumulated savings component funded by a portion of the premiums you pay.
This cash value amount grows over time at a guaranteed rate and can be accessed tax-deferred during your lifetime through policy loans, withdrawals, or even to cover premium payments. It is also worth noting that this amount is separate from the death benefit. At death, beneficiaries receive the policy’s death benefit (base amount plus any paid‑up additions and dividends on deposit, minus loans/interest). The accumulated cash value generally remains with the insurer and is not paid out in addition to the death benefit.
How does cash value grow?
During the early years of the policy, a larger portion of your premium goes toward insurance costs and administrative expenses. As a result, the cash value grows gradually. However, as the policy matures, the cash value typically increases at a faster pace.
Additionally, if you own a participating whole life policy, annual dividends may further increase your cash value and death benefit. Unlike market-based investments, guaranteed cash value is not affected by volatility. This makes it a relatively stable long-term commitment.
How to use cash value in whole life insurance?
You can access the cash value of a whole life insurance policy by taking out a policy loan, making a partial withdrawal, using the cash to pay premiums, or fully surrendering the policy.
Each option has different tax implications and may affect your policy’s cash value or death benefit, so it’s important to understand how they work before accessing your policy.
Here’s an overview of how you can use the cash value of your whole life insurance policy:
| Method | How it works | Tax implications | Impact on policy |
| Policy loan |
|
|
|
| Cash withdrawal |
|
|
|
| Pay premiums |
|
|
|
| Surrender the policy |
|
|
|
What are whole life insurance dividends?
If you purchase a participating whole life insurance policy, you may receive annual dividends from your insurer. These dividends are based on the performance of the insurer’s participating account and may be paid to eligible policyholders
The dividends are issued when the participating account performs better than expected in terms of investment returns, claims experience, and operating expenses. Additionally, dividend scale interest rates and payouts vary by insurer and can change over time. While these amounts are not guaranteed, they add flexibility and long-term value to your policy
How to use your whole life insurance dividends?
Similar to the cash value component, you can use your dividends to purchase additional paid-up life insurance, receive cash payments, or even repay your outstanding policy loans.
Here’s an overview of how you can use your whole life insurance dividends:
| Dividend option | How it works |
| Paid-up additions | Purchase additional fully paid-up life insurance, increasing both cash value and the death benefit |
| Cash payment | Receive the dividend directly as cash |
| Premium reduction | Use dividends to pay some or all of your premium payments |
| Deposit with the insurer | Leave dividends on deposit to earn interest, subject to the insurer’s rates |
| Loan repayment | Apply dividends toward outstanding policy loans |
What is your Whole Life Insurance worth?
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by
Can you cancel your whole life insurance policy?
Yes, most whole life insurance policies can be cancelled at any time. However, since these policies build cash value, cancelling them differs from cancelling a term life policy. If you surrender your whole life insurance policy, the insurer generally pays you the available cash surrender value after deducting any applicable surrender charges, outstanding policy loans, or unpaid interest. Once cancelled, your coverage ends, and your beneficiaries will no longer receive a death benefit.
Like most life insurance policies in Canada, whole life insurance also includes a free-look (cooling-off) period, typically lasting 10 to 30 days after you receive your policy. During this period, policyholders can review and cancel the policy, receiving a full refund of any premium paid.
Are there any exclusions to whole life insurance?
While whole life insurance covers natural and accidental death, there are certain exclusions and situations where a claim may be denied, or the policy may become void.
Here’s an overview of common exclusions to whole life insurance:
| Exclusion | What you need to know |
| Death by suicide | Most policies have a two-year suicide exclusion, similar to the contestability period. If death occurs during this time, the death benefit is usually not paid, though premiums may be refunded. |
| Death due to risky activities | If you participate in high-risk activities, such as skydiving or scuba diving, the insurer will assess the risk during underwriting. Depending on the activity, you may be offered standard coverage, charged a higher (rated) premium, or have an exclusion added to your policy. Any exclusions or premium adjustments will be explained before your policy is issued. |
| Homicide involving the beneficiary | If the beneficiary is involved in the policyholder’s death, they cannot receive the payout under Canada’s “slayer rule” |
| Fraud or misrepresentation | Providing false or incomplete information on your application can result in policy cancellation or claim denial |
| War and terrorism | Some policies may limit or exclude deaths caused by war, armed conflict, or terrorism |
| Undisclosed pre-existing medical conditions | Failing to disclose requested medical information can void your policy or lead to a denied claim or policy cancellation |
Exclusions vary by insurer and policy. Review policy wordings for specific limitations and definitions that apply to your coverage.
How does whole life compare to other life insurance policies available?
Whole life insurance is one of the many types of life insurance available in Canada. Depending on your financial goals, you may also consider term life insurance, universal life insurance, Term-to-100 insurance, or no-medical life insurance.
Here’s a quick overview of how whole life insurance compares to other popular options:
| Feature | Whole life insurance | Term life insurance | Term-to-100 insurance | Universal life insurance | No-medical life insurance |
| Coverage | Lifetime | 10–30 years | Lifetime | Lifetime | Term or lifetime |
| Premiums | Fixed | Lowest, fixed during term | Fixed | Flexible | Higher |
| Cash value | Guaranteed | No | No | Investment-linked | Permanent policies only |
| Medical exam | Usually required | Often required* | Usually required | Usually required | Not required |
| Investment/Cash growth | Guaranteed cash value | None | None | Investment options | Depends on policy |
| Death benefit | Guaranteed for life | Guaranteed during term | Guaranteed for life | Flexible | Guaranteed if eligible |
| Flexibility | Moderate | Low | Low | High | Moderate |
| Best for | Estate planning & lifelong protection | Temporary financial needs | Affordable permanent coverage | Lifelong coverage with investment flexibility | Applicants with health concerns |
| Cost | Highest | Lowest | Moderate | High | Higher than medically underwritten policies |
For a detailed comparison of the plans, check out the different types of life insurance in Canada.
Is whole life insurance worth it in Canada?
Yes, whole life insurance can be worth it if you are seeking lifelong financial protection, guaranteed cash value growth, and estate planning benefits. Unlike term life insurance, whole life insurance is not designed solely to replace your income for a limited period. It provides permanent financial protection while building cash value, in exchange for comparatively higher premiums.
Whole life insurance may be worth considering if you:
- Want guaranteed lifetime coverage
- Want to leave a tax-free inheritance for your family
- Need funds to cover estate taxes or final expenses
- Have dependents who will rely on your financial support
- Want to build guaranteed cash value over time
However, if your priority is affordable coverage at lower premiums, you may consider a term life policy. While it does not build cash value or pay dividends, it offers high coverage at relatively low premiums, making it a good choice for individuals with debts, mortgages, and other temporary financial obligations.
Additionally, some Canadians combine term life and whole life policies. They purchase term policies for large and temporary financial obligations, while relying on a smaller whole life insurance policy for lifelong protection and estate planning.
Our advisor’s take on whole life insurance
At PolicyAdvisor, we recently helped a 42-year-old parent who had already secured term life insurance to protect their family’s income and was seeking coverage that would last beyond retirement. Their goal was to leave a financial legacy for their children while building an asset they could access later in life if needed.
Client profile
- Age: 42
- Family: Married with two children
- Primary concern: Lifelong financial protection and leaving an inheritance
- Coverage goal: $1,000,000 in permanent life insurance
Why we recommended whole life insurance
- Guaranteed lifetime coverage that will not expire after retirement
- Fixed premiums that remain predictable over the life of the policy
- Guaranteed cash value that grows over time and can be accessed if needed
- Opportunity to earn dividends through a participating policy, which helps increase long-term policy value
How to purchase whole life insurance in Canada?
PolicyAdvisor’s licensed life insurance advisors can help you compare whole life insurance quotes from Canada’s leading insurers based on your age, budget, health, coverage needs, and financial goals.
Whether you are looking to build wealth, protect your family, or leave a lasting financial legacy, our advisors at PolicyAdvisor can help you choose the whole life insurance policy that best aligns with your long-term objectives.
Frequently asked questions
Is the whole life insurance death benefit taxable in Canada?
No. In most cases, life insurance death benefits are paid tax-free to your named beneficiaries.
What is the difference between whole life and term life insurance?
Term life insurance provides coverage for a fixed period and does not build cash value. Whole life insurance provides lifelong coverage, builds guaranteed cash value, and may pay dividends if it is a participating policy.
How long does it take to build cash value?
Cash value begins accumulating once your policy is in force, although growth is generally slower during the first few policy years. It typically accelerates over the long term.
Can I borrow money from my whole life insurance policy?
Yes, most whole life policies allow you to borrow against your accumulated cash value. Any outstanding loan and interest will generally reduce the death benefit if not repaid.
Are whole life insurance dividends guaranteed?
No, dividends are only available on participating whole life policies and are not guaranteed. They depend on the insurer’s financial performance.
Can whole life insurance expire?
No, whole life insurance provides lifetime coverage as long as the policy requirements are met.
Can I have more than one life insurance policy?
Yes, many Canadians own multiple life insurance policies to meet different financial needs. For example, you may combine whole life insurance with a term life policy for additional temporary coverage.
What is term life insurance in Canada? (2026 Guide)
If someone depends on your income, term life insurance is one of the most affordable solutions to protect their financial future. It offers coverage for a specific period (such as 10, 20, or 30 years), and if you pass away during the policy term, your beneficiaries receive a tax-free, lump-sum payment known as a death benefit.
Unlike permanent life insurance, term life insurance does not build cash value or include an investment component. Instead, it focuses on providing high-value financial protection at significantly lower premiums, making it one of the most popular types of life insurance for Canadian families.
Need insurance answers now?
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
What is term life insurance in Canada?
Term life insurance is a type of life insurance that provides financial protection for a set number of years. If the insured dies during that coverage period, the insurer pays a tax-free lump sum to their chosen beneficiaries. Since term life insurance does not have a savings or investment component, it typically costs much less than permanent life insurance. This is great for applicants seeking higher coverage amounts for lower premiums.
For example, a healthy 35-year-old parent may be able to purchase $500,000 in coverage for somewhere between $25 and $40 per month. The same amount of coverage for whole life insurance could cost around $250 to $400 per month. This makes whole life roughly ten times more expensive than a term life policy.
Term life insurance in Canada: At a glance
| Feature | Details |
| How it works | Pay premiums for a fixed term. If you die during the term, your beneficiaries receive a tax-free payout |
| Coverage period | Typically 10, 15, 20, 25, or 30 years |
| Who is it best for | Families, homeowners, parents, young professionals, and business owners |
| Cost | Can cost up to 90% less than permanent life insurance since coverage lasts for a fixed period. |
| Cash value | None. Term life insurance is designed solely to provide financial protection |
| Death benefit | Tax-free payout to your beneficiaries |
| Renewal | Most policies are renewable, but premiums typically increase |
| Can I convert it? | Most policies can be converted to permanent life insurance without a medical exam before a specified age or conversion deadline |
| Common coverage amounts | Typically $100,000 to $5 million or more |
Types of term life insurance in Canada
Although term life insurance provides temporary coverage, insurers offer it in several structures to suit different needs. The most common options are Term 10, Term 20, and Term 30 policies, while some insurers also provide level term, annual renewable term (ART), and return of premium (ROP) term policies.
Here’s a quick overview of the different types of term life insurance in Canada:
| Type of term life insurance | How it works | Best for |
| Level term life insurance | Premiums and death benefit remain the same throughout the policy term | Most Canadians seeking predictable costs |
| Annual renewable term (ART) | Coverage renews every year, with premiums increasing annually based on your age | Short-term coverage needs or temporary financial obligations |
| Return of premium (ROP) term | Returns some or all eligible premiums if you outlive the policy term, depending on the insurer and policy | People who want the possibility of getting premiums back |
| Term 10 (T10) | Provides level coverage for 10 years | Short-term financial obligations, such as personal loans or smaller mortgages |
| Term 20 (T20) | Provides level coverage for 20 years | Families, homeowners, and parents |
| Term 30 (T30) | Provides level coverage for 30 years | Long-term financial protections, such as raising children or paying off a long-term mortgage |
Pros and cons of term life insurance
How does term life insurance work in Canada?
Term life insurance has one of the most straightforward processes among insurance policies. You choose how much coverage you need and how long you want it to last. In exchange for regular premium payments, your insurer agrees to pay your beneficiaries a tax-free death benefit if you pass away during the policy term.
Here’s how a term life insurance policy usually works:
Step 1: Choosing the right coverage amount
Choose a coverage amount that would secure the financial future of your family and protect your loved ones from outstanding debts or other costs. As a general rule of thumb, many applicants choose coverage anywhere between 7 and 15 times their annual income.
Step 2: Choose your policy term
Once you have selected the coverage amount, you need to choose how long your coverage should remain in place. Most Canadian insurers offer the following periods:
| Policy type | Coverage period |
| Term 10 | 10 years |
| Term 20 | 20 years |
| Term 25 | 25 years |
| Term 30 | 30 years |
Step 3: Complete your application and pay your premiums
Once you have chosen your coverage amount and period, you will need to complete your application and name the beneficiary. Most applicants choose their close relatives, such as their spouse, children, or parents, as the beneficiary.
Once the application is completed, you will need to pay your premiums. You can make premium payments monthly or annually. Some insurers offer lower overall costs if you choose to pay annually instead of monthly.
Step 4: Your beneficiaries receive the death benefit
If you pass away while your policy is active, your beneficiaries submit a claim to the insurance company. Once the claim is approved, the insurer pays the death benefit as a tax-free lump sum.
Unlike investment or estate assets, term life insurance proceeds are typically paid directly to named beneficiaries, helping them access funds more quickly during a difficult time.
How to choose the right term life insurance coverage amount?
Choosing the right amount of term life insurance is one of the most important decisions you will make when buying a policy. The coverage amount should be enough to help your loved ones maintain financial stability by replacing the lost income and support you provide if you were to pass away unexpectedly.
When deciding the coverage amount, you should keep in mind factors such as:
- Outstanding mortgage balance
- Personal loans or other debts
- Daily living expenses
- Future childcare costs and education expenses
- Funeral and final expenses
- Income replacement for several years
For many families, a common rule of thumb suggests choosing coverage between 7 and 15 times their annual income. This offers a sizable amount that can cover most future expenses with ease.
Using the DIME method to calculate term life insurance
Another method of calculating how much coverage you need is to use the debt, income, mortgage, and education (DIME) method. It is a simple way to estimate how much term life insurance you may need by considering four major financial obligations your family may need to cover if you pass away.
Let’s assume Sarah is 35 years old, married, has one young child, and is the primary income earner for her family.
Here’s an estimate of her term life insurance needs using the DIME method:
| DIME factor | Amount |
| Debt (credit card balance and car loan) | $25,000 |
| Income replacement (10 years of annual income at $100,000) | $1,000,000 |
| Mortgage (remaining mortgage balance) | $500,000 |
| Education (future education costs for one child) | $150,000 |
| Total estimated life insurance needed | $1,675,000 |
Based on the DIME method, Sarah may consider approximately $1.7 million to 2 million in term life insurance coverage. This amount could help her family pay off outstanding debts and offer financial security for the foreseeable future. While it is a handy index, your ideal coverage amount may differ based on factors such as savings, investments, and long-term financial goals.
Do you need a medical exam for term life insurance?
Not always. Many Canadians can qualify for term life insurance without a medical exam. However, this depends on your age, health, lifestyle, and the amount of coverage you apply for. Many insurers now offer accelerated underwriting and simplified issue options, which allow eligible applicants to qualify without a medical exam. Some insurers also offer no-medical life insurance, although these policies may have lower coverage limits and higher premiums.
However, you may still need a medical exam if:
- You are applying for a high coverage amount
- You are older or have certain pre-existing medical conditions
- The insurer requires additional health information based on your application
Most term life insurance policies in Canada may require you to submit a health questionnaire and furnish information about your height, weight, blood pressure, and medical history. If you are a smoker, you may be subject to additional blood, urine, or cotinine tests. Some applicants may also be required to undergo an electrocardiogram (ECG).
How much does term life insurance cost in Canada?
The cost of a term life insurance policy ranges between $21.60 and $741.60 per month. Your premiums depend on the coverage amount and personal factors, such as gender, age, smoking status, and health.
Here is a sample term life insurance rate for $500,000 coverage:
| Age | 10-Year Term | 20-Year Term | 30-Year Term | Term 100 |
| 25 | $21.60 | $27.90 | $36.90 | $196.58 |
| 35 | $22.04 | $30.15 | $53.55 | $292.50 |
| 45 | $39.15 | $66.60 | $134.10 | $470.25 |
| 55 | $96.75 | $198.90 | $357.30 | $741.60 |
| 65 | $324.45 | $610.65 | na | na |
*Monthly premiums for non-smoking male
Some insurers also offer lower overall premiums if you choose to pay annually instead of monthly. Speak with your advisor to compare the payment options and determine which offers the best value for your policy.

How are term life insurance premiums calculated?
Life insurance companies calculate your premium by assessing the likelihood of paying a claim during the policy term. This is primarily based on your age, health status, smoking status, coverage amount, and other related features.
Here’s a brief overview of the factors that may affect term life insurance premiums in Canada:
| Factor | How it affects your premium |
| Age | Younger applicants typically pay lower premiums |
| Health | Good overall health can help you qualify for lower rates |
| Smoking status | Smokers and tobacco users generally pay significantly more |
| Coverage amount | Higher coverage amounts result in higher premiums. |
| Policy term | Longer terms, such as 30 years, usually cost more than shorter terms like 10 or 20 years |
| Gender | Women often pay slightly lower premiums than men because they generally have longer life expectancies |
| Family medical history | A family history of serious illnesses may affect your premium, depending on the insurer |
| Occupation | High-risk jobs, such as mining or commercial aviation, can lead to higher premiums |
| Hobbies and lifestyle | Activities like skydiving, scuba diving, or motor racing may increase your rates |
| Policy riders | Optional add-ons, such as critical illness or child riders, increase the cost of your policy |
| Payment frequency | Paying annually instead of monthly may qualify you for savings with some insurers. |
When should you purchase term life insurance?
The best time to purchase term life insurance is while you are still young and healthy, before taking on major financial responsibilities. Buying a policy earlier can help you lock in lower premiums, as life insurance generally becomes more expensive with age and as health changes.
In terms of financial responsibilities, you can consider purchasing term life insurance before major milestones such as starting a family, buying a house, or taking on significant debts or loans. The death benefit can help protect your beneficiaries from financial hardships should you pass away unexpectedly.
Learn which is the best time to buy life insurance in Canada
What happens when your term life insurance expires?
Once your policy expires, it does not pay out automatically. Instead, you have several options, depending on your insurer and personal circumstances.
Here is an overview of the choices you can make once your term life insurance policy expires:
| Option | What it means | Typical age limit |
| Renew your policy | Continue your coverage, but at a higher premium | Up to age 75–85, depending on the insurer and policy |
| Convert to permanent life insurance | Switch to a permanent policy without additional medical underwriting if you are eligible | Usually available until age 65–71 or before the policy’s conversion deadline |
| Buy a new policy | Apply for a brand-new term policy based on your current age and health | Most insurers accept new applications up to age 75–80, depending on policy and term |
| Let the policy expire | Coverage ends, and no further premiums are required | No age limit. Coverage ends after the term is over |
If you renew your policy, you will have to pay an increased premium based on your age and other factors at the time of renewal. Renewing can be a good option if you still have financial responsibilities and wish to remain covered for an extended period.
On the other hand, many applicants also convert their term life insurance into a permanent life insurance policy before a specified age or deadline. It is great for those who want lifelong coverage or are interested in estate planning.
However, you can choose to purchase a new policy with different coverage amounts or policy terms to align with your changing needs or financial planning. Alternatively, you can also choose to let the policy expire if your financial needs are met or you have enough savings to offset future costs.
Can you cancel your term life insurance policy?
Yes, most term life policies can be cancelled at any time. If you no longer need coverage, you can cancel your policy by notifying your insurer or advisor. Once cancelled, your coverage ends, and your beneficiaries will no longer be eligible to receive a death benefit. In most cases, you will not receive a refund on the premiums you have already paid.
Additionally, most Canadian insurers are required to provide a free look or cooling-off period after you receive your policy contract. During this time, you can review the policy terms and cancel the policy for a full refund of any premiums you have paid (provided you have not raised any claims during this time). While the industry standard is ten days, some insurers may offer up to 30 days.
Are there any exclusions to term life insurance?
While term life insurance generally covers natural and accidental death, there are certain exclusions where a claim may be reduced or denied. These exclusions vary by insurer and policy, so it’s important to review your policy contract carefully.
Here’s an overview of common exclusions to term life insurance:
| Exclusion | What you need to know |
| Death by suicide | Most policies have a two-year suicide exclusion as part of the contestability period. If death occurs during this time, the death benefit is usually not paid, though premiums may be refunded. |
| Death due to risky activities | Deaths resulting from high-risk activities (such as skydiving, racing, or private aviation) may be excluded unless you have additional coverage or a rider |
| Homicide involving the beneficiary | If the beneficiary is involved in the policyholder’s death, they cannot receive the payout under Canada’s “Slayer Rule” |
| Drug- and alcohol-related deaths | Claims may be denied if drug or alcohol use directly contributed to the insured’s death, based on the insurer’s investigation and exclusion policy |
| Criminal acts and illegal activities | Deaths that occur while committing a crime or engaging in illegal activities are generally not covered |
| Fraud or misrepresentation | Providing false or incomplete information on your application can result in policy cancellation or claim denial |
| War and terrorism | Some policies exclude deaths caused by war, armed conflict, or terrorism |
| Death in high-risk countries | Coverage may be limited or excluded if death occurs in countries affected by war, civil unrest, or political instability |
| Undisclosed pre-existing medical conditions | Failing to disclose a medical condition can void your policy or lead to a denied claim, even if the condition contributed to your death |
| Self-inflicted injuries | Deliberate self-harm, dangerous stunts, or certain situations may not be covered |
How does term life compare to other life insurance policies available in Canada?
Aside from term, you can get permanent life insurance. Unlike a fixed term for 10 or 20 years, these policies cover you for the rest of your life and may have an investment component.
Some of the most common types of permanent life insurance are:
- Whole
- Universal
- Term-to-100
Here’s a quick overview of how term life insurance compares to other popular options:
| Feature | Term life insurance | Term to 100 insurance | Whole life insurance | Universal life insurance |
| Coverage duration | Fixed term (e.g., 10, 20, or 30 years) | Lifetime (coverage to age 100) | Lifetime | Lifetime |
| Premiums | Lowest and fixed during the term | Fixed until age 100 (or for life, depending on the policy) | Higher but generally fixed for life | Flexible within policy limits |
| Cash value | No | No | Yes (guaranteed growth) | Yes (investment-linked) |
| Medical exam required | Often required, but non-medical options are available | Usually required | Usually required | Usually required |
| Investment component | None | None | Guaranteed cash value accumulation | Flexible investment options |
| Death benefit | Guaranteed if premiums are paid during the term | Guaranteed for life if premiums are maintained | Guaranteed for life | Can be adjusted within policy rules |
| Policy flexibility | Limited (renew or convert before expiry) | Low | High (cash value options with fixed coverage) | High (flexible premiums, investments, and death benefit) |
| Best for | Income replacement, mortgage protection, raising a family, and temporary financial obligations | Lifelong coverage without paying for cash value or investment features | Estate planning, lifelong financial protection, and leaving an inheritance | High-income earners seeking lifelong coverage with investment flexibility |
| Typical cost | Lowest | Lower than whole life but higher than term life | Highest | Higher than term; varies based on investment choices |
For a detailed comparison of the plans, check out the different types of life insurance in Canada
Is term life insurance worth it in Canada?
Yes, term life insurance is worth it for most Canadians who are seeking affordable financial protection for a specific period. The policy offers high coverage at relatively low premiums, making it a good choice for individuals with debts, mortgages, and high financial liabilities.
A term life insurance policy helps your loved ones replace lost income and pay off major outstanding debt, ensuring the burden does not rest upon them. It is one of the most cost-effective options for safeguarding your family from financial responsibilities should you pass away.
However, if you need lifelong coverage or are seeking to build cash value and estate planning, a permanent life insurance policy may be more suitable. While the premiums are significantly higher than term life, it provides more financial protection and rewards you with cash value and lifelong protection.
If your goal is to protect your family’s finances and cover immediate debts without paying the higher cost of permanent life insurance, term life insurance offers excellent value and coverage.
Our advisor’s take on term life insurance
At PolicyAdvisor, we recently helped a 35-year-old parent secure affordable term life insurance to protect their family’s financial future. They were seeking enough coverage to replace their income, pay off their newly acquired mortgage, and support their children’s future while keeping monthly premiums affordable.
Client profile
- Age: 35
- Family: Married with two young children
- Primary concern: Income replacement and mortgage protection
- Coverage goal: $1 million in affordable life insurance
Why we recommended term life insurance
- Affordable premiums for a high coverage amount during their peak earning years
- Coverage aligned with their mortgage term to help pay off outstanding debt
- Flexibility to extend the term if financial protection is still required
- The option to convert to permanent life insurance when financial needs change
How to purchase term life insurance in Canada?
PolicyAdvisor’s licensed life insurance advisors can help you compare term life insurance quotes from Canada’s leading insurers based on your age, budget, health, coverage needs, and financial goals.
Whether you are looking to protect your family, cover your mortgage, or secure affordable coverage for a specific period, our advisors at PolicyAdvisor can help you choose the right term length, coverage amount, and optional riders to fit your needs.
Connect with an advisor
Looking for the best term life insurance quotes in Canada? PolicyAdvisor makes it easy to compare quotes from Canada’s leading life insurance companies.
Our advice is 100% free, with no obligation to buy. Whether you are comparing insurers, choosing a policy term, or deciding how much coverage you need, we are here to guide you every step of the way.
Frequently asked questions
Is the term life insurance death benefit taxable in Canada?
No. Life insurance death benefit is generally tax-free in Canada. The amount is paid tax-free to the named beneficiaries if the policyholder passes away during the term.
Can I have more than one term life insurance policy?
Yes, many Canadians own multiple life insurance policies to cover different financial needs or life stages. Additionally, you can combine term and permanent policies to satisfy different financial goals.
Can I convert my term life insurance into permanent life insurance?
Yes, many Canadian insurers allow you to convert your policy before a specified age or conversion deadline without additional medical underwriting. Check your policy or consult with your advisor for eligibility requirements.
What happens if I miss a premium payment?
Most insurers provide a grace period (usually 30 or 31 days) during which you can make the missed payment and keep your coverage active. If the premium remains unpaid beyond this grace period, your policy may lapse.
Can I renew my term life insurance policy after it expires?
Yes, in many cases. Many term life insurance policies in Canada are renewable within a specified period or until a specified age. If you choose to renew, your premiums will typically increase based on your age at the time of renewal.
Does term life insurance cover accidental death?
Yes, most term life insurance policies cover accidental death, alongside death due to illness or natural causes, provided the policy is in force and no exclusions apply.