Life Insurance Age Limit in Canada – Comprehensive Guide to Rates and Coverage

What is the age limit for life insurance in Canada?

In Canada, the maximum age limit for purchasing life insurance is between 75 and 85. For term life insurance, you can continue to renew your policy until you reach 85 years of age.

For whole life or universal life insurance, you can purchase a life insurance policy until you reach the company-approved age limit.

However, the exact age limit may vary from one company to another based on their underwriting guidelines. For instance, companies like Sun Life and Desjardins can offer life insurance to individuals up to 85 years of age.

Types of life insurance policies and their age limits

Although the age limit varies from one insurance provider to another, here are a few general age limits based on various types of life insurance. Take a look:

  • Term life insurance: Applicants may qualify for term life insurance up to around 70 or 75 years old. After this age, options may become limited, and insurers often restrict the length of coverage available
  • Whole life insurance: This type of insurance generally allows applicants up to 85 years old. Whole-life policies provide lifelong coverage and can be a viable option for older individuals seeking insurance
  • Guaranteed issue life insurance: This type of policy is specifically designed for seniors and usually has an age limit of about 75 years old. It is accessible even for those with pre-existing conditions, though it may come with higher premiums

Find out more about the various types of life insurance in Canada through our detailed blog.
Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

How age limit impacts life insurance policy premiums

Life insurance premiums increase with age due to the higher risks associated with older individuals. As people age, the likelihood of developing health issues or facing mortality increases. As a result, insurers raise premiums to cover potential claims. 

The risk of chronic conditions, hospitalization, and other health-related expenses grows over time. These risk factors prompt insurers to adjust premiums accordingly to ensure their own financial stability.

Factors influencing premium rates of life insurance policies

Here are a few factors influencing life insurance premium rates:

  • Age: Younger individuals generally pay lower premiums since they are considered less risky and likely to live longer
  • Health status: Pre-existing conditions, family’s medical history, and lifestyle choices like smoking can significantly impact premium rates
  • Policy type and coverage amount: Whole life insurance typically has higher premiums than term life insurance. Higher coverage amounts also lead to higher premiums
  • Occupation: High-risk jobs can result in higher premiums due to the increased likelihood of accidents and injury

Cost of life insurance by age

Life insurance premiums may vary according to an individual’s age. The older a person gets, the higher the cost of life insurance may become. 

Check out our detailed table depicting the average monthly premiums paid by men and women of different age groups:

Term life insurance for ages 25-65

Age Group Non-smoker Male Non-smoker Female Smoker Male Smoker Female
25-34 $15 $13 $30 $25
35-44 $20 $18 $45 $35
35-44 $50 $40 $100 $80
55-64 $100 $80 $180 $150
65+ $200 $150 $350 $300

Whole life insurance for ages 25-65

Age Group Non-smoker Male Non-smoker Female Smoker Male Smoker Female
25-34 $275 $250 $350 $300
35-44 $350 $300 $475 $400
35-44 $500 $425 $700 $575
55-64 $750 $625 $1,100 $900
65+ $1,200 $1,000 $1,800 $1,500

Why age limits matter in life insurance policies

Knowing about the age limit of life insurance can be beneficial for most individuals seeking coverage. Here are a few reasons why age limit matters:

Risk assessment

Companies assess risk based on an individual’s age. As individuals age, their likelihood of health issues and mortality increases, which directly impacts premium rates. 

Insurers set age limits to manage their risk exposure effectively and ensure financial stability.

Financial planning and security

The true purpose of life insurance is to provide a financial safety net to the insured’s family. Prioritizing the age limit ensures that the insured can secure coverage while they’re financially stable. 

By planning ahead and getting life insurance within the standard age limit, the insured individual can ensure the overall financial security of their loved ones in their absence.

Long-term financial commitment

Since life insurance is usually a long-term investment, it requires the insured individual to have the financial stability and affordability for paying premiums. 

Getting life insurance at the right time ensures longer coverage periods with lower premiums. On the other hand, late applicants may only receive shorter coverages at a much higher premium.

If you’re a senior looking for the right life insurance fit, we’ve got you covered. Read our blog to find out more.

Types of life insurance for seniors

Seniors in Canada can avail life insurance options tailored to their unique health conditions and coverage needs:

1 Term life insurance

Term life insurance is ideal for seniors under 75 who seek coverage for a specific period. It provides a death benefit if the policyholder passes away within the term but doesn’t build cash value. Premiums are generally lower than permanent life insurance.

2 Whole life insurance

This is a type of permanent insurance that covers the policyholder for life, provided premiums are paid. 

It also accumulates cash value over time, which can be borrowed against or withdrawn. Whole life insurance can be availed by seniors up to 85 years of age.

3 Simplified issue life insurance

Simplified issue life insurance involves a simple health questionnaire without a medical exam. It’s a good option for seniors with minor health concerns. This insurance provides faster approval and moderate coverage.

4 Guaranteed issue life insurance

Guaranteed-issue life insurance is ideal for seniors with significant health issues. This policy provides guaranteed approval regardless of health status. However, these insurance policies have higher premiums with lower coverage amounts.

Finding the best life insurance rates for seniors

Getting a competitive life insurance rate for seniors can be quite tricky but not impossible. For individuals over 50, a detailed comparison of multiple insurance policies and their quotes can help them find the right coverage at the most affordable price.

Tips for obtaining competitive quotes

Here are a few effective tips for obtaining the most competitive life insurance rates in Canada. Take a look:

  • Choose the right type of insurance: Depending on your health and financial needs, select a policy type that offers the best balance of coverage and cost, such as term life, whole life, or guaranteed issue life insurance
  • Consider a medical exam: If you’re in good health, opting for a traditionally underwritten policy with a medical exam may result in lower premiums compared to no-medical or guaranteed issue policies
  • Review policy features: Pay attention to policy features like renewal options, cash value accumulation, and additional riders (e.g., critical illness or long-term care). These can add value to your policy or adjust it to better fit your needs
  • Work with an insurance broker: An experienced broker can provide personalized advice, help you navigate different options, and negotiate better rates with insurers on your behalf

Is there a type of life insurance where premiums do not increase with age?

Yes, some life insurance policies such as participating whole life insurance and group benefits, have fixed premium rates. 

Participating whole life insurance policies have level premiums — the premiums do not change for the entirety of the policy duration. 

Group life insurance policies typically have level premiums for all members regardless of age, gender, or health status. 

Gender differences in life insurance costs

Gender differences significantly impact life insurance costs. This usually occurs due to varying life expectancies and health risks associated with each gender.

Some of the key factors that influence the costs of life insurance are as follows:

  • Life expectancy: Women generally live longer than men.  This indicates the fact that women are perceived as lower risk, leading to lower life insurance rates
  • Health risks: Men are statistically more prone to certain health conditions, such as heart disease and hypertension, which can increase mortality risk. Insurers also consider lifestyle choices. Men are more likely to engage in risky behaviors, such as smoking and heavy drinking. These factors further influence premium costs
  • Occupational hazards: Men often work in higher-risk occupations, such as construction or mining. This may lead to higher insurance premiums compared to women, who are more likely to work in lower-risk jobs

Do women pay more by age for life insurance?

Women generally pay less for life insurance compared to men, even as they age. However, premiums for women still increase with age as the risk of health issues and mortality rises. 

Younger women pay comparatively lower premiums than older women for the same amount of coverage.
Still looking for the best life insurance rates?
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Frequently asked questions (FAQs)

Should a 75-year-old have life insurance?

Yes, a 75-year-old individual should have life insurance. Having life insurance can ensure that the individual’s family remains protected in their absence.

It can also help the family pay for their loved one’s funeral and cover any remaining mortgage amount.

Can I be denied life insurance because of age?

Yes, you can be denied life insurance because of age, especially if you’re applying for a new policy later in life. Many insurers have maximum age limits for certain types of life insurance policies, like term life insurance, and may decline coverage if you’re above that age. 

As you age, insurers may consider you a higher risk due to health concerns, leading to potential denial or higher premiums for coverage. 

Does life insurance expire with age?

If you have term life insurance, the policy will expire once the specified term period is over. However, whole life insurance ensures lifetime coverage as long as the insured individual continues to pay the premiums.
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What Happened to Great-West Life Insurance?

Great-West Life went through major changes in the company’s structure in 2020. The following is a brief history of Great-West Life Insurance, the current status of the company, and how to reach them regarding your policies.

If you’re looking for Canada Life
(formerly Great-West Life),
please contact 1-888-252-1847

History and Ownership: Great-West Life Assurance Company

Great-West Life Assurance Company was founded and incorporated in the year 1891 in Winnipeg, Manitoba. It wasn’t until 1942 that Great-West Life became the first Canadian company to enter into the accident and health insurance business.

Jeffrey Hall Brock started the company due to a lack of insurance options offered to Western Canadians at the time. The head office was developed within the “Exchange District” of Winnipeg, which is located on the corner of Rorie Street and Lombard Avenue.

Interestingly, in 1912, two Great-West Life policyholders were passengers on the Titanic, and the company covered their policies with no questions asked (Great-West Life was also responsible for the first death payout of a policyholder in 1893). The word assurance was used instead of “insurance” during these early days, as that was the term more commonly used throughout the British Commonwealth.

Merger and consolidation as Canada Life

Over the years they would become colloquially known as Great-West Life above anything else, although the beginning of 2020 brought a big change for the company. In 2019, the company announced it would be merging its brand with other companies under the same ownership, London Life and Canada Life.

The company is now known as Canada Life, although there are times where you will see references to Great-West Life through the transition period over the next few months and years. Rest assured, all of the policies you had before this merger will continue with the newly combined companies. These companies have a deep history in the Canadian insurance landscape.

London Life Insurance Company

London Life Insurance Company is almost 140-years old and was responsible for serving well over 2 million Canadians. They previously merged with Great-West Life in 1997 when they completed their first merger until the company merged again with Canada Life in 2003 while retaining its branding and still operating as a separate entity.

London Life is known for its “Freedom 55” motto, which refers to its financial services which aim to help their customers save enough money to where they can retire at the age of 55.

Canada Life Financial Corporation

Hugh Cossart Baker Sr. founded the Canada Life Assurance Company on August 21st, 1847. The firm was officially incorporated in 1849, and had to fight off a takeover bid by Manulife in 2003; this led to their eventual acquisition by the Great-West Life Assurance Company (through owner Power Financial Corporation) in that year.

The very first head office of Canada Life Assurance Company was located in Hamilton, Ontario, eventually moving to what is now known as the “Birks Building” (on King Street East and Hughson Street South in Hamilton). They moved several other times, once to the Canada Life Building that was finished development in 1895, and once more to their eventual Toronto headquarters in 1900.

Cawthra House was the company headquarters from 1926 to 1929 at King and Bay Streets in Toronto. They acquired and founded additional sister companies like Canada Life (UK) and Crown Life Insurance Company of Canada (CLICC).

What is Great-West Life Called now?

Canada’s Minister of Finance provided the final approval of amalgamation (the process of a company and their holding companies combining to become one large entity) of the Canadian insurers on November 25, 2019. The corporations and subsidiaries that were merged to create what we now know as The Canada Life Assurance Company are:

  • Great-West Life Assurance Company
  • London Life Insurance Company
  • Canada Life Assurance Company (and their holdings)
  • Canada Life Financial Corporation
  • London Insurance Group Inc.

All of these companies operated as separate entities until January 1st, 2020 when the merger became official and The Canada Life Assurance Company began operation. Canada Life is now considered one of the country’s biggest life insurance companies and administers any insurance plan once owned by Great-West Lifeco.

best life insurance canada

If you’re looking for Canada Life
(formerly Great-West Life),
please contact 1-888-252-1847

Great-West Life Insurance products

Great-West Life offered many different types of insurance before the merger took place. Below you’ll find a list of the many products and investment management services that Great-West Life Insurance offered to their customers:

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

What happened to my Great-West Life insurance policy?

Any insurance policies previously held with Great-West Life will now be serviced by Canada Life; you can find all of the information surrounding your coverage on the Canada Life website. As of January 1st, 2020, all of the contracts and policies associated with any of the merged companies transferred over to The Canada Life Assurance Company.

Amalgamation allows all of your policies and contracts to remain unchanged, so you will continue to benefit from their services as you would in the past. The Canada Life Assurance Company is dedicated to providing clients with the best coverage possible as they complete all aspects of this merger. The companies merged to provide improved customer service, more reliable coverage, and an overall better experience for all clients. Thus everything, like your contact details, benefits information, direct deposit and Groupnet details, your plan number, and more remains unchanged as your policy is served by the new Canada Life.

If you’re wondering how you can file a claim with Great-West Life Insurance, all you have to do is contact Canada Life for more information.

How do I submit a claim to Great-West Life?

You likely have questions surrounding your Great-West Life insurance policy and whether you’re still covered (the short answer is yes), and in turn, you might wonder who you’re supposed to contact. The goal of Great-West Life’s merger is to provide customers with a superior experience, as there are more assets to work with that will help improve their service and offer more flexibility in how they service their customers.

You don’t have to sign any paperwork or fill out any forms to ensure that your policies are carried over during the merger; this is an automatic process. That said, if you have any questions about submitting a claim, your policy, or your coverage details, you can always contact Canada Life for more information or access their support page (canadalife.com/support).

Websites and almost anything associated with Great-West Life is still being updated, which is why you may still see references to the recently merged company.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Can someone have multiple life insurance policies in Canada?

Life insurance policies are incredibly flexible and customizable. Not only do you have the choice between term life insurance and permanent life insurance, but you can also add life insurance riders to tailor a policy to exactly the coverage you need. That said, there are situations where you may need to think about changing your coverage or adding more policies to the coverage you already have.

It may seem strange to hold more than one life insurance policy simultaneously. Is it even allowed? We answer that and more below.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Can you have multiple life insurance policies?

Yes, in Canada it is perfectly legal and common to have multiple policies.

While there is no legal maximum number of policies (so you can have 2 life insurance policies or many more), insurance companies will look at the total amount of coverage you are seeking to determine whether it is reasonable and consistent with your needs.

In fact, you may already be covered by multiple policies and not even know it.

As most workplace insurance benefits include one life insurance policy, you would hold multiple policies if you took out any coverage on your own.

Beyond that specific situation, you can choose to have multiple life insurance policies of your own, from separate life insurance companies if you choose.

But why wouldn’t someone just get the coverage they need and hold only one life insurance policy?

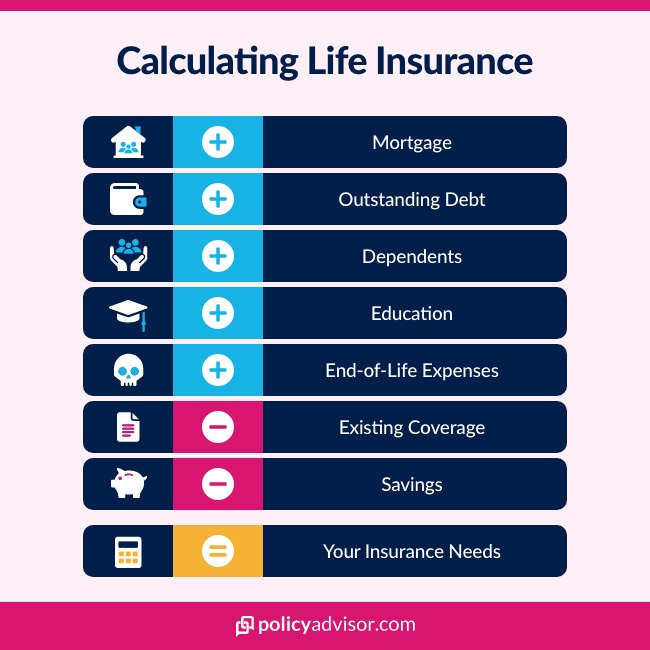
Check out PolicyAdvisor's life insurance calculator.

Why would someone want to have more than one life insurance policy?

There are several scenarios where it makes sense to hold multiple life insurance policies at the same time.

For example, you may have already secured life insurance at a competitive monthly premium in your younger years that you think is sufficient. But, life happens. Perhaps a $250,000 policy you secured at that time is not adequate now with a new mortgage or children on the way.

Instead of discarding that coverage and starting from scratch with a new policy, you can keep your existing coverage and add more through a separate policy. This additional life insurance policy can have a different term and death benefit amount to better match your evolving needs.

Other reasons for taking more than one policy include laddering and risk avoidance. Laddering is a concept where you take out multiple term life insurance policies for varying terms (like 30, 25, 20 and 10 years) and with a decreasing amount of coverage as you grow older.

The idea stems from you having less financial risk and dependents as you age: children may become less reliant on your income, and you will have more and more of your mortgage debt paid down, as these may have been the reasons you acquired life insurance in the first place. Many Canadians also use permanent life insurance as part of their laddering strategy.

Risk avoidance is rooted in the unlikely event one of your chosen insurance providers fails or goes bankrupt. Some don’t like the idea of having all of their eggs in one basket, especially in the world of finances.

By spreading coverage among several insurance carriers, they ensure they still have coverage if one goes under. While there is nothing wrong with this approach, there are many “fail-safes” in the Canadian insurance industry that protect your coverage and make sure you are taken care of should something happen to your insurance provider.

Different kinds of insurance policies cover different kinds of needs. Term life insurance is great for providing financial protection to children or covering a mortgage debt, while whole life insurance (or permanent life insurance) is commonly used for long-term estate planning.

Lastly, multiple policies should not be confused with multi-life policies that are sometimes utilized for life insurance for couples.

Pros and cons of holding multiple life insurance policies

Pros Cons
Allows you to add coverage as needs and financial goals evolve More paperwork and multiple contracts to keep track of
Can protect different needs and goals with matching coverage Multiple premium payments taken out monthly
Diversify coverage across providers Policies added later in life will be more expensive
Cost effective; only pay for coverage when you need it.

Can you apply to multiple insurance carriers at once?

Yes, you can apply to multiple insurance carriers, but there are often better and faster ways to get multiple life insurance policies then applying to several providers at the same time.

In North America, insurance companies share limited information regarding insurability of an applicant through a regulated body called the Medical Information Bureau (MIB). They do this to enhance transparency and consistency of information between the companies.

In rare cases, the information the MIB provides prevents the more unscrupulous applicants from holding too many policies simultaneously or providing false information to get insured by one company after getting declined by another.

If you are sending out multiple life insurance applications at the same time, it will raise some red flags among the providers and the MIB.

This will slow down your approval while they asses whether you have a good reason to apply to multiple carriers and in rare cases it may result in you getting out-rightly denied for coverage.

What are the alternatives to buying multiple life insurance policies?

There are many alternatives to applying for more than one life insurance policy:

  • Using riders such as term riders or accidental death riders. They can be added to a base life insurance policy rather than buying the individual coverage.
  • Adding guaranteed insurability. You can increase coverage in the future to meet your evolving needs.
  • Converting your existing term life insurance policy – or a portion of it – into whole life insurance using the conversion feature.

In any case, enlist the help of an experienced digital broker like PolicyAdvisor whether you need one life insurance policy or think you will end up owning several.

We have the institutional knowledge and experience to help you navigate multiple applications and approvals, ensuring we don’t step on any toes as we present you with the potential costs and savings of multiple life insurance policies. Schedule a call today to get started.

Will all the policies pay out in full in the event of a death benefit?

Yes. You can claim on multiple policies and death benefits will be paid as per individual policy approvals and exclusions, if any. Life insurance policies do not coordinate or adjust benefits for other individual coverage that is in place.

Can you increase your life insurance coverage by buying several policies at once?

As mentioned above, yes – but within limits. Holding multiple policies is a common way for one to increase their life insurance coverage, but an insurance provider approves policies not only based on your health but also on the legitimacy of your coverage needs and your perceived ability to keep up with your monthly insurance premiums.

Overextending your finances to maintain several large life insurance policies does not make sense if the end result is you not having coverage at all.

Instead, calculate the right amount of coverage for your needs and contact a trusted broker to help tailor a life insurance coverage plan that works for your needs AND your budget.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

When should I get term life insurance?

Choosing a life insurance policy is a big decision. And like most important decisions, people tend to avoid considering when to buy life term insurance for as long as possible.

Whether it’s a fear of commitment driving that trepidation (just saying, the average age for newlyweds has been trending up for decades) or confusion about the value of life insurance, more and more people are putting off purchasing coverage. Our survey suggests 20% of those that have put off insurance decisions did so because they didn’t understand it.

But is that a risky move? Can you wait too long to buy life insurance? Or is it possible to get coverage too early?

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is term life insurance?

Term life insurance is a type of insurance policy that covers you for a specified length of time, called a term, and pays a death benefit to your beneficiaries if you die, within the term. There are different term lengths (such as 10, 20, 25,30 years or up to age 65) available.

When you buy term life insurance, you choose your coverage amount (the death benefit) and coverage term. Your insurance company determines your premiums based on your coverage amount and coverage term; those premiums stay level through the coverage term.

When is the best time to buy term life insurance?

Conventional wisdom in the insurance industry says that you should get life insurance coverage as early as possible when you’re young and healthy.

Insurance companies offer cheaper quotes to younger people because they carry less risk to insure due to the fact they are less likely to die.

On top of that, most term life insurance policies offer level premiums which means you’ll pay the same amount every month (or another agreed-upon frequency) for the length of your term – even as you age.

This ‘double whammy’ (not an official insurance term) means you can lock into a really low rate for a really long time (potentially 30 plus years). Needless to say, that’s a tempting offer. If your internet provider offered to lock you in at ‘new-customer-pricing’ for the next quarter-century, you’d leap at the opportunity.

Securing a life insurance policy in your early 20s is also recommended because of another common term life insurance feature called guaranteed renewability. This protects you from declined coverage when your term is up for renewal because of any health conditions you may have developed since you first purchased your policy.

For example, let’s say you don’t buy life insurance and you end up with high cholesterol and diabetes at 40 and decide you now want coverage. There’s a chance you’ll get declined by some insurers who will consider you too high a risk. However, if you already purchased a 20-year term policy (with guaranteed renewability) at 20 and developed those same ailments, you’ll be guaranteed the opportunity to renew your coverage This is a great way to hedge your bets against unforeseen circumstances.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Do I really need term life insurance?

When determining your term life insurance needs, there is a lot to consider.

Everyone knows the old saying, “you don’t know what you’ve got ‘til it’s gone,” (thanks Joni – or if you were born in the ’90s, thanks Counting Crows). An equally apt – but way less catchy – expression holds just as true “you don’t think you need things until you really need them.”

If you’re trying to figure out the best time to buy life insurance, ask yourself the following questions:

If you answered yes to any of those questions, take a minute to stop hyperventilating. Ok, you’re good? Now start looking into buying a term life insurance policy.

Term life insurance might seem like an unnecessary expenditure when you’re young and entering the workforce but once that’s no longer the case, the need for it becomes apparent. Life insurance is designed to protect those who are financially dependent on you should you die. Whether that’s your newborn baby, your business partner, or your spouse, they’re the ones hindered by this sudden loss. That’s a big risk to take for those who count on you.

We’re not trying to scare you, but take a minute and think about what would happen if you died tomorrow, strictly from a financial perspective. Can your spouse handle your mortgage payments? Who would pay off your credit cards? Can your business partner keep your company afloat? This can help you figure out if now is the right time to buy a term life insurance policy.

What about others types of insurance?

It’s true, there are also other types of insurance which could better suit your needs like permanent life insurance (which covers you for your whole life and generally has a cash value) or universal life insurance (which is again similar, and has a more involved investment component). While permanent life insurance and other types of coverage can be used to cover big life events and expenses as we mentioned above, they are also commonly used for covering end-of-life expenses and tax planning. While they are useful types of coverage, permanent life insurance and related policies might not suit your current needs. Speaking with a licensed advisor like those at PolicyAdvisor can help you figure out what type of life insurance policy best suits your needs.

And, don’t forget to head to these posts to learn more about permanent life insurance, universal life insurance, and other types of life insurance.

How much term life insurance do I need?

If you feel like the people in your life would be in a tough spot without your income, then you’ll probably want to get insured sooner than later regardless of your age. Concerns about premium costs can come secondary to ensuring you’re covered for an appropriate amount to match your financial situation.

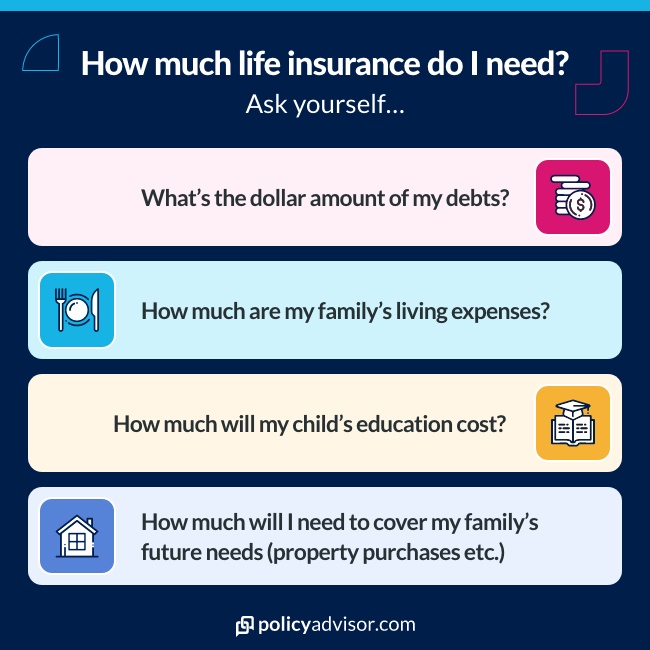
To figure out how much life insurance you need, consider any debts you have, how long your loved ones may be financially dependent on your income, what your partner would need to continue their quality of life, and any other obligations you may have, like dependent parents or education costs.

Still not sure how much term life insurance coverage is appropriate? Use our quick and easy life insurance coverage calculator for an honest assessment or read our honest guide to life insurance for answers to many questions that first-time life insurance buyers have.

Timing is everything when buying life insurance

Choosing the right time to purchase life insurance can be frustrating. No one wants to pay for coverage they don’t need, but peace of mind can outweigh the value of a dollar depending on your risk-aversion. Either argument is financially prudent, so it’s natural to feel conflicted.

Ultimately the decision is personal but should be influenced by those who depend on you.

  • Term life insurance is not a personal savings plan nor a roulette bet, it’s an investment in the financial security of the people in your life.

If needing that security is a possibility – whether you’re 22 or 42 – now’s a good time to take cover. You can start by exploring policies offered by some of the largest Canadian insurance companies right here on our website.

Or, contact us below. Our friendly advisors are happy to help you find the lowest rates for the best coverage!

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much does life insurance cost for a 40-year-old?

Wondering about the cost of life insurance in your 40s? Like most Canadians your age, changes in lifestyle might have you thinking about what your family’s financial future will look like. If you are in your 40s and contemplating life insurance, or looking to update your existing policies, there is no time like the present.

The younger you buy, the cheaper it is—so there’s no better time than now!

Read on to find out the monthly cost for life insurance in your 40s, and why you should either buy your first policy or upgrade your existing policy to match your lifestyle.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

life insurance cost in 40s canada

What is the average cost  for life insurance costs for a 40-year-old

Term life insurance costs about $50 per month for $500,000 in coverage for the average male, non-smoking, 40-year-old.

As we’ve explained before, insurance premiums depend on various risk factors such as your age, gender, smoking status, lifestyle, and overall health. These factors are taken into account to determine your life expectancy and the chances the life insurance company will have to pay out your death benefit. If you partake in high-risk activities, your life expectancy statistically decreases and the cost of life insurance is adjusted accordingly. For example, smoking more than doubles (and almost triples) your life insurance rates in your early forties, and keeps that trend going by age 49.

That being said, we’ve crunched the numbers from over different Canadian life insurance companies to give you the average cost of life insurance in your 40s. See the charts below that have term life insurance quotes by age for a 20-year term life insurance policy, divided by gender and smoking status.

Life Insurance Premiums – Male, 20-Year Term

Age $250K $500K $1MM
40 $29 $48 $88
41 $32 $53 $98
42 $34 $59 $109
43 $38 $64 $119
44 $41 $69 $130
45 $45 $75 $141
46 $50 $84 $159
47 $55 $93 $176
48 $60 $102 $195
49 $66 $112 $213

*Representative values, based on regular health

The story is similar for women, initial rates are lower than men’s at this age, and smoking continues to have a meaningful impact on premiums. See the chart below that has quotes for 40-year-old women, both smoking and non-smoking, for 20-year term life policies.

Life Insurance Premiums – Female, 20-Year Term

Age $250K $500K $1MM
40 $22 $36 $65
41 $24 $39 $72
42 $26 $42 $78
43 $28 $46 $86
44 $30 $50 $93
45 $32 $54 $100
46 $36 $59 $113
47 $39 $65 $123
48 $43 $72 $135
49 $47 $79 $149

*Representative values, based on regular health

These average life insurance rates will still vary depending on personal factors like your health and medical exam results, smoking status, location, and more. You may also feel you need a higher death benefit or a longer year term depending on your financial situation, life insurance coverage needs, and all the other life stuff that accompanies your forties.

Looking for a more exact monthly rate? Get a quote in seconds from some of the best life insurance companies in Canada. Get the lowest rates on the market by shopping over 30 insurance providers in seconds! Fill out the quote form below!

Yes, you should get life insurance in your 40s. Buying life insurance in your 40s means financial protection for your family at low rates because your health history is good. You are still relatively young in middle age and can secure a good monthly premium.

There are some clear signs of whether you need life insurance in your forties:

  • You and your partner plan on spending the rest of your life together
  • You have children of any age
  • You have a mortgage, or plan on buying or upgrading your home soon
  • You have other forms of debt such as credit card debt or a line of credit
  • You are the main earner for your family, with dependents like your children, partner, or parents relying on your annual income
  • You are continuing to accumulate assets that will someday be transferred to your beneficiaries
  • You want to make sure your family can cover your final expenses, like funeral costs

You may have coverage through a group plan at your work, but at this age career changes and promotions are more and more likely – you could find yourself with a gap in coverage or no coverage at all depending on that next role. Additionally, with a work policy, the type of coverage and policy options are limited. Find out why you shouldn’t just rely on your group life insurance plan.

Not to mention, as you age, health conditions start to creep up, and having a pre-existing condition while you’re applying for coverage can make your monthly cost increase.

You may already have life insurance you purchased when you were younger, but the plan, benefits, and options may no longe work with your current lifestyle. As you take the escalator up in your career and glide towards your peak earning potential, your growing nest egg will need more protection. Be it marriage, children, mortgages, or pets, your financial and protection needs can change drastically in 5 to 10 years. Your forties may, therefore, be a good time to revisit your existing coverage.

How much life insurance does a 40-year old need?

A Canadian in their forties, with a mortgage, children, and a partner who earns an income would need at least $500,000 in coverage. That amount would cover their house payments and child-care expenses, cost of living, and children’s education costs in the next 20 years. However, this isn’t one-size-fits-all.

To check your coverage needs, try out our easy-to-use life insurance calculator.

Find out how much coverages you need in your 40s!

What is the best life insurance for someone over 40?

At 40-years-old, term life insurance policies are likely your best option. However, the type of policy you choose ultimately depends on your personal circumstances and financial goals. At this relatively young age, you have your options wide open.

1 Term life insurance

Term life insurance provides attractive pricing, consistent premiums, and adaptability to accommodate your changing requirements. Term insurance plans stand out as straightforward life insurance products, with a fixed term life insurance rate for assured coverage over a designated period of time. If you’re in excellent health and lead a healthy lifestyle, this would be a great policy option for you! Many term policies offer the flexibility to convert coverage into permanent life insurance in the future, catering to extended coverage needs as your life circumstances evolve.

2 Whole life insurance

Those looking to get a little more out of their life insurance might consider whole life insurance. This type of permanent policy will cover you for your entire life at a fixed rate. Additionally they come with a cash value growth component that you can loan or borrow against. If you’re investment-savvy, you may also consider universal life insurance.

The average life insurance rate for whole life insurance is higher because of these perks beyond the standard death benefit. That being said, at 40, you have plenty of time for the cash value to grow to make a permanent life insurance policy worth your while.

3 No medical life insurance

Those with pre-existing conditions, complicated medical history, health issues, or a family history of health conditions may want to look into no medical life insurance policies if you’re not having luck with standard life insurance. The monthly costs for these policies are higher and the coverage amounts are lower, but isn’t a medical exam and very few health questions involved.

To find out which life policy is best for you when you’re in your 40s, check out our article that breaks down all the different types of life insurance available in Canada.

How do I buy life insurance in my 40s?

You now have an idea of what term life insurance might cost during mid-life – but everyone’s situation is different. The cost of life insurance is as unique as you! If you have 5 minutes, you can get customized term life insurance quotes in minutes through PolicyAdvisor’s online tool.

Still not quite sure how much coverage you need? We’re always here to chat! Book a call with one of our licensed insurance agents to make sure you 40 is your year to make great financial decisions!

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is Annual Renewable Term life insurance (ART)?

In most of our articles, when we mention term life insurance, we are referring to level term life insurance. What this means is the premium rate is locked in for the length of your coverage term. For example, let’s say you applied and were approved for a 20-year term life insurance policy, with a monthly premium of $30. That $30 is what you pay every month for 20 years (or 240 months). 

Some applicants shop and compare for quotes to ensure they can lock in the lowest monthly premium for the longest term possible given their age, health, and smoking status. This ensures a stable fixed cost and the peace-of-mind knowing they are covered for their desired length of time: Typically, 10, 20, 30 years or to age 65 or 100, depending on their provider.

However, there is another term insurance which is not mentioned quite as much, that works a little differently and offers insurance seekers added flexibility and options with their coverage. Annual renewable term life insurance, while not the most popular or well-known product, has some features that set it apart from level term insurance and make it a useful option for specific financial situations.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is Annual Renewable Term life insurance?

Annual Renewable Term (ART) life insurance is a short term life insurance policy which locks in your premiums for one year and can be optionally renewed at the end of each year. 

The insurance company guarantees to renew the policy yearly for a set number of years. 

The premium rate is guaranteed but not level: it increases every year. While, yes, the price increases, you are still guaranteed your insurability every year you renew your term. The premium rates start low at the beginning of the policy but increases every year as the age increases, given the rise in mortality risk of the insured person.

Annual renewable term life insurance caters to individuals seeking temporary life insurance coverage at a low cost.

Learn more about renewing life insurance.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

How does Annual Renewable Term life insurance work?

Just like any other form of life insurance, the annual renewable term life insurance offers financial protection to your dependents, in the event of your passing away, during the term of the policy.

To obtain ART, you have to first establish your insurability with a medical questionnaire or further medical underwriting through a medical exam and/or blood work.

Once your insurability is established, you choose your death benefit amount and find out what your monthly (or yearly if you choose) premium is. You now have life insurance for the year, and can renew each year until you feel you no longer need the coverage or want to look into other options such as term, whole, or universal life insurance.

The first year’s premiums are typically much lower than what one would pay in a longer term life insurance policy, but keep in mind they do increase every year. While the increase may appear minimal in the early years of the coverage, they will change substantially once you hit higher ages.

Also keep in mind that in most cases annual renewable term life insurance is not a long-term solution (more on this below). If you continue to renew your coverage beyond the initial first few years, you may quickly approach the point where a 10 or 20 year term life insurance policy would have a lower premium than what you currently pay. Unfortunately, you’ll have no time machine to go back and choose the least-expensive option at this point.

How much does Annual Renewable Term life insurance cost?

Below are the annual premiums a healthy, non-smoker at age 40 would qualify for with both ART coverage and 10-year term life insurance for $100,000. In this case, the applicant would save hundreds of dollars over the 10 year period by locking in a rate for pure term life insurance; there are no cost savings here through ART coverage.

Premiums for $100,000 Coverage, Non-Smoker, Good Health, 10-Year Term, Age 40-49

Age ART Term Life Insurance
40 $129 $121
41 $129 $121
42 $129 $121
43 $143 $121
44 $163 $121
45 $177 $121
46 $194 $121
47 $213 $121
48 $233 $121
49 $257 $121
Total $1,766 $1,210

This example for the same circumstances at age 50 are a little different. While there is slight savings in the early years with ART, the annual renewable premiums are substantially higher in the later years. After 10 years, one who chose term life insurance would save about $800 (male: $833, female: $793).

Premiums for $100,000 Coverage, Non-Smoker, Good Health, 10-Year Term, Age 50-59
Age ART Term Life Insurance
50 $205 $226
51 $205 $226
52 $205 $226
53 $230 $226
54 $268 $226
55 $299 $226
56 $339 $226
57 $386 $226
58 $442 $226
59 $511 $226
Total $3,090 $2,257

The savings are even more pronounced in one’s sixties. Below are the premiums for the same $100,000 policy for a 60-year-old non-smoker. A male applicant could save over $3,300, and a female applicant would save over $2,500, at the end of the term as opposed to continually renewing their Annual Renewable Term coverage.

Premiums for $100,000 Coverage, Non-Smoker, Good Health, 10-Year Term, Age 60-69
Age ART Term Life Insurance
60 $497 $550
61 $497 $550
62 $497 $550
63 $594 $550
64 $739 $550
65 $863 $550
66 $1,008 $550
67 $1,179 $550
68 $1,382 $550
69 $1,622 $550
Total $8,878 $5,497

Why would someone choose Annual Renewable Term life insurance?

There are several situations where an annual renewable term life insurance policy makes sense. 

Short term debt obligations: Those carrying a temporary debt can find annual renewable term policies useful. If you are carrying a mortgage debt or car loan, but know you will be selling that asset to pay off the debt in the near future, an annual renewable policy can be a cost effective way to protect yourself in this period.

For those that rely solely on workplace benefits for their life insurance coverage needs, ART policies can offer a temporary solution when one is between jobs or find themselves temporarily unemployed.

Another ideal use case for ART coverage is for those who need insurance immediately, but intend to improve their health to the point where it would lower their premium for another form of insurance.

Some other uses for ART coverage include:

  • Business owners looking to cover a short-term loan
  • New parents making sure they are covered while they weigh all of their insurance options.
  • Smokers who can take the time afforded to them through ART coverage to quit smoking permanently and dramatically lower their future insurance premiums.
Check out PolicyAdvisor's life insurance calculator.

What are the similarities between ART and term life insurance?

As mentioned, there are several ways an annual renewable term life insurance policy is similar to level term life insurance:

  • Regardless of length, both types of policy are renewable at the end of the term
  • Similarly, premiums are guaranteed for the term
  • Both offer temporary life insurance protection
  • Pricing for both reflects cost of pure life insurance
  • There is no access to any cash value or investment accounts

What are the differences between ART and term life insurance?

Despite both being temporary forms of life insurance, annual renewable term life insurance does have some key differences with traditional term life insurance.

Term Life Insurance Annual Renewable Term
Renewed after initial term, generally of 10, 20, 30 years Renewed annually
Premiums are fixed for the term Premiums increase every year
Covers wide range of uses Covers short-term and temporary use-cases

How do you buy annual renewable term life insurance?

Not all Canadian life insurance providers offer ART policies. Companies like Empire Life have options for annual renewable term life insurance with the additional option to convert that coverage to a 20-year term life insurance policy, should you decide that is the right option for you down the road.

Regardless of whether you choose a term life policy or think an annual renewable term is what your coverage needs call for, our licensed brokers have decades of experience helping Canadian insurance seekers find the right coverage at the right price for their unique coverage needs. 

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Who needs no-medical life insurance?

There are many factors one must consider when contemplating who should get no-medical life insurance. Time commitment, health issues, iatrophobia (the fear of doctors) – the list goes on. Before you start your search for no-medical life insurance, find out if it’s the right fit for your needs at this time.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Definition of no-medical life insurance

No-medical life insurance is just that. Life insurance issued to an applicant without the need for medical underwriting; a process that typically entails a medical exam by a paramedical service employed by the insurance company you’ve chosen to work with. The medical exam typically includes a blood test, a urine test, and a check of your vitals (blood pressure, and height and weight) in addition to a medical questionnaire. On the other hand, no-medical exam policies exclude the body fluid sample collection and rely solely on the questionnaire.

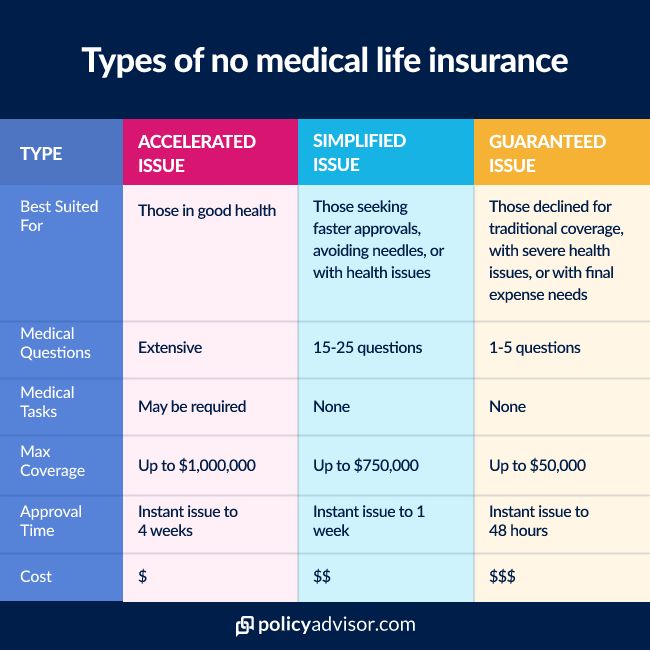
Digging deeper, no-medical life insurance comes in three different varieties: accelerated issue, simplified issue, and guaranteed issue. Each policy type requires a different level of scrutiny into your health and medical history, and their premiums reflect this. Typically, accelerated issue life insurance will have the lowest premiums due to its more in-depth, dynamic medical questionnaire, while guaranteed issue life insurance has the highest premiums as it asks for virtually no-medical history from its applicants.

There are different types of no-medical life insurance.

How do I know if I should get no-medical life insurance?

Whether for one of the reasons stated above, or another concern you have when it comes to medical underwriting, you have many factors to consider whether you want to go forward with no-medical life insurance. As we mentioned, no-medical life insurance policies are priced differently than those that are medically underwritten. And by different, we mean more expensive.

Thus, keep that in mind when contemplating the following scenarios. You can save a substantial amount of money by going through medical underwriting for term life insurance if you have that option. Before proceeding with any life insurance policy, speak with your broker. Licensed experts – like ours at PolicyAdvisor – are specially trained to help you navigate insurance questions like these. We have years of experience helping Canadians pick the right life insurance for their needs and their budgets, all while saving them time completing their applications digitally.

who needs no medical life insurance

Should I get no-medical life insurance if I have underlying health conditions?

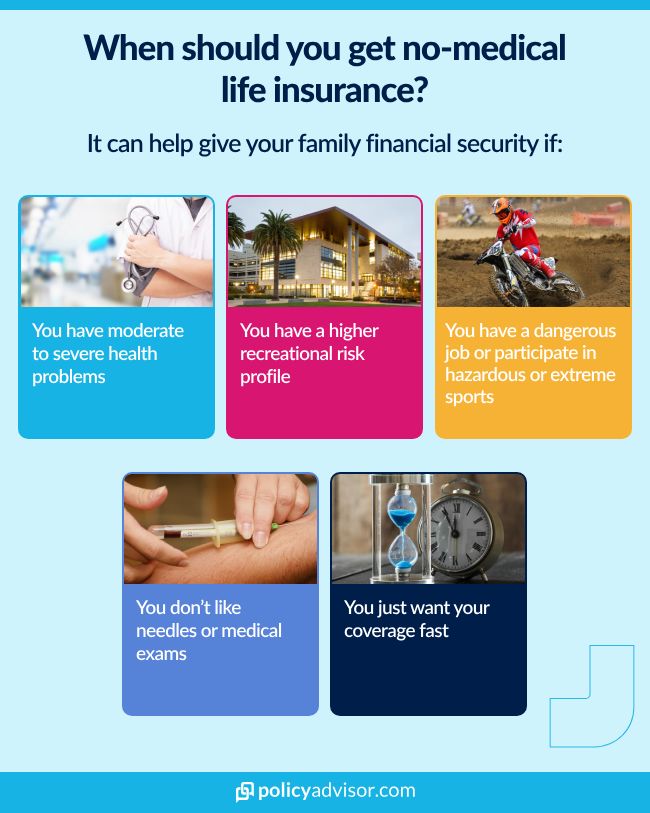
no-medical life insurance is certainly an option for those with health concerns. If you’ve survived a recent critical illness (like cancer, heart disease, etc), or suffer from a chronic illness, your number of traditional insurance options may be slim Not only that, but coverage could be denied once you apply or prohibitively expensive once you are provided with the final price after a medical exam.

In some of these cases, your best option may be no-medical life insurance. However, speak with a licensed broker. They will have the best idea of whether no-medical life insurance or a traditional option is best for you. Keep in mind that CLHIA statistics show only a small number of life insurance applications are denied each year.

Read More: Can I Get Life Insurance With Pre-existing Health Conditions?

Should I get no-medical insurance if I have diabetes?

The above answer is also sound advice for diabetics applying for life insurance or contemplating no-medical life insurance. While, as a diabetic, you may have assumed you won’t qualify for traditionally underwritten life insurance, that’s simply not the case. 

Diabetics with demonstrably consistent, tight control of their blood sugar, and in general good health can qualify for the same insurance pricing as anyone else applying for underwritten life insurance.

However, perfect control is not a reality for many of the millions of Canadians living with diabetes. Even a hemoglobin A1C above 7 can result in an increased rating from an insurance company. If your diabetes control is at a point where it results in an incredibly high insurance rating or outright decline of an application, then you may consider no-medical life insurance.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Should I get no-medical life insurance if my previous application was denied?

Having your life insurance application denied is not ideal, but it does not mean you have no choice when it comes to protecting your income for your family or beneficiaries. An application denial is a scenario where you may instantly choose to navigate the different no-medical life insurance policies – like simplified and guaranteed issue – to ensure you get coverage. Before you do so, speak with your broker and find out why your insurance was denied. You may have the chance to reassess your application, reapply with a different insurance company, or have it insured with exclusions for the specific issue that triggered its denial. 

Either way, having an experienced broker by your side will help you find the right policy for you on your new search or modify your previous application so that it works for your situation.

do i need no-medical insurance

Should I get no-medical life insurance if I am healthy and want to save time?

The short answer: yes

The long answer? There are many ways to save time when comparing and buying life insurance. First and foremost, a digital life insurance broker can help you through the insurance buying process. They can provide you with quotes in minutes and guide you towards the best choices that can save you money; all in a fraction of the time a traditional mortgage broker would take to get you covered.

What’s even better is – thanks to their years of experience – our brokers can guide you to accelerated issue life insurance options that don’t require face-to-face medical exams, yet offer comparable pricing to other medically underwritten insurance policies. Companies like Assumption Life, Canada Protection Plan, Desjardins, Empire Life, Manulife, Industrial Alliance (iA), RBC and others offer a substantial amount of term life coverage to those in good health without the need for a medical exam. Depending on your age, some of these companies can offer coverage of as much as $5 million dollars to healthy applicants without requiring a medical exam.

While there is nothing better than instant – our licensed brokers can do the time-consuming leg-work involved in finding you the best policy while avoiding the higher premiums of some no-medical options. no-medical life insurance is not the sole choice if you want to save time AND money.

Should I get no-medical life insurance if I don’t like the doctor’s office?

You certainly can, but there are other options if you want to get life insurance without entering your doctor’s crowded waiting room. All insurance companies offer a paramedical appointment to collect your health information. A nurse can visit you at home or your place of work and collect bloodwork, blood pressure, and the other information required by underwriters. 

But, as alluded to previously, there are some providers that offer accelerated issue term life insurance policies. Depending on your health and how you answer the initial medical questionnaire, you may qualify for coverage without ever having to do a medical.

I’m not sure if I need no-medical life insurance. Who can I talk to?

We thought you’d never ask! PolicyAdvisor’s mission is to help Canadians save time and money as they seek out life insurance coverage. We work with 20 of Canada’s biggest and best insurance companies. Our experience with these providers grants us the ability to find the right, custom coverage for your needs. And that means saving you time and recommending no-medical insurance that fits your budget and needs when appropriate. Reach out and we’ll help you start comparing life insurance quotes online. In the mean time, check out our life insurance calculator so you have an idea of how much coverage you may need.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Frequently Asked Questions about non-medical life insurance (FAQ)

1. What is non-medical life insurance?

Non-medical life insurance or life insurance without a medical exam refers to the fastest-growing category of life insurance products in Canada. Non-medical life insurance policies do not require a medical exam, blood test, or an assessment of your vitals (blood pressure, height and weight etc). Without the requirement for such tests, life insurance coverage can be obtained much faster – sometimes even instantaneously. No wonder it’s so popular.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

2. What are the benefits of life insurance coverage without a medical exam?

Life insurance without a medical exam has historically been made available to those individuals that have moderate to severe health issues. These policies are usually more accommodating in their underwriting requirements and therefore cater to harder to insure individuals or those that have been declined health coverage. Increasingly, such coverage is also available through accelerated underwriting to healthy individuals that may want to set up coverage quickly and avoid the pain points of traditional underwriting (or just the major pain point associated with syringes!).

In effect, non-medical coverage offers several benefits such as:

  • Easier underwriting process
  • Faster to complete the process
  • More accommodating for those with prior health considerations or previously declined applications
  • Avoid dealing with blood work or needles
  • No face to face interaction necessary
Who needs no medical life insurance?

3. Is there a waiting period for non-medical life insurance claims? Does my coverage start right away?

The waiting period for a life insurance policy refers to the length of time (usually up to 2 years) when claims may not be paid by insurance companies. Most non-medical options allow for coverage to be available instantly after approval, without any waiting period.

There are some products in the market where the coverage may be deferred. Such products are typically offered to individuals with severe health considerations or those currently undergoing treatment.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

4. Which companies offer life insurance coverage without a medical exam?

Most Canadian life insurers offer a substantial amount of life insurance coverage without requiring a medical test. At PolicyAdvisor, we work with the best life insurance companies in Canada and have access to both their standard (medically underwritten) products and non-medical products.

Many of the biggest life insurance companies in Canada such as Manulife, Canada Life, Desjardins, Industrial Alliance, RBC Life Insurance, BMO Life Insurance and others are now able to offer significant life insurance coverage without requiring a blood test. In some cases, for healthy applicants, coverage as much as $5 million can be offered without medicals (also known as without fluids) using these companies’ accelerated underwriting processes.

There are also leading providers, such as Canada Protection Plan, Assumption Life, and Industrial Alliance (iA) that specialize in offering simplified life insurance products, that are available without a medical exam. This type of simplified coverage is best suited to individuals with moderate to severe health issues. In such cases coverage is limited to a maximum of $500,000.

5. Is non-medical insurance expensive?

If you are in good health, then life insurance coverage without a medical exam offers comparable premiums to coverage obtained after bloodwork and vitals are taken.

If however you have some prior health considerations, then the premiums may be higher to compensate for the elevated risk the insurance company is taking on.

6. Can I get joint coverage with my spouse without a medical?

Non-medical term insurance is generally issued on an individual basis. However if you and your spouse are in good health and qualify for accelerated underwriting, then you will be able to get joint coverage without medicals. Our advisors can easily assist you when reviewing your options for joint coverage.

7. Should I get non-medical insurance if I am healthy?

If you want your coverage approved and in place quickly then we recommend you take a non-medical policy if you are eligible. Without the time commitments of in-person blood work and tests there is no downside or price difference for non-medical coverage.

Some of the insurance providers we work with offer more favorable rates for customers who are in good health. For example, Canada Protection Plan has products such as Express Elite that are specifically designed for applicants in good health, who want quick coverage.

Check out PolicyAdvisor's life insurance calculator.

8. Are non-medical policies safe? Will my non-medical life insurance pay out a claim?

Yes! Of course, they are safe and will pay out a claim. The claims process for non-medical life insurance works exactly as it would for any other type of life insurance. The process for applying is easier and faster than regular medically underwritten issuance. However, there is no difference in the claims process between life insurance with a medical and without a medical.

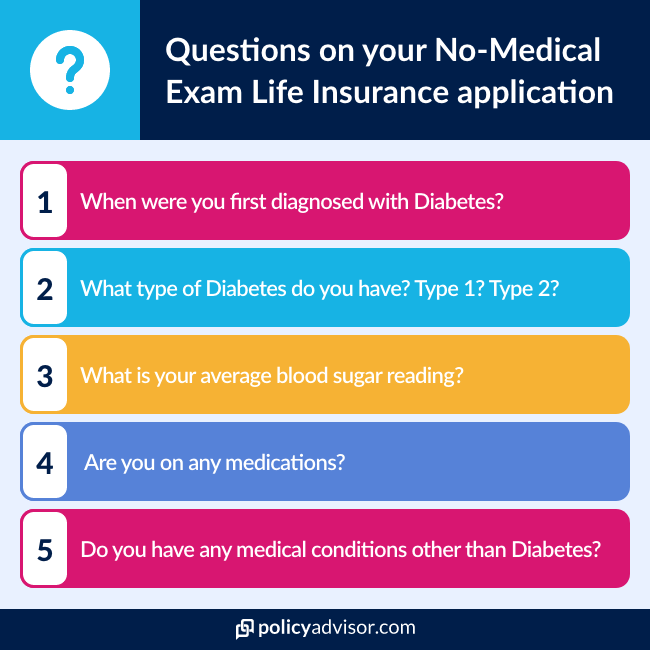
9. I have Diabetes. Can I qualify for insurance without medicals?

There are several options for life insurance coverage for diabetes. The availability of these options depends on the age of the applicant, how long they have had diabetes, the degree of control, and the presence of any related complications if any. Non-medical policies are usually more accommodative for those with prior health conditions, including diabetics. Get in touch with us and we will be able to go over the details of your diabetes history and ensure you get a plan that’s right for you.

10. Can I get life insurance without a medical if I have been treated for cancer?

There are several on-medical life insurance options for those that have successfully overcome cancer. The coverage options depend on your age, type of cancer, the number of years since your treatment was completed, and a few other factors. At PolicyAdvisor, our advisors are able to work with you to find a suitable non-medical insurance product, personalized for your needs.

Read more about life insurance after cancer

FAQ non medical life insurance

11. Can I get non medical life insurance if I have heart disease and have had angioplasty?

You may be able to qualify for certain types of non medical life insurance depending on the severity of the heart condition and the number of years since the heart treatment or angioplasty was completed. Generally speaking, if the time since your angioplasty was completed is more than 3 years, you should qualify for life insurance coverage.

Read more about getting life insurance with a heart condition

12.  Can I increase my coverage later?

Most insurance companies will require you to complete a new application. This will include a new questionnaire. If there is no change in your health or lifestyle situation, then you can always apply for additional coverage, under a new policy.

No Medical Insurance Quotes - instantly.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

13. Can I get insurance without a medical if I am on a work permit?

Yes, you can! Some insurers provide life insurance coverage for individuals on a temporary work permit or a student visa, albeit for lower coverage amounts. You do not have to be a Canadian citizen or permanent resident to apply for coverage without a medical exam.

14. Can I get non-medical insurance if I’m recovering from a chronic illness?

If you have a chronic illness or are recovering from one, there may be options available for your life insurance needs. Guaranteed life insurance is available for those currently receiving medical treatment, although these products usually have a waiting or deferral period. For example, if you have recently been diagnosed with a mental health disorder such as anxiety, depression, or bipolar, your insurance provider may require a two-year deferral period. 

Our experienced life insurance advisors are happy to assist you. Schedule a call and we will be ready to assist.

15. What is the application process for non-medical life insurance?

As Canada’s best life insurance advisor, we are making the life insurance purchase process radically simple and easy. Our in-house advisors will help you complete a digital application form that will be electronically submitted to the insurance company. The form will ask a few medical and non-medical questions. Once the application is submitted, it takes 1 to 2 weeks for approval, although in some cases coverage can be approved instantly. Once the policy is approved, you may also have the option to receive the policy electronically.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Single versus joint life insurance: which to choose?

When couples start researching and planning their life insurance choices, a common question that arises is whether to opt for Single versus Joint life insurance. Once a couple determines they plan on spending a significant amount of time together – if not the rest of their lives – they typically share some financial responsibilities. 

Term life insurance is a great choice for couples to ensure all their temporary financial obligations are met in such dire circumstances, but there are choices when it comes to joint coverage. 

Let’s look at what these are, their positives and negatives and finally, which one is better.

What is Single Life Insurance?

Single life insurance is simply life insurance that covers only one individual. A single life insurance policy pays out the chosen lump sum benefit if the insured individual passes away during the ‘term’ or length of the policy. It is not tied in any way to a person’s marital status. When you read about life insurance, it refers to individual or single life insurance, unless otherwise specified.

In the context of a couple seeking life insurance:

  • Both the partners can apply for and obtain their own single or individual life insurance
  • The individual coverages can be customized to their respective needs. In other words, the partners can have their respective coverage amounts, coverage lengths, and even have respective beneficiaries for their policies, if they may so desire.
  • If one of them passes away, the beneficiary will receive the proceeds of life insurance. The surviving spouse will continue to have coverage.
Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is Joint Life Insurance?

A joint life insurance policy covers two or more lives. It is usually purchased by couples who want to cover themselves jointly under one policy.

It may also be purchased in a business context. By insuring the lives of two or more business partners, the death benefit can be used to settle any business liabilities upon the passing away of a key stakeholder. While it sounds simple, the exact way joint life insurance works depends on the type of insurance you choose: Joint first-to-die or Joint last-to-die.

What are the different types of Joint Life Insurance?

There are two types; joint first-to-die and joint last-to-die.

Joint first-to-die life insurance

Joint first-to-die is a type of life insurance where the full insurance coverage amount is payable upon the death of the first of the two or more individuals insured under the policy. 

In the case of a joint first-to-die policy covering couples; when either one of the insured individuals passes away, the beneficiary, who in most cases is the surviving partner, receives the death benefit. 

Similar to traditional term life insurance, the surviving partner can use the amount for whatever pressing financial needs they may have – be it mortgage protection, paying off other debts, or providing for the family by replacing lost income. Upon the payment of the claim, the policy generally expires and the surviving partner may no longer have insurance coverage, unless requested.

A joint first-to-die policy is best suited for those with a significant financial obligation that would fall on the surviving partner such as an outstanding mortgage balance or in cases where the surviving spouse depends substantially on the income of their spouse for their ongoing living needs. In such cases, the surviving spouse can use the death benefit to clear off the immediate financial liability or to take care of living expenses.

Joint first-to-die policies can also offer some unique benefits:

Insurability privilege: Within a limited period following the death of the first insured, the surviving insured can request continued life insurance coverage from the insurance company without undergoing new medical underwriting. However, such coverage is more expensive as it is offered as permanent life insurance and the premium is recalculated based on the current age of the surviving insured. Most companies will specify a maximum age for coverage eligibility of the second insured. 

Double payout on simultaneous deaths: Many companies offer a double benefit option on joint first-to-die policies, whereby an additional coverage amount will become payable to the beneficiary if both the insured die together or within a short time (45 or 90 days) of each other. 

Joint last-to-die

Joint last-to-die life insurance pays out once both insured individuals pass away. The deaths can happen simultaneously or years apart, but no payment is made until both the insured have died.

Let’s assume a couple takes out a 20-year joint last-to-die policy. There is no payout if only one insured individual passes away in year 10. Instead, the surviving partner needs to continue paying premiums for the rest of the term. Once the surviving partner also passes away, their chosen beneficiary receives the death benefit , provided it is within the policy term length.

A joint last-to-die policy is better suited for when there are no significant financial obligations on the surviving spouse. Instead,  the coverage is used to provide for final expenses or leave a legacy for children or other dependents, after both partners have passed away. Most couples that choose joint last-to-die policies name their children as beneficiaries to help ensure their future financial well-being.

Read more about how different types of life insurance work in Canada.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Positives of Joint Life Insurance

A joint life insurance pays out a claim regardless of which of the insured passes away.

Taking on one joint policy is generally less expensive than taking out two individual life insurance policies; this is great if you’re trying to tighten your household budget. However, keep this in mind: if an individual or both parties applying for joint coverage are young and in good health, then they could get two individual life insurance policies while only paying just a little bit more. 

Negatives of Joint Life Insurance

Joint life coverage allows only limited personalization. The amount and length of coverage has to be the same for each of the insured. 

Furthermore, a joint life insurance policy only pays out once. While obtaining two individual policies instead increases the cost, it means double the coverage as two independent policies each pay out on their own. 

Again let’s use our example of a 20-year term life insurance policy. With individual policies, if one member of the couple passes away in year 10, their policy pays out but the remaining partner’s policy is still active.

While we all hope our relationships last forever – that unfortunately isn’t always the case. If one finds themselves in a situation where they are no longer in a relationship with the partner with which they applied for a joint life insurance policy, it may prove difficult to split the joint policy into two individual ones with the same coverage. Instead, one may have to apply for life insurance again, and risk not qualifying at the same rating as before.  

Joint first-to-die coverage has another similar problem – if the surviving partner needs to find new coverage once the initial policy has paid out, it will be difficult or more expensive for them to find it later in life.

Read more about what affects the cost of life insurance here.

What to choose between a single versus joint life insurance policy

Which is better: Single or Joint First-to-Die Life Insurance for couples?

Policy Joint First-to-Die Life Policy Individual Term Life Policy
Number of contracts One common policy contract covers both the insured Two separate policies are issued to cover each of the insured
Coverage amount Same coverage amount for each of the insured Coverage amounts can be different and personalized for each of the insured
Coverage term Same coverage term for each of the insured Coverage terms can be set separately
Premium cost Premium is cheaper by approx. 7-10%, for the same coverage amount and term Premium is higher vs. joint policy by 7-10%
Post-claim Policy expires, once a claim is paid. Surviving spouse continues to be insured, even if a claim is paid
Survivor coverage Surviving spouse can request for:-new coverage with medical underwriting -continued coverage without medical underwriting through conversion into a permanent life coverage, albeit at higher premiums Coverage continues for surviving spouse, even if one claim is paid
Coverage after divorce Can request for individual coverage after divorce or dissolution albeit at higher prices Individual coverages can continue without any change

Why would you want joint life insurance?

Joint life insurance can be better suited for couples if:

  • They want to align their premium costs to a limited budget
  • They have one discrete need (such as a mortgage debt) and there would be no residual need for covering the surviving partner once a claim is paid.

Why would you want individual life insurance?

Individual life insurance can be better suited for a couple if:

  • They have multiple needs such as providing protection for young children, or ongoing lifestyle expenses for the family. Individual insurance allows coverage to continue for surviving spouses, even if one of the spouses passes away and a claim is paid.
  • They want coverage that is customized for each of the spouses such as different amounts or terms of coverage.
  • They are able to pay the slightly higher premiums than joint coverage.

Can you get joint life insurance if you are not married?

Yes you can. As long as you have reasonable interest (also referred to as insurable interest) in the longer life of the other insured, you are able to get joint life insurance coverage. This insurable interest may be due to a personal relationship (in the case of spouses or common law partners) or due to common business interests like we mentioned above. Common-law couples are therefore eligible to apply for joint life insurance. 

What happens to a joint life insurance policy after divorce?

A divorce can get further complicated with a joint life policy. A couple can certainly choose to retain the original joint life insurance coverage, post the divorce, if they so intend to. But if they want their coverage to also go separate ways, then they have no other option but to cancel the joint policy.

Most joint policies will offer a limited period insurability privilege whereby upon divorce or dissolution of the union, any of the insured under the original joint policy can request for individual life insurance benefit, without undergoing new medical underwriting. Such coverage cannot exceed their pro rata share of the previous joint benefit. The premium is however always more expensive since it is based on the age of the insured at the time of the request. 

There is much more flexibility with individual coverage in the event of a divorce. Two respective individual coverages can continue to be independently retained. Although on most occasions, the individual owners may want to change beneficiaries if they had named each other as the beneficiary prior to the divorce.

Read more about life insurance and divorce.

Ultimately, while joint life insurance is slightly less expensive than taking out two individual single policies, it is not as flexible as individual term life insurance.

If you’re able, we would urge you to look at an individual or single life insurance policy for yourself and your partner when contemplating the best life insurance company for your needs.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much life insurance do I need?

So, you have decided that you need to buy a life insurance policy. Now you’re wondering, how much life insurance do I actually need? To find this out, you’ll need to take a deeper look into your finances and expenses.

Everybody would love to leave a fortune for their family when they die. So they wonder “What’s the right amount of life insurance?”

After all, when you’re gone, there’s going to be a giant you-sized hole in their lives. They will have lost a parent, a spouse, a sibling, or a child… bummer is an understatement.

You might think of going with a multimillion-dollar term life insurance policy. With millions, at least your family will never have to worry about money for the rest of their lives. Choosing a life insurance coverage amount should be a no-brainer right? The higher, the better!

Well… frankly, it’s not that realistic for most people to own such a large life insurance policy. The higher your death benefit payout, the more expensive your premiums become. If you can’t afford to pay for your policy and you have to cancel it, your family will receive nothing.

On the flip side, you don’t want to pick too little coverage. In that case, your dependents will only receive enough to cover your funeral expenses. Our survey for Life Insurance Trends has shown that Canadians are underinsured.

It’s quite a conundrum. So, really, how much life insurance coverage should you get?

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

How do I determine how much life insurance I need?

The best way to figure out how much insurance you need is to use a life insurance calculator. These calculators perform an instant audit of your personal and financial situation. It looks at both your assets and liabilities. Then, it lets you know how much insurance you need to cover those liabilities.

But wait, hold on! Before you close your browser to go find a calculator, we have one right here! Our life insurance needs calculator can help determine your needs in a matter of minutes. We focus on a few key areas of your finances to keep things simple.

There are several factors you should think about when considering how much life insurance you may need.

How much life insurance do you need to cover your debt?

Do you owe anybody money? We’re not talking about your buddy for dinner last week, but rather big debts. We’re talking credit card debt, car loan debt, your mortgage, etc. If you die unexpectedly, someone is on the hook for paying back any debts you owe. This is one of the main motivating factors in getting life insurance. An appropriate coverage amount gives you peace of mind. Life insurance ensures your spouse, children, or even parents wouldn’t have to deal with your debt on top of grieving your death.

The primary source of debt for most Canadians is usually their mortgage. But it’s not uncommon to have balances owing on lines of credit, credit cards, and student loans.

Adding up these liabilities can be used as a starting point for figuring out your base coverage needs.

Blue bulb

Quick facts

The average Canadian carries about $8,500 in non-mortgage debt – don’t feel too bad if you’re still paying off a vacation…or two.

How much life insurance do I need to cover my family’s living expenses?

The next step in figuring out your coverage needs is by asking yourself three questions:

  1. How many dependents do I have?
  2. How much of my after-tax annual income do they rely on?
  3. How many years will they rely on my money?

A dependent is anyone who needs your financial support. If you’re the primary breadwinner in your house and/or have kids, then you already have dependants. You may also have elderly parents or disabled family members that depend on you financially. Their needs should all be considered when calculating the coverage amount. They will be the beneficiaries of the life insurance payout.

Now that you’ve decided who relies on you, ask yourself: how much will they need each year?

Does your partner earn an annual salary, even if you pay most of the bills and cost of living? How much rent or mortgage does your family pay? What about food, clothing, utilities, etc.? How much money would they need every year to maintain their standard of living? Add these expenses up for a yearly total.

calculating life insurance needs

What percentage of my after-tax annual income do I think they’d need?

The rule of thumb is 10-15x your annual salary. That’s just your base insurance needs, though. Other things to consider are the ages of your children and your partner. They may only need the annual figure for a temporary amount of time. If your children are teenagers, for instance, they may be self-sufficient in less than a decade. Or, if your children have disabilities or require other care into adulthood, you might factor in more years.

Still looking for the best life insurance rates?
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

How much coverage do I need to provide for the future?

Life insurance isn’t just about covering your debts, mortgage payments, or your family’s living expenses after your untimely death. Your life insurance payout can also pay for:

  • Child care so your spouse has support while they grieve
  • Health insurance, dental insurance, or any other insurance they may lose 
  • A down payment on a house or condo for your spouse or children
  • Wedding costs for your children
  • Donations to charities

Other than these costs, it’s wise to include around $10,000 in additional coverage for final expenses such as funeral costs.

How much life insurance do I need to protect my savings?

Do you have any savings? Whether it’s in your bank account, an investment portfolio, an RRSP you opened at 19, or wads of cash stuffed under your mattress, any assets you’ve stored away can help reduce your life insurance coverage needs.

While some people reduce their life insurance coverage because they have savings, others may buy life insurance to protect it. That way, their dependents won’t need to dip into savings that have been allocated for long-term growth (like investments) or sell assets (such as a home, car, etc.).

If you have existing life insurance plans you should also factor them in.

What is your Whole Life Insurance worth?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Discussing life insurance coverage with your dependents

No one enjoys planning for death. But crunching the numbers gives you cold, hard, facts about your family’s financial needs. But don’t forget to discuss your financial protection plan with your loved ones. Talk about what they think they’d need if you were to die.

For example, say your partner has their own income and you both do not have children. In this case, a $1,000,000 term life insurance policy, might not be necessary. Your partner may be comfortable living off their own current income. However, if you have a large family with young children who will need child care and their cost of living met for over a decade, plus college costs and inheritance, and a mortgage balance on top of that, perhaps $1,000,000 isn’t out of the question.

Other methods to determine your life insurance needs

DIME Method

The DIME method is often used by brokers and financial advisors to determine your life insurance needs on the fly. It stands for four major aspects that you should consider in your financial strategy: Debt, Income, Mortgage, and Education. However, this common rule is an oversimplified calculation. It doesn’t consider:

  • your savings
  • your existing life insurance policies
  • paying for funeral expenses
  • paying for any other future expenses your family may have

Multiply your money

Looking to simplify even more? This popular rule of thumb is used by Many life insurance companies. You simply multiply your annual income by 10 – 15x to determine the right amount of coverage.

These methods work in a pinch, but only using a life insurance calculator will give you an accurate answer to how much life coverage you actually need.

expanding on the DIME method for life insurance needs

Frequently Asked Questions

How much coverage do I need to plan for my children’s education?

If your child chooses to go to post-secondary, you should account for their tuition fees. Just one year of tuition, books, lodging etc. can cost around $20,000 on average. It’s a major expense that they might not be able to afford if your children were to lose your salary.

What kind of life insurance do I need?

One last consideration in deciding how much coverage you need is picking the type of life insurance. There are two types of life insurance: term and permanent

1 Term life insurance

Covers large amounts of outstanding debts that are temporary. It can also cover your salary while your dependents are still counting on you as a main breadwinner.

2 Permanent life insurance

Covers you for your entire life. You may only need a small amount of that permanent coverage to handle final expenses or estate taxes.

The final thing to consider is life insurance premiums—what’s the cost of life insurance? A life insurance payout can be invaluable to your family, but you have to be able to afford your premiums today. A term life policy is cheaper because it’s only for a temporary period of time. A permanent life insurance policy can be more costly because coverage continues until you die. You want to choose a policy that not only has the right coverage amount but that also has manageable premium payments for your living financial plan.

How much life insurance coverage should I buy?

The short answer: 10-15 times your annual salary. But, the best way to get the answer to that question is to use a life insurance calculator that performs an instant audit of your personal and financial situation.

After you’ve talked things over with your family and entered your financial information into our calculator, PolicyAdvisor can help! Our licensed agents will provide you with a life insurance quote that matches your individual circumstances and coverage needs. We work with dozens of life insurance companies to provide you with affordable life insurance rates. 

If you‘re still not sure how much life insurance you need, that’s perfectly ok. Feel free to experiment with different coverage levels in our online tools until you find the perfect match, read our company reviews, or check out our honest guide to life insurance.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */