Disability insurance in Canada: What it is and how it works

Disability insurance is an income replacement policy that pays you a tax-free monthly benefit if an illness or injury prevents you from working. In Canada, disability insurance is available through employer group plans, association plans, and individual policies you buy yourself. This guide explains exactly how disability insurance works in Canada.

What is disability insurance in Canada?

Disability insurance is an income‑replacement coverage that pays you a monthly benefit if an illness or injury prevents you from working and earning your usual income. It’s designed to help you continue paying your bills, debt payments, and everyday expenses when your paycheque stops but your costs do not.

In Canada, it acts as a financial safety net, typically replacing 60% to 80% of your regular income so you can continue paying your mortgage, bills, and living expenses while you recover. Unlike critical illness insurance, it pays an ongoing monthly benefit rather than a single lump sum on diagnosis. 
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Do I need disability insurance in Canada?

Statistically, 1 in 3 Canadians will experience a period of disability lasting longer than 90 days before they reach age 65. Your ability to earn an income is your most valuable asset. If you earn $80,000 a year and have 20 years left until retirement, your future earning potential is $1.6 million. You insure your $40,000 car and your $600,000 house without a second thought. Insuring yourself is important to maintain your current lifestyle for an extended period of time.
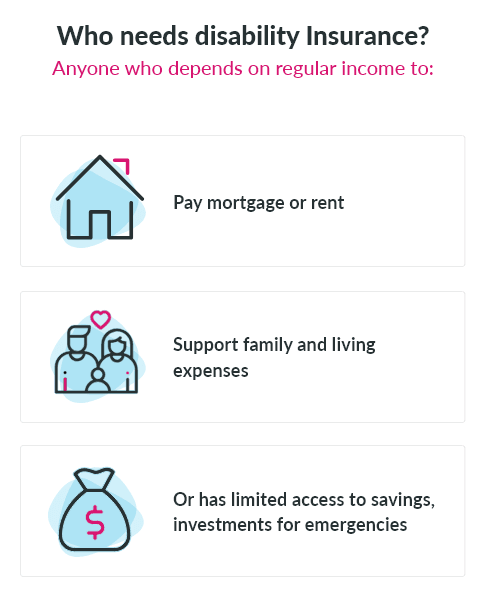
Who needs disability insurance

What conditions qualify for disability insurance in Canada?

Canadians are susceptible to injuries and conditions that prevent them from working. No wonder 12 million Canadians have disability insurance coverage. Common causes of claims include:

  • Mental Health Conditions: Major depression, severe anxiety, bipolar disorder, and post-traumatic stress disorder (PTSD).
  • Musculoskeletal Disorders: Chronic back pain, severe arthritis, and degenerative disc disease.
  • Neurological Disorders: Multiple sclerosis (MS), epilepsy, Parkinson’s disease, and stroke.
  • Systemic and Chronic Illnesses: Cancer, heart disease, diabetes complications, and autoimmune disorders like lupus.
  • Chronic Pain and Fatigue: Fibromyalgia and myalgic encephalomyelitis/chronic fatigue syndrome (ME/CFS).
  • Respiratory Disorders: Severe asthma and chronic obstructive pulmonary disease (COPD).

What are the different types of disability insurance?

In Canada, disability coverage is divided into two distinct categories:

1. Short-term disability insurance

Short-term disability insurance is usually offered to cover the loss of income from short-term or temporary health issues arising from a less-serious illness or accident.

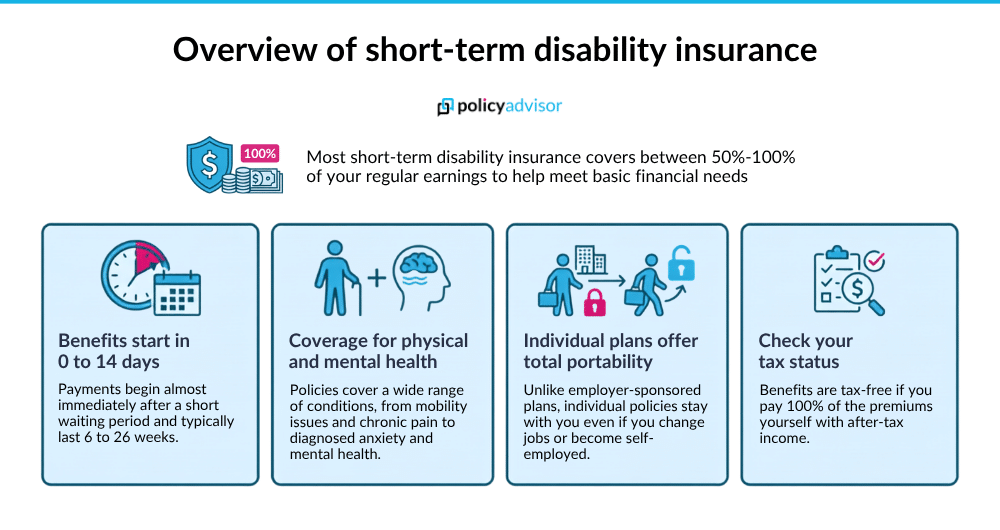
The benefit payments can begin as soon as you use up your sick leave, sometimes as early as 1-14 days after a claim is submitted, with coverage lasting typically between 6-26 weeks, although coverage can also go as long as 52 weeks. 

It’s commonly used for temporary health issues, like minor accidents, sports injuries and back problems that may prevent you from working for a few weeks or months. Short-term disability insurance are generally offered by your employer as they seek to attract and retain talent.

2. Long-term disability insurance

Long-term disability insurance is used to protect against loss of income from more persistent, ongoing health issues. 

Its coverage usually begins right after the short-term disability period is over and the coverage time can be for 2 or 5 years, although most long-term disability coverage lasts until the age of 65 (standard retirement age). 

It’s usually purchased by individuals to supplement their employer-provided disability insurance. It’s commonly used for mental health problems, musculoskeletal problems, accidents, and more.

How disability insurance works: Step by step guide

Here’s the simplest way to understand how disability insurance works: you buy coverage, pay premiums, and if in case you become disabled, you claim the benefits, and then eventually return to work or reach the end of your benefit period.

Step 1: You secure coverage through work or individually

Many Canadians usually get disability coverage through employer group benefit plans. These plans typically provide short‑term disability (STD), long‑term disability (LTD), or both, often with premiums partially or fully paid by the employer.

If you don’t have sufficient disability insurance through work or you’re self‑employed, you can buy individual disability insurance from a Canadian insurer. Individual policies let you customize coverage and keep it even if you change jobs or employers.

Step 2: You design your policy

When you apply for individual disability insurance, or when you enroll in certain group plans with optional choices, you’ll decide key policy features such as:

  • Monthly benefit amount: This is the maximum income the policy will pay you each month while you’re disabled.
  • Waiting period: This is the time you must be continuously disabled before benefits begin.
  • Benefit period: This is how long benefits can continue once approved; for example, 2 years, 5 years, or to age 65. 
  • Optional riders and features: Common riders include cost‑of‑living/inflation protection (COLA), residual or partial disability benefits, waiver of premium, etc.

Step 3: You pay premiums and keep coverage in force

Once you’re approved, the policy stays in force as long as you keep paying premiums. Many individual disability policies in Canada are either non‑cancellable (the insurer cannot change premiums or benefits before a stated age, often 65) or guaranteed renewable (the insurer must renew coverage as long as you pay premiums but can adjust rates by risk class in future).

Employer group plans typically continue while you’re an eligible employee and stop if you leave the employer or retire.

Step 4: If you become disabled and stop working

If an illness or injury prevents you from performing the duties of your job or, under some policies, any job suited to your education and experience, you may meet the eligibility criteria of disability insurance. The different definitions of disability significantly impact how and when benefits are paid out.

  • Own-Occupation: You will be eligible for benefits if a disability prevents or limits you from performing the duties of your pre-injury occupation. There are no restrictions: for instance, you can continue to receive benefit payments even if you’re able to work in another occupation.
  • Any-Occupation: Under this type of policy, you may be ineligible to receive benefits if you can work in any other job. You may not even be working, but if you are deemed to be able to work, you will not be eligible for benefits under a policy with this definition.

Step 5: You satisfy the waiting/elimination period

Most long‑term disability policies have an elimination period during which you must remain disabled before monthly benefits begin. Some plans coordinate this period with paid sick leave, employer STD benefits, or EI sickness benefits so that income continues during the wait time.

Step 6: You submit a disability insurance claim

To start a claim, you (or your employer for group plans) complete disability claim forms and submit medical and income documentation. Common documentation includes:

  • A claimant statement describing your job duties, symptoms, and how the condition prevents you from working.
  • An Attending Physician’s Statement (APS) or medical questionnaire completed by your treating physician or specialist, detailing diagnosis, treatment, restrictions, and expected duration.
  • Employment and income verification, such as pay statements, T4 slips, tax returns, or financial statements for self‑employed applicants.

Step 7: The insurer assesses your disability and eligibility

The insurer’s claim team reviews medical evidence, occupation details, and policy terms to decide whether you meet the definition of total or partial disability. They may request additional information, schedule independent medical examinations, or obtain further records before making a decision.

For many group LTD plans, the initial test focuses on whether you’re unable to perform the essential duties of your own occupation for the first 24 months of benefits, then shifts to whether you can perform any occupation for which you’re reasonably qualified afterward. Individual policies can use different definitions, including pure own‑occupation coverage that doesn’t change over time.

Step 8: Monthly disability benefits begin

Once your claim is approved and the elimination period is satisfied, your insurer starts paying monthly disability benefits based on your policy’s insured amount and any applicable offsets. Benefits typically replace a portion of your gross pre‑disability income. Benefits are usually paid monthly and may be taxable or tax‑free depending on how premiums were funded.

Step 9: Benefits continue while you meet the policy definition

Disability benefits can continue for months or years as long as you:

  • Continue to meet the policy’s definition of disability.
  • Provide reasonable ongoing medical updates when requested.
  • Participate in recommended rehabilitation programs when appropriate.

Many Canadian plans include rehabilitation or return‑to‑work support, such as funding for physiotherapy, psychological care, retraining, job search assistance, or workplace modifications. Some policies also include residual or partial disability benefits that allow reduced benefits when you can work part‑time or in a lower‑paying role. If you recover enough to return to work or no longer meet the disability definition, benefits stop.

Step 10: When disability insurance benefits end

Benefits usually end when:

  • You no longer satisfy the policy’s disability definition (for example, you can perform the duties of your own occupation or another gainful occupation as defined). 
  • You reach the end of the benefit period (e.g., 2 years, 5 years, or your policy’s termination age such as 65)
  • You fail to provide required medical evidence or do not comply with reasonable treatment or rehabilitation requirements, as defined in the policy.
  • You pass away; some policies include limited survivor benefits that pay a few months of benefits to a beneficiary.

How much does disability insurance pay in Canada?

Disability insurance typically replaces between 60% and 80% of your pre-tax earned income. You cannot insure 100% of your income. Furthermore, your coverage amount is based on your earned income (salary, wages, business income). It does not insure passive income (like rental properties or dividend investments) because you will continue to receive that income even if you are confined to a hospital bed.

For qualified professionals seeking coverage, the monthly benefit can range from $500 to as high as $25,000 a month depending on your specific occupation and current income levels, or even more for highly specialized cases.

I have employer-provided disability coverage, why do I need individual disability insurance?

Employer disability or for that matter most group-arranged disability policies have limitations, such as a limited coverage amount that is likely inadequate to cover your income replacement needs, nor do they have any flexibility to customize coverage.

Also, if you change employers or leave the group, you risk losing the coverage and most certainly the temporary benefit of lower pricing. Individual disability insurance plans, that you apply for directly, are something you can truly call your own. Ask the million of Canadians that have chosen to buy their own disability policies.

What can disability insurance payments be used for?

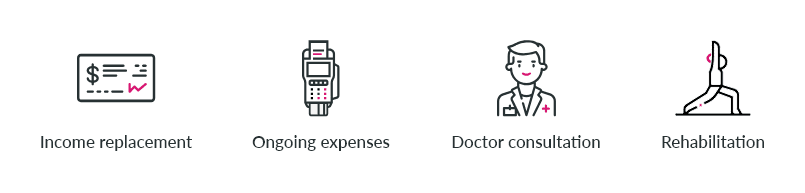
Whatever you choose! The monthly benefit you receive from an individual disability insurance policy can cover your everyday expenses as well help you pay any long-term debt repayments and medical bills. Additionally, many policies also provide non-monetary benefits such as rehabilitation, financial planning, job training, and more to help you regain your physical, emotional, and financial well-being.
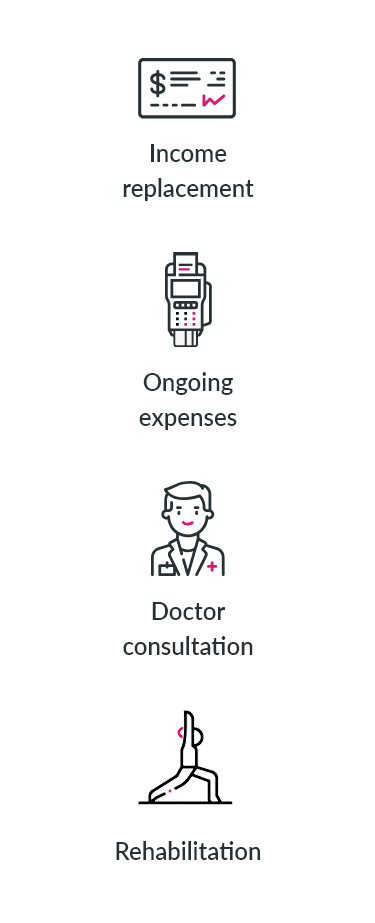
Disability benefit uses

How much does disability insurance cost in Canada?

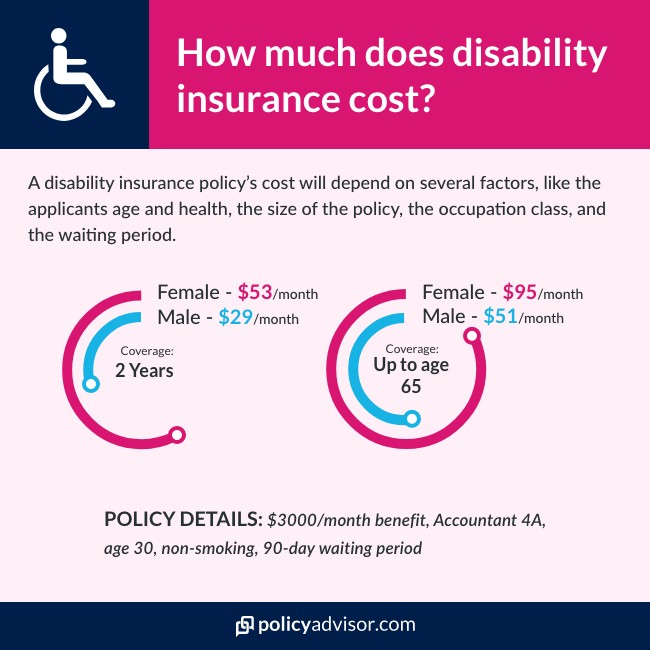
As a rule of thumb, disability insurance can cost between 1 – 3% of your annual income. The premiums can be paid monthly, quarterly or annually. However, insurance companies calculate your specific premium based on several risk factors.

What factors affect the cost of disability insurance?

The actual cost of disability insurance depends on a few factors like:

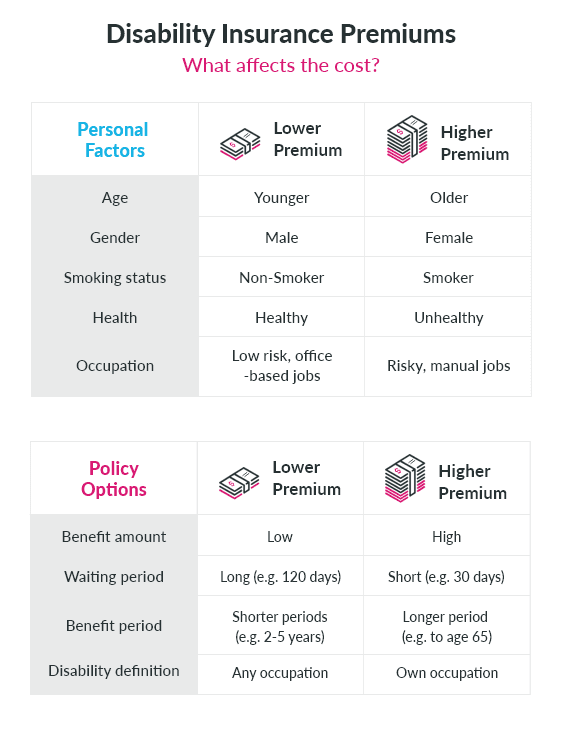
  • Age: The younger you are, the lower the risk of experiencing a disability and therefore the lower the cost of protecting you against it. Older applicants pay more.
  • Gender: In Canada, statistically, women file more disability claims than men at younger ages , meaning female rates are historically higher than male rates for the same occupation class.
  • Smoking Status: Smoking (or tobacco use) is the leading risk for disability and premature death in Canada. A tobacco-free lifestyle has huge health benefits and even bigger insurance premium benefits.
  • Health: Insurance companies look at your recent and past health history to establish whether they can offer disability insurance and the price at which they should offer.
  • Occupation: Premiums are usually based on the type of occupation a person has and the perceived level of risk. A high-income earning professional working from an office has a lower premium compared to a heavy machinery operator.
Disability insurance cost

Other policy factors that affect your disability insurance premiums

The cost of disability insurance also depends on certain variable factors you choose when you start the policy: the benefit amount, the waiting period, the benefit period, and the classes of disability.

  • Benefit Amount: It depends on your current income and occupation class but is generally offered between 60-80 percent of your monthly take-home pay, up to a pre-defined maximum.
  • Elimination Period: Most long-term disability policies will allow waiting periods of 30, 60, 90, 120, 180 and 365 days, although 120 days is the most commonly selected period. The longer your waiting period the lower you will pay in premium.
  • Benefit Period: Common term lengths are 2 years, 5 years, or until age 65. The longer your chosen benefit period, the higher your premium.
  • Disability Definition: This is the most important criteria for defining the cost of your disability insurance and can even determine whether or not you will be considered eligible to receive benefits.

How do I apply for individual disability insurance?

The application process for individual disability insurance is very similar to applying for life insurance. Insurance companies will pay particular attention to whether you have any preexisting conditions that could later prevent you from working.

There is also an extra step to verify your income level and work credentials since your coverage amount is generally established based on your current income. In some cases, companies may also benchmark coverage off the average income levels from previous years.

Will disability insurance cover me if I’m self-employed?

If you are amongst the rising number of entrepreneurial Canadians choosing to be their own boss, you should plan for a safety net for you and your family through disability insurance. Disability insurance plans are designed to cover self-employed individuals’ needs for protecting their income and some can also help cover business expenses. You’ll need to provide proof of income for a substantial period of time and the status may also affect the price of premiums.

Does disability insurance cover pre-existing conditions?

Pre-existing conditions don’t necessarily disqualify you from obtaining disability insurance. Insurance companies will typically carve out an exclusion for certain pre-existing conditions. These exclusions may be permanent, or in some cases may be removed if there is no recurrence or degeneration of the condition within a pre-designated period of time.

If you currently deal with a condition or disability but can still perform the duties of your occupation, it’s possible to obtain disability insurance for conditions or illnesses unrelated to your current disability. You can be covered for new, unrelated disabilities, but not further complications from the pre-existing ones you had.

Is pregnancy covered under individual disability insurance?

It’s complicated and really depends on your policy. While most policies won’t pay disability benefits for a normal pregnancy or childbirth, some will approve claims for disabilities arising from complications during pregnancy or childbirth. When in doubt, speak to our licensed advisors.
Thinking about disability insurance?
Use our one-of-a-kind disability insurance assessment tools and get instant disability insurance quotes.
GET STARTED

Do I need disability if I have critical illness insurance and life insurance?

Life insurance and critical illness insurance are important protection products, however, they serve very different needs. Life insurance covers your death; an insurance company will pay your designated beneficiary a lump-sum tax-free amount when you die.

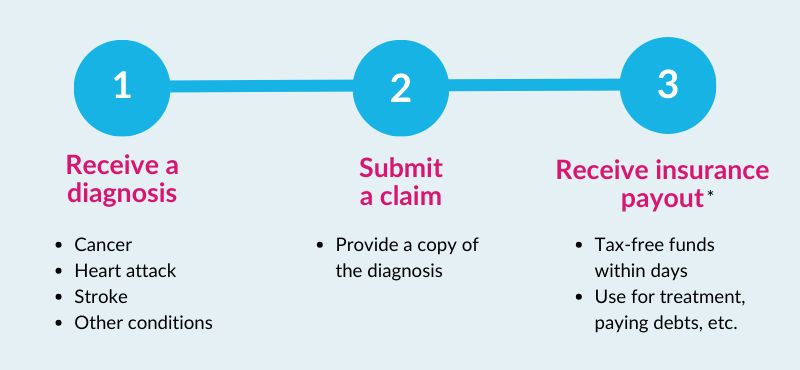
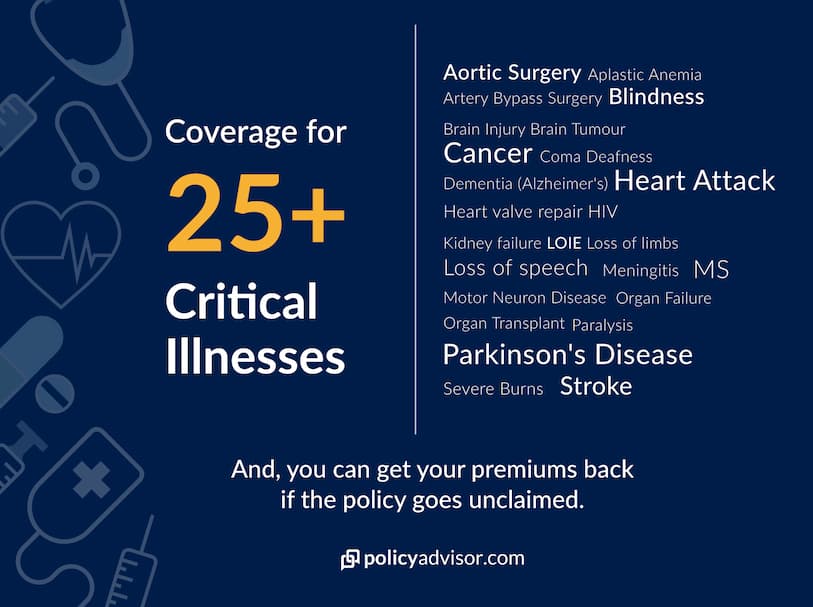
Critical illness insurance covers if you develop a specified illness, have a health event or undergo treatment. You receive a tax-free lump-sum payment once proof of the illness or health incident is established.

Similar to critical illness insurance, disability insurance is a living benefit to you. However, the disability is specifically designed to replace your ongoing income when you are unable to work due to disabilities that may not qualify as life-threatening and therefore not trigger a payment under critical illness policies.

Wouldn’t public healthcare or Canada Pension Plan (CPP) cover me instead?

If you contribute to Employment Insurance (EI) and the Canada Pension Plan (CPP) or Quebec Pension Plan (QPP), you may qualify for EI Sickness Benefits and CPP Disability Benefits. However, eligibility rules are strict, and payouts are often far below your current earnings.

EI Sickness Benefits support Canadians who can’t work due to illness, injury, or quarantine. Benefits are payable for up to 26 weeks after a one-week waiting period, at 55% of your average insurable weekly earnings, up to a maximum of $729 per week. Benefits are taxable, and while some claimants may qualify for a family supplement based on net family income and dependants, the overall safety net is limited and typically insufficient to maintain your lifestyle.

CPP Disability Benefits are for contributors whose disability is both severe (prevents any substantial, gainful work) and prolonged (long-term or likely to result in death). The maximum monthly CPP Disability payment is $1,741.20, while the average for new beneficiaries is about $1,210–$1,235 per month. CPP benefits are taxable, and approval requires that you be unable to work at any job on a regular basis.

Private disability insurance is designed to cover the gap left by these public programs, providing higher, more reliable income replacement when you can’t work.

I have insurance through WSIB, why would I need private disability insurance?

The Workplace Safety and Insurance Board (WSIB) is an Ontario-specific workers’ compensation board. Each province, territory, and Canada itself (for Federal employees) has its own. These boards exist to protect employees from the financial hardships associated with work-related permanent injuries and conditions and are solely funded through employer premiums.

In cases where you have WSIB coverage through your employer, remember it may not be what you think it is. Disability insurance offered through WSIB is generally tailored specifically around covering accidents that happen on the job. If you are injured outside of the workplace, this insurance won’t cover you, and mostly involves lump sum tax-free payments for loss of appendages or senses like sight and hearing due to a workplace accident.

When should I buy disability insurance?

If you need disability insurance, then purchase it right now! The cost of disability insurance will never be lower for you than it is currently; the costs only increase with age. If you’re in relatively good health, you should easily qualify for a disability policy and can lock in lower rates at this age.

Alternatively, if your health declines or occupation changes, you may no longer be insurable at an affordable premium in the future that you could easily obtain today.

How do I buy disability insurance in Canada?

You can buy disability insurance in Canada directly through PolicyAdvisor by comparing quotes, customizing your coverage, and applying online. Simply calculate your income replacement needs, compare personalized quotes online from top insurers, and submit your digital application in minutes.

Our licensed advisors help you get the best rate, assist with medical underwriting requirements, and lock in your policy without any pushy sales tactics.

30 Insurance Providers. One Phone Call.
PolicyAdvisor can help you save time and money when comparing Canada's top insurance companies. Give us a call!
GET STARTED

Frequently Asked Questions

Are disability insurance payments taxable?

Disability income may or may not be subject to income tax, depending on whether the policy premium was funded with pre-tax or after-tax dollars, among other considerations. If you are paid out by a policy that was fully or partly paid by your employer or another association or entity, generally using pre-tax premium dollars, you will be taxed when you receive the payment.

However, if you are paying the full price for premiums throughout your coverage period, and do not claim them as tax-deductible business expenses, you will not be taxed on the benefit.

Can I get my premiums back if I don’t make a claim during the coverage period?

Some disability insurance policies offer a Return of Premium (ROP) rider. What this means is that after a set time period where you make zero claims, you are entitled to receive a percentage back of the premiums you paid.

What happens at the end of the coverage period?

Some disability insurance policies have options to convert them to long-term care coverage at the end of the coverage period. You would typically need to be between the ages of 55-65 when your coverage period ends to take advantage of this option.

What happens to my disability insurance payout if I die?

In most cases, your benefit ends with your death, the same as your wages would with a job. However, many disability policies will also include a survivor benefit whereby your family or any designated beneficiary may receive a lump sum payment of up to 3 times the maximum monthly benefit, should you pass away while receiving disability benefits.

Do I pay more if I purchase a disability policy through a broker?

Of course not! On the flip side, you may be able to save money on a disability policy if you use an independent broker. At PolicyAdvisor, we compare multiple insurers, evaluate them across features and prices and recommend to you the best disability coverage at the lowest price possible.
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

A guide to short-term disability insurance in Canada

Disability insurance can protect you and your family from major loss of income if you are injured or become ill and can no longer work. Coverage is categorized based on the length of the benefit period, called short-term disability insurance (STD) and long-term disability insurance (LTD). STD provides temporary income replacement while you recover, while LTD typically takes over when your STD benefits or elimination period ends, providing income support for a longer-term disability.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is short-term disability insurance?

Short-term disability insurance provides income replacement if you are unable to work for a short period of time. The benefit payments can begin as soon as the waiting period is over (0-14 days), with coverage lasting typically between 6-26 weeks, although coverage can also go as long as 52 weeks. 

It is commonly used for temporary health issues, like minor accidents, sports injuries and back problems that may prevent you from working for a few weeks or months. The benefit payments from STD insurance can cover most of your lost income, so while you recover, you don’t have to worry about meeting your basic financial needs.

short-term disability insurance

How does short term disability insurance work?

Short-term disability insurance acts as income replacement for the time after you use your sick days and before any long-term disability insurance kicks in (if you have that in place). 

  • Apply for STD insurance benefits: Once your sick days are exhausted or if you do not have paid sick leave, you can file a claim under your short-term disability plan to replace part of your lost income
  • Provide medical documentation: The insurer will require medical records, reports, or other information from your healthcare provider to confirm your condition and inability to work
  • Complete the waiting period: Your policy may have a waiting or elimination period before benefits begin. Depending on the plan, this can vary from a few days to several weeks.
  • Receive income replacement: Once your claim is approved and the applicable waiting period of 0-14 days has been met, you can receive a portion of your regular income. Short term disability coverage lasts 6 to 26 weeks, although some plans may provide benefits for up to 52 weeks

If you remain unable to work after your short-term disability benefits end, you may transition to long-term disability insurance benefits, provided you meet its eligibility requirements.

What does short-term disability usually cover?

Short term disability insurance can cover a range of illnesses, injuries, and medical conditions that temporarily prevent you from working. Common conditions that may be covered under short-term disability benefits include:

  • Cognitive issues: Conditions that affect brain function, such as memory problems, difficulty concentrating, impaired decision-making, confusion, or delirium, may make it difficult to perform regular work activities
  • Breathing difficulties: Respiratory conditions such as asthma, pneumonia, influenza, tuberculosis, or other lung diseases can make it difficult to work, particularly when symptoms significantly affect breathing or physical activity
  • Chronic pain: Persistent pain caused by conditions such as back problems, arthritis, or cancer may qualify when the symptoms are severe enough to prevent an employee from performing their regular duties or daily activities
  • Hearing issues: Hearing impairment caused by factors such as illness, injury, prolonged exposure to loud noise, or other medical conditions may affect a person’s ability to perform their job, particularly in workplaces where communication or hearing is essential
  • Digestive issues: Conditions affecting the digestive system, such as irritable bowel syndrome (IBS), gastroesophageal reflux disease (GERD), or certain cancers, may qualify when symptoms prevent an employee from working
  • Restricted mobility: Conditions that limit movement or the use of the upper or lower body may qualify for STD insurance benefits. For example, an injury or illness that requires the use of a wheelchair, cane, or walker may temporarily prevent someone from performing their regular job duties

What does short-disability insurance not cover?

Short-term disability insurance doesn’t cover work-related or on-the-job injuries. There are a few other exclusions as well, such as:

  • Pre-existing conditions
  • Self-inflicted injuries
  • Work-related injuries
  • Elective or cosmetic procedures
  • Cosmetic procedures
  • Disabilities outside the policy definition

How can short-term disability insurance help in real-life situations?

One of our advisors recently helped a client who worked as a construction worker. After reviewing his income, occupation, and existing workplace benefits, the advisor helped him choose short-term disability coverage to protect his earnings if an injury temporarily prevented him from working.

Later, the client was injured in a car accident and required hospitalization followed by several months of recovery at home. Because he was unable to perform physically demanding duties or return to the construction site, he could not earn his usual income. After satisfying the policy’s waiting period (0-30 days), his short-term disability benefits provided a portion of his lost income, helping him cover everyday expenses while he recovered and prepared to return to work.

Types of short-term disability insurance

Short-term disability benefits in Canada can come from government programs, an employer-sponsored group plan, or an individual policy purchased from a private insurer. Each option works differently and offers different levels of income protection.

  • Government programs: The federal government offers disability-related income support through programs such as Employment Insurance (EI) Sickness Benefits and Canada Pension Plan (CPP) Disability Benefits. EI Sickness Benefits provide short-term income support, up to a maximum of $729 per week for up to 26 weeks. CPP Disability Benefits are available to eligible CPP contributors aged 18 to 65 with a severe and prolonged disability that regularly prevents them from working, offering a maximum monthly benefit of $1,741.20
  • Employer-sponsored plans: Many employers offer short-term disability coverage as part of a group benefits plan. Depending on the plan, benefits may replace 50%-100% of your regular income while you are unable to work. Your employer may pay all or part of the premium, making this coverage relatively affordable for employees. However, the amount and duration of coverage depend on your employer’s plan
  • Individual short-term disability insurance: You can also purchase disability coverage directly from a private insurer. An individual policy can provide coverage that is separate from your employer, giving you greater control over the amount of income you want to protect, the waiting period, and the benefit period. Because the policy is owned by you, coverage generally remains in place even if you change jobs, as long as you continue paying the premiums

How is an individual policy different from a work short-term disability plan?

The main difference between an individual short-term disability (STD) policy and an employer-sponsored plan is who owns and pays for the coverage. Here’s how they compare:

  • Who pays the premiums: With an individual policy, you purchase coverage directly from a private insurer and pay the premiums yourself. With an employer-sponsored plan, your employer may pay all or part of the premium, or the cost may be shared among employees through payroll deductions. Some workplace or union plans may also allow you to pay an additional premium to upgrade your coverage
  • Cost: Employer-sponsored STD coverage is often less expensive for employees because the premiums may be subsidized by the employer or negotiated as part of a group benefits plan. Individual coverage is generally more expensive because you are responsible for the full premium
  • Coverage and flexibility: An employer’s short-term disability plan generally has predetermined benefit amounts, waiting periods, and coverage terms that apply to eligible employees. An individual policy, on the other hand, gives you greater flexibility to choose the amount of income you want to protect and adjust features such as the waiting period, definition of disability, and benefit period to suit your needs
  • Portability: Individual short-term disability coverage is generally portable, meaning it stays with you if you change jobs, become self-employed, or leave the workforce, as long as you continue paying your premiums. Employer-sponsored coverage is tied to your employment and may end when you leave the company
Still looking for disability insurance rates?
PolicyAdvisor saves you time and money when comparing Canada’s top insurance companies. Check it out!
GET STARTED

Benefits of short-term disability insurance

Listed below are some of the reasons why STD Insurance is important:

  • Replaces a portion of lost income: Short term disability benefits can replace 50-100% of your regular income when an illness or injury prevents you from working. Having income protection can reduce the financial stress associated with an unexpected illness and allow you to focus on recovering rather than returning to work too soon
  • Bridges the gap before LTD coverage: STD insurance coverage can provide income support during the initial weeks or months of a disability before long-term disability (LTD) benefits become available, if LTD coverage is included in the plan
  • Supports employee retention: For employers, offering short term disability coverage can make a benefits package more competitive and help attract and retain employees. Employees often place greater value on workplaces that protect against unexpected financial hardship
  • Encourages employees to take necessary time off: Income protection can give employees greater flexibility to take time away from work when they are genuinely ill or injured, rather than feeling pressured to work through a health issue
  • Flexible spending: Payouts go directly to you with no restrictions, meaning you can use the funds for rent, groceries, utilities, or medical bills

How long do short-term disability benefits last?

Short-term disability benefits most commonly last 6 to 26 weeks, although the exact duration varies by plan. Benefits may be approved in shorter increments and require updated medical documentation to continue. If you remain unable to work after STD benefits end, you may transition to LTD benefits if you have eligible coverage. 

Do anxiety or mental health issues qualify for short-term disability?

Yes, anxiety and mental health issues usually qualify for short-term disability. This applies when a medical practitioner confirms that your symptoms prevent you from performing your usual job duties. For example, if a panic attack hospitalizes you and you are unable to work, it may better justify a short-term policy’s payout. As mental health issues become more widely diagnosed and recognized at the same level as physical illness or injury, more insurers are including them in their short-term disability plans.

However, not every policy guarantees mental health coverage. Some might only cover physical injuries or require additional premiums to be included in the scope for mental health coverage, or may exclude specific mental illnesses depending on the individual’s mental health history. Also, whether mental health issues qualify may depend on the severity. For example, a stress leave may create a grey area to qualify for short-term disability insurance.

Are short-term disability benefits taxable in Canada?

Short-term disability benefits may be taxable depending on who pays the premiums. If your employer pays all or part of the premiums, the benefits are taxable. If you pay 100% of the premiums yourself with after-tax income, the benefits are tax-free. If benefits are taxable, you may have to pay income tax on the amount you receive. The tax treatment thus can vary based on how your plan is structured and who actually pays the premium.

Is short term disability insurance worth it?

Whether you should purchase short-term disability insurance depends on you and your family’s needs. First, figure out how much income you will need to replace if you face an unfortunate circumstance that leaves you unable to work. Could employment insurance payouts cover this amount? Or do you need additional coverage?

Further, your employer may sponsor short-term disability coverage. This might be an affordable option for you to cover some of your income, but it might not provide enough to fit your family’s needs. This might mean purchasing additional policies or upgrading your work plan. 

It is beneficial to work with an insurance advisor to determine what your short-term disability needs are and how much a short term disability insurance policy costs. One of our advisors at PolicyAdvisor can review your employer-provided plan and make sure you have a short-term disability policy that matches your needs. Schedule a call with one of our experts today and ensure your family is protected if you ever face an illness, accident, or injury.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently asked questions

Can I get individual short-term disability insurance if I am self-employed?

Yes, self-employed individuals can purchase individual short-term disability insurance from a private insurer since they do not have access to employer-sponsored coverage. An individual policy provides portable income protection and allows you to choose coverage based on your income and financial needs.

Can I have short-term and long-term disability insurance at the same time?

Yes, you can have both short-term and long-term disability insurance at the same time. STD provides income replacement during the initial weeks or months of a disability, while LTD can take over after the STD benefit period or LTD waiting period ends if you remain unable to work and meet the policy’s eligibility requirements.

Can I get short term disability insurance without an employer?

Yes, you can purchase an individual short-term disability insurance policy directly from a private insurer without relying on employer-sponsored coverage. This can be particularly useful for those whose workplace does not offer short term disability benefits.

What happens when short-term disability benefits end?

If you remain unable to work after your short-term disability coverage ends, you may transition to long-term disability (LTD) benefits, provided you have LTD coverage and continue to meet its eligibility requirements.

How long is the waiting period for short-term disability insurance?

The waiting period for short term disability insurance is usually 0-14 days, depending on the policy. It refers to the period you must wait before STD benefit payments begin after becoming disabled. During this time, you may need to rely on sick leave, savings, or other sources of income to cover your expenses.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Long-term disability insurance in Canada: A complete guide

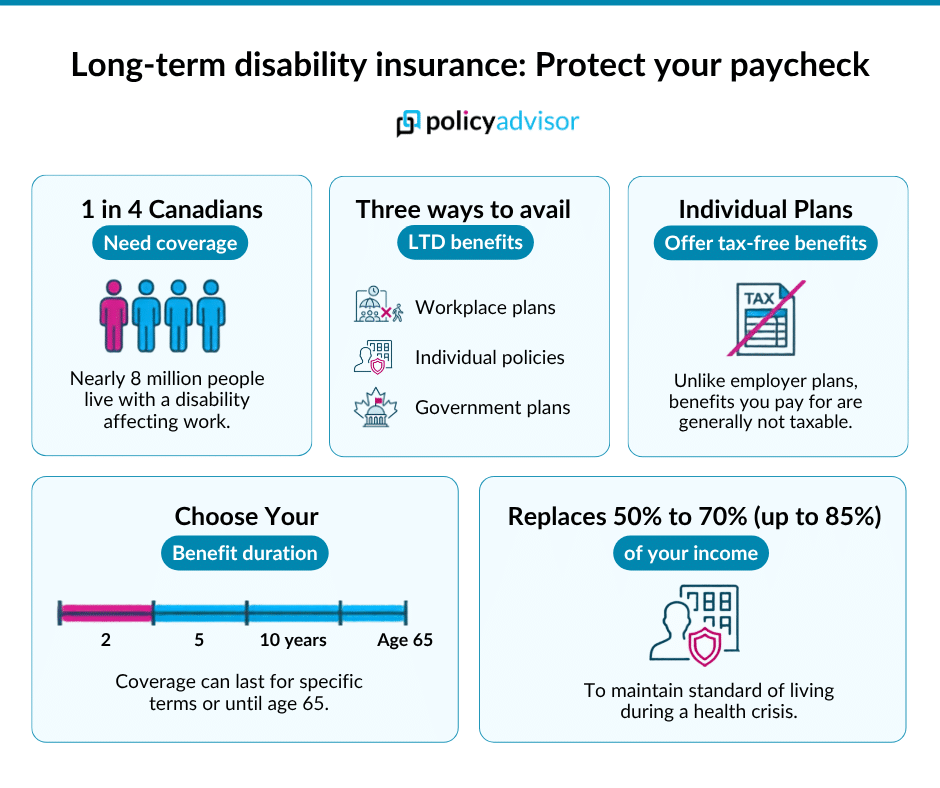
Long-term disability (LTD) insurance provides income protection if an illness or injury prevents you from working for an extended period. This coverage can be important for Canadians because nearly 8 million people aged 15 and older, 27% of the population, were living with a disability, according to the latest comprehensive Statistics Canada data. Long-term disability benefits typically replace part of your income after an elimination period and can continue for several years or until age 65.

Looking for the most affordable plan?

Enjoy the best rates on your disability insurance purchase today!

What is long-term disability insurance?

Long-term disability insurance provides income protection if you become unable to work due to a serious illness or injury. It typically replaces 50% to 70% (sometimes up to 85%) of your income and kicks in after short-term disability benefits end. 

Coverage can last 2, 5, or 10 years, or even until age 65, depending on the policy. Common conditions that qualify for benefits include cancer, mental health disorders, and musculoskeletal injuries, helping individuals manage financial needs while recovering.

While employer-provided disability plans and government programs like EI, CPP, and WSIB offer some coverage, they often have limitations on benefit amounts, eligibility, and coverage duration.  An individual policy can help fill gaps in employer-sponsored coverage. Private long-term disability insurance allows you to customize coverage, choosing benefit amounts, coverage length, and waiting periods. However, the benefits are often coordinated with other income (CPP‑D, WSIB, EI, employer DI), and tax treatment depends on who pays the premium.

long-term disability insurance

What are the types of long-term disability insurance?

There are three types of long-term disability insurance. It is available through workplace plans, government plans, and as individual policies. The main differences are who qualifies, how much control you have, and whether the coverage stays with you if you change jobs.

  • Group long-term disability insurance: This coverage is provided through an employer or a professional association. It provides coverage for a portion of your salary if you become disabled. The plan offers pre-set benefits and policy terms, which may include limitations on benefit amounts, waiting periods, and coverage duration. Association plans can be particularly relevant for professionals who do not have employer-sponsored coverage
  • Individual long-term disability insurance: Individual or private LTD insurance is purchased privately from an insurer. This provides greater control over the benefit amount, waiting period, benefit period, and definition of disability. It can supplement existing group coverage and help fill gaps in workplace or association plans
  • Government disability benefits: Government programs can provide financial support to Canadians who cannot work because of a disability. Depending on the situation, this may include EI sickness benefits, CPP disability benefits, or workers’ compensation benefits such as WSIB

Differences between group and individual long term disability plans

Group and individual long-term disability (LTD) insurance differ in cost, underwriting, taxation, coverage flexibility, control over the policy, and portability. In the table below, we have listed the differences between group and individual long-term disability plans. 

Group vs individual long-term disability plans:

Features Group long-term disability plans Individual long-term disability plans
Eligibility & underwriting Generally easier to qualify for, with limited or no individual medical underwriting for basic coverage Usually requires individual underwriting, including health questions and potentially a medical exam
Who pays the premiums? Your employer may pay all or part of the premiums You pay the premiums yourself, typically with after-tax income
Taxability If your employer pays the premiums, the benefits are generally taxable Benefits are tax-free
Cost Typically less expensive because the risk is spread across a group of employees Usually more expensive because the policy is individually underwritten and offers greater customization
Coverage flexibility Coverage amounts, waiting periods, benefit periods, and other features are determined by the group plan You can customize key features, including the benefit amount, waiting period, benefit period, and definition of disability
Portability Coverage may end when you leave your employer, although conversion options may be available Coverage generally stays with you regardless of changes in employment
Control over the policy Your employer or plan sponsor selects the policy terms You choose the insurer and policy features based on your needs

How long can you get long-term disability benefits from work?

Long-term disability insurance administered through your employer functions similarly to individual long-term disability insurance. A plan might provide two to five years of payouts or provide the benefit until your retirement age. However, you might not have the option to choose the benefit period for an employer-sponsored plan. An employer is typically selecting the benefit period instead. If the selected period doesn’t work for your circumstances, it might be beneficial to look into private insurance.

Employers may also give employees the option to upgrade their work policy. But doing so can come at an additional cost. For example, suppose your employer-sponsored long-term disability plan pays 50% of your income for five years after a 120-day waiting period. The plan might have an upgrade option, where, in exchange for a $50 bi-weekly paycheque deduction, your employer’s long-term disability insurance now offers a benefit of 65% of your income until you’re 65 after a 120-day waiting period. 

What is partial or residual disability insurance?

Partial or residual disability insurance provides benefits when an illness or injury limits your ability to work or reduces your income, but does not prevent you from working entirely. For example, if you return to work part-time or in a reduced-capacity role and earn less than before your disability, the policy may pay a proportion of your long term disability benefit to help replace the lost income.

How does long term disability insurance work?

To get the benefits of long-term disability insurance, you pay premiums while working, and if you become disabled, you submit a claim and complete the policy’s waiting period before receiving monthly benefits.

Here’s how a long-term disability policy works:

  • You pay premiums while you are working: You get long-term coverage in exchange for the premiums you paid while you could work. This usually costs between one and three percent of your annual income. You are no longer required to make premium payments once your benefit period starts
  • You become disabled: If an illness or injury prevents you from working and meets the policy’s definition of disability, you can submit a claim to your insurer
  • You complete the waiting period: Also called the elimination period, this is the time between the onset of your disability and when benefits become payable. Common waiting periods include 4, 8, 12, 16, 20, or 52 weeks or even 2 years. Generally, a longer waiting period means lower premiums. This is because your disability might recover before the end of the waiting period. If so, you can return to work, and there’s no longer a need for long-term disability payouts.
  • You can get short-term disability benefits: During the waiting period before your long-term coverage begins, you may have short-term disability insurance
  • You receive long term disability benefits: Once your claim is approved and the waiting period ends, the insurer pays the long term monthly disability benefit outlined in your policy. Your long-term disability benefits may continue for a specified number of years or until a certain age, provided you continue to meet the policy’s definition of disability

Core definitions of disability

Not every illness or injury automatically qualifies for LTD benefits. Your policy will define what constitutes a disability and the conditions you must meet to receive benefits. For example, some policies use an “own occupation” definition, while others may require that you be unable to perform any occupation for which you are reasonably suited by education, training, or experience.

Any occupation vs regular/own occupation plans

Long-term disability insurance is categorized into “any occupation” and “regular or own occupation” plans. Any occupation plans only allow you to receive disability benefits if you are entirely unable to work i.e., your illness or injury means you can’t perform the duties of any job you’re reasonably suited for. For example, suppose you work as a cashier at a grocery store. You suddenly can’t perform cashier tasks, which require long periods of standing, due to an injury. In this case, you might still qualify to work as a store greeter, which can be done sitting down. You then wouldn’t be eligible for your policy’s disability benefits because you are able to work another reasonably suited job despite your injury. 

An own occupation plan means that an inability to perform the primary duties of your role qualifies you for disability benefits. So even if you could still work another job, you would receive benefits if you are unable to perform the role you had before the injury or illness. Some insurers will end or reduce benefits, however, if they discover you begin working another role. We recommend “own occupation” plans for individuals with specialized professions that would require a significant pay cut if they chose to work in another field.

What illnesses qualify for long-term disability?

A LTD can be caused by illness, injury, or chronic conditions and must meet the definition of disability in your insurance policy. Some of the most common long-term disabilities include:

  • Serious illnesses (e.g., cancer, heart disease)
  • Mental health disorders (e.g., severe depression, anxiety)
  • Chronic conditions (e.g., multiple sclerosis, arthritis)
  • Injuries (e.g., spinal cord damage, paralysis)

Other common illnesses and injuries include: 

  • PTSD
  • Back injuries
  • Factures
  • Head or brain injuries (concussions)
  • Diabetes
  • Nervous system disorders and seizures
  • Lupus
  • Fibromyalgias and chronic fatigue syndrome
  • Gastrointestinal illness (Crohn’s, colitis, irritable bowel syndrome, diverticulitis)

To qualify for benefits, your condition must significantly impact your ability to work and may require medical proof.

How can long-term disability insurance help in real-life situations?

One of our advisors recently helped a client who worked in a physically demanding warehouse job. The advisor reviewed his income, occupation, and financial obligations and helped him choose a long-term disability policy that would provide monthly income if an illness or injury prevented him from working.

Later, the client was diagnosed with multiple sclerosis (MS), which made it difficult for him to continue performing his regular duties. After using his sick days and available short-term disability benefits, he completed the waiting period under his long-term disability policy and began receiving monthly benefits that replaced a portion of his lost income. This helped him continue covering his living expenses while he was unable to work.

Do anxiety or mental health issues qualify for long-term disability?

Yes, anxiety and other mental health conditions can qualify for long-term disability benefits if the condition prevents you from working and meets your policy’s definition of disability. However, some LTD policies place specific limits on mental health claims, such as a maximum benefit period of 24 months. Short-term disability (STD) coverage may also apply first, but it typically provides benefits for a much shorter period, often several weeks or months, before LTD begins.

Your insurer will assess medical evidence and your ability to work when reviewing the claim. For instance, severe depression involving a medical diagnosis and drug treatments might justify a long-term disability payout. However, long-term leave from work due to stress may not necessarily trigger a policy’s coverage.

Benefits of long-term disability insurance in Canada

Disability insurance benefits anyone in their prime working age in the following ways:

  • Income protection: Disability insurance ensures a steady income if you are unable to work due to illness or injury. Many people think that they won’t suffer from a disability, but statistics show that disabilities are more common than you might expect
  • Peace of mind: Knowing you have financial support in case of disability relieves stress. Some might say they have savings, but savings can deplete quickly without a regular income
  • Covers expenses: It helps cover daily living expenses, medical bills, and rehabilitation costs. You might think you can rely on your spouse’s income, but a single income may not be sufficient, especially with additional medical expenses
  • Maintains standard of living: Helps you maintain your lifestyle and support your family financially. Your employer may provide workplace benefits, but employer-provided plans may not offer adequate protection or may end with your job
  • Customizable coverage: Policies can be tailored to your specific needs, ensuring optimal coverage. Some might find disability insurance expensive, but the cost of not having coverage can be far greater in the long run

How long do most long-term disability benefits last?

The duration of long-term disability benefits can vary based on the kind of disability that you have or the specific plan that you have purchased. Some companies offer disability benefits for a specific period such as 2, 5 or 10 years, whereas other companies can extend their disability benefits until an individual reaches 65 years of age. 

Many individuals choose coverage that lasts until they reach retirement age or can access other financial support, ensuring long-term financial security in case they are unable to return to work.

Don't wait until times get tough. Prepare beforehand!

Get instant disability insurance quotes now!

How much long term disability coverage do you need?

The long-term disability coverage you need depends on the amount of income you would want to replace and how much is actually covered through your employer or government plans. You should choose coverage that can replace 50% to 70% of your income. 

Some of the factors that you should take into consideration to determine the coverage are as follows:

  • Calculate your monthly take-home income. This gives you a starting point for the amount you may need to replace
  • Review your existing disability benefits. Check your employer’s group plan, CPP/QPP disability benefits, and other sources of income you may qualify for
  • Calculate your essential monthly expenses and include housing, food, utilities, debt payments, insurance, and other ongoing financial commitments
  • Cover the remaining income gap through an individual long-term disability insurance policy. Subtract the employer benefits from your estimated monthly expenses to check how much individual coverage will be enough

How is long-term disability insurance taxed in Canada?

The tax treatment of long-term disability (LTD) benefits depends primarily on who pays the premiums:

  • Employer-paid premiums: If your employer pays all or part of the long-term disability premiums, the benefits you receive are generally taxable as income
  • Employee-paid premiums: If you pay the entire premium yourself with after-tax income, your disability benefits are generally tax-free
  • Shared premiums: If you and your employer both contribute to the premiums, the tax treatment will be dependent on the benefits received from your employer

Is life insurance the same as long-term disability insurance?

Long-term disability insurance and life insurance are quite different. Life insurance is a legal agreement with your life insurance company to pay a designated beneficiary a tax-free lump sum amount upon your death. 

Thus, the two main differences are: 

  • Life insurance is paid in a lump sum to your designated beneficiary, while long-term disability insurance is a periodic benefit payment to you
  • Life insurance payouts trigger on your death, while long-term disability payouts trigger after the waiting period once you face a disability

Overall, disability insurance aims to cover your daily expenses when you can no longer earn an income. In contrast, life insurance provides your beneficiary, often your spouse or children, with a lump sum payment to cover funeral costs, debts, and other expenses after your death. 

However, some life insurance policies offer a disability rider. This is essentially an add-on to life insurance coverage to accommodate the possibility of a disability. There are two key types of disability riders:

  • Disability waiver rider: Eliminates life insurance premium payment requirements if you acquire a permanent disability
  • Disability income rider: Provides a monthly income benefit if you become totally and permanently disabled and meet the policy’s eligibility requirements

Although life insurance can accommodate disabilities through riders, it doesn’t replace a long-term disability policy. Riders don’t provide the flexibility and customizability that an individual long-term disability policy has. Riders also offer less protection, as they only pay out a portion of your life insurance benefit and do not provide any ongoing income replacement.

Do I qualify for CPP as well as LTD coverage?

Yes, you can qualify for both Canada Pension Plan Disability (CPP-D) and long-term disability coverage at the same time. The eligibility rules, however, vary for the two plans. To qualify for CPP-D, you must be under 65 years of age, while for other long-term disability plans, the eligibility will depend on the disability plan type you choose. Moreover, your long-term disability insurer will also require you to apply for CPP and may reduce your long-term disability benefit by the amount of CPP you receive. This is known as an offset, so receiving both does not necessarily mean you will receive the full amount of both benefits.

Things to consider when buying long-term disability insurance

When buying long-term disability insurance, a few things you need to consider include the definition of disability, waiting period, monthly benefits, and a few more.

  • Definition of disability: Check whether benefits are based on your ability to perform your own occupation or any occupation you are reasonably suited for
  • Monthly benefit: Choose an amount that can cover your essential expenses and supplement any existing disability benefits
  • Plan type: While individual plans are more customizable, group plans are more affordable. Pick a plan that best suits your needs and budget
  • Waiting period: A longer waiting period generally means lower premiums, but you will need enough savings or other coverage to support yourself during that time
  • Benefit period: Policies may pay benefits for a set period, such as 2 or 5 years, or until a specified age, such as 65
  • Exclusions and limitations: Review conditions or circumstances the policy does not cover before purchasing

Should you get a long-term disability plan?

Yes, long-term disability insurance may be worth considering if losing your income because of an illness or injury would make it difficult to cover your regular expenses. Whether you need additional coverage depends on your income, savings, employer-sponsored benefits, and eligibility for government disability programs.

Before purchasing an LTD plan, consider these questions:

  • How much income will you need to replace if you can no longer earn a salary from your job?
  • Could programs like EI or CPP or your workplace group disability insurance fully cover your expenses?
  • Do you need to purchase additional coverage to make up the difference between what you currently earn and any income you’d receive if you faced an injury, accident, or disability?

These questions can sometimes become challenging to answer. It might help to work with an insurance advisor to determine what type of long-term disability coverage you need. PolicyAdvisor’s expert advisors can suggest an individual long-term disability policy and match you to an insurer that fits your needs. Schedule a call now to get started!

Need further assistance?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Can I get long-term disability insurance if I’m self-employed?

Yes, as a self-employed individual, you can purchase individual long-term disability insurance to protect your income. Since you don’t have access to employer-provided benefits, this type of insurance ensures financial security if you become unable to work due to illness or injury.  When assessing coverage, insurers may average your income over the past two to three years and may request financial documents, such as tax returns or notices of assessment, to verify your earnings.

Does long-term disability insurance cover mental health conditions?

Yes, some disability insurance policies do cover mental health-related disabilities, such as severe depression, anxiety disorders, or PTSD, but coverage varies by insurer. While some plans offer full benefits, others may have limitations (up to 24 months) or exclusions for mental health conditions. It is important to carefully review the policy terms so that you do not find any surprises during times of need. 

What happens to my long-term disability insurance if I recover and return to work?

If you recover before your benefit period ends, your disability payments will stop once you can resume work. However, some policies include residual or partial disability benefits, which provide reduced payments if you can return to work part-time but not full-time. This can be helpful if your condition prevents you from working at your full capacity. 

Do I have to pay taxes on long-term disability benefits?

Whether or not you pay taxes on LTD benefits depends on who pays the premiums. If your employer pays for the policy, any benefits you receive are generally taxable income. However, if you pay the premiums yourself using after-tax dollars, your benefits are tax-free.

What happens to my long-term disability insurance if I change jobs?

Your employer-sponsored long-term disability coverage will generally end when you leave the employer, subject to the terms of the group plan and any available conversion options. An individual long-term disability insurance policy, however, generally remains in force as long as you continue paying the premiums.

Can I get long-term disability insurance if I have a pre-existing condition?

Yes, having a pre-existing condition does not automatically prevent you from getting LTD insurance. However, the insurer may apply exclusions, limitations, higher premiums, or decline coverage depending on your health history and underwriting assessment.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is Life Insurance and How Does it Work in Canada?

About one-third of Canadians are currently without life insurance and 1 in 4 millennials in the country admit they are unlikely to purchase any kind of insurance in the near future.

The basics of life insurance are just not on our radars. So if you thought ‘Term to 100’ was the title of a Drake song, don’t be embarrassed, you’re not alone.

Life insurance 101 isn’t common knowledge in Canada, which is exactly why it’s a subject worth exploring, especially if you’ve increasingly found yourself in the company of real estate agents, in-laws, or babies.

But where to begin? Is a death benefit a charity concert? Does “participating insurance” come with a ribbon? Is “return-of-the-premium” a new Star Wars flick?

Let’s just start with the basics…

What is life insurance?

Life insurance is an agreement between you and a life insurance company. The agreement is if you die, they will pay a death benefit (a lump sum of tax-free money) to someone you choose. In exchange, you agree to periodically pay them an insurance premium: a small amount of money over time.

You both decide on the amounts of cash coming in and out and the timeframes involved, but in a super simplified form, that’s really it.

How does life insurance work?

Life insurance provides financial protection to your loved ones in the event of your death. There are four key aspects of how life insurance works: 

  1. Agreement and premium payments: Life insurance is a contractual agreement between an insurance company and a policyholder. The policyholder pays monthly or annual premiums, and in return, the insurer agrees to pay a death benefit to the beneficiaries in the event of the policyholder’s death
  2. Beneficiary designation: Policyholders can designate both, primary and contingent beneficiaries. Minors cannot be named as primary beneficiaries
  3. Claim process: Upon the policyholder’s demise, the beneficiaries can file a claim process with the insurer by submitting essential documents. Once the documentation is verified, the insurance company will pay the lump sum death benefit to the primary beneficiary
  4. Living benefits: Some permanent life insurance policies such as whole life insurance allow the policyholder to access a portion of the death benefit during their lifetime. This is known as cash value

What does life insurance cover?

A life insurance policy payout can be used by the beneficiaries in any way they want to, including for: 

  • Funeral and burial expenses 
  • Replacing lost income
  • Covering outstanding debts
  • Funding your children’s education
  • Covering everyday living expenses

Life insurance terminology

Here are some handy definitions for common life insurance terminology:

Term Definition
Policyholder The person who owns the life insurance policy
Insured The individual whose life is covered by the policy
Insurer The company that provides life insurance coverage
Premium The amount paid regularly to maintain the policy
Beneficiary The person or entity designated to receive the death benefit
Death benefit The amount paid to beneficiaries upon the insured’s death
Cash value The savings component of a permanent life insurance policy that grows over time
Policy term The length of time the insurance coverage is in effect
Riders Additional provisions that can be added to a policy to customize coverage

What are the different types of life insurance in Canada?

There are two main types of life insurance:

  • Term life insurance, which lasts for a period of time called a term
  • Permanent life insurance, which covers you for the rest of your life

Most Canadians wind up with term insurance, either through individual plans or through their employer as a group plan.

Learn more about the different types of life insurance.

Term life insurance

Term life insurance makes the promise if you die, we’ll pay, but only if that were to happen within a specified period of time, or ‘term’. These terms are generally 10, 20, or 30 years, but you can choose smaller or larger term lengths or coverage that last until a specific age.

Whole life insurance

Whole life insurance covers you for your entire life and there is a cash value associated with your policy. Sometimes, whole life policies will also pay dividends based on the insurance company’s profits. This is known as participating insurance.

Limited-pay whole life insurance

Limited-pay insurance is similar to whole life, except the payment plan is condensed. For example, the term could be 20 years: once you’ve paid your premiums over that 20-year period, your insurance is guaranteed for life and you’re off the hook for premiums. This type of coverage is typically the most expensive policy option. This is because premiums are front-loaded to offset the years where you will no longer be paying.

Universal life insurance

Universal life insurance is the same as whole life insurance, except you have more choice of where your cash value is invested. If you’re a savvy investor, this gives you the opportunity to generate a larger return than what is guaranteed from a traditional whole life policy. That said, it requires you to actively monitor the investment choices you’ve made with the cash value. Alternative investment solutions may help you achieve your financial goals faster.

Term to 100 life insurance

Even though the word term is in the name, term to 100 is a whole life insurance policy that covers you until your death. The difference is with this policy there is no cash value or investment component, making the premiums a little cheaper. As a bonus, if you do live beyond age 100, you are no longer required to pay premiums and retain your coverage. Term to 100 life insurance policies are unique to Canada.

Annual renewable term life insurance (ART)

A less popular life insurance option, annual renewable term life insurance (ART) is designed for those looking for short-term life insurance coverage. ART is available on an annual basis with the possibility of renewal and can protect people who are between jobs, who want to improve their health before locking in a longer-term policy, or those with short-term debt.

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Is life insurance worth it?

If you have dependents, life insurance premiums are worth the cost. Life insurance provides peace of mind knowing that your family will be taken care of financially when you pass away.

If you don’t have dependents, there could be other circumstances where the benefits of life insurance is worth the price of premiums. These can include:

  • Taking advantage of your youth and health to ensure a lower premium and future insurability
  • Providing a charitable gift to your favorite cause or organization
  • Leaving a financial gift or legacy to children or grandchildren, regardless if they are dependents or not

When should I buy life insurance?

Life events create the need for life insurance. Buying a home, having children, and getting married are good indicators that there are those in your life who depend on your income to maintain their quality of life. Premiums rise as you age, so purchasing insurance earlier in life can save you money.

Do I need life insurance?

Perhaps a better question is, do the people in your life need it?

Insurance is for clearing out debts (personal or business-related) and supplying an income replacement source to someone who relies on you because you’re no longer around.

Buying life insurance lets you secure assets for your family’s future by investing in an alternate income source. Without life insurance and the security of this death benefit, you’re putting all your family’s financial eggs in one basket: you, being alive and able to earn an income.

You may assume you have life insurance through your work’s group benefits, but such policies require a close look to ensure it covers everything you need.

Does life insurance have cash value?

Permanent life insurance policies accumulate a cash value as the insurance companies invest your premiums. Policies such as whole life and universal life insurance have this investment feature. You can either cash it out, save it, loan against it, or apply the value to your existing policy.

Learn more about the cash value of life insurance.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

How much does life insurance cost?

The cost of life insurance depends on several individual factors. For most young, healthy adults life insurance costs are quite reasonable on a 20-year term policy.

For instance, a 30-year old, non-smoking Ontario woman of average health, would only pay $21 per month for a $500,000 death benefit on a 20-year policy. If you’re personalizing your insurance policy so that it suits your specific needs and budget, life insurance can and should be affordable.

Coverage 10-Year Term 20-Year Term
$250,000 $11/month $14/month
$500,000 $15/month $21/month
$1,000,000 $23/month $36/month

Premiums for female, non-smoker, 30-years old

Personal factors affect your life insurance cost. Factors include:

  • Age: Insurance premiums rise in cost as you age.
  • Smoking Status: Smokers pay more for life insurance.
  • Gender: Generally, men have higher life insurance premiums than women.
  • Health: Insurance providers see health problems as adding to the risk of insuring you.
  • Family Medical History: Insurance providers also calculate the risk of known hereditary illnesses.

Details of your life insurance policy will also affect the price of your monthly premium. These aspects include:

  • Term Length: The longer your coverage period, the higher the premiums.
  • Coverage Amount: A larger death benefit will also dictate higher insurance premiums.
  • Type of Insurance: Term life insurance is less expensive than whole life insurance.

What are life insurance premiums?

Life insurance premiums are the amount of money you agree to pay the insurance company, usually monthly or annually, in order to receive coverage. The higher your age, the longer your term, or the larger your death benefit, the higher your premiums will be.

How much life insurance do I need?

You should get as much life insurance as you can afford. Most wish to leave a multi-million dollar fortune to their family and loved ones when they die. But that’s not financially realistic for most.

Determine what “affordable premium” means to you. Build a budget to assess your family’s current financial needs, their future needs, your current liabilities and debts, and any costs associated with your death. That’ll reveal what kind of coverage amount you should aim for and the costs associated with it.

Some use the 10x your annual income rule, but we highly recommend using our life insurance coverage calculator to get a quick but comprehensive recommendation.

Should I get life insurance through work?

Getting life insurance through work can be a convenient and cost-effective option, but it’s important to consider your specific needs and circumstances. Here are a few points to help you decide:

  1. Employer-provided life insurance is often easier to obtain and may come at a lower cost since it’s typically part of a group plan. The premiums are often subsidized by your employer, making it an affordable option
  2. While convenient, the coverage amount offered through work might be limited, often equating to one or two times your annual salary. This may not be sufficient to cover all your needs
  3. One of the downsides of employer-provided life insurance is that it’s not always portable. If you change jobs or lose your job, you might lose your coverage. Having a separate individual policy ensures that you maintain coverage regardless of your employment status

What happens to a term life insurance when it expires?

When your insurance policy expires you have several options. Typically you

  • can convert a policy to whole life coverage
  • renew the policy at a higher premium
  • apply for a brand new life insurance policy
  • let the coverage expire if you no longer need it

Learn more about what to do if you outlive your term life insurance policy.

Can I renew a term insurance policy?

Most term life plans come with a renewability clause, that lets you extend your coverage upon expiry without having to redo your medical exam.

The downside of renewing your coverage is the cost: your premiums are reassessed (increased) to match your older age. Thus, some Canadians prefer to apply for a new insurance policy at the end of the term.

Looking for an affordable life insurance policy?

Get the lowest quotes at PolicyAdvisor!

What personal information do I need to share with my insurance company?

Life insurance companies have a mandatory set of questions they ask during the underwriting process. They include:

Based on your answers to these questions, you’ll be placed into a risk category and offered premiums accordingly.

Additional in-person medical exams will be required from time to time, especially when applying for larger coverage amounts.

Learn more about how to prepare for a life insurance medical exam.

What is an attending physicians statement?

The provider may also ask for a health report (called an attending physicians statement or APS) from your family doctor or any specialists you see about ongoing health conditions.

Who should you name as your life insurance beneficiaries?

Your beneficiaries are those you name in your policy that receive the death benefit when you die. It’s important to list the right people so that your policy’s payout is used as you intended. If you do not name a beneficiary or there is ambiguity at the time of your death then probate can affect your life insurance benefit.

Are there different types of beneficiaries?

Yes, there are revocable and irrevocable beneficiaries.

  • Revocable Beneficiary: a beneficiary that can be changed without their consent.
  • Irrevocable Beneficiary: a beneficiary that has to sign off on any changes to the policy, including coverage and beneficiary changes.

Should you name your children as beneficiaries?

In Canada, minor children cannot legally receive the funds from a life insurance policy until they reach the age of majority. Thus, many people create a trust to manage the funds of life insurance death benefits meant for their children.

A trust is an estate planning tool that allows you to choose another party (the trustee) to manage financial assets for a beneficiary until a pre-determined time or when they reach the age where they can legally manage their own funds.

Learn more about managing life insurance benefits with a trust.

Who needs life insurance in Canada and why?

Canadian life insurance can help different people with varying circumstances, like:

  1. Couples: Life insurance is important for couples, as it ensures that one partner’s death doesn’t create a financial burden for the surviving partner. It can help cover living expenses, debts, and future financial goals
  2. Business owners: Business owners should consider life insurance to protect their business interests. It can provide funds for succession planning, cover outstanding business debts, and help ensure the business continues smoothly in the event of their death
  3. Seniors: Seniors may need life insurance coverage to cover final expenses, such as funeral costs, and to leave a financial legacy for their heirs. It can also help with estate planning and ensure that the estate is not burdened with unexpected costs
  4. Parents with young children: Parents with young children should consider life insurance to secure their children’s financial future. It can help cover education costs, daily living expenses, and ensure that their children are cared for financially in their absence
  5. Single individuals: Single individuals without dependents may still benefit from life insurance. It can help cover personal debts, funeral costs, and leave a financial gift or charity donation
  6. Professionals with high incomes: High-income professionals often have significant financial responsibilities and goals. Life insurance can help protect their income, ensure the continuation of their lifestyle for their family, and address any large debts or estate taxes
  7. Parents with adult children: Parents with adult children may want life insurance to provide a financial cushion or to leave an inheritance. It can also help with estate planning and cover any remaining debts
  8. Individuals with significant debts: If you have substantial debts, such as a mortgage or student loans, life insurance can ensure that these debts are paid off and don’t become a burden to your loved ones

Should I add life insurance riders to my policy?

A life insurance rider is an optional feature added to your life insurance policy to better address your unique insurance needs. An insurance rider typically requires an additional payment which is added to your monthly premium, though some riders may also be included at no extra cost. There is a wide range of available riders. Common riders include additional term riders, critical illness riders, and guaranteed insurability.

Learn about life insurance for riders or read more about:

Which is the best life insurance policy?

The life insurance policy you should choose isn’t an answer in the back of the book. Life insurance is a deeply personal purchase and there are a lot of factors to consider. Not only should you factor in your family’s current financial needs, but you should also account for future costs like tuition fees, funeral arrangements, estate taxes, and any other debts or obligations you would want settled should you die. There a lot of options to choose from and a myriad of coverage combinations when you search for life insurance quotes. But, you should only purchase a policy you can afford and that you’re confident makes the most sense for you and your family.

Luckily, we’ve built a pretty great tool that can help you figure that out.

Head to our life insurance calculator, learn more about the best term life insurance or best whole life insurance in Canada, or check out the ratings below.

Term Life Insurance Company Rating
Assumption Life ★★★★★
Beneva ★★★★
BMO Insurance ★★★★★
Canada Life ★★★★
Canada Protection Plan ★★★★★
CIBC Insurance
Desjardins ★★★★
Empire Life ★★★★★
Equitable Life ★★★★
Foresters Financial ★★★★
Humania ★★★★
Industrial Alliance (iA) ★★★★★
ivari ★★★
Manulife ★★★★★
RBC Insurance ★★★★★
Sun Life ★★★
Wawanesa ★★★★

Should I get life insurance for my children?

As a parent or grandparent, there are benefits to purchasing a life insurance policy for your child or grandchild. Life insurance for children ensures future insurability for your child, regardless of health issues. The policy also offers an effective way to build wealth and can be an attractive alternative to Registered Education Savings Plans (RESPs).

Do you need insurance to travel to Canada?

Certain visas that allow for travel or stays in Canada do require insurance coverage. Super visa insurance is mandatory for those seeking approval for their super visa status. While other visitors to Canada need insurance, it is not mandatory for entrance into the country.

Need help?

Call us at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

What does life insurance cover?

Life insurance provides a death benefit to your beneficiaries, which is typically tax-free. It can cover expenses such as funeral costs, outstanding debts, income replacement, education costs, and estate taxes, helping to ensure financial stability for your loved ones.

How does a term life insurance policy work?

A term life insurance policy offers coverage for a specific period, such as 10, 20, or 30 years. If the insured dies during this term, a death benefit is paid to the beneficiaries. If the term ends and the insured is still alive, the policy expires unless renewed or converted to a permanent policy.

How does life insurance payout work?

When a policyholder dies, beneficiaries file a claim with the insurer, providing a death certificate and policy details. Once the claim is approved, the insurer pays out the death benefit, usually as a lump sum, though other payout options may be available.

Why life insurance?

Life insurance ensures your loved ones are financially protected if you pass away. It helps cover living expenses, pay off debts, fund education, and manage estate planning, providing financial security for your family.

How to use life insurance while alive in Canada?

In Canada, permanent life insurance policies can offer access to cash value through loans or withdrawals. Some policies may also include riders for terminal or critical illnesses. You can also surrender the policy for its cash value, though this will end the coverage.

What are the tax implications of life insurance in Canada?

In Canada, life insurance death benefits are generally tax-free for beneficiaries. Permanent policies with cash value grow tax-deferred, but withdrawals or loans may be taxable if they exceed the premiums paid.

Employer-paid group life insurance is considered a taxable benefit to employees. If owned personally, life insurance bypasses probate, but corporate-owned policies may have tax implications.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is critical illness insurance & How does it work in Canada?

Each year, thousands of Canadians are diagnosed with serious health conditions like cancer, heart attack, and stroke—life-altering events that bring unexpected financial challenges, from higher expenses to lost income to lifestyle adjustments.

Critical illness insurance provides financial protection during these difficult times through a lump sum payment upon diagnosis of a covered condition. In this post, we’ll explore how critical illness insurance works and help you decide if it’s a worthwhile investment for your future.

What is critical illness insurance?

Critical illness insurance is an agreement you make with a life insurance company that they will pay you a tax-free lump-sum of money if you…

  • develop a life-threatening illness
  • have a serious health event
  • or undergo treatment while under their coverage

Unlike life insurance, the payout doesn’t happen after you die. It’s a living benefit you receive while you are alive to help with immediate financial burdens of a critical illness. You get the payout once proof of a specified illness or incident is established (barring any policy waiting period).

How does critical illness insurance work?

Critical illness insurance (also known as CI insurance) works by offering financial support should you or your family member be diagnosed with a serious illness such as cancer, heart attack, or stroke.

Just like with life insurance, you’ll be required to pay monthly premiums over the course of your term length to maintain that protection. Both the amount of the benefit and the monthly payments are decided when you apply for the policy.

During your policy term, if you are diagnosed with a critical illness, you submit a claim that includes your official diagnosis documentation. Then the insurance company pays you the benefit.

How does critical illness insurance work?

*Subject to waiting period

Is critical illness insurance taxable?

No, the lump sum payment received from a critical illness insurance policy is generally tax-free in Canada. This tax-free benefit helps policyholders use the payout for necessary expenses without worrying about deductions. However, exceptions apply if the policy is owned by a business and premiums were deducted as a business expense.

Common uses for critical illness insurance

The payout (or benefit) from a critical illness insurance policy can help replace lost income, support personal and family needs, and pay a mortgage and other loan payments.

Let’s look at the different ways to use a critical illness insurance benefit:

Income

Replacing income

For you or your family to take time off work.

Debt

Debts

Mortgages, business loans and other liabilities.

At home care

At-home care

Hiring nurses or other home-care practitioners.

Medicine

Prescription medicine

Out-of-pocket expenses not covered by provincial plans

Enhanced care

Enhanced care

Upgraded medical facilities and services

Medical device

Modifications

Renovations or modifications to your home, car, or other household expenses

Treatment

Additional treatment

Out-of-country or alternative medical expenses

Protection

Savings protection

Eliminate the need to use retirement savings

What illnesses are covered by critical illness insurance?

Critical illness insurance in Canada covers over 30 life-threatening conditions, including cancer, heart attack, kidney failure, and stroke. These conditions are selected because they often involve high medical costs and lifestyle changes that impact your ability to work.

Here’s a list of conditions usually covered by critical illness insurance:

Basic critical illness coverage

  • Cancer
  • Heart attack
  • Stroke

Enhanced critical illness policy coverage

  • Acquired Brain Injury
  • Aortic Surgery
  • Aplastic Anemia
  • Blindness
  • Bacterial Meningitis
  • Cancer
  • Coma
  • Coronary Artery Bypass Surgery
  • Dementia, including Alzheimer’s Disease
  • Deafness
  • Heart Attack
  • Heart Valve Replacement or Repair
  • Kidney Failure
  • Loss of Independent Existence
  • Loss of Limbs
  • Loss of Speech
  • Major Organ Failure on Waiting List
  • Major Organ Transplant
  • Motor Neuron Disease
  • Multiple Sclerosis
  • Occupational HIV Infection
  • Paralysis
  • Parkinson’s Disease
  • Severe Burns
  • Stroke (Cerebrovascular accident)
Critical illness insurance coverage list

What is partial payout in critical illness insurance policies?

A partial payout allows you to receive a portion of your critical illness insurance benefit if you’re diagnosed with an early-stage or less severe covered condition.

Partial payment details:

  • The specified illnesses will be made clear to you before your coverage begins
  • Often non-life-threatening cancers fall into this category
  • This clause allows you to receive some money (typically between 10-25 percent of your coverage amount and is subject to dollar value limits) during your recovery
  • You can maintain your protection should you contract a terminal condition down the road

The conditions eligible for partial payment vary from company to company.

Some conditions eligible for partial payout are:

  • Early thyroid cancer
  • Early prostate cancer
  • Stomach tumours
  • Superficial skin cancers
  • Ductal breast cancers
  • Coronary angioplasty

Can I receive multiple critical illness insurance payouts if I am diagnosed with multiple conditions?

Yes. It is possible to receive multiple payouts on a critical illness insurance policy for partially critical conditions. However, coverage only pays out once in its entirety for fully critical conditions. The amount of times you can claim partial conditions depends on your policy wording.

How much does Critical Illness Insurance cost?

Get instant quotes from Canada's top critical illness insurance providers and find the perfect coverage for your family.

$100K

How much does critical illness insurance cost?

In general, you can expect to pay anywhere from $21-70 per month for critical illness insurance. On average, it’s more expensive than term life insurance but not so expensive that you can’t afford it. Just like life insurance, the younger and healthier you are, the less expensive your critical illness insurance premium is.

Coverage amounts are smaller than what you’d see for a life insurance death benefit, so that also helps keep premiums low. Canadians typically elect for an average critical illness coverage of $77,000 according to the Canadian Society of Actuaries.

Other factors that can affect the cost of premiums include:

  • your term length
  • the number of conditions covered by your policy
  • any riders or clauses you opt for
  • smoking status

Critical illness insurance riders

Some companies allow you to add riders to a critical illness insurance policy that can add coverage or return your premiums. With some policies, you may be able to choose the number of illnesses covered as well as the amount of coverage and the term length of the rider. Critical illness riders typically have a 30 day survival period that needs to be completed, before the policy can pay out the proposed benefit of the rider.

Child critical illness rider

A Child Critical Illness rider provides coverage for the insured’s children if they are diagnosed with a childhood illness. The exact list and number of illnesses covered vary across insurers.

Return of Premium on Death rider or Expiry rider

A Return of Premium on Death or Expiry rider returns all or a part of the premiums one has paid over the course of their policy when the policy term ends or when the individual passes away.

Is critical illness insurance worth it?

Yes, critical illness insurance is worth the money. Critical illness insurance is protection you buy to protect you and your family from the financial fallout that happens if you get critically sick. If you want the financial freedom to recover from a serious illness on your own terms, then you need this type of insurance.

Because critical illness insurance pays a living benefit, getting coverage is even more of a personal decision than life insurance. Life insurance is really about your family’s needs. Critical illness insurance is about your financial needs while you recover.

Look at the stats: 

  • 1/2 of Canadians will be diagnosed with cancer in their lifetime
  • The average out-of-pocket expenses for cancer in Canada is around $400 a month. This excludes treatment covered by public or private health care and can be more depending on the type of cancer
  • When you’re diagnosed with cancer, you’ll likely have to take time off work to recover

So, can you afford to take time off work, cover your usual bills, plus at least $400 a month to pay for your treatment/recovery? If you can’t, critical insurance is worth it.

Buying this insurance can give you the peace of mind to know, that if you’re facing a critical diagnosis, you’ll be able to focus completely on recovery.

Learn more about whether critical illness insurance is worth it.

Advantages Disadvantages
Financial protection for your family More expensive than life insurance
Flexibility in how benefit is used Some companies only offer basic policies
Premiums can be returned if there are no claims
Ability to get coverage as a rider or separate policy

Cancer and heart disease are common critical illnesses in Canada.

Can I get life insurance and critical illness insurance together?

Yes, many Canadian insurance companies offer life insurance and critical illness coverage together. You can add critical illness coverage as a rider to your life insurance policy. This can help you apply for both life insurance and critical illness coverage at the same time without having to go through underwriting again.

Learn more about critical illness insurance versus critical illness riders.

How much critical illness insurance coverage do I need?

In general, Canadians commonly purchased between $50,000 and $100,000 in coverage or more.

Because the coverage pays a living benefit, it’s intended to cover a shorter period of time, specifically while you are treating and recovering from an illness. Hopefully, your recovery will be swift, and you wouldn’t be reliant on the money paid out by your policy for the remainder of your life.

If you’re unsure how much coverage you want, an insurance calculator can suggest a coverage amount based on your estimated needs and give you an estimate of the monthly expenses associated with the policy.

Learn your coverage needs with our critical illness insurance calculator.

Which are the best critical illness insurance companies in Canada?

We reviewed the top companies offering such policies so you can make an informed decision on your critical illness insurance provider. Companies like Canada Protection Plan (which allows credit card payments), Sun Life, Canada Life, BMO Insurance, and more offer critical illness benefits in Canada.

Read more about the best critical illness insurance companies in Canada.

How can I get my critical illness insurance quotes?

Still have questions? Schedule a chat with a licensed insurance agent from PolicyAdvisor.  They’re happy to go over anything you’re curious about and provide you with many quotes from the best insurance companies in Canada. Save time and money when you speak to our brokers, form your life insurance plan, and compare quotes online.

Insurance can be affordable

Find the lowest critical illness insurance quotes in Canada within minutes!

Frequently asked questions

How often do critical illness insurance payout?

On average, about 80 percent of critical illness insurance claims are approved, and this percentage continues to rise. Approval rates vary by provider, which is why you should research different companies and understand their coverage definitions and waiting periods before purchasing a policy.

Which three illnesses are covered under most critical illness policies?

Cancer, heart attack, and stroke are covered under most basic critical illness insurance policies. Enhanced policies may include up to 26 conditions or more.

How much is the maximum coverage for critical illness?

The maximum amount of coverage offered by Canadian critical illness insurance providers is $3 million. Usually, Canadians get $50,000 – $100,000 in critical illness coverage.

Do you need critical illness or disability insurance?

You need both critical illness insurance and disability insurance to fully financially protect yourself from injury or illness. They are two different insurance products. Critical illness insurance will pay you a lump sum payment if you are diagnosed with a critical illness.

Disability insurance will replace a portion of your income if you are sick or injured and cannot work. Both products will help ensure your family is financially taken care of if you become very sick.

Can I be refused critical illness coverage?

The average Canadian resident should have their application accepted depending on their history. However, you can be refused or denied coverage by the insurance carrier you applied to.

You and your family’s medical history will factor heavily into the underwriting process. If you have already been diagnosed with an illness, or have pre-existing conditions your likelihood of being insured or availability of coverage options may be reduced.

Will I get my money back if I do not claim on my critical illness policy?

Yes, some critical illness policies allow for a return of premium. Some insurers will return all of the premiums you’ve paid if you haven’t made a successful claim at the end of your term, hit certain age milestones, or surrender your policy.

This is an optional clause and it will increase the cost of premiums.

There’s also a return of premium on death clause, which means your premiums will be paid back to your chosen beneficiary should you pass away unexpectedly, without receiving a full benefit payment under your critical illness policy.

Do you have to spend a critical illness insurance payout on treating your illness?

No. You only need to be diagnosed with a covered condition to receive your critical illness insurance benefit. The tax-free payment can be used however you choose—whether for medical expenses, replacing lost income, supporting family needs, hiring care providers, or seeking treatment abroad.

What is the survival period in critical illness insurance?

In order to get your payout,  you must pass the 30-day survival period after your diagnosis. This waiting period is consistent across most insurance companies and covers most types of diseases. Some companies now permit a zero-day survival period for certain conditions.

If I get better, do I have to return the benefit?

You do not have to give back your critical illness payout if you recover from the covered medical condition. Critical illness plans are not defined by recovery, treatment, or death. It is a one-time payment that is triggered by the diagnosis of specific diseases or conditions.

Critical illness insurance coverage differs from other types of insurance in that it is a living benefit that pays out a one-time lump sum.

  • Term life insurance – pays out after your death
  • Long-term care insurance –  pays for assistance for those who can no longer take care of themselves
  • Disability insurance – pays out monthly if you cannot work due to an illness or disability
  • Critical illness insurance – pays out a one-time lump sum when you are diagnosed with a life-threatening illness or disease
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Understanding Mortgage Insurance in Canada: A Complete Guide

Homeownership can be overwhelming, especially when it comes to understanding the various financial products involved. Among these, mortgage insurance is a critical component that can significantly impact your home-buying experience and financial security.

Whether you are a first-time homebuyer or looking to refinance your existing mortgage, understanding mortgage insurance is essential. So, this comprehensive guide to mortgage insurance in Canada will break down everything you need to know.

We will explore the types of mortgage insurance available, their benefits and drawbacks, the costs involved, and how they can affect your homeownership journey.

What is mortgage insurance?

In Canada, mortgage insurance is a financial protection product otherwise known as creditor insurance. It is typically offered by your mortgage lender. In the unfortunate event of your death, if your mortgage is still outstanding, mortgage insurance pays the debt you owe to your bank for your mortgage loan.

An example of how mortgage insurance works

Let’s say you are purchasing a house for $100,000.

  • You pay a 15% down payment ($15,000).
  • The amortization period is 25 years.
  • Leaving an $85,000 mortgage loan that you need to pay off over the next 25 years.

If you die within this 25-year period, your lender still expects to be paid back. Without this insurance, your family or your estate will need to come up with $85,000 by dipping into their savings or selling the property to settle the mortgage loan.

Mortgage insurance ensures that the mortgage loan is paid off in these circumstances. This kind of insurance is sometimes referred to as mortgage life insurance or private mortgage insurance.

Read our full review of the Best Mortgage Insurance Companies in Canada

What are the types of mortgage insurance?

There are three main types of mortgage insurance in Canada, 

  • Mortgage default insurance
  • Mortgage loan insurance
  • Optional mortgage protection insurance

Mortgage default insurance

Mortgage default insurance is mandatory coverage in Canada for homebuyers with a down payment of less than 20%. This insurance protects lenders in case the borrower defaults on their mortgage. 

For example, if you buy a house for $400,000 with a 5% down payment, mortgage default insurance reduces the lender’s risk and lets you secure a mortgage despite the smaller downpayment.

Mortgage loan insurance

Mortgage loan insurance, also known as CMHC insurance, works like mortgage default insurance, protecting lenders against the risk of borrower default. This insurance allows buyers to secure a home loan with a smaller down payment. 

For instance, if you put down 10% on a $500,000 home, mortgage loan insurance safeguards the lender, making it easier to obtain mortgage approval in the Canadian housing market.

Optional mortgage protection insurance

Optional mortgage protection insurance is an additional policy that homeowners in Canada can purchase to enhance their financial security. This insurance provides support to cover mortgage payments in case of unforeseen events such as disability, critical illness, or death.

For example, if the primary breadwinner in your family becomes critically ill, this insurance can help cover the mortgage payments, ensuring your family can maintain their home without facing financial hardship.

Benefits of mortgage insurance

Mortgage insurance has several advantages, like:

  • Financial security for lenders: Mortgage insurance, whether mandatory or optional, protects lenders. It reduces the risk of borrower default so that lenders can recover their funds even if the borrower is unable to continue making payments
  • Enables homeownership with lower down payments: Mortgage insurance makes homeownership accessible to more Canadians by allowing for smaller down payments. Without this insurance, many potential buyers would need to save for a much larger down payment, delaying their ability to purchase a home
  • Access to competitive mortgage rates: With mortgage insurance, lenders face reduced risk, which can result in lower interest rates for borrowers. This can lead to significant savings over the life of the mortgage and make homeownership more affordable
  • Stability in the housing market: Mortgage insurance contributes to the stability of the Canadian housing market by protecting lenders from widespread defaults. This stability can help prevent housing market crashes and maintain overall economic health
  • Stabilizes the housing market during economic downturns: During economic downturns, mortgage insurance plays a crucial role in stabilizing the housing market. By protecting lenders, it helps prevent a surge in foreclosures and supports market stability
  • Flexibility for borrowers: Mortgage insurance provides flexibility for borrowers to purchase a home sooner with a lower down payment. This flexibility can be crucial for first-time homebuyers or those looking to upgrade to a larger property
  • Enhanced borrower qualifications: With the protection of mortgage insurance, lenders are often more willing to approve borrowers who may not meet traditional lending criteria. This can include individuals with lower credit scores or those with less established credit histories

Drawbacks of mortgage insurance

While mortgage insurance comes with several benefits, it also has a few drawbacks:

  • High costs and added interest on premiums: Premiums can be high, and if added to your mortgage balance, you’ll pay interest on them over the life of the loan, raising the total amount paid
  • Impact on home equity: Premiums added to your loan balance can slow the rate at which you build equity in your home
  • Provincial sales tax requirements: In some Canadian provinces, mortgage insurance premiums are subject to provincial sales tax, increasing the overall cost
  • Long-term cost: While enabling homeownership sooner, the long-term cost of paying premiums over several years can be substantial

Key differences in insurance types

Mortgage Default Insurance vs. Mortgage Protection Insurance

Here’s how mortgage default insurance and mortgage protection insurance differ:

Feature Mortgage Default Insurance Mortgage Protection Insurance
Purpose Protects the lender in case the borrower defaults on the mortgage Protects the borrower by covering mortgage payments during unforeseen events like illness, disability, or death
Mandatory/optional Mandatory for down payments less than 20% Optional
Who it protects Lender Borrower and their family
When it’s required Required by lenders for high-ratio mortgages Can be purchased at any time by the homeowner
Cost Added to the mortgage and can increase monthly payments Separate premium paid by the homeowner
Coverage Covers the lender’s loss in case of default Covers mortgage payments or remaining balance upon certain conditions
Benefit payout Paid to the lender Paid to the borrower or their family
Eligibility Based on the down payment amount Based on the borrower’s health and risk factors
Tax treatment Premiums are not tax-deductible Premiums may be tax-deductible under certain conditions

To learn more about how mortgage default insurance works and how much it costs, head to our CMHC Mortgage Default Insurance Calculator.

Is mortgage loan insurance the same as mortgage protection insurance?

No, mortgage loan insurance and mortgage protection insurance are not the same. Mortgage loan insurance is mandatory for homebuyers who make a down payment of less than 20%.  Mortgage protection insurance is optional. Here are some of the key differences between the two:

Mortgage Loan Insurance

  • Often referred to as CMHC insurance, mortgage loan insurance is mandatory  for homebuyers who make a down payment of less than 20% of the home’s purchase price
  • This insurance protects the lender against the risk of borrower default. It ensures that the lender can recover their funds even if the borrower is unable to continue making mortgage payments 
  • The cost of mortgage loan insurance is typically added to the mortgage amount, which can affect monthly payments and the overall cost of homeownership

Mortgage Protection Insurance

  • It is an optional policy that homeowners can purchase to protect themselves and their families
  • This insurance provides coverage in case the homeowner experiences a critical illness, disability, or death 
  • The benefits of mortgage protection insurance are paid directly to the borrower or their family, helping to cover mortgage payments or pay off the remaining balance
  • Unlike mortgage loan insurance, mortgage protection insurance is not required by lenders and serves to offer additional peace of mind and financial security to the homeowner
Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Do I need to buy mortgage insurance?

No, mortgage insurance is not mandatory to qualify for your mortgage. But your lender making it seem like it is. That’s because it protects them—not you.

However, it is smart to consider protecting the outstanding balance of your mortgage. A term life insurance policy that matches your mortgage term is a cost-effective way to protect your mortgage debt.

Read more about if life insurance is mandatory to qualify for a mortgage.

Mortgage insurance alternatives

Term life insurance can provide the same security as traditional mortgage insurance. This alternative is referred to as mortgage protection insurance. It is usually a more affordable option and provides more flexible coverage.

How to cover a mortgage debt with life insurance

Protecting a mortgage with life insurance works by getting term life insurance that is in force during the amortization period of your mortgage.

Your beneficiaries are entitled to a tax-free death benefit that never reduces and can be applied to whatever they choose through mortgage protection insurance.

Private mortgage insurance, as it is sometimes called, offers the same security throughout the riskiest years of your mortgage loan, with several additional benefits not offered by conventional loan insurance:

  • You can get coverage well beyond the amount of your mortgage balance
  • You get to pick your own beneficiary, instead of paying for insurance to protect the lender

Learn more about mortgage protection through term life insurance.

Mortgage insurance vs term life insurance – which is better?

While mortgage insurance pays off one’s mortgage in the event the borrower dies, other products can do a better job at protecting a mortgage debt.

A term life insurance policy can offer you better mortgage protection in a number of ways:

  • The policyholder chooses the beneficiary
  • In turn, the beneficiary can choose exactly how the benefit is used
  • The benefit can go towards paying off the mortgage and/or other uses, like servicing other debts or handling final expenses

Learn more about mortgage insurance versus life insurance.

mortgage versus life insurance

How much mortgage insurance do I need?

How much mortgage coverage you need depends on the value and cost of your home and several other facts. Unfortunately, you don’t get much of a choice if you go through your lender – the coverage amount is tied to the value and term of your mortgage loan.

However, life insurance allows you to cover your mortgage loan balance and many other financial needs, including:

  • child care
  • education costs
  • your family’s future living expenses
  • funeral expenses
  • anything your beneficiaries wish

Our insurance calculator can help you find out exactly how much coverage you need.

Learn more about how much life insurance you need.

How much does mortgage insurance cost?

The cost of mortgage insurance can be 2-4 times as much as a term life insurance policy. In the below table, you can see just how affordable term insurance can be.

Coverage 10-Year Term 20-Year Term
$250,000 $11/month $14/month
$500,000 $15/month $22/month
$1,000,000 $24/month $35/month

*Premium payments for female, non-smoker, 30-years old

Why is mortgage insurance expensive?

Lender-provided mortgage insurance is expensive because there is no underwriting. Underwriting is the process an insurance company goes through to determine the appropriate fees for taking on the financial risk of your death.

Without this stringent evaluation process, they are more blindly taking on the financial risk of your policy paying out.

Read more about why mortgage insurance is so expensive.

Where do I get mortgage insurance?

You can only get mortgage insurance from the lender who provided your mortgage loan.

However, term insurance is available from several companies nationwide and the expert advisors at PolicyAdvisor have reviewed them all. We can help you find the best provider to protect your mortgage and make insurance part of your financial plan. Contact us below for advice on protecting your foray into the real estate market, or other needs like critical illness insurance or disability coverage.

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

How long does it take to get an insured mortgage?

It generally takes anywhere from a few days to a couple of weeks to get an insured mortgage in Canada. However, the duration can vary depending on several factors, such as the lender, the complexity of your financial situation, and the completeness of your application. 

Why is mortgage insurance often considered expensive?

Mortgage insurance is often considered expensive because it adds a significant cost to your mortgage payments. The premiums for mortgage loan insurance are typically added to your mortgage balance, which means you pay interest on them over the life of the loan. Additionally, if you choose to pay the premiums upfront, it can be a substantial amount that makes homeownership more expensive.

Can I cancel my mortgage insurance?

In most cases, you can cancel your mortgage loan insurance once you have paid down your mortgage to less than 80% of the home’s value, meaning your loan-to-value ratio is less than 80%. However, if you have opted for optional mortgage protection insurance, you can typically cancel it at any time, but this will depend on the terms of your policy.

How are mortgage insurance premiums calculated?

Mortgage insurance premiums are typically calculated as a percentage of your loan amount. For mortgage loan insurance, the premium rate varies based on the size of your down payment and the loan-to-value ratio. 

For example, the premium might be higher for a smaller down payment. Optional mortgage protection insurance premiums are based on factors such as your age, health, and the amount of coverage you choose.

Is mortgage insurance a one-time payment?

No, mortgage insurance, typically offered by your lender, is not a one-time payment. It is generally included in your monthly mortgage payment and can only be canceled once you reach 20% equity in your home.

Do you have to pay mortgage insurance up front?

Yes, you can pay your entire mortgage insurance premium upfront, especially if you have sufficient funds to cover the downpayment, premium expenses, and other initial costs. Paying your mortgage insurance premium upfront can help lower your monthly mortgage payments.

What age does mortgage insurance end?

In Canada, mortgage insurance, also known as mortgage life insurance or private mortgage insurance (PMI), automatically ends when you reach the age of 70.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

The Canadian guide to travel insurance for students

There’s no denying that travel can be a great experience for students. It broadens horizons, introduces new cultures, and can be a great way to learn more about the world. However, it’s important to remember that travel can also be dangerous.

Accidents happen, and sometimes they can lead to serious injuries or even death. That’s why it’s so important for students to have travel insurance.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is travel insurance?

Travel insurance is a type of insurance that helps to cover the cost of medical care if you become sick or injured while travelling. It can also protect you from financial loss if you experience a trip interruption or cancellation.

Emergency medical and dental treatments are expensive in Canada, and as an international student, you likely won’t be covered by provincial healthcare. This means that if you experience an emergency, you could be responsible for a large medical bill and out-of-pocket expenses.

Likewise, for Canadian students travelling or studying abroad, it’s important to know that your provincial health plan likely doesn’t extend to other countries.

Learn more about travel insurance.

What types of students need travel insurance in Canada?

Travel insurance for students can mean many different things depending on your home country and reason for travel. They can include:

  • International students studying in Canada
    Students from outside of Canada who come to the country to study are not covered by a provincial or territorial government health insurance plan.
  • Canadian students studying in another country
    When Canadians travel outside of Canada, they do not retain access to public healthcare options in other countries. Many schools require students hold a medical insurance plan before they begin classes.
  • Canadian students travelling abroad
    Many students are afforded the opportunity to travel internationally in the summer months or even when they complete their degree or program. Emergency medical coverage is also important in these circumstances.

Why do Canadian students need travel insurance?

If you are a student and plan to travel outside Canada ‒ even for a single day ‒ you should buy travel health insurance before your trip or vacation.

There are a number of risks students face when travelling, and travel coverage can help protect them from financial loss in the event of an emergency. If you need medical assistance while abroad, insurance can help cover the cost of your medical bills or return back to Canada if necessary.

Travel insurance is an important consideration for any trip, and it’s especially important if you’re travelling for months on end to a country with higher costs for medical treatments.

Why do international students studying in Canada need travel insurance?

Your trip to Canada is meant to be an experience. If an unexpected medical emergency for visitors to Canada occurs, it can cost you thousands of dollars per day in medical expenses that are not covered by Canada’s public healthcare system.

Travel medical insurance can relieve that potential financial burden and give you peace of mind during your stay, knowing you are covered for any unexpected medical expenses.

Check our our review for the Best Visitor Insurance for International Students in Canada
There are many different types of Travel Insurance for students, foreign workers, snowbirds, super visa holders, and others travellers to/from/within Canada.

What should travel medical insurance cover for students?

Every travel medical insurance policy for visitors is unique, as one has many options when applying for coverage. The main benefits a student should consider are coverage for emergency medical services (including dental), medical transportation, and repatriation (the transportation of your body should you pass away outside of your country of origin).

Most travel medical insurance policies typically cover:

  • Emergency medical treatment for illness or injury
  • Hospital expenses
  • Prescription medications
  • Emergency dental services
  • Essential medical equipment (crutches, wheelchairs, slings, braces, etc.)
  • X-rays and other diagnostic services and laboratory procedures (bloodwork, ultrasounds, etc.)
  • Required ground, air or sea ambulance services
  • Follow-up post-medical appointments
  • Medical evacuation
  • Ambulance travel to the nearest hospital

Student travel medical insurance policies may cover additional non-emergency medical benefits:

  • Annual medical exams
  • Eye exams
  • Dental exams and cleaning

Lastly, student travel policies often include a modest accidental death or dismemberment benefit to be paid out to oneself or a beneficiary should they become dismembered or lose their life, respectively.

travel insurance for students

Does student travel insurance cover pre-existing conditions?

Most student travel medical insurance policies do not cover a pre-existing medical condition by default. Given the relatively young age of most applicants, pre-existing conditions are not the top concern for students applying for coverage.

However, if you are a student with a pre-existing medical condition, securing coverage that takes your medical condition into account is incredibly important. If your condition is stable, it is typically easier to secure coverage.

In many cases, if you have shown no symptoms or diagnosis of a pre-existing medical condition for 90 to 180 days prior to the effective date of the policy and have not had treatment for the condition during that time, it will not be considered a pre-existing condition during your coverage period.

You should always check the wording of any potential policy for details and to see if your medical condition would be covered during trips outside of your home country.

Some conditions may get excluded from your travel medical insurance coverage during the underwriting process. A pre-existing condition exclusion could include:

They can also include relatively mild conditions for which you have taken prescription medication such as:

Insurance providers will look at the specific state of your illness or condition to evaluate the risk associated with the pre-existing condition. They then make their decision accordingly for your travel insurance plan.

Some providers offer policies that will cover pre-existing conditions, though the premium will be higher to compensate for the added risk.

One should request an explanation of the limitations and restrictions on any pre-existing medical condition, tests, and treatments they may have had.

Frequently Asked Questions

Which is the best travel insurance company for students?

The best travel insurance company is the one that best suits your needs. Several Canadian insurance companies offer policies specifically catered to students. Providers construct their policies differ from one another, thus each trip may have a best-suited policy from a unique provider. Some of these providers include:

Manulife

  • Offers up to $2 million CAD in coverage
  • Non-emergency medical benefits are included in coverage, including annual medical and eye exams
  • Accidental death or dismemberment also included; including accidents resulting in death, blindness or dismemberment
  • Free Assitance Centre; 24/7 helpline which can help you answer questions about your trip before or after departure

Tugo

  • Offers up to $2 million CAD in coverage
  • Offers coverage for medical expenses incurred by students enrolled in a school in Canada and Canadian students enrolled in a school outside of Canada
  • Non-emergency medical benefits are included in coverage, including annual medical and eye exams, as well as maternity care

Allianz

  • Specific policies for international students studying in Canada
  • Offers up to $5 million CAD in coverage
  • Coverage lasts up to a full year after student has completed studies and works in Canada
  • Option to add spouse and dependents to policy
  • In our review of the Best Travel Insurance for Visitors to Canada, we recommend Allianz as the best choice for international students in Canada

MHS International

  • Specific policies for international students studying in Canada
  • Offers up to $2 million CAD in coverage
  • Three different coverage tiers: Silver, Gold, and Platinum with increasing benefit amounts as you move up
  • Policy offers coverage outside of Canada as long as majority of stay is in Canada (except USA; 30 days coverage only)

Destination Travel Group

  • Offers up to $2 million CAD in coverage
  • Coverage for both students enrolled in a school in Canada and Canadian students enrolled in a school outside of Canada
  • Maternity coverage of up to $25,000 for pre-natal care and involuntary termination of pregnancy or complications
Compare and save
Save money and time when you compare multiple travel medical insurance policies, only with PolicyAdvisor
GET QUOTES

Do students need travel insurance plans if they have credit card coverage?

While credit card coverage is a great add-on, the coverage is often limited. This is especially true considering the extended trip length many students take.

Credit card travel plans provide basic travel coverage, but they have a limited coverage period. As well, it is often only in force if your trip was purchased with the same credit card, and the extended time a semester abroad takes would disqualify coverage in most cases.

Learn more about credit card travel insurance and its limitations.

Can I get coverage through my student union?

Many university and college student unions offer group coverage for students while they attend studies at their respective schools, and include the fees for coverage alongside tuition. While this is an option for international students on each side of the border, the period of coverage for these plans is only in effect while you are enrolled in studies. They rarely offer the flexibility or breadth of coverage an independently owned plan can offer.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much does disability insurance cost?

Disability insurance is an important part of your insurance portfolio, along with life and critical illness insurance. If you can no longer work due to an injury or illness, disability insurance provides you a living benefit—it’s income replacement for when you’re down and out. 

So, what’s it going to cost you? There are different types of disability insurance, different cost influencers, and even employer benefits to consider. We’re here to demystify how much disability insurance can actually cost, looking at what the insurance covers, how much you can expect to pay in premiums, and why it’s worth it!

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What are the different types of disability insurance?

Before we dive into the numbers, let’s define the types of disability insurance available to you.  There are two main types of disability insurance you should know about: short-term disability and long-term disability coverage. The two are not mutually exclusive, as long-term disability insurance usually follows short-term coverage.

Short-term disability insurance (STD) is a policy that temporarily covers the loss of income due to accident or illness. Short-term disability…

  • Provides coverage for short periods of time, typically 1-6 months
  • Some policies may extend coverage for up to a year  
  • Usually offered by employers to their workers, with coverage extending from 70-100% of your income

Long-term disability (LTD) provides protection from loss of income for longer-lasting health problems. Long-term disability…

  • Kicks in after the short-term coverage period has ended
  • Has a variable coverage period depending on the policy in question
  • Typically covers 2-10 years, or up until retirement age (65 years)
  • Coverage usually from 50-70% of income
  • Is most commonly claimed for longer duration mental health afflictions or physical health concerns (cancer treatment, musculoskeletal issues and injuries from accidents, etc to name a few)

Often, short-term disability insurance plans are integrated with long-term disability, providing coverage during the LTD waiting period. The waiting period (aka Elimination Period) is the period of time between the start of your disability and the start of the benefit payment period. During the waiting period, you are paying for your needs out-of-pocket. Most long-term disability policies will allow waiting periods of 30, 60, 90, 120, 180, and 365 days, although 90 or 120 days is the most commonly selected period. 

The longer your waiting period the lower your premium. Why? Most disabilities are resolved within the first few months (such as broken bones, back issues, short-term illnesses); the longer the waiting period, the less likely an insurer will have to start paying out on a claim.

the cost of disaiblity insurance for males and females

How much of your income does disability insurance cover?

If you lose the ability to work due to an illness or injury, short-term disability insurance will typically cover between 70% and 100% of your income, up to a maximum amount or until your coverage period expires.  After your short-term coverage and waiting period are up, Long-term disability income typically covers between 50-70% of your gross income.

It is also helpful to know that supplementing the disability coverage you get through employee benefits with an individual policy will not double your coverage: you will still only be entitled to the coverage you are eligible for based on your income level. In other words, insurance providers will coordinate so that your disability insurance income does not exceed what you are eligible for (usually a maximum of 80% of your income). 

That being said, if your employee disability insurance does not provide sufficient coverage, it may still be worthwhile to top up with a private policy or opt strictly for an individual policy where you get to determine coverage and premium plans.

Still looking for disability insurance rates?
PolicyAdvisor saves you time and money when comparing Canada’s top insurance companies. Check it out!
GET STARTED

How much does short-term disability insurance cost per month?

Like life insurance, where cost is partially related to the size of the benefit you buy, disability insurance coverage is also determined by other factors, like age, health status, and gender. However, the cost calculations differ in that the disability insurance benefits you receive every month is relative to your original income. 

Additionally, what is more likely to be influenced by the policy cost is how long your disability coverage lasts and how broad-reaching the definition of “disability” is. We’ll touch on this more below.

Many short-term disability policies are offered through employer benefits, meaning that employees pay little to nothing in premiums. Instead, the premiums are usually deducted directly from their paycheques, if any. 

Generally, the cost of an STD insurance policy is highly dependent on your salary. Because disability insurance pays out a portion (between 50% and 100%) of your income, premiums costs vary significantly. Among the cheapest options for short-term disability insurance are injury-only policies (which exclude illnesses) that can start around $10/month. However, it will truly depend on what your employer offers—your work may have set up a specific group rate with the insurance provider. For private policies, it’s best to get an individual quote based on your income replacement needs.

How much does long-term disability insurance cost per month?

Long-term disability premiums tend to range between 1% and 3% of your income, making it one of the most affordable and effective insurance products for income protection. 

Thus, a person making $40,000 (before taxes) can buy a long-term disability insurance policy for a monthly benefit of $2,500 per month for as little as $24/month (2 year benefit period) or $43 per month (coverage to age 65). At $100,000, premiums will be upwards of $80/month. In short, the higher the monthly benefit, the higher will be the premiums. However, there are of course other factors that contribute to the price as well (see the below chart). 

For individual plans, the cost will vary depending on policy length, coverage, and your insurance needs. Here is one example of what individual long-term disability insurance may cost.

How much does disability insurance cost?

We can only offer quotes for ages 18-60
Please select gender
Please select occupation
Please enter a valid annual income
Policy details
  • Benefit Amount: $3000/month
  • Occupation Class: Accountant – 4A
  • Age: 30
  • Status: Non-smoking
  • Waiting Period: 90 Days

Coverage Length Male Female
2 Years $29/month $53/month
Up to age 65 $51/month $95/month

If you have a long-term disability insurance policy through an employer, you will pay substantially less in monthly premiums. In the Government of Canada disability insurance plan, for example, the government covers 85% of the premium costs, while the insured employee pays the remaining 15%. For an employee earning $45,000, the employee’s monthly contribution is $15.75 per month. 

Some employers may offer long-term coverage in addition to short-term packages. However, it’s important to keep in mind some employer benefits have very strict definitions of disability, choosing to opt for the cheapest insurance plan to save them money. 

For example, many work plans choose an “any-occupation” definition of disability. This is the most stringent definition of disability that can be covered in a disability insurance policy. Under this type of policy, you may be ineligible to receive benefits if you can work in any other job. You may not even be working, but if you are deemed to be able to work, you will not be eligible for benefits under a policy with this definition.

How do insurance companies decide disability insurance premiums?

For an individual disability insurance policy, the cost of premiums varies depending on several factors, such as age, gender, health, smoking status, and occupation. Like most insurance policies, the risk to insurers increases the older a person is, as the possibility of getting a disability is higher and so premiums increase with age. 

Disability insurance cost

Where disability insurance premiums diverge from life insurance is when it comes to gender. While men tend to pay more in life insurance premiums, women can be subject to higher disability insurance premiums, due to a higher statistical filing rate and more expensive claims. 

According to insurer stats, women are more likely to take time off work due to disability. Health and occupation also factor in: medical history can influence private disability insurance rates as can having a higher risk job. For example, an office worker may have access to lower premiums than someone working with heavy machinery.

Of course, the type of policy also comes into play. Disability insurance policies with lower benefits and shorter coverage periods will have lower premiums than policies with higher benefits and longer coverage periods. 

The nature of the coverage is also important. For example, disability insurance coverage has three definitions of disability: “any occupation,” “regular occupation,” and “own occupation”. Any occupation coverage—the cheaper option—only pays out if the policyholder is unable to work at any job.  A policy with a “regular occupation” definition also protects your ability to work in your pre-injury occupation or one fitting your experience and level of education. Own occupation, by contrast, provides coverage if the policyholder is unable to work the job they have. This type of coverage, which pays out more frequently, is thus more expensive.

The last important cost influencer for long-term disability insurance premiums is the waiting period. Also known as the elimination period, the waiting period is the time between when you stop working and when the disability benefits kick in. During this period, you will either be covered by short-term disability insurance (which has short wait periods) or you will pay out of pocket. For an LTD policy, the length of a waiting period has an impact on the premiums you pay: a short waiting period (30-60 days) will have much costlier premiums than a longer waiting period (120-365 days).

Is a disability insurance benefit paid monthly?

Yes, unlike critical illness insurance which pays out a one-time lump sum, disability insurance issues monthly or bi-weekly payments. The reasoning is that the benefit payments mimic regular income earnings even if you are not able to work. The idea is that monthly disability payments will ensure stability and enable you and your family to maintain your cost of living prior to losing the ability to work. 

Depending on where your disability benefits are coming from (either individual or employer), they may or may not be considered taxable income. If you are receiving benefits through an employer who pays the policy premiums, your monthly disability benefit income will likely be taxable.

With an individual disability insurance policy—which are becoming more popular as employers cut back on benefits and people are increasingly self-employed—you are responsible for paying premiums to keep the policy active. One of the greatest advantages of individually-owned coverage is that the monthly benefits you receive are tax-free.

How much do you get paid out for disability insurance in Canada?

With short and long-term disability insurance, it is common to get paid out 50-100% of your income each month, depending on the type policy. 

In Canada, it is possible you will receive some income replacement if you become unable to work even without employer benefits or an individual disability insurance policy. For example, if you are eligible for employment insurance (EI), you may receive sickness benefits. These provide up to 15 weeks of coverage if you become unable to work for medical reasons. With EI sickness benefits the coverage is limited: it pays out up to 55% of your monthly income up to a maximum of $595/week or $2,380/month. For people making less than $30,000/year, this could be suitable for short-term disability coverage. Anything more, however, and it is probably a good idea to buy supplemental disability insurance. 

While EI sickness benefits are intended for short-term financial support, the Canadian government also offers a safety net for long-term disability through the Canadian Pension Plan (CPP) disability benefit. People with a long-term disability who are under the age of 65 and who have contributed enough to the CPP qualify for this benefit. However, this coverage is even more limited than EI with an average monthly amount of $1,031 up to a maximum of $1,413/month. If you qualify for this benefit and have private disability insurance, your private benefit will be adjusted to account for the CPP payment. 

Ultimately, it is a good idea to look into protecting yourself and your family financially should you lose the ability to earn an income. While it is unfortunate to think about, an accident or sudden diagnosis can upturn your life, not only affecting your health but also your ability to work and earn a living. Disability insurance provides a safety net in these cases, ensuring that you can focus on yourself and your loved ones during this time, rather than worry about how to make ends meet. In some cases, government benefits or employer benefits will be enough, but if you don’t qualify for these or have additional coverage needs, it is worthwhile to think about a private disability policy.

Who sells disability insurance?

Many insurance companies also sell disability insurance products, and there’s one quick, simple marketplace that lets you compare them all.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */