 1-888-601-9980
The best life insurance for millennials in Canada depends on your income, debts, dependants, mortgage, and long-term goals. For many people in their 20s, 30s, and 40s, term life insurance offers affordable protection for a mortgage, income replacement, and young children. Whole life insurance may be worth considering for lifelong coverage, estate planning, or supporting a dependant who will need permanent financial protection.
Quick view:
- Empire Life (5/5): Best for competitively priced whole life insurance
- Equitable Life (5/5): Best for participating whole life and good dividend history
- Manulife (5/5): Best for wellness rewards and comprehensive term coverage
- Canada Life (4.5/5): Best for flexible term lengths and permanent coverage options
- RBC Insurance (4.5/5): Best for customizable terms and income protection
- Beneva (4.5/5): Best for built-in extreme disability protection
Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.
Top 6 best life insurance companies for millennials in Canada
Based on PolicyAdvisor’s 2026 comparison, companies such as Manulife, Empire Life, and Canada Life offer greater flexibility, built-in benefits, and term life features that make them particularly suitable for protecting families and children.
Here’s an overview of the six best life insurance companies for millennials in Canada:
1. Empire Life: Best for competitively priced whole life insurance
Empire Life is an ideal choice for millennials seeking a permanent policy at competitive rates. The insurer offers EstateMax and OptiMax Wealth, two participating whole life insurance policies featuring guaranteed cash values, level premiums, and the potential for non-guaranteed policy dividends.
Empire Life’s EstateMax focuses on long-term death benefit and estate protection, while OptiMax Wealth focuses on earlier cash value accumulation. Both plans offer up to $20,000,000 in coverage, which is worth considering for leaving a legacy for children or grandchildren as well as tax-advantaged wealth transfer.
The insurer also offers the Solution Series Term life plans with ART, 10-, 15-, 20-, 25-, and 30-year term options, which can help policyholders align coverage with temporary outstanding debts or mortgage periods. Annual Renewable Term (ART) is a life insurance option offered by Empire Life that renews coverage annually without new medical underwriting, making it a seamless way to extend coverage.
Eligible policies may also offer a term exchange and term conversion privilege, offering enhanced flexibility for the future. The term exchange is available for Solution ART, Term 10, 15, and 20 before the seventh coverage anniversary, while the term conversion is available for all Solution Series term plans until the policy anniversary nearest the policyholder’s 75th birthday. Some plans also have a carry-over feature, where eligible term coverage is converted to permanent life insurance, while the rest continues as a term policy alongside the new policy.
The illustrative cost of Empire Life term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.89/month.
The illustrative cost of Empire Life participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $233.55/month.
- Best for: Competitively priced participating whole life and flexible permanent protection
- Plans: Solution Series, EstateMax, OptiMax Wealth
- Policy types: Term life and participating whole life
- Term lengths: Annual renewable term and 10, 15, 20, 25, and 30 years
- Permanent coverage: EstateMax offers 10-pay, 20-pay, and Life Pay; OptiMax Wealth offers 8-pay, 10-pay, 20-pay, and Life Pay
- Standout feature: Two participating whole life products with different cash-value priorities, alongside eligible term exchange and conversion options
2. Equitable Life: Best for participating whole life and good dividend history
Equitable Life is a strong choice for Canadian millennials seeking lifelong coverage alongside guaranteed cash value and the potential to earn non-guaranteed dividends. The insurer’s Equimax Estate Builder and Equimax Wealth Accumulator plans are permanent life policies with coverage of up to $25 million (without a special quote), making them worth considering for those seeking higher coverage amounts.
The Wealth Accumulator plan prioritizes higher early cash values within the first 20 years, while the Estate Builder plan prioritizes higher long-term value and estate planning. These plans can be suitable for millennials who want tax-advantaged wealth transfer or want to leave behind a legacy to cover potential final expenses. Equitable also has a long history of participating policy dividends, having credited dividends annually since 1936. However, these dividends are not guaranteed and are based on the insurer’s performance. The insurer’s dividend scale interest rate is 6.40% for July 2026 to June 2027.
In addition, eligible policyholders can combine permanent insurance with substantial term riders, helping policyholders avoid purchasing permanent coverage to protect temporary needs. This hybrid approach can work well for those seeking a comprehensive coverage strategy for temporary and long-term protection.
For millennials seeking temporary protection, the insurer’s Term 10, Term 20, and Term 30/65 plans allow families to secure substantial coverage for mortgages or other financial obligations that are expected to end after a period. Eligible Term 10 and 20 policies are guaranteed renewable and have a conversion feature. However, Term 10 and Term 20 can be converted up to age 71, whereas Term 30/65 can be converted only up to age 60.
The illustrative cost of Equitable Life term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.89/month.
The illustrative cost of Equitable Life participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $266.34/month.
- Best for: Participating whole life, guaranteed cash values, and dividend history
- Plans: Equitable Term 10, Term 20, Term 30/65, Equimax Estate Builder, Equimax Wealth Accumulator
- Policy types: Term life and participating whole life
- Term lengths: 10 years, 20 years, and 30 years or to age 65
- Permanent coverage: Equimax participating whole life with 10-pay (Equimax Estate Builder), 20-pay, and Life Pay options
- Standout feature: Long-standing participating dividend history and a choice between early cash-value accumulation and estate-focused whole life insurance
3. Manulife: Best for wellness rewards and comprehensive term coverage
Manulife is ideal for millennials looking for affordable term life coverage with benefits that reward wellness and healthy lifestyle habits. The Family Term plan offers coverage up to $20 million with variable term lengths: Term 10, Term 20, to age 65, and a lifetime premium option. In addition, eligible Manulife policies can also be converted from term to permanent coverage, making them a good option for those seeking future flexibility.
In addition to the standard term life policies, Manulife also offers Family Term with Vitality Plus, which offers a higher coverage amount of $25 million alongside health and wellness rewards with potential for savings on partner brands such as Amazon, Garmin, and HelloFresh. These savings and benefits can be ideal for millennials who prioritize healthy habits and fitness.
Millennials who want comprehensive coverage can consider Manulife Synergy, which is a 3-in-1 plan with life, disability, and critical illness insurance with one shared pool of coverage between $100,000 and $500,000. Synergy can also be converted to a permanent policy within 60 days of the policy’s expiry, making it ideal for future flexibility.
Meanwhile, Manulife Par offers participating whole life insurance with guaranteed cash values, potential dividends, and different premium payment periods, making it ideal for those looking for lifetime protection.
The illustrative cost of Manulife term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $11.13/month.
The illustrative cost of Manulife participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $331.71/month.
- Best for: Wellness rewards, family protection, and future insurability
- Plans: Family Term, Family Term with Vitality Plus, Manulife Par, Synergy
- Policy types: Term life and participating whole life
- Term lengths: 10 years, 20 years, to age 65, and lifetime-duration options
- Permanent coverage: Manulife Par offers 10-pay, 20-pay, and pay-to-age-90/100 options, depending on eligibility
- Standout feature: Manulife Vitality wellness rewards, optional guaranteed insurability, and children’s protection benefits
4. Canada Life: Best for flexible term lengths and permanent coverage options
Canada Life may suit millennials in Canada who want to customize their term life insurance alongside the option to convert to permanent life insurance later. The My Term plan has term lengths ranging from 5 to 50 years, making it easier to align coverage closely with outstanding debts or mortgages. Eligible policies can also be exchanged for longer terms or be partially or fully converted to a permanent policy.
The optional Guaranteed Insurability Rider in eligible Canada Life policies can be ideal for millennials who want to purchase a new permanent policy and increase their coverage later without worrying about their health and how it would affect their ability to get coverage.
In terms of lifetime coverage, Canada Life offers three participating whole life insurance policies: Wealth Achiever, Balanced Achiever, and Estate Achiever. Wealth Achiever focuses on stronger early cash values, while Balanced Achiever combines this with a potential long-term death benefit. Meanwhile, the Estate Achiever can aid in long-term estate planning for millennials who want to leave behind a legacy for their children and grandchildren.
The illustrative cost of Canada Life term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $12.36/month.
The illustrative cost of Canada Life non-participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $587.52/month.
- Best for: Flexible term lengths, future policy changes, and permanent coverage
- Plans: My Term, Wealth Achiever, Balanced Achiever, Estate Achiever
- Policy types: Term life and participating whole life
- Term lengths: 5 to 50 years
- Permanent coverage: Participating whole life with multiple guaranteed premium payment options
- Standout feature: Extensive term customization, eligible partial conversion, and three participating whole life plans for different financial priorities
5. RBC Insurance: Best for customizable terms and income protection
RBC Insurance is an ideal choice for millennials who want larger amounts of coverage for long-term income replacement or to cover a large mortgage. The YourTerm policy offers coverage of up to $25 million for term lengths between 10 and 40 years in one-year increments, making it easier to match coverage to a mortgage, an income-replacement period, or the years during which children or other family members will remain financially dependent.
Eligible term 10 policies can also be exchanged for longer coverage before the earlier of the 8th policy anniversary or the policy anniversary nearest the insured’s 70th birthday, making them ideal for millennials whose financial priorities can change over time. In addition, eligible policies can be converted from term to whole life insurance, which works well for an applicant who needs lifelong coverage.
For millennials seeking permanent coverage, RBC Growth Insurance and RBC Growth Insurance Plus offer participating whole life insurance with guaranteed cash values and the potential to earn dividends. Growth Insurance prioritizes long-term cash value accumulation, while Growth Insurance Plus is worth considering for those seeking earlier cash value growth. Growth Insurance offers coverage between $25,000 and $25,000,000, while Growth Insurance Plus offers coverage between $250,000 and $25,000,000.
The illustrative cost of RBC Insurance term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $13.41/month.
The illustrative cost of RBC Insurance participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $285.39/month.
- Best for: Customizable term lengths, large coverage amounts, and income protection
- Plans: RBC YourTerm, RBC Growth Insurance, RBC Growth Insurance Plus
- Policy types: Term life and participating whole life
- Term lengths: 10 to 40 years in one-year increments
- Permanent coverage: RBC Growth Insurance and Growth Insurance Plus with 10-pay, 20-pay, and Life Pay options
- Standout feature: Precise term customization, substantial coverage limits, and access to participating whole life insurance
6. Beneva: Best for built-in extreme disability protection
Beneva may suit millennials in Canada who want comprehensive life insurance coverage along with additional protection against severe disabilities. The insurer’s Term Plus plans include an Extreme Disability Benefit, which can offer policyholders an advance on their death benefit (of up to 50% to a maximum of $250,000) in the event of a qualifying extreme disability. This amount is deducted from the final death benefit paid to beneficiaries. Note that it is not a separate disability income coverage.
The advance on the death benefit can be well-suited for millennials who encounter qualifying disabilities, potentially helping cover things such as rehabilitation, home modification, or lifestyle changes. In addition, term life policies also offer flexible coverage periods, term exchange, and conversion for eligible policies.
For Canadian millennials considering lifelong protection, Beneva’s Whole Life 20 and Whole Life 100 offer non-participating policies with guaranteed premiums. These policies are suited for policyholders who solely want permanent life insurance without benefits like dividends.
The illustrative cost of Beneva term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $11.16/month.
The illustrative cost of Beneva whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage with a 20-pay option is approximately $151.20/month.
- Best for: Built-in extreme disability protection, mortgage coverage, and family flexibility
- Plans: Term Plus, Whole Life 20, Whole Life 100
- Policy types: Term life and non-participating permanent life insurance
- Term lengths: 10, 15, 20, 25, 30, 35, and 40 years
- Permanent coverage: Whole Life 20 and Whole Life 100, with guaranteed premiums
- Standout feature: Built-in Extreme Disability Benefit offers an advance on the existing death benefit for qualifying severe disability
Comparing the six best life insurance companies for millennials in Canada
| Insurer | Monthly term premium | Future policy flexibility | Term and coverage flexibility | Permanent insurance and long-term benefits (15%) | Family benefits and underwriting accessibility (10%) | Standout feature for millennials |
| Manulife | $11.13 | Eligible conversion; guaranteed insurability | Term 10, 20, to 65, lifetime option | Manulife Par participating whole life; guaranteed cash values, potential dividends; multiple payment periods | Multi-life coverage and eligible savings; children’s protection; Synergy combines life, CI and disability coverage | Vitality Plus rewards healthy habits, with potential savings and wellness benefits |
| Equitable Life | $10.89 | Term exchange and conversion; eligible term riders | Term 10, 20, 30/65 | Equimax Wealth Accumulator for earlier cash values; Estate Builder for long-term estate value; potential dividends | Children’s rider with future conversion up to 5× rider coverage; eligible term riders; preferred underwriting options | Long-standing participating dividend history and a choice between early cash-value and estate-focused whole life |
| Canada Life | $12.36 | Partial conversion, term reset, permanent conversion | My Term 5–50 years | Wealth, Balanced and Estate Achiever participating whole life; different cash-value and estate-planning priorities | Children’s term rider; Guaranteed Insurability Rider; accidental death and disability waiver options on eligible policies | Customizable 5–50-year terms to closely match mortgages, income-replacement periods and retirement |
| RBC Insurance | $13.41 | Eligible exchange and permanent conversion | YourTerm 10–40 years in one-year increments | RBC Growth Insurance for long-term value; Growth Insurance Plus for earlier cash values; potential dividends | Children’s Term Rider with conversion up to 10× rider coverage (maximum $150K); Simplified Term option; eligible waiver riders | One-year term increments help millennials align coverage precisely with mortgages and dependent years |
| Empire Life | $10.89 | Term exchange, conversion with carry-over | ART; 10, 15, 20, 25, 30 years | EstateMax for long-term death benefit growth; Optimax Wealth for earlier cash values; multiple premium-payment options | Children’s life and critical illness riders; spousal coverage options; eligible guaranteed insurability | Flexible term-to-permanent combinations alongside competitively priced participating whole life |
| Beneva | $11.16 | Eligible term exchange and permanent conversion | Term Plus 10–40 years; level/decreasing coverage | Whole Life 20 and Whole Life 100; non-participating permanent coverage with guaranteed premiums | Children’s protection and CI rider options; simplified and guaranteed-issue products; multi-life arrangements | Built-in Extreme Disability Benefit may advance up to 50% of the death benefit, capped at $250,000 |
Sample premiums reflect illustrative 2026 monthly quotes for a 40-year-old male non-smoker seeking $100,000 in term life coverage for a 10-year term. Actual premiums vary by age, sex, smoking status, health, coverage amount, product, and underwriting. Minimum coverage and available benefits vary by product and eligibility.
How we chose the best life insurance companies for millennials in Canada
PolicyAdvisor reviewed more than 30 Canadian life insurance companies before shortlisting six insurers that stood out most for millennials in Canada. We looked at whether each insurer offered competitive pricing and how the plans could support millennials navigating mortgages, growing families, income replacement, and long-term financial planning.
We also assessed whether each insurer offered flexibility to adapt coverage as time passed. This included term exchange, permanent conversion, guaranteed insurability, and relevant riders.
For consistency, our methodology uses comparable term life insurance premiums for pricing, rather than whole life premiums. Participating and non-participating whole life products have different premium structures, dividend features, and cash value benefits, making a direct price-based comparison less meaningful.
After shortlisting the six strongest companies, we ranked each insurer individually using the same weighted criteria to show where one company may be stronger than another company.
How we rated the best term life insurance companies for families
| Rating factor | Weight | What we considered |
| Pricing and affordability | 30% | Comparable 10-year term premiums and minimum coverage amounts for protecting family income |
| Future policy flexibility | 25% | Term exchange, permanent conversion, partial conversion, and guaranteed insurability options |
| Term and coverage flexibility | 20% | Term lengths, coverage limits, renewability |
| Permanent insurance and long-term benefits | 15% | Whole life options, cash values, dividends |
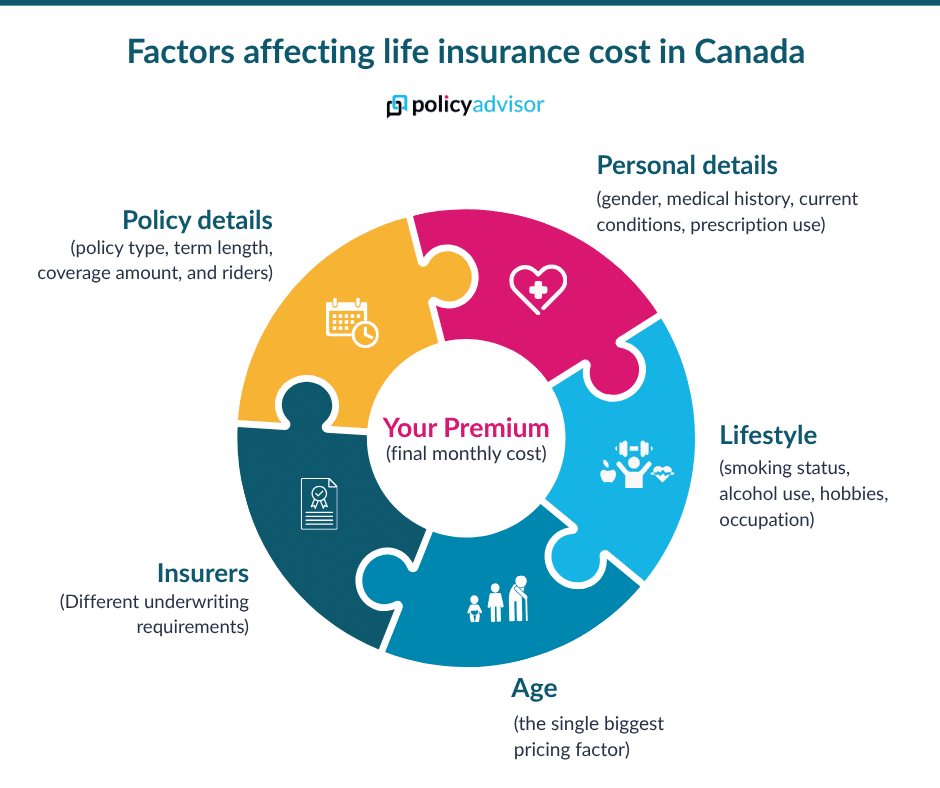
| Family benefits and underwriting accessibility | 10% | Family riders, wellness rewards, disability benefits, underwriting |
After selecting the six insurers, we scored each company out of 5, using the same weighted factors listed above. A 5/5 insurer performs especially well across both pricing and policy flexibility, while a 4.5/5 insurer remains a strong option for millennials but may have higher sample premiums, fewer term choices, or fewer standout features that are beneficial for those in their 30s and 40s. The underlying weighted result was then rounded to the nearest 0.5 for the displayed overall rating.
PolicyAdvisor ratings for the six best life insurance companies for millennials in Canada
| Insurer | Pricing 30% | Future flexibility 25% | Term flexibility 20% | Permanent benefits 15% | Family/accessibility 10% | Final rating |
| Empire Life | 5/5 | 5/5 | 4.5/5 | 5/5 | 4.5/5 | 5/5 |
| Equitable Life | 5/5 | 5/5 | 4.5/5 | 5/5 | 4.5/5 | 5/5 |
| Manulife | 4.5/5 | 5/5 | 4.5/5 | 5/5 | 5/5 | 5/5 |
| Canada Life | 4/5 | 5/5 | 5/5 | 5/5 | 4.5/5 | 4.5/5 |
| RBC Insurance | 3.5/5 | 5/5 | 5/5 | 4.5/5 | 4.5/5 | 4.5/5 |
| Beneva | 4.5/5 | 4.5/5 | 4.5/5 | 3.5/5 | 5/5 | 4.5/5 |
Ratings are based on PolicyAdvisor’s weighted methodology and illustrative 2026 term life insurance pricing. Actual premiums, eligibility, and product features vary by applicant and policy. Rankings are for comparison purposes and do not indicate the best or cheapest insurer for every individual. Pricing scores consider comparable term life premiums and available coverage options, while overall ratings also account for family benefits, policy flexibility, and underwriting accessibility.
Why do millennials need life insurance in Canada?
Millennials may need life insurance to protect their families from financial burdens and outstanding debts if they pass away unexpectedly. As Canadians move into their 30s and 40s, they typically take on financial responsibilities, such as purchasing a new house, taking on a loan, or funding their children’s education.
Here are some reasons why millennials need life insurance in Canada:
- Income replacement: Help a spouse or partner replace income during key working years
- Mortgage and debt protection: Provide financial support to repay mortgages or loans
- Childcare and domestic support: Cover daycare or additional caregiving support while children remain dependant
- Future education expenses: Offer financial support for children’s schooling and higher education
- Lifelong dependants: Provide ongoing financial support for a child or another family member who may never become financially independent due to a disability
- Business protection: Help cover business loans or succession arrangements
- Estate planning: Offers a strategy to provide an inheritance, support wealth transfer, or help cover potential final tax liabilities, probate, or estate administration fees
- Help cover funeral and final expenses: The death benefit can be used to cover funeral costs and other final expenses after death
Should millennials choose term or whole life insurance in Canada?
For most millennials in Canada looking to protect a mortgage or outstanding temporary financial obligations, a term life policy is generally an ideal choice. However, a whole life policy may be worthwhile if you plan to leave a legacy, seek a guaranteed death benefit, or want lifelong protection for your dependents and family members.
When is term life insurance better for millennials in Canada?
Term life insurance is usually recommended for individuals who need a large death benefit for a defined period (like 10 or 20 years) or need higher coverage at affordable premiums. For example, if you have a mortgage for 10 years, a term life policy would make much more sense since the obligation is temporary and will be over once the period ends.
When can whole life insurance make sense for millennials in Canada?
Whole life insurance can be ideal for millennials in Canada who need lifelong coverage or have a dependant who requires permanent financial protection. However, a whole life policy is typically recommended for those who have enough disposable income to comfortably cover the higher premiums and enjoy cash value growth and non-guaranteed dividends (in participating policies) over the years.
Check out our detailed guide on term vs. whole life insurance in Canada for a better understanding of which policy works best for you
How much life insurance coverage do millennials in Canada need?
For many millennials in Canada, a common starting point is to purchase life insurance that is equal to about five to 10 times your annual income. However, this is just a baseline and should be adjusted based on your financial situation, debts, and other factors.
Here are some things to keep in mind before deciding how much life insurance coverage you need:
- Mortgage balance
- Other debts
- Income replacement
- Childcare requirements
- Existing savings and investments
- Existing workplace or personal life insurance
- Dependent members in your family
Still confused? Use our life insurance calculator to estimate how much coverage you need.
Life Insurance Tip
What life insurance features should millennials look for in Canada?
As a millennial purchasing a life insurance policy in Canada, you should look beyond the cheapest premiums or the most affordable policies. Instead, you should consider features that remain relevant for you in the future, including during decisions such as homeownership, parenthood, or career changes.
Here are some salient features that can be useful for millennials seeking life insurance in Canada:
- Term conversion privileges: Allow eligible policyholders to convert from term to permanent life insurance without new evidence of insurability
- Term exchange options: Allow eligible shorter-term policies to be exchanged for longer coverage periods in case the need for coverage is extended
- Guaranteed insurability: Allows millennials to purchase additional coverage without any evidence of insurability, subject to applicable policy limits
- Flexible term lengths: Help align coverage closely with mortgage repayment, dependent years, or retirement periods
- Family and children’s benefits: Provide additional options for protecting eligible children and family members under a single policy or through optional riders
- Living benefits: Living benefits, such as the Extreme Disability Benefit, provide eligible financial support during qualifying severe health or disability events, helping manage costs and providing financial support
- Underwriting accessibility: Simplified or accelerated underwriting options can make it easier for millennials with underlying health conditions to secure coverage
Life insurance for millennials in Canada by life stage
Life insurance priorities for millennials in Canada can change as financial responsibilities shift, priorities change, or children grow older. As a result, different policies can benefit specific stages in life and offer more tailored coverage.
Here’s how life insurance priorities for millennials in Canada change by life stage:
| Millennial life stage | Primary financial priorities | Coverage to consider |
| Single professionals | Personal debts, dependent parents, business obligations | Smaller term coverage or whole life insurance where needed |
| Newly married or common-law couples | Shared debts, home purchase, income replacement | Individual term policies or eligible joint life coverage |
| First-time homeowners | Mortgage repayments, housing costs | Term coverage aligned with mortgage years.
Optional permanent policy for lifelong needs |
| Millennials expecting children | Parental leave, childcare, future household expenses | Convertible term insurance, family riders, children’s rider |
| Millennials with young children | Income replacement, daycare, education | Larger term coverage with suitable family benefits, waiver of premium, living benefits |
| Established professionals | Higher income, mortgage, long-term planning | Term coverage with optional permanent insurance for lifelong needs |
| Self-employed millennials | Business loans, succession, income protection | Term or permanent insurance based on business needs. Whole life policy can be used for business succession |
| Millennials in their 40s | Remaining debts, dependants, retirement planning | Review term duration to align with debts and consider permanent policy for lifelong needs |
| Millennials planning an inheritance | Estate liquidity, lifelong protection | Whole life or combined term and permanent coverage |
Is employer-provided life insurance enough for millennials in Canada?
While employer-sponsored life insurance can be a good starting point, it is typically recommended to get a personal life insurance policy. Most group benefit policies have limited coverage amounts or are based on a certain percentage of salary, which might be insufficient for millennials with higher coverage needs.
In addition, group benefits are generally tied to your workplace and usually end when you leave your job. If you leave your job or are looking for new employment, you will remain without coverage. Meanwhile, a personal life insurance policy is portable and follows you wherever you go. Individual policies also offer greater control in terms of customization, such as term length, coverage amount, riders, and additional benefits.
Cost of life Insurance for millennials in Canada
Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.
Powered by

What mistakes should millennials avoid when buying life insurance?
As a millennial looking to protect your family in Canada, you should avoid choosing a policy based solely on premiums or purchasing insufficient coverage, as this can result in inadequate protection for your beneficiaries if you, your spouse, or a key family member passes away unexpectedly.
Here are some common mistakes to avoid when buying life insurance as a millennial in Canada:
- Insuring only the earning members: Beyond the earning individuals, other family members may contribute value through childcare and household responsibilities. It is recommended to insure them as well for comprehensive coverage
- Purchasing based on the lowest premium: The cheapest term 10 policy may not be the best choice if you need protection for longer terms or if you are missing important benefits or riders that could be useful for you
- Buying insufficient coverage: While lower coverage may be more affordable, it may not provide enough money to sufficiently replace income, repay outstanding debts, and support children in case you or any other key member passes away unexpectedly
- Ignoring conversion privileges: As a millennial in your 40s, a conversion privilege can help you secure permanent life insurance without having to go through the hassle of new applications
- Ignoring your budget: While a whole life insurance policy offers lifelong coverage, premiums are significantly higher than a term policy. As a result, you should ensure you have enough disposable income to comfortably maintain coverage
- Relying only on employer coverage: Group life insurance may end when you change jobs, leaving you without protection unless conversion or portability options apply.
- Choosing lender mortgage insurance: Bank mortgage insurance generally pays the lender, with coverage decreasing as the mortgage is repaid. Personal term insurance offers beneficiaries greater flexibility.
- Ignoring beneficiaries and policy ownership: Outdated beneficiary details or unsuitable ownership arrangements can affect who receives the payout and potential tax implications.
Our advisor’s take on the best life insurance for millennials in Canada
At PolicyAdvisor, we recently helped a Canadian couple, aged 40 and 38, with two children and a remaining mortgage of $450,000. Both parents work full-time and contribute to the household income. They were seeking life insurance to ensure coverage that can provide income replacement, mortgage protection, and temporary financial assistance in the event of the unexpected.
The couple wanted $1.5 million in coverage for each parent, which would help the surviving parent cover household expenses, childcare costs, outstanding financial obligations, and final expenses. Based on their requirement, we compared coverage from 30+ Canadian insurers before recommending RBC Insurance’s YourTerm term life insurance.
Client profile
- Parent 1: 40-year-old full-time professional
- Parent 2: 38-year-old full-time professional
- Family: Two children, aged 5 and 8
- Mortgage balance: $450,000
- Primary concern: Income replacement, mortgage protection, and children’s financial security
- Coverage goal:$1.5 million in term life insurance for each parent
- Additional priority: Affordable protection, conversion flexibility
Why we recommended RBC YourTerm
- Affordable term protection: RBC YourTerm offers multiple term lengths with one-year increments that can help them align coverage with the number of years remaining on the mortgage as well as the years their children are dependant on them
- Future conversion flexibility: The ability to convert from term to permanent without any evidence of insurability is helpful for the family when their mortgage is over, and they wish to switch to lifelong coverage
- Customizable riders: Riders like the Accidental Death Benefit Rider and Waiver of Premium can be ideal for long-term protection and comprehensive coverage
- Children’s protection: RBC’s optional Children’s Term Rider can protect eligible children, providing a future conversion option that lets them secure individual coverage

We recommended RBC Insurance’s YourTerm for its customizable term lengths, substantial coverage options, and future conversion flexibility, helping the couple protect their mortgage and replace lost income
How to buy life insurance for millennials in Canada
PolicyAdvisor’s licensed life insurance advisors can help millennials in Canada compare term and whole life insurance options from leading insurers based on their income, financial obligations, mortgage obligations, dependants, and long-term financial goals.
Whether you are looking for the best life insurance for millennials in Ontario, Alberta, British Columbia, or Quebec, the right policy depends on your financial responsibilities, coverage needs, and budget. If you are buying your first home, starting a family, or switching careers, our advisors can help you compare policy features and family-oriented benefits to find a plan that aligns with your financial goals.
Frequently Asked Questions
What is the best life insurance for millennials in Canada?
The best life insurance depends on your financial needs, dependants, and budget. Based on our evaluation of millennials, insurers like Equitable Life, Canada Life, RBC Insurance, Beneva, Empire Life, and Manulife offer features and benefits that can complement the financial goals of millennials in Canada.
Is term or whole life insurance better for millennials?
The right policy ideally depends on your financial situation, obligations, and long-term coverage needs. While a term life policy is ideal for temporary requirements, a whole life insurance policy can suit those with lifelong coverage needs.
Can millennials in Canada combine term and whole life insurance?
Yes, millennials in Canada can purchase separate term and whole life policies to address temporary and lifelong needs individually. Additionally, many insurers such as Manulife, RBC, and Equitable Life allow policyholders to purchase term life insurance through riders, offering extended coverage under a single policy.
Can I increase or change life insurance as my family grows?
Yes, many policies from leading Canadian insurers like RBC Insurance and Equitable Life let you convert a term policy into permanent insurance within a specified period. In addition, eligible policies may also let you purchase additional coverage through a guaranteed insurability benefit, add certain riders, or exchange an eligible shorter term for longer coverage.
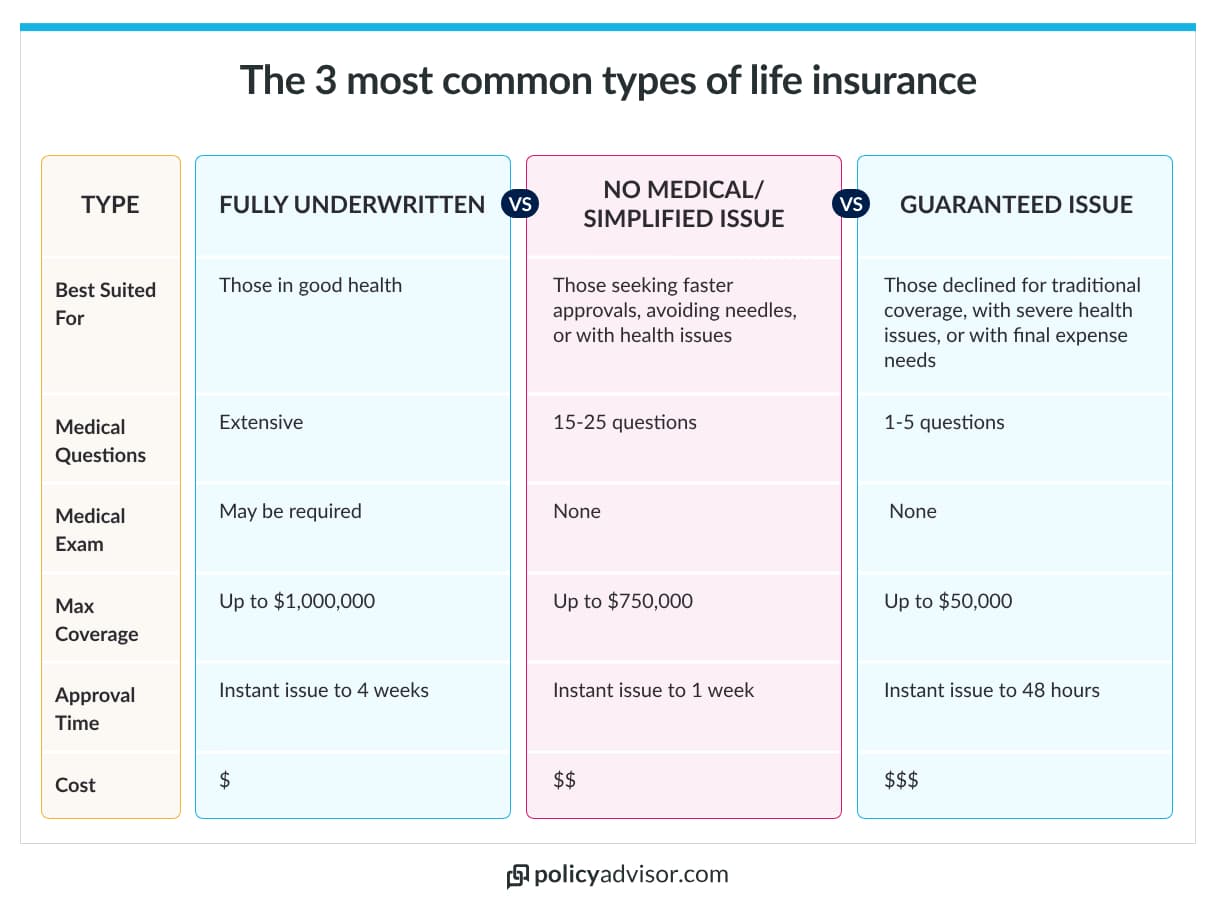
Can millennials get life insurance without a medical exam?
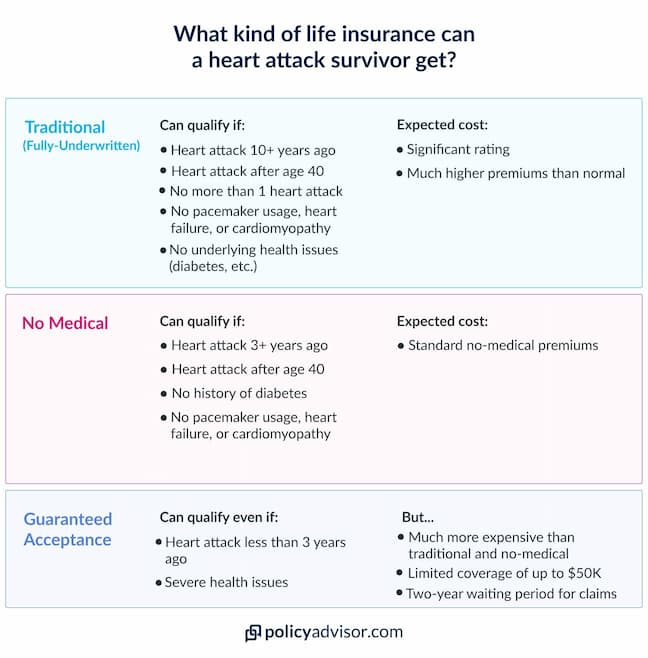
Yes, millennials with medical conditions can apply for no medical coverage, like Simplified Issue policies or apply for guaranteed-issue life insurance coverage if they do not qualify for traditionally underwritten policies. Simplified-issue policies require applicants to fill out a health questionnaire, while guaranteed-issue policies are offered as long as they meet basic requirements, such as age and residency.