Whole life insurance in Canada and how does it work

Whole life insurance can provide lifelong financial protection while offering features that go beyond a traditional term policy. It can be used for estate planning, leaving a legacy, covering final expenses, or building cash value. It comes as no surprise that many Canadians choose it for lifelong protection and tax-advantaged cash growth. This article explains whole life insurance and how it works so you can invest in a policy that keeps you and your loved ones protected.

Whole life insurance explained

Whole life insurance is a type of permanent life insurance that provides coverage for your entire life rather than a limited term. In exchange for regular premium payments, the insurer guarantees a generally tax-free death benefit (unless it exceeds the policy’s adjusted cost basis) to your beneficiaries when you pass away.

Unlike term life policies, whole life insurance also includes a guaranteed cash value component that accumulates over time. Depending on the policy you select, the plan may also earn annual dividends that can further supplement your death benefit and cash value. As a result, premiums are typically 7 to 10 times higher than those of comparable term life policies. 

For example, a healthy non-smoker 30-year-old parent may be able to purchase $100,000 in term life coverage for somewhere between $10 per month. The same amount of coverage could cost around $70 per month for whole life insurance. While whole life policy costs significantly more, the higher premiums reflect its lifelong coverage, guaranteed cash value, and potential dividend growth.

Key features of whole life insurance:

Feature Details
How it works Pay premiums to receive guaranteed lifetime coverage while building cash value
Coverage period Lifetime
Cash value Guaranteed cash value grows over time and may be accessed through policy loans or withdrawals
Death benefit Generally tax-free payment to your beneficiaries
Dividends Available on participating whole life policies (dividends are not guaranteed)
Premiums Usually fixed for life or for a limited payment period
Typical coverage amounts $25,000 to $10 million or more

How does whole life insurance work in Canada?

Whole life insurance combines lifelong financial protection with a built-in savings component. As long as you continue paying your premiums, you remain covered for the entirety of your life. Additionally, a portion of your premiums contributes to your policy’s guaranteed cash value, which grows over time. 

Here’s how a whole life insurance policy usually works:

Step 1: Choosing the right coverage amount: Choose a coverage amount that would secure the financial future of your family and protect your loved ones from outstanding debts or other costs. Many applicants choose anywhere between 7 and 15 times their annual income

Step 2: Choose your policy type: Next, you will select the type of whole life insurance that best aligns with your financial goals.

Step 3: Complete your application and pay your premiums: Once you have chosen your coverage amount and payment period, you will need to complete your application and name the beneficiary. Most applicants choose their close relatives, such as their spouse, children, or parents, as the beneficiary. Additionally, they can choose one or more beneficiaries

Step 4: Your policy builds cash value: One of the defining features of whole life insurance is the cash value. Each premium payment contributes toward a guaranteed cash value that grows over time on a tax-advantaged basis. Additionally, if you choose a participating whole life policy, you may earn dividends based on how the insurer performs financially

Step 5: Your beneficiaries receive the death benefit: If you pass away while your policy is active, your beneficiaries submit a claim to the insurance company. Once the claim is approved, the insurer pays the death benefit as a tax-free lump sum

Types of whole life insurance in Canada

While whole life insurance provides permanent coverage to policyholders as long as premiums are paid, many insurers offer the policy in different structures to suit different financial goals. The most common options are participating and non-participating, and limited-pay whole life insurance.

Participating whole life insurance

Participating whole life insurance is one of the most popular permanent life insurance policies in Canada. Alongside guaranteed lifetime coverage and cash value growth, eligible policies may also receive annual dividends based on the insurer’s financial performance.

These dividends can be used to purchase additional paid-up insurance, increase the policy’s cash value, reduce future premiums, or even repay policy loans. While the dividends are not guaranteed, most major Canadian insurers have historically paid them. 

Best for: Participating whole life insurance is a good choice for those who are looking for long-term wealth accumulation and estate planning.

Non-participating whole life insurance

Non-participating whole life insurance provides guaranteed lifetime protection with fixed premiums and guaranteed cash value growth. However, unlike participating whole life policies, it does not pay dividends.

Since there is no dividend component, these policies are simpler and more predictable. The returns and death benefit are guaranteed when the policy is issued, providing greater certainty over the life of the policy. 

Best for: This policy is well-suited for those looking for seeking predictable lifelong coverage. 

Limited-pay whole life insurance 

Limited-pay whole life insurance policies allow you to complete all premium payments within a predetermined period while keeping coverage for life. Common payment schedules include:

  • 10 Pay
  • 20 Pay
  • Pay to Age 65

Although the premiums are higher since they are paid in a shorter period, policyholders no longer need to make payments once the policy becomes fully paid up. As the premiums are paid, the cash value increases on a tax-deferred basis if the policy is “exempt” under the Income Tax Act.

Once enough cash value has accumulated, you can borrow or withdraw from it (subject to policy rules) for retirement income, emergencies, or other financial needs. However, this may reduce the death benefit and cash value.

Best for: Those who want lifelong coverage but prefer to finish paying premiums within a set period.

What is a children’s whole life insurance policy?

Whole life insurance for children provides lifelong protection with added financial benefits such as growing cash value over time. Here’s why whole life insurance for children can be a smart choice:

  • Cost-effective payments: Premiums for children’s whole life policies are generally lower, making it an affordable way to secure coverage for life. Since rates are locked in early, you avoid higher costs later
  • Guaranteed lifetime coverage: Once a policy is in place, the child is covered for life, regardless of future health changes. As long as premiums are paid, the policy cannot be cancelled by the insurer.
  • Securing insurability: Buying insurance early ensures that the child has coverage even if they develop health issues later. This helps avoid challenges in obtaining insurance as an adult
  • Cash value that builds over time: Children’s whole life policies build cash value over time, offering a financial asset they can access later for education, a home, or other needs. The cash value grows tax-deferred, adding long-term benefits
Learn more about life insurance for children 

A whole life insurance policy can be used during your lifetime and can help benefit your beneficiaries after you pass away.

How much whole life insurance coverage do you need?

You generally need whole life insurance coverage that is 10 times your salary. Choosing the right amount of whole life insurance depends on your financial goals and the needs of your loved ones. While it offers lifelong coverage and cash value growth, it’s essential to determine how much coverage will adequately protect your family.

Two common strategies to help you decide are the ‘Ten times salary’ and the ‘Years to retirement’ rules.

The ‘Ten Times Salary’ Rule: This rule suggests buying a policy with a death benefit equal to ten times your annual salary. For example, if you earn $80,000 per year, you would aim for a policy with an $800,000 death benefit. This method ensures that your family can maintain their current lifestyle, cover debts, and manage expenses in the event of your passing. It’s a straightforward approach that offers a solid financial cushion.

The ‘Years to Retirement’ Rule: This strategy focuses on covering your income until retirement. Multiply your annual income by the number of years left until you retire. If you earn $80,000 annually and plan to retire in 20 years, you would need $1.6 million in coverage. This method ensures that your family can replace your income until you’re no longer working.

Using the DIME method to estimate whole life insurance

Another method of calculating how much coverage you need is to use the debt, income, mortgage, and education (DIME) method. It is a simple way to estimate how much term life insurance you may need by considering four key financial obligations your family could face.

Let’s assume Michael, a 45-year-old business owner, wants to ensure his family is financially secure while also leaving an inheritance.

Here’s a projection of whole life insurance coverage using the DIME method:

DIME Factor Amount
Debt (credit card balance and personal loan) $75,000
Income replacement (10 years of annual income at $180,000) $1,800,000
Mortgage (remaining mortgage balance) $600,000
Education (future education savings for one child) $150,000
Total estimated life insurance needed $2,625,000

Based on the DIME method, Michael may consider approximately $2.6 million in life insurance coverage. However, because he also wants to leave an inheritance and reduce the tax burden on his estate, he may choose a higher coverage amount through a whole life insurance policy. 

While it is a handy index, your ideal coverage amount may differ based on factors such as savings, investments, and long-term financial goals.

Pros and cons of whole life insurance

Pros:
✓Guaranteed lifetime coverage and cash value growth
✓Tax-deferred cash value growth
✓Potential to receive annual dividend payments that can be used to reinvest, withdraw, or buy more insurance
✓The investment component is managed by the insurance company, and it does not fluctuate with the market
✓The amount you pay will stay the same for the duration of the entire life insurance policy
✓Your death benefit or coverage amount can grow over time with cash value or dividends
✓Your policy can be paid off in a short time frame so you don’t have to worry about it later
Cons:
✗Higher premiums than term life insurance
✗Cash value builds slowly during the early policy years
✗May offer lower short-term return compared to some investment products
✗Cancelling or surrendering the policy early can result in surrender fees and potential tax consequences
✗Whole life policies involve cash value accumulation and annual dividends, which can be challenging to grasp at first

How much does whole life insurance cost in Canada?

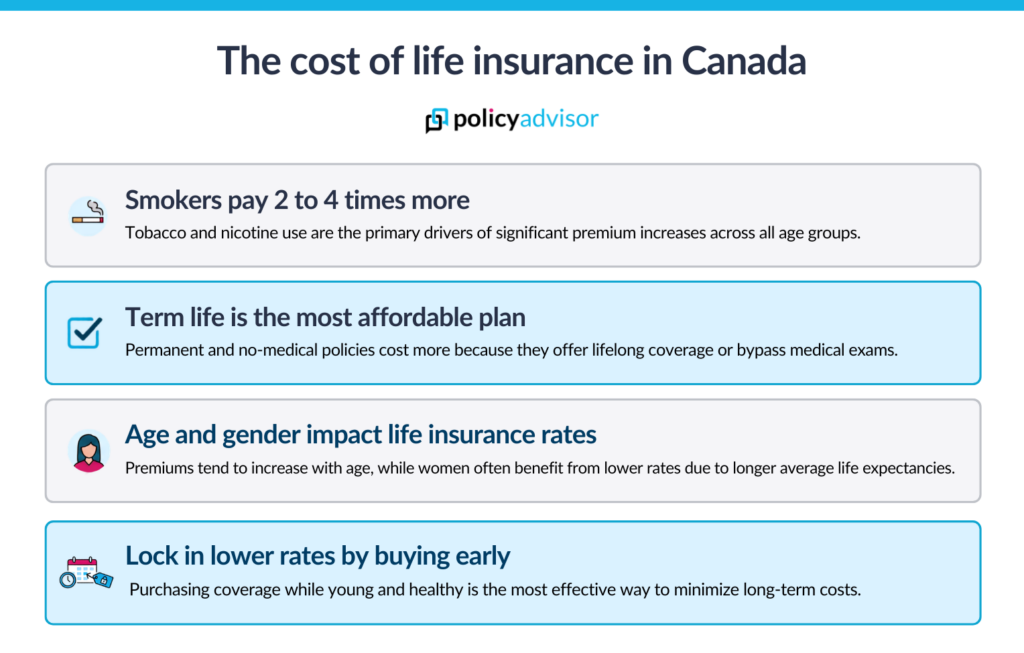
The cost of a whole life insurance policy ranges between $57 and $382. The premium depends on the policy type, coverage amount, and personal factors, such as gender, age, smoking status, and health. 

Cost of $100,000 whole life insurance policy:

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
20 $70.74/month $138.42/month $57.24/month $118.89/month
30 $100.35/month $177.84/month $88.74/month $156.15/month
40 $141.66/month $228.96/month $127.53/month $207.00/month
50 $223.83/month $292.23/month $181.71/month $270.81/month
60 $319.41/month $382.14/month $277.92/month $351.81/month

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

Protect your loved ones for life, and beyond.

We’ll help you find the lowest quotes from top insurers in Canada!

How are whole life insurance premiums calculated?

Life insurance companies calculate your premium by assessing how likely you are to make a claim over the life of the policy. It is primarily based on your age, smoking status, health conditions, coverage amount, and other related factors.

Personal factors:

  • Age: Younger applicants generally qualify for lower premiums. A 30-year-old male non-smoker pays $100.35/month for a non-participating policy with $100,000 in coverage, while a 40-year-old male non-smoker can pay $141.66/month
  • Health: Good overall health can help you secure more favourable rates
  • Smoking status: Smokers and tobacco users typically pay significantly more than non-smokers
  • Gender: Women often pay slightly lower premiums because they generally have longer life expectancies
  • Occupation: High-risk occupations may increase premiums depending on the insurer
  • Lifestyle and hobbies: Activities such as skydiving, scuba diving, or motor racing may result in higher rates

Policy and coverage factors:

  • Coverage amount: Higher death benefits result in higher premiums. A $500k policy will cost more than a $250k whole life insurance policy
  • Policy type: Participating whole life policies usually cost more than non-participating policies because of their dividend potential
  • Payment period: Limited-pay policies often have higher annual premiums than lifetime-pay policies since payments are compressed into fewer years
  • Policy riders: Optional add-ons, such as critical illness, child, or disability riders, increase the overall cost of your policy
  • Payment frequency: Some insurers offer modest savings if you pay annually instead of monthly

How do whole life insurance premiums work?

A whole life insurance policy will offer coverage as long as you pay the premiums. Here’s how it works:

  • The premiums will remain fixed, and the coverage remains active as long as you pay the premiums
  • A part of the whole life insurance cost goes towards life insurance coverage, and the other part builds the cash value
  • The greater the cash value, the more interest will be accrued, and the greater the cash value

Why is whole life insurance expensive?

Whole life insurance costs more than term life insurance because it provides lifetime coverage and builds cash value. Unlike term insurance, which covers you for a set period, whole life insurance is designed to pay a guaranteed death benefit whenever you die, provided the policy remains in force. Premiums also help fund the policy’s cash value and other guarantees, which contribute to the higher cost.

What is the cash value of whole life insurance? 

Cash value in life insurance is essentially an accumulated savings component funded by a portion of the premiums you pay. This cash value amount grows over time at a guaranteed rate and can be accessed tax-deferred during your lifetime through policy loans, withdrawals, or even to cover premium payments. 

It is also worth noting that this amount is separate from the death benefit. At death, beneficiaries receive the policy’s death benefit (base amount plus any paid‑up additions and dividends on deposit, minus loans/interest). The accumulated cash value generally remains with the insurer and is not paid out in addition to the death benefit.

How does cash value grow?

During the early years of the policy, a larger portion of your premium goes toward insurance costs and administrative expenses. As a result, the cash value grows gradually. However, as the policy matures, the cash value typically increases at a faster pace. 

Additionally, if you own a participating whole life policy, annual dividends may further increase your cash value and death benefit. Unlike market-based investments, guaranteed cash value is not affected by volatility. This makes it a relatively stable long-term commitment.

How to use cash value in whole life insurance?

You can access the cash value of a whole life insurance policy by taking out a policy loan, making a partial withdrawal, using the cash to pay premiums, or fully surrendering the policy.

Each option has different tax implications and may affect your policy’s cash value or death benefit, so it’s important to understand how they work before accessing your policy.

Here’s an overview of how you can use the cash value of your whole life insurance policy:

Method How it works Tax implications Impact on policy
Policy loan
  • Borrow against your policy’s cash value
  • Policy acts as collateral
  • Generally tax-free
  • May become taxable if policy lapses or is surrendered
  • Coverage remains in force
  • Cash value continues to grow (subject to policy terms)
  • Unpaid loan and interest reduce the death benefit
Cash withdrawal
  • Withdraw a portion of your cash value while keeping the policy active
  • Tax-free up to your adjusted cost basis (ACB)
  • Excess withdrawals may be taxable
  • May reduce the cash value and death benefit
Pay premiums
  • Use accumulated cash value to cover premium payments
  • Generally not taxable
  • Keeps the policy active without out-of-pocket premiums
  • Reduces available cash value
Surrender the policy
  • Cancel the policy
  • Receive the cash surrender value after applicable surrender charges and policy loans
  • Gains above your adjusted cost basis (ACB) may be taxable
  • Coverage ends permanently
  • Death benefit is forfeited

What happens to cash value when the insured dies?

When the insured dies, the cash value is not paid out to the beneficiaries and is returned to the insurance company. In most whole life policies, the insurer pays the beneficiaries only the death benefit, while the accumulated cash value is generally not paid separately. The cash value, however, helps the insurer fund the guaranteed death benefit.

What are whole life insurance dividends?

If you purchase a participating whole life insurance policy, you may receive annual dividends from your insurer. These dividends are based on the performance of the insurer’s participating account and may be paid to eligible policyholders.

The dividends are issued when the participating account performs better than expected in terms of investment returns, claims experience, and operating expenses. Additionally, dividend scale interest rates and payouts vary by insurer and can change over time. While these amounts are not guaranteed, they add flexibility and long-term value to your policy

How to use your whole life insurance dividends?

Similar to the cash value component, you can use your dividends to purchase additional paid-up life insurance, receive cash payments, or even repay your outstanding policy loans.

  • Paid-up additions: Purchase additional fully paid-up life insurance, increasing both cash value and the death benefit
  • Cash payment: Receive the dividend directly as cash
  • Premium reduction: Use dividends to pay some or all of your premium payments
  • Deposit with the insurer: Leave dividends on deposit to earn interest, subject to the insurer’s rates
  • Loan repayment: Apply dividends toward outstanding policy loans

Can you cancel your whole life insurance policy? 

Yes, most whole life policies can be cancelled at any time. However, since these policies build cash value, cancelling them differs from cancelling a term life policy. If you surrender your whole life insurance policy, the insurer generally pays you the available cash surrender value after deducting any applicable surrender charges, outstanding policy loans, or unpaid interest. Once cancelled, your coverage ends, and your beneficiaries will no longer receive a death benefit. 

Like most life insurance policies in Canada, whole life insurance also includes a free-look (cooling-off) period, typically lasting 10 to 30 days after you receive your policy. During this period, policyholders can review and cancel the policy, receiving a full refund of any premium paid.

What is your Whole Life Insurance worth?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$100K

What does whole life insurance not cover?

While whole life insurance covers natural and accidental death, there are certain exclusions and situations where a claim may be denied or the policy may become void.

Common exclusions and limitations include:

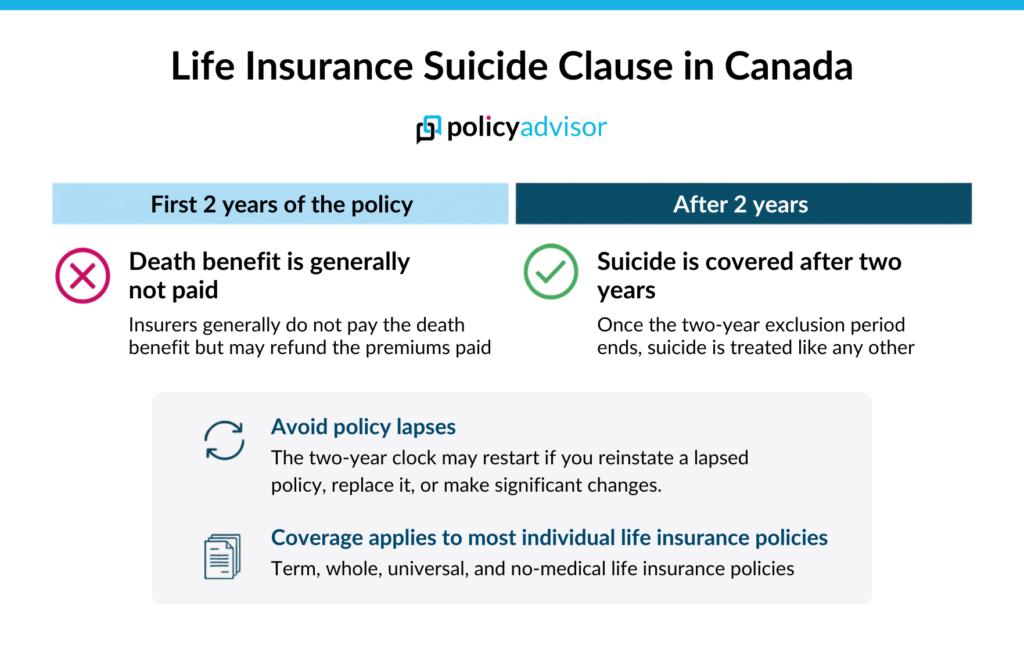
  • Suicide: Most policies have a two-year suicide exclusion. If death occurs during this period, the death benefit is generally not paid, although premiums may be refunded
  • Risky activities: Activities such as skydiving or scuba diving may result in higher premiums, standard coverage, or an exclusion, depending on the insurer’s underwriting assessment
  • Fraud or misrepresentation: False or incomplete information on an application can result in claim denial or policy cancellation
  • War and terrorism: Some policies may restrict or exclude coverage for deaths related to war, armed conflict, or terrorism
  • Undisclosed medical conditions: Failing to disclose requested health information can lead to claim denial, policy cancellation, or the policy being declared void

Exclusions vary by insurer and policy. Review policy wordings for specific limitations and definitions that apply to your coverage.

What other types of life insurance can I get in Canada?

If you are looking for alternatives to whole life insurance, these are the other types of life insurance that you can get in Canada, such as term life insurance, term-to-100 insurance, universal life insurance, funeral insurance, and no-medical life insurance.

  • Term life insurance: A type of life insurance that lasts for a certain number of years, called a term. Usually inexpensive and great for short-term needs
  • Term-to-100 life insurance: A type of life insurance policy that covers you for your entire life, but does not have a cash value or investment component as whole life does
  • Universal life insurance: A type of permanent life insurance that gives the policyholder more control over the investment part of the policy
  • No-medical life insurance: A type of insurance coverage that does not require a medical exam, and can ask just a few or no health questions at all. Usually gives lifelong coverage but comes with a lot of downsides

How does whole life compare to other life insurance policies available?

Whole life insurance is one of the many types of life insurance available in Canada. Depending on your financial goals, you may also consider term life insurance, universal life insurance, or no-medical life insurance.

Here’s a quick overview of how whole life compares to other popular life insurance options:

Feature Whole life insurance Term life insurance Term to 100 insurance Universal life insurance No-medical life insurance
Coverage duration Lifetime Fixed term (e.g., 10, 20, or 30 years) Lifetime (coverage to age 100) Lifetime Term or permanent
Premiums Higher but generally fixed for life Lowest and fixed during the term Fixed until age 100 (or for life, depending on the policy) Flexible within policy limits Higher than comparable medically underwritten policies
Cash value Yes (guaranteed growth) No No Yes (investment-linked) Usually, only if it is a permanent policy
Medical exam required Usually required Often required, but non-medical options are available Usually required Usually required No medical exam required, but it has a waiting period
Investment component Guaranteed cash value accumulation None None Flexible investment options Depends on the policy type
Death benefit Guaranteed for life Guaranteed if premiums are paid during the term Guaranteed for life if premiums are maintained Can be adjusted within policy rules Guaranteed if policy terms are met
Policy flexibility Moderate (cash value options with fixed coverage) Limited (renew or convert before expiry) Low High (flexible premiums, investments, and death benefit) Moderate, depending on the insurer and policy type
Best for Estate planning, lifelong financial protection, and leaving an inheritance Income replacement, mortgage protection, raising a family, and temporary financial obligations Lifelong coverage without paying for cash value or investment features High-income earners seeking lifelong coverage with investment flexibility People with health conditions or those needing quick approval
Typical cost Highest Lowest Lower than whole life but higher than term life Higher than term; varies based on investment choices Higher than comparable medically underwritten policies

For a detailed comparison of the plans, check out the different types of life insurance in Canada.

Best whole life insurance providers in Canada

In Canada, you can buy whole life insurance from some of the best companies, including Sun Life, Canada Life, Equitable Life, Manulife, and a few others. The right insurer depends on your coverage amount, participating-account objectives, payment period, financial strength, underwriting, policy guarantees, and dividend history.

You can also read our blog on the best whole life insurance companies in Canada to compare the top options available. Here is a quick overview of some of the best companies you can consider:

  • Equitable Life: A strong option for those who value a mutual-company structure and participating whole life coverage.
  • Manulife: Offers multiple premium payment options, including 10-pay, 20-pay, pay-to-90, and pay-to-100, along with its Vitality Plus option
  • Empire Life: Known for balanced whole life offerings through EstateMax and Optimax Wealth, with options for different long-term financial goals
  • Sun Life: Offers high coverage amounts and flexible policy features that can suit high-net-worth estate planning needs.
  • Foresters Financial: Offers competitive whole life options for smokers, including a Quit Smoking Incentive

Is whole life insurance worth it?

Yes, whole life insurance can be worth it if you are seeking lifelong financial protection, guaranteed cash value growth, and estate planning benefits. Unlike term life insurance, whole life insurance is not designed solely to replace your income for a limited period. It provides permanent financial protection while building cash value, in exchange for comparatively higher premiums.

Who is whole life insurance best suited for?

Whole life insurance is a good choice for those who:

  • Want guaranteed lifetime coverage
  • Want to leave a tax-free inheritance for your family
  • Need funds to cover estate taxes or final expenses
  • Have dependents who will rely on your financial support
  • Want to build guaranteed cash value over time

Who may not need whole life insurance?

Whole life insurance may not be an ideal choice if:

  • Your priority is affordable coverage at lower premiums
  • You want temporary coverage
  • You have limited financial obligations

Can whole life insurance be used for corporate business planning?

Yes, whole life insurance can be used for corporate and business planning in Canada, particularly by incorporated business owners. With a corporate-owned life insurance (COLI) policy, the corporation owns and pays the premiums and is generally named as the beneficiary.

The policy can help with business succession, shareholder agreements, estate planning, and providing liquidity to cover financial obligations when an insured business owner dies. Depending on the policy structure, the corporation may also build cash value that can support longer-term financial planning.

Is whole life insurance tax deductible?

While premiums paid for personal whole life insurance aren’t tax deductible, the policy offers several tax advantages, such as:

  • Tax-deferred cash value growth: Whole life policies entail a cash value component that grows on a tax-deferred basis. That means you won’t incur taxes on the cash value growth until you withdraw it
  • Tax-free death benefit: The death benefit paid to beneficiaries isn’t taxable
  • Tax-free loans against cash value: If you borrow against your whole life policy’s cash value, the loan amount isn’t subject to taxes
  • Tax-free interest-earning deposits: If you choose to receive your annual dividends in an interest-earning deposit, they remain tax-free unless withdrawn

How many years do you pay on a whole life policy?

The number of years you pay for a whole life insurance policy depends on the payment structure chosen at the time of purchase. Typically, whole life policies offer lifetime payments, limited payments, or single-premium policies.

  1. Lifetime payments: You pay premiums throughout your entire life to keep the policy active. This option spreads the cost over time, resulting in lower annual premiums
  2. Limited payment policies: You pay premiums for a set number of years, such as 10, 20, or 30 years, or until a specific age (like 65). After this period, the policy is fully paid, but coverage continues for life
  3. Single premium: You make a one-time lump sum payment upfront, and the policy remains active for your lifetime without any further premiums

Do you get your money back at the end of a whole life insurance?

No, you don’t get your premiums back at the end of a whole life policy. Instead, you get a cash surrender value that depends on the total cash value minus any applicable charges that the insurer may levy.

If your policy has a cash value of $50,000 and has accumulated $5,000 in dividends, but has $2,000 in surrender charges, your cash surrender value would be $53,000. This is calculated in the following way:

$50,000 + $5,000 – $2,000 = $53,000.

The cash value can be withdrawn or used as collateral for a loan. The death benefit is paid to beneficiaries upon your passing, provided the policy remains active.

Does your money grow in Canadian whole life insurance?

Yes, your money grows in a whole life insurance policy through its cash value component. It not only provides lifelong protection but also builds cash value over time.

A portion of your premiums is allocated to this cash value, which grows at a guaranteed rate, often supplemented by dividends if you have a participating policy.

The cash value can serve as a valuable financial resource; you can borrow against it, use it for future premiums, or even access it for retirement or other expenses.

This growth is tax-advantaged, meaning you won’t pay taxes on the cash value growth as long as it remains within the policy. Whole life insurance offers both security and a way to build wealth over time, making it a popular choice for Canadians seeking long-term financial planning.

Do you need a medical exam for whole life insurance?

In many cases, yes. Most traditional whole life insurance policies in Canada require medical underwriting, particularly if you are applying for a higher coverage amount. Depending on your age, health, and smoking status, insurers may require you to take tests to assess your health conditions.

However, many insurers also offer simplified issue and guaranteed acceptance whole life insurance with little or no medical underwriting. It is worth noting that simplified issue and guaranteed issue whole life insurance policies will typically have lower coverage limits and higher premiums, compared to traditional policies with medical underwriting.

What age to get whole life insurance?

Although there is no ideal age to get a whole life policy, the sooner you buy one, the better it will be for you. The youngest age limit to get life insurance in Canada is 18 years. Starting early on it can have certain benefits such as:

  • Lower premiums: Premiums are significantly cheaper when you’re young and healthy
  • Guaranteed coverage: Secures lifelong coverage, even if health conditions develop later
  • Builds cash value early: More time for your policy to accumulate cash value, creating a financial safety net
  • Long-term savings: Spread costs over a longer period, making it more affordable
  • Future financial security: Provides stability for dependents and can be used for estate planning or retirement

Case study: A whole life insurance example

Let’s look at how whole life insurance works in a real-world example. John is a 30-year-old Canadian who’s thinking about estate planning. He wants lifetime insurance coverage so he can leave a financial benefit for his family after he dies.

The chart below shows the cash value of his policy over time.

  • Age: 30
  • Gender: Male
  • Policy type: Whole life (non-participating)
  • Death benefit: $250,000
  • Annual premium: $1,565
  • Payment type: Life pay (premiums paid annually for life)

Features Whole life insurance
Cash value Yes
Dividends No, non-participating policies do not pay dividends
Premiums Typically fixed for the life of the policy
Death benefit Paid tax-free to the beneficiary
Cash value access May be accessed through a policy loan, withdrawal, or surrender, subject to the policy terms and potential tax consequences

Figures are based on an insurance illustration for a Desjardins non-participating whole life policy purchased through PolicyAdvisor.com for a 30-year-old male in normal health.

John can access the cash value of his policy during his lifetime, subject to the policy’s terms. However, accessing the cash value can reduce the policy’s value or death benefit and may have tax implications.

How to find the right whole life insurance policy?

Choosing the right whole life policy requires careful consideration of several factors to ensure it aligns with your financial goals. Here’s a step-by-step guide to help you make an informed decision:

  • Choose the amount of coverage you need: Determine how much coverage will adequately protect your family. Consider factors like income replacement, debt, future expenses, and long-term financial goals
  • Examine riders: Riders are optional add-ons that enhance your policy. Popular options include critical illness coverage, waiver of premium, and accelerated death benefits. Assess which riders suit your needs
  • Look at the rate of return on cash value: Whole life policies build cash value over time. Evaluate the guaranteed rate of return and any potential dividends if you’re considering a participating policy
  • Be aware of surrender charges: If you cancel your policy early, surrender charges may apply. Understand these fees and how long they last to avoid surprises
  • Understand the different approval processes: Some policies require a medical exam, while others offer simplified or guaranteed issue options. Choose the process that best suits your health status and preferences
  • Check the insurer’s financial strength: A financially strong insurer is more likely to meet its long-term obligations. Review ratings from agencies like AM Best or Moody’s to gauge stability
  • Speak with our advisors: Our experienced advisors help you compare life insurance quotes from 30+ top insurers across Canada so you can choose a plan that best meets your needs
Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

How long does it take to build cash value?

Cash value begins accumulating once your policy is in force, although growth is generally slower during the first few policy years. It typically accelerates over the long term. The timing and amount of cash value growth depend on the specific policy, premium structure, and whether the policy is participating or non-participating.

Are whole life insurance dividends guaranteed?

No, dividends are only available on participating whole life policies and are not guaranteed. They depend on the insurer’s financial performance. Insurers determine dividends based on factors such as the performance of the participating account, investment results, mortality experience, and expenses. An insurer’s historical dividend payments do not guarantee future payments.

Can I have more than one whole life policy?

Yes, many Canadians own multiple life insurance policies to meet different financial needs. Having multiple policies can help address different financial needs, such as estate planning, business protection, or leaving an inheritance. You may also combine permanent coverage with a term life policy when you need additional coverage for a specific period, such as while raising children or paying a mortgage.

Can I get life insurance riders with whole life insurance?

Yes, you can enhance a whole life insurance policy by adding riders, depending on the options your insurance provider offers. Commonly available riders include a term rider, child rider, accidental death and dismemberment benefit rider, guaranteed insurability rider, return of premiums rider, critical illness rider, and disability waiver of premiums rider, among others.

What happens if I miss a premium payment on my whole life insurance policy?

Missing a premium payment on your whole life policy can have varying consequences depending on the policy’s terms. Many policies include a grace period, typically 30 days, during which coverage remains active. If you fail to pay within this window, the insurer may use the policy’s cash value to cover premiums. If no cash value is available, the policy may lapse, leading to a loss of coverage. Some policies offer options like automatic premium loans to prevent lapses.

Can I use my whole life insurance policy as collateral for a loan in Canada?

Yes, you can use your whole life insurance policy as collateral for a loan, thanks to its cash value component. Many Canadian lenders accept this arrangement, allowing you to borrow against your policy. Alternatively, you can take a policy loan directly from the insurer. In both cases, it’s important to maintain the policy and repay the loan to avoid reducing the death benefit or risking a policy lapse.

How soon can I cash out my whole life insurance policy?

It depends on your provider. Most Canadian companies will let you access your policy’s cash value on the anniversary after 5 or more years. This depends on whether you want to withdraw it, borrow against it, or access it any other way. But you may want to wait. The longer you let whole life insurance cash value accumulate, the bigger the amount you can use and the more benefit you can have.

How much can I borrow from a whole life policy?

You can normally borrow up to 90% of your policy’s cash value if you want to take out a policy loan directly from your insurance provider. If you want to borrow from a bank or lender and just use your policy as loan collateral, you can borrow up to 100% of the premiums you paid.

How long does whole life insurance last?

Whole life insurance is designed to provide coverage for the insured’s entire lifetime, rather than for a fixed term. The policy remains in force as long as its requirements are met, such as paying premiums when due or maintaining sufficient policy value where applicable.

Should you buy whole life insurance for your child?

Yes, many Canadian parents and grandparents purchase whole life insurance for children to give them lifelong coverage at a young age. Buying coverage while a child is young can lock in lower premiums for life, guarantee their future insurability regardless of changes in health, and begin building cash value that they can access later in life, subject to the policy terms.
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best life insurance for couples in Canada (2026 guide)

Life insurance for couples in Canada can help protect shared financial responsibilities such as a mortgage, debts, child-care costs, and future family expenses. This applies whether you are married, common-law, newly married, or planning to start a family. When comparing life insurance for married couples, you can choose two separate life insurance policies or, depending on the insurer and product, joint or combined coverage.

While separate life insurance policies are the best fit for most couples due to their flexibility, joint life insurance can be a more suitable and cost-effective option for couples who want to protect shared financial obligations, simplify policy management, or reduce policy fees. The right type of couples life insurance depends on your incomes, mortgage and debts, dependants, and budget.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Top 5 best life insurance companies for couples in Canada

Choosing the right life insurance company for couples in Canada is just as important as choosing the right type of policy. While many insurers offer great benefits, the following companies offer greater flexibility, built-in benefits, and features that make them particularly suitable for partners with shared financial goals.

Here’s an overview of the five best life insurance companies for couples in Canada:

BMO Insurance

BMO Insurance is an excellent choice for couples who want their coverage to remain stable even after a life-changing event. Even if one insured person in a joint policy passes away, the surviving insured member can continue coverage at the same premium, provided the coverage amount remains unchanged.

This feature is great for couples seeking hassle-free coverage, especially at older ages when premiums are higher. In addition, BMO also offers the Empathy service, which provides emotional and logistical support to the policyholder’s beneficiaries.

Beneva

Beneva is well suited for couples who want more than just a death benefit. The policies include valuable built-in features such as the Extreme Disability Benefit and Guaranteed Insurability Option, ensuring policyholders can increase coverage later on without additional medical underwriting (under qualifying circumstances).

Additionally, eligible policies also have the option to add valuable riders such as child coverage and accidental death benefits, allowing couples to customize their protection and help ensure the financial safety of their beneficiaries.

Empire Life

Empire Life has one of the most seamless application processes, combining a streamlined online application process with competitive policy features. Couples can benefit from policy fee savings, strong term conversion options, and the ability to choose from a wide selection of term and permanent life insurance plans.

Policyholders can also add critical illness insurance under the same policy, making it easier for them to build a comprehensive financial protection plan. Additionally, the joint first-death plan offers temporary insurance to the surviving partner for an additional 90 days. This gives the spouse time to figure out their next steps without suddenly being unprotected.

RBC Insurance

RBC Insurance stands out for its Pick-a-Term feature, which lets partners choose a customized term length rather than selecting only standard options such as 10 or 20 years. This flexibility allows them to match coverage with major financial obligations like mortgages, education, or even retirement planning.

Many eligible policies also feature a seamless conversion option, allowing couples to transition from term to whole life without additional medical underwriting. Couples can also benefit from policy fee savings when purchasing joint coverage.

Manulife

Manulife is an excellent option for couples who want to combine life insurance with wellness incentives. Through the Manulife Vitality program, policyholders can earn points and receive rewards for maintaining healthy lifestyle habits, such as exercising, participating in activities, and completing health assessments.

Additionally, Manulife life insurance offers a Waiver of Premium option for couples. If either partner becomes totally disabled due to injury or illness, the premiums for the entire joint policy are waived, ensuring coverage remains active while household income is impacted.

Quick overview of the five best insurance companies for couples in Canada:

Insurer Best for Standout feature
BMO Insurance Long-term flexibility Surviving insured can continue coverage at the same premium (subject to policy conditions)
Beneva Built-in policy benefits Extreme Disability Benefit and Guaranteed Insurability Option
Empire Life Fast digital applications Digital underwriting, policy fee savings, Critical Illness integration
RBC Insurance Custom term lengths Pick-a-Term feature and joint policy fee savings
Manulife Wellness-focused couples Manulife Vitality rewards program and Waiver of Premium

What is the best life insurance for couples in Canada?

The best life insurance for couples in Canada depends on a couple’s financial goals, family situation, and long-term plans. Leading insurers such as BMO, Empire Life, RBC Insurance, and Manulife offer unique features that suit couples seeking financial protection.

While many assume a joint policy is best, separate life insurance policies can offer greater flexibility, personalized coverage, and better long-term value. Joint first-to-die insurance covers two people but generally pays one benefit when the first insured dies. Meanwhile, joint last-to-die insurance generally pays the benefit after the second insured dies. This can make it useful for estate expenses and wealth transfer.

Here’s a quick overview of life insurance for couples in Canada:

Feature Details
Types of coverage
  • Individual life insurance
  • Combined (Or multi-life) life  insurance
  • Joint first-to-die life insurance
  • Joint last-to-die life insurance
Separate policies
  • Each person has their own coverage, beneficiary, and death benefit
  • Couples with shared financial obligations
Joint first-to-die  Covers two people and generally pays once after the first death
Joint last-to-die Pays after the last insured person dies
Combined/multi-life Can include two separate policies under one contract
Best insurance companies
  • BMO
  • Beneva
  • Empire Life
  • RBC Insurance
  • Manulife
Can unmarried couples apply? Common-law partners can purchase life insurance individually or jointly if they meet the insurer’s eligibility requirements

Types of life insurance available for couples in Canada

In Canada, couples can choose between joint life insurance policies that cover both partners under a single plan or individual policies that provide separate coverage for each person. Based on the type you choose, the following options are available:

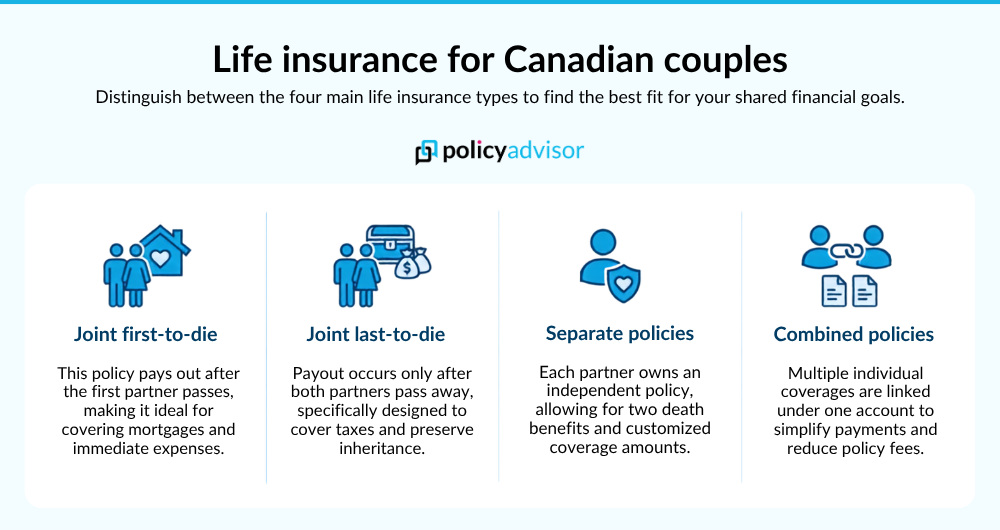
  • Joint first-to-die life insurance
  • Joint last-to-die (survivorship) life insurance
  • Two separate life insurance policies
  • Combined or multi-life insurance policy

Here’s a quick overview of the different policy types:

Joint first-to-die life insurance

A joint first-to-die life insurance policy covers two people under a single contract and pays the death benefit after the first insured person passes away. Once the benefit is paid, the policy ends, and the surviving partner no longer has coverage.

Couples commonly choose this option to ensure the surviving spouse has financial protection for living expenses, debts, child care, or mortgage payments. While it is comparatively less expensive than two separate policies, note that joint first-to-die life insurance only provides one death benefit.

Joint last-to-die (survivorship) life insurance

A joint last-to-die policy insures two people under one contract but pays the death benefit only after both insured individuals have passed away. Since the insurer does not pay until the death of both partners, premiums are often lower than buying two separate policies.

This option is great for parents or partners who wish to protect their children and other beneficiaries from debts and to support estate planning and wealth transfer.

Two separate or single life policies for couples

In this case, each spouse owns an individual policy with their own coverage amount, beneficiaries, and policy features. Each policy pays its own death benefit when the insured passes away, offering beneficiaries two separate payouts over time.

This is the most flexible option, working well for couples with different incomes, debts, health conditions, or long-term financial goals. Additionally, separate policies are easier to maintain in the event of a divorce or separation. Since they are not under a joint policy, the individuals continue to be insured without any complications or reassessment. 

Combined or multi-life insurance policy

A combined or multi-life insurance policy allows two people to have two coverages within a single insurance contract. It combines features of joint policies while offering personalized and individual solutions under one policy. 

Each insured person has their own benefit, but the policy is offered under one application and one premium payment schedule. Beneficiaries receive two death benefits, one for each policyholder. Despite being combined, the death benefits are separate for each individual. Since there are two policies under one contract, couples can save on policy or administration fees, reducing the overall costs.

life insurance couples Canada

Comparing life insurance options for couples in Canada

Each policy type has its own series of benefits and features. Separate term insurance for a husband and wife is ideal for families, while joint first-to-die life insurance is ideal for individuals seeking protection for mortgages and other major expenses. Meanwhile, a joint last-to-die policy is well suited for estate planning and creating a legacy.

Here’s a comparison of the major life insurance options available for couples in Canada:

Feature Joint first-to-die life insurance Joint last-to-die (survivorship) life insurance Two separate life insurance policies Combined or multi-life insurance policy
Who is covered? Two people under one policy Two people under one policy Two people have two separate policies, their own policy Two individual policies linked under one account
When is the death benefit paid? After the first insured person dies After both insured individuals have passed away When each insured person dies, according to their own policy Single payout based on the policy type
Number of payouts One One Two (one per policy) Two (one per coverage)
Policy ends when After the first claim is paid After the second insured dies and the claim is paid Each coverage ends independently according to its terms Each coverage ends independently according to its terms
Best suited for Income replacement, mortgage protection, and covering shared debts Estate planning, wealth transfer, and leaving an inheritance Couples who want flexible, personalized coverage Couples who want separate coverage with simplified administration
Coverage flexibility Low Low High High
Premiums Often lower than two comparable permanent policies Often lower than two comparable permanent policies Based on each individual’s age, health, and coverage needs Similar to separate policies, though some insurers may offer administrative discounts
If one partner dies, does the surviving partner remain insured? No, the policy ends after the payout.  Yes, but no benefit is paid until the surviving partner also passes away Yes, the surviving partner’s policy remains active Yes, the surviving partner’s policy remains active

It is also worth noting that many insurers offer a conversion or survivor privilege when couples purchase life insurance. This allows the surviving partner to purchase a new individual policy within a short window (usually 30 to 90 days) without undergoing a medical exam or answering new health questions.

When are separate life insurance policies better for couples?

Separate policies can provide greater independence when each person has different insurance needs. It is also great for couples with different incomes, allowing them to customize the policy according to their financial obligations.

Here’s when a separate policy makes sense:

  • You need different amounts of insurance: One partner may earn substantially more, carry more debt or have greater financial obligations. Separate policies allow each person to choose a different death benefit that covers their outstanding obligations.
  • You need different coverage periods: One partner may have a mortgage that lasts 20 years, while the other has a car loan for 10 years. Separate policies can help couples choose a term that aligns with their obligations
  • You want two separate death benefits: If you are a parent who wishes to leave behind a legacy for your children or help manage final costs, separate policies offer a death benefit for each death. This offers greater financial support than a joint policy
  • You want independence: Separate policies offer increased flexibility after separation or divorce, allowing individuals to retain their policies without being affected

When does joint or combined life insurance make sense for couples?

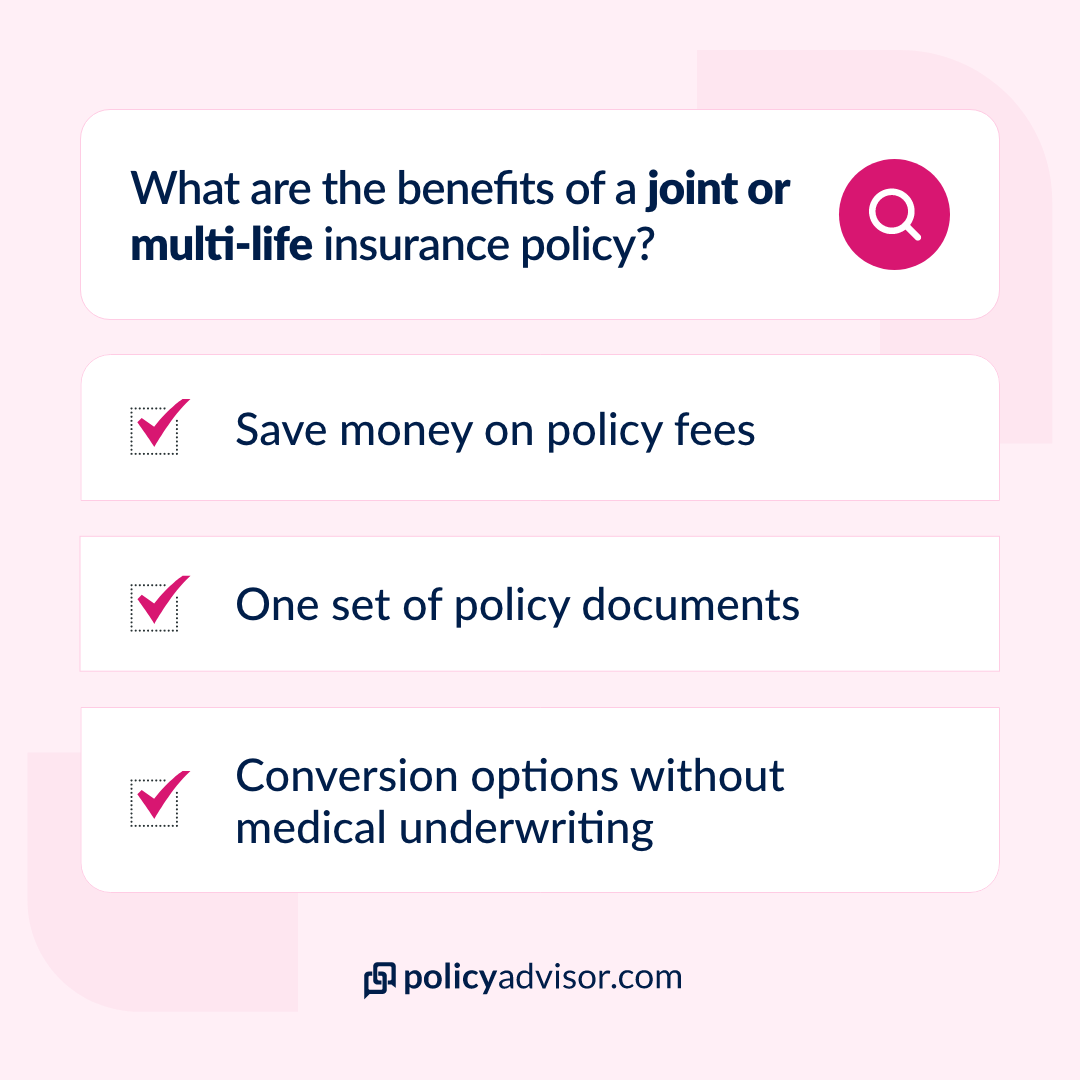
A joint or combined policy can make sense when both partners’ insurance needs are closely connected, or they wish to simplify the process and save on administration fees. 

Here’s when a joint policy makes sense:

  • You want to protect a shared debt: A joint policy is great if you wish to protect a shared obligation, such as a mortgage or a car loan. The benefit is paid after the first death and may provide the surviving partner with financial support to manage debts or replace household income
  • You want one policy to manage: Many insurers allow two coverages to be kept under one contract instead of managing two entirely separate policies, reducing the complexity and paperwork
  • You want to reduce policy fees: Many combined or multi-life products can reduce administrative or policy fees when couples purchase a joint policy. Insurers even offer savings on premiums when purchased as a family

What happens to joint life insurance after divorce or separation?

A joint policy cannot automatically be assumed to split into two individual policies following a separation. If a couple separates, they will have to reach out to the insurer regarding splitting the policy and associated administrative processes. Couples purchasing joint coverage should review the policy’s separation or conversion provisions before buying instead of assuming that coverage can always be divided later.

How much does life insurance cost for couples in Canada?

The cost of a life insurance policy for couples in Canada ranges from $224.10 to $615.15. The premiums depend on the plans chosen and the coverage, as well as personal factors such as age, smoking status, and health. 

Here is a sample life insurance rate for two 35-year-olds for Term100 from Beneva:

Feature Individual life (Male) Individual life (Female) Combined/ Multi-life Joint First to Die Joint Last to Die
Beneva/ Monthly prem $332.1 $288.45 $615.15 $457.2 $224.1
Life covered Single Single Both Both Both
Coverage Amount 500k 500k 500k + 500k 500k 500k
Saving  –  – 1% 26% 64%

Cost of life Insurance for couples

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Should couples buy joint or separate life insurance?

For most Canadian couples, it is recommended to obtain separate life insurance policies, as this allows each partner to customize their coverage and modify riders or terms independently. However, two individual policies for couples could cost as much as $620.55, whereas a joint policy costs as little as $224.1 per month. 

Separate policies provide two death benefits and have customised features, making it easier to maintain coverage if the partners divorce or separate. On the other hand, joint policies can be a good option for couples seeking lower premiums or fewer complications.

Pros and cons of purchasing a joint policy for couples

Pros:
✓One policy covers both partners
✓Easier to manage with a single premium and policy document
✓May cost less than two comparable permanent policies
✓Well suited for protecting shared financial obligations like a mortgage
Cons:
✗Typically pays out only once (depending on the policy type)
✗Less flexibility to customize coverage for each partner
✗May not be ideal if partners have different insurance needs
✗Creates additional complications if the partners divorce or separate
✗Equivalent Single Age (ESA) may increase costs when there is a significant age difference

Pros and cons of purchasing individual policies for couples

Pros:
✓Each partner chooses their own coverage amount, policy type, and term
✓Each policy pays its own death benefit
✓Surviving partner remains insured after the other partner dies
✓Easier to update coverage as financial needs change
✓Greater flexibility for beneficiaries and policy riders
Cons:
✗Usually costs more than a comparable joint policy, especially for permanent insurance
✗Two policies to manage and pay for
✗Separate underwriting and applications for each partner
✗Beneficiary updates must be made separately for each policy
Benefits of joint-life policy
More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

How much life insurance coverage do couples need?

For many Canadian families, a rule of thumb is to purchase life insurance worth around five to 10 times annual income. However, this is just a baseline and should be adjusted based on your financial situation.

Here are certain things to keep in mind before you decide how much coverage you need:

  • Mortgage balance
  • Other debts
  • Income that would need to be replaced
  • Child-care requirements
  • Education costs
  • Existing savings and investments
  • Existing workplace or personal life insurance

Still confused? Use our life insurance calculator to estimate how much coverage you need.

What mistakes to avoid when purchasing life insurance for couples in Canada?

Many couples purchase life insurance to protect their loved ones, but choosing the wrong policy, waiting too long, or having insufficient coverage can leave their family financially vulnerable.

Here are some of the common mistakes you should avoid as a couple while purchasing life insurance in Canada:

  • Waiting too long: Many couples postpone buying life insurance until they have children or purchase a home. Purchasing coverage early protects you from higher premiums later on due to age and health conditions
  • Buying too little coverage: Some couples choose the lowest premium without considering how much coverage their family would actually need. Ensure the policy amount sufficiently covers debts, future income replacement, and living expenses
  • Choosing the wrong type of policy: Many couples automatically choose a joint policy because it appears simpler or less expensive. However, a term life policy or a joint last-to-die policy might offer better estate planning and coverage in certain situations
  • Forgetting the Stay-at-Home Partner: Many couples think they only need insurance on the person who earns the most money. If a stay-at-home partner passes away, the surviving partner must pay for child care, cleaning, and cooking.
  • Not reviewing coverage after major life events: Many couples forget to review their coverage amount or duration after major events like child birth, starting a business, purchasing a home, or taking on significant debt. This can leave them without sufficient coverage or term in the future.

When should couples in Canada get or review life insurance?

Couples in Canada should get or review life insurance when their circumstances and stages of life change. This can include when you:

  • Move in with your partner
  • Start a family
  • Buy or rent a home
  • Start a business
  • Take on a new loan or other financial obligation

Apart from this, major financial decisions such as buying a home, becoming parents or taking on additional debt are also good opportunities to review life insurance for married couples or new partners. Since age is an essential factor in evaluating life insurance premiums, purchasing coverage early can help you potentially unlock lower rates.

Can you change or cancel your life insurance policy as a couple in Canada?

Yes, most life insurance policies in Canada can be changed or cancelled. However, your available options depend on the type of policy you own and the rules specific to your insurer and policy. Common changes include increasing coverage, converting term coverage to permanent coverage, or replacing a joint policy with individual policies.

Here are some of the most common changes couples make to their life insurance coverage:

Option What it means
Increase your coverage Purchase additional life insurance if your financial responsibilities grow
Replace your policy Switch to a new policy with a different insurer or coverage amount
Convert a term policy Many insurers allow you to convert eligible term life insurance into permanent coverage before a specified age or deadline
Replace a joint policy Couples who have different goals, or who divorce or separate, may replace a joint policy with individual policies
Cancel your policy Stop paying premiums and end your coverage if you no longer need life insurance

It is also worth noting that many life insurance policies in Canada include a “free-look” period to review and cancel for a refund. As a couple, you should review your life insurance coverage and goals after major life events, such as purchasing property, having children, or planning for retirement. Contact our advisors today for a comprehensive plan based on your needs.

Our advisor’s take on the best life insurance for couples in Canada

At PolicyAdvisor, we recently helped a married couple in their early thirties secure life insurance after purchasing their first home and welcoming their first child. They were seeking coverage to ensure the surviving spouse could continue paying the mortgage, replace lost income, and support their child.

Client profile

  • Ages: 32 and 34 years
  • Family: Married with one young child
  • Primary concern: Income replacement and mortgage protection
  • Existing debt: $620,000 mortgage
  • Coverage goal: $1.5 million in total life insurance
  • Approximate monthly premiums: $332.1 (Male) and $288.45 (Female), respectively

Why we recommended separate term life insurance

  • Different coverage needs: Each spouse required a different coverage amount based on their income and financial responsibilities 
  • Two death benefits: Each policy provides its own death benefit, offering greater financial support 
  • Conversion option: The policies included the option to convert to permanent life insurance if their long-term financial goals changed 
  • Affordable coverage:  Lower monthly premiums allowed them to get higher coverage without exceeding their budget

How to purchase life insurance for couples in Canada?

PolicyAdvisor’s licensed life insurance advisors can help couples compare life insurance quotes from leading Canadian insurers based on their ages, budget, coverage needs, and financial goals. They can help you estimate your coverage and decide between joint and separate policies.

Whether you are a married couple in Canada, raising a family, or planning your estate, PolicyAdvisor can help you compare quotes and apply online with licensed advisors. We will compare policy types, term lengths, and riders to help you choose the right protection for you and your loved ones.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently Asked Questions

What is the best life insurance for couples in Canada?

For most Canadian couples, two separate term life insurance policies are the best option. They offer better flexibility and allow each partner to choose their own coverage, beneficiaries, and riders with ease.

Is joint life insurance cheaper than separate policies?

Joint life insurance can sometimes have lower premiums than purchasing two comparable individual policies because both partners are insured under a single contract. However, it only pays one death benefit. Once it is paid, coverage ends.

Can common-law couples purchase life insurance together?

Yes, most Canadian insurers allow common-law partners to purchase either separate or joint life insurance policies if they meet the insurer’s eligibility requirements. Coverage options are usually the same as those available to married couples.

Can couples have different coverage amounts?

Yes, if you have separate life insurance policies. Since each policy is its own contract, you can choose to customize it based on your needs. Additionally, you can choose separate beneficiaries.

Can couples buy life insurance online?

Yes, couples can buy life insurance online. Our trusted advisors at PolicyAdvisor can help you compare quotes.

Can we name a minor child as beneficiary?

In most cases, appoint a trustee for any minor’s share so funds can be managed for the child’s benefit until they reach the age of majority in your province.

What if one of the partners has a health condition?

You can consider separate policies so one partner’s health does not influence the other’s pricing or approval. Consider exploring fully underwritten, simplified issue, or guaranteed issue options, depending on your situation.

What happens to joint life insurance after divorce or separation?

This depends on the policy terms and agreement between the policyholders. Some joint life insurance policies can be split into separate policies or transferred to one partner, while others may need to be cancelled.

What happens to joint first-to-die insurance after one partner dies? 

Once the first partner passes away, the policy will pay the death benefit and then end. However, some insurers like RBC include a survivor privilege with these policies. Under this, the surviving insured can apply for new coverage within 60 days without providing evidence of insurability.

What is spouse life insurance?

Spouse life insurance generally refers to life insurance that covers your husband, wife, or partner. A spouse in Canada may have their own individual life insurance policy, be covered with their partner under joint life insurance, or be a dependant on an employer group benefits plan.

Is term insurance good for a husband and wife?

Term life insurance can be suitable for married couples seeking coverage for a temporary obligation for a defined period, such as while paying a mortgage or supporting dependent children.

What types of insurance are most common for couples in Canada?

Life insurance for couples in Canada can include two individual policies, joint first-to-die insurance, joint last-to-die insurance, and certain combined or multi-life policies. The right policy depends on your financial needs, income, and flexibility.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much does a $50,000 life insurance policy cost in Canada?

The cost of a $50,000 life insurance policy in Canada ranges between $8.32 and $165.04 for term life and $26.60 and $273.20 for whole life insurance. Your premiums depend on factors such as your age, health, sex, smoking status, coverage type, and the insurer’s underwriting assessment. Read on to learn the difference in cost and the factors affecting your premiums.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

$50,000 term life insurance vs. $50,000 whole life insurance

Here is a quick overview of monthly term and whole life insurance premium costs for $50,000 in Life insurance:

Applicant example $50,000 term life $50,000 whole life
Age 20, non-smoker $9.45 $28.94
Age 30, non-smoker $9.68 $34.70
Age 40, non-smoker $10.13 $51.26
Age 50, non-smoker $15.39 $77.85
Age 60, non-smoker $33.97 $133.02

How much does $50,000 term life insurance cost?

A term life insurance policy for $50,000 in Canada ranges between $8.32 and $165.04, depending on various factors such as age, sex, term duration, and health. This policy provides coverage that lasts for a specific period of time known as a term. Your term life insurance can last either a fixed number of years (like 10, 20, 30 or even 40 years) or until you reach a certain age (like age 65).

The insurance premiums are guaranteed for the initial term of the policy and are paid directly to the insurance provider. Upon the end of the term, the coverage may automatically renew, or expire depending on the plan type.

If you die while the policy is in force, your beneficiaries will receive the death benefit as a tax-free lump sum of cash. If you choose to renew the policy at the end of the term, the premiums will increase based on the renewal schedule provided at the time of the initial contract. If you do not want to continue your coverage with the renewal premiums, you can cancel the policy.

The cost of term life insurance is primarily based on the length of term, the insured person’s age, gender, health, smoking status, and the amount of the death benefit they choose.

Term life insurance costs for $50,000

Based on standard health, male, $/month

Age Non-Smoker Smoker
20 $9.45 $11.70
25 $9.45 $11.70
30 $9.68 $12.74
35 $9.90 $13.77
40 $10.13 $16.56
45 $11.57 $23.72
50 $15.39 $36.13
55 $23.03 $50.12
60 $33.97 $65.32
65 $51.74 $101.86

Term life insurance costs for $50,000

Based on standard health, female, $/month

Age Non-Smoker Smoker
20 $8.32 $9.00
25 $8.32 $9.14
30 $8.55 $9.81
35 $8.78 $11.66
40 $9.00 $15.07
45 $10.04 $19.43
50 $13.64 $25.79
55 $18.67 $35.46
60 $25.69 $49.95
65 $39.95 $57.09

How much does $50,000 whole life insurance cost?

A whole life insurance policy for $50,000 in Canada ranges between $26.60 and $273.20, depending on various factors such as age, sex, payment term, and health. Premiums generally increase with age and can be higher for smokers and applicants with certain health risks. Whole life policies generally cost more than term insurance because they provide permanent coverage and typically include a cash value component. It is a type of permanent life insurance policy available in Canada. 

As long as you continue paying the required premiums, your policy continues to be in effect till you stop paying or pass away. So, it comes as no surprise that many Canadians choose it for lifelong protection and tax-advantaged cash growth.

Furthermore, whole life insurance combines this financial protection with some access to liquidity. Unlike term life policies, whole life insurance also includes a guaranteed cash value component that accumulates over time. Depending on the policy you select, the plan may also earn annual dividends that can further supplement your death benefit and cash value.

The cash value of a whole life insurance policy is accessible while the policyholder is still living. They can either borrow against or withdraw from the cash value.

Similar to term life insurance above, the cost of whole life insurance premiums is based on age, health, gender, smoking status, the size of the death benefit, and the added expense of insuring someone’s life for an extended period (their entire life).

As an individual gets older, the health risks increase. This has a direct impact on the cost of your policy. Since the coverage lasts one’s entire life and the policyholder retains the value put into the policy, whole life insurance has higher premiums.

Whole life insurance costs for $50,000 (Non-participating)

Based on standard health, cash value coverage, $/month

Age Non-Smoker Smoker
20 $28.94 $34.74
25 $29.66 $37.53
30 $34.70 $45.63
35 $41.04 $55.85
40 $51.26 $70.83
45 $64.04 $90.14
50 $77.85 $114.93
55 $98.10 $157.19
60 $133.02 $212.99
65 $185.94 $273.20
Life insurance was complicated. Not anymore.

Check out our free insurance assessment tools.

What does $50,000 life insurance cover?

Your financial needs change and evolve, and there are many reasons someone may need a relatively smaller life insurance policy. A $50,000 life insurance death benefit can help beneficiaries cover expenses such as funeral costs, outstanding debts, and ongoing financial support.

Here are some reasons to consider $50,000 of life insurance:

  • Pay outstanding debts: Life insurance proceeds can help beneficiaries manage debts and other financial obligations
  • Help cover funeral and final expenses: A life insurance death benefit can be used toward funeral costs and other expenses after death
  • Provide additional financial support: The death benefit can provide beneficiaries or dependants with additional funds after you pass away
  • Leave a legacy: The death benefit can be used to make a charitable donation or leave a gift to children or grandchildren
  • Laddering: The smaller amount can contribute to a life insurance ladder strategy where you layer different amounts of life insurance. You can pair $50,000 in whole life while purchasing a higher amount of term life coverage 

Is $50,000 of life insurance enough in Canada?

A $50,000 life insurance policy may be enough if your goal is primarily to cover final expenses, smaller debts, or provide a modest additional benefit to your beneficiaries. However, it may not provide enough protection if your family would need substantial income replacement or help covering larger long-term financial obligations.

As a general rule of thumb, Canadians should aim to secure a life insurance policy worth 7 to 10 times their gross annual income to sufficiently manage their expenses at different stages of their lives.

Still confused about whether $50,000 is enough for you? Contact our licensed advisors and find a plan that suits your financial needs.

Who might need $50,000 life insurance? 

A $50,000 policy may suit a Canadian individual or family whose life insurance needs are relatively limited. It may be well suited for individuals looking to leave money for funeral expenses, repay smaller debts, or pay off the remaining mortgage amount without bearing the cost of higher premiums.

Still confused if $ 50,000 life insurance is the right amount for you? Check out our life insurance calculator.

What affects the cost of a $50,000 life insurance policy?

The cost of a $50,000 life insurance policy in Canada may be attributed to several additional factors, including an individual’s health, age, gender, job profile, and whether they have additional riders. Find out more:

Health

Health is one of the primary factors that determine your life insurance premiums because it directly affects your life expectancy and the financial risk undertaken by the insurer. When you apply, underwriters evaluate metrics like your BMI, blood pressure, cholesterol, and pre-existing chronic conditions, alongside your family medical history and smoking status. While good health unlocks lower premiums, poor medical conditions may increase premiums significantly.

Age

Age is the single biggest factor influencing the cost and availability of life insurance, since mortality increases as you get older. Younger Canadians typically receive lower rates or more favourable underwriting, compared to older applicants.

Gender

Gender is a key factor in determining the cost of a life insurance policy in Canada. Statistically, women tend to live longer than men, which can result in lower premiums for women. 

Insurers calculate premiums based on life expectancy, so men may face higher premiums for the same coverage amount, such as a $50,000 policy, compared to women.

Job profile

Your occupation can also influence the cost of your life insurance policy. Jobs that are considered high-risk, such as those in construction, aviation, or mining, often lead to higher premiums because they increase the likelihood of injury or death. Conversely, low-risk occupations, such as office work, may result in lower premiums.

Additional policy riders

Policy riders and options are additional features you can add to your life insurance policy, which can increase the overall cost. Common riders include critical illness coverage, accidental death benefits, and waiver of premium. 

While these riders provide extra protection and benefits, they come at an additional cost, raising the premiums of your $50000 life insurance policy. The more riders you add, the higher the premium will be.

Can you get $50,000 life insurance without a medical exam? 

Yes, you can purchase a simplified issue or guaranteed issue life insurance policy without a medical exam. A simplified issue term life insurance policy can range between $8.33 and $68.49. Additionally, some insurers may request that applicants fill out a health questionnaire as part of the process.

Here are the options available if you wish to obtain $50,000 without a medical exam:

Simplified issue life insurance policy

Simplified issue is a type of life insurance underwriting for term or permanent policies that requires applicants to answer a limited number of health questions without completing a medical exam. While approval is faster, premiums are much higher than those of traditionally underwritten policies. 

Guaranteed issue life insurance policy

Guaranteed issue life insurance offers coverage without any medical questions or examinations. Acceptance is generally guaranteed as long as the applicant meets the insurer’s age requirements. 

This policy type is essentially a last-resort option for Canadians with serious medical conditions or those who have difficulty qualifying for life insurance coverage. Guaranteed issue features the highest premiums and lower coverage limits, owing to the higher risk assumed by the insurer. 

How do I get the best quotes for $50,000 life insurance coverage?

At PolicyAdvisor, we help Canadians compare quotes from leading life insurance companies and find the right fit for their coverage needs. Book some time with our licensed advisors and find out how easy it is to get the right amount of coverage from the comfort of your own home.

I need insurance. Where do I start?

Our calculator gets you the right quotes and the lowest rates.

Frequently Asked Questions

How much is a $50,000 whole-life policy?

The cost of a $50,000 whole-life policy for a non-smoker can range from $26.60 to $197.55 per month. For the same coverage amount, a smoker may have to pay between $28.94 and $273.20 per month. 

Healthier applicants typically pay less, while individuals with health issues may face higher premiums. Additional policy riders and options can also increase the cost.

Is $50,000 of life insurance enough coverage?

Whether a $ 50,000 life insurance policy is enough coverage depends on an individual’s financial situation and goals. This amount may be sufficient to cover final expenses, such as funeral costs and outstanding debts, or to provide a modest financial cushion for loved ones. 

However, if an individual has dependents, a mortgage, or significant financial obligations, they might need a higher coverage amount to adequately protect their family’s financial future.

How does an individual’s age affect the cost of their  $50,000 life insurance policy?

An individual’s age significantly affects the cost of a $50000 life insurance policy. Generally, the younger you are when you purchase the policy, the lower your premiums will be. This is because younger individuals are typically at lower risk of health issues and death. 

As individuals age, premiums increase due to the higher risk of health problems, making it more expensive to obtain the same coverage.

Is $50,000 term life insurance cheaper than permanent life insurance? 

Yes, term life insurance is generally less expensive than permanent life insurance, owing to its limited coverage and lack of cash value accumulation. Permanent policies like whole life insurance provide lifelong coverage alongside cash value growth and non-guaranteed dividends in participating policies.

Can seniors get $50,000 of life insurance?

Yes, seniors in Canada may qualify for $50,000 of life insurance. However, eligibility depends on their age, health, and the insurer’s policy terms. Some insurance companies may limit the amount and types of coverage available based on age.

Can I get $50,000 of life insurance with no medical exam?

Yes, some insurers offer $50,000 of life insurance without a medical exam through simplified issue and guaranteed issue policies. Insurers like RBC, Humania, and Manulife offer various no-medical plans that offer coverage to Canadians without a medical exam. However, policyholders may be required to complete a health questionnaire.

Can I convert $50,000 term insurance to permanent insurance?

Yes, if your term life policy offers a conversion privilege, you may be able to convert some or all of your $50,000 term coverage to permanent life insurance before the policy’s conversion deadline. Depending on the contract, conversion may also be available without providing new medical evidence of insurability.

Is $50,000 of whole life insurance a good investment?

Yes, a whole life insurance policy for $50,000 is a good investment if you need lifelong coverage for that amount, alongside cash value growth and non-guaranteed dividends. It can be used to leave behind a legacy or help cover final expenses.

Does smoking affect the cost of $50,000 of life insurance?

Yes, smokers generally pay more for the same amount of life insurance than non-smokers. A smoker may pay 50% to 100% more than a non-smoker for the same amount of coverage, owing to the increased mortality risks associated with smoking.

Can I use $50,000 of life insurance to cover funeral expenses?

Yes, a beneficiary can use proceeds from a $50,000 life insurance death benefit to help pay funeral and other final expenses. The policyholder can leave behind the death benefit for dependants or specific beneficiaries, allowing them to use it to pay funeral costs and other associated expenses.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Does life insurance cover suicides in Canada?

Life insurance is designed to provide financial protection for your loved ones, but not every cause of death is treated the same under an insurance policy. Suicide is generally covered by many Canadian insurers after the policy’s suicide exclusion period. Understanding how insurers assess suicide-related claims, the rules that apply, and when benefits may or may not be paid can help you make informed decisions before buying coverage.

If you or a loved one are experiencing  a mental health crisis, please  contact the Mental Health Support Line at 9-8-8

Want to explore life insurance?

Get the lowest life insurance quotes at PolicyAdvisor!

Does life insurance cover suicide in Canada?

Yes, life insurance in Canada generally covers suicide, but only after the policy’s suicide exclusion period has ended. Most insurers, including Canada Life, Equitable Life, Manulife, Sun Life, and others, have a two-year suicide clause.  If the insured dies by suicide within those first two years, the death benefit is generally not paid. Once this period expires, beneficiaries are generally eligible to receive the full death benefit, provided all policy terms and conditions have been met.

Life insurance coverage for suicide:  at a glance

Situation What generally happens
Suicide within the first 2 years of an individual policy The full death benefit may not be payable; the contract may provide for a premium refund or another amount
Suicide after the 2-year period The death benefit may be payable if the policy remains valid and other terms are satisfied
Policy reinstatement A new 2-year exclusion period may apply from the reinstatement date
Replacing a policy The new contract may begin a new 2-year suicide period

What is the suicide clause in life insurance?

A suicide clause is a standard provision found in most life insurance policies in Canada that limits or excludes the payment of the death benefit when the insured dies by suicide during a specified period after coverage begins. The clause is designed to protect insurers from individuals purchasing coverage with the intention of making an immediate claim due to suicide.

If the policyholder dies by suicide during the exclusion period, the insurer will typically deny the death benefit. Once the exclusion period ends, suicide is generally treated like any other covered cause of death. Eligible beneficiaries can usually receive the death benefit, depending on the terms and conditions of the policy.

How long does the suicide clause last?

A two-year exclusion period is common in many individual term, whole life, universal life, and no-medical life policies, but it should not be assumed that every policy uses identical wording. One must review the policy’s suicide provision, effective date, reinstatement clause, etc.

In some cases, the two-year period may restart if:

  • The policy lapses and is later reinstated
  • A new policy replaces an existing one
  • Significant changes require new underwriting (depending on the insurer and policy)

Why insurers include this clause

Insurers include a suicide clause to reduce fraudulent life insurance claims and keep premiums affordable for all policyholders. Without an exclusion period, someone could purchase a policy knowing an immediate claim was likely, creating a significant financial risk for insurers.

The clause serves several purposes:

  • Prevents insurance fraud: Discourages individuals from buying a policy solely to trigger an immediate death benefit
  • Keeps premiums affordable: Reduces unnecessary claim risk, helping insurers maintain stable pricing for all customers
  • Promotes fair underwriting: Ensures life insurance functions as long-term financial protection rather than an immediate financial payout
  • Provides long-term coverage: Once the exclusion period ends, suicide is generally covered like other causes of death, giving families financial security when they need it most
does life insurance cover suicide

How does suicide affect life insurance payouts?

Whether a life insurance policy pays out after suicide depends on when the death occurs and the type of policy. Your policy wording will normally state exactly how your provider will deal with a death by suicide.

In case of death during the suicide clause period

If the insured dies by suicide within the policy’s suicide exclusion period, the insurer generally does not pay the policy’s death benefit. Instead, some insurers refund the premiums paid, although the exact amount and terms may vary by policy. For example, policy terms from insurers like  Desjardins, Sun Life, and others state that they will return payments made or the policy’s cash value if the policyholder dies by suicide before the 2-year period is up.

Alternatively, some providers may choose to deduct fees. The exact payment depends on the policy wording.

In case of death after the suicide clause period

Once the two years specified in the clause have passed, the life insurance policy will treat it as a regular cause of death. The provider will pay out if the individual passes away for any of the typical covered reasons, including suicide. 

If the policy remains in force and there has been no material misrepresentation or policy lapse, the insurer will usually pay the full death benefit to the named beneficiaries. The claim is processed through the insurer’s standard claims procedure, and the payout can be used for any purpose, such as replacing lost income, paying off debts, covering funeral expenses, or supporting long-term financial needs.

In case of a joint life insurance policy

A joint life insurance policy generally includes the same two-year suicide clause as an individual life insurance policy, but the treatment of a claim depends on whether the policy is joint first-to-die or joint last-to-die. For joint first‑to‑die, no benefit is payable if the first death is suicide within two years. Once that period has passed, the benefit is payable at the first death. For joint last‑to‑die, there is no payout at the first death regardless of cause or exclusion. The suicide clause is assessed at the death of the second individual, which triggers the benefit as per policy wording.

Does the suicide clause apply to every type of life insurance?

Yes, the suicide clause generally applies to most individual life insurance policies in Canada, including term life, whole life, universal life, and many no-medical life insurance plans. While the exact wording may differ between insurers, most policies include a two-year suicide exclusion period that begins on the policy’s effective date.

The only exception is group life insurance, which is provided through an employer or association, and may have different terms from an individual policy. Some group plans include a suicide exclusion period, while others may not. Coverage and payout conditions depend on the insurer and the specific group contract.

Secure the financial future of your loved ones

Get the most affordable life insurance rates in Canada today!

Does medically assisted death (MAID) affect life insurance?

No, Medical Assistance in Dying (MAID) in most cases does not affect a valid life insurance claim in Canada. Since MAID is a legal medical procedure available to eligible individuals under Canadian law, many insurers do not automatically apply the standard suicide exclusion clause. Instead, they assess claims according to their policy wording and internal claims guidelines.

The Canadian Life and Health Insurance Association states that compliant MAID will not be considered suicide for life insurance purposes. Regardless of the approach, eligible beneficiaries can generally receive the death benefit if the policy is valid and all terms have been met.

However, MAID does not remove other valid grounds for ineligibility, such as:

  • Material misrepresentation when the insured applied for coverage
  • A medical condition that was specifically excluded when the policy was issued

Does a history of mental illness affect life insurance coverage?

Yes, a history of mental illness can affect life insurance coverage, but it will not prevent you from getting coverage. Many insurers offer coverage to applicants with conditions such as depression, anxiety, bipolar disorder, or other mental health disorders. Approval and premiums are based on factors such as your diagnosis, treatment plan, symptom stability, medications, hospitalization history, and overall health, not simply the diagnosis itself.

It is also important to note that having a mental health condition does not change the standard suicide clause. Most life insurance policies apply the same two-year suicide exclusion period to all policyholders, regardless of their mental health history.

Does a previous suicide attempt affect a life insurance application? 

Yes, a previous suicide attempt can affect a future life insurance application. Insurers like Sun Life specifically consider the applicant’s age, number of attempts, and time since the incident. Additionally, they may consider factors such as resulting medication, hospitalization, underlying psychiatric conditions, and stability of home and life.

When can the suicide clause restart?

Although the suicide clause typically expires after two years, it may restart in certain situations. This most commonly happens when a lapsed policy is reinstated, as many insurers begin a new two-year suicide exclusion period from the date of reinstatement.

The clause may also restart if you replace your existing policy with a new one or make significant changes that require new underwriting, such as applying for a higher coverage amount. Since these rules vary by insurer and policy type, it is important to review your policy documents or speak with your insurance advisor before making changes to your coverage.

How do beneficiaries file a life insurance claim after a suicide-related death?

In case of a suicide-related death, beneficiaries should notify the insurer promptly and provide the required documents. The insurer will review the claim, including the policy terms and the timing of the death, before determining whether the death benefit is payable. Here’s a step-by-step process for the same:

  • Notify the insurer: Contact the life insurance company as soon as possible to report the death and begin the claims process, if applicable
  • Submit the required documents: Provide the completed claim form, death certificate, proof of identity, and any other documents requested by the insurer
  • Cooperate with the claim review: The insurer may review the policy’s effective date, cause of death, and medical records to determine whether the suicide exclusion or contestability period applies
  • Review the claim decision: If the policy terms have been met, the death benefit is generally paid. If the claim is denied, the insurer will explain the reason in writing

What documents are needed for a suicide-related life insurance claim?

For a suicide-related life insurance claim in Canada, beneficiaries will generally need to provide the insurer with standard death-claim documents as well as any additional records required to confirm the cause and circumstances of death. 

While the exact list of documents can vary based on the insurer, it may include:

  • Proof of death, such as an official death certificate
  • Coroner’s or police report
  • Proof of identity for the beneficiary or claimant
  • Physician’s statement or medical records, if requested

Beneficiaries are requested to contact the insurer after a death to know if any additional documentation may be required.

What happens if a life insurance claim is denied because of suicide?

If a life insurance claim is denied because of suicide, it is usually because the insured died during the policy’s suicide exclusion period. If your claim is denied, you should take the following steps:

  • Review the insurer’s explanation: Understand why the claim was denied and which policy provision applies
  • Check the policy wording: Confirm whether the suicide exclusion or another policy condition was the reason for the denial
  • Request additional information: Ask the insurer to explain how they reached their decision, if anything is unclear
  • Appeal the decision if appropriate: If you believe the claim was wrongly denied, you may be able to provide additional evidence or request a formal review by the insurer

What should beneficiaries do after a suicide-related death?

In case of a suicide-related death, beneficiaries should notify the insurer promptly and provide the required documents. The insurer will review the claim, including the policy terms and the timing of the death, before determining whether the death benefit is payable. Here’s a step-by-step process for the same:

  • Notify the insurer: Contact the life insurance company as soon as possible to report the death and begin the claims process, if applicable
  • Submit the required documents: Provide the completed claim form, death certificate, proof of identity, and any other documents requested by the insurer
  • Cooperate with the claim review: The insurer may review the policy’s effective date, cause of death, and medical records to determine whether the suicide exclusion or contestability period applies
  • Review the claim decision: If the policy terms have been met, the death benefit is generally paid. If the claim is denied, the insurer will explain the reason in writing

What happens if a life insurance claim is denied because of suicide?

If a life insurance claim is denied because of suicide, it is usually because the insured died during the policy’s suicide exclusion period. If your claim is denied, you should take the following steps:

  • Review the insurer’s explanation: Understand why the claim was denied and which policy provision applies
  • Check the policy wording: Confirm whether the suicide exclusion or another policy condition was the reason for the denial
  • Request additional information: Ask the insurer to explain how they reached their decision, if anything is unclear
  • Appeal the decision if appropriate: If you believe the claim was wrongly denied, you may be able to provide additional evidence or request a formal review by the insurer
Looking for expert advice?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently Asked Questions

How do life insurance companies determine if someone died by suicide?

Once an insurance claim is submitted, your insurance company will do its own investigation before making a payout. In the unfortunate instance of a death by suicide, life insurers will usually look into the cause of death. This may include reviewing medical records, law enforcement or police reports, and speaking with family members or friends. After the investigation is complete, the insurer will determine whether the death benefit is payable.

Does life insurance pay out if suicide occurs after two years?

Yes, in most Canadian life insurance policies, the full death benefit is paid if the insured dies by suicide after the two-year suicide exclusion period has expired. The policy must remain active, premiums must be up to date, and there must be no material misrepresentation on the application.

Does replacing or reinstating a life insurance policy restart the suicide clause?

Yes, replacing or reinstating a life insurance policy can restart the suicide clause. Many insurers restart the two-year suicide exclusion period when a lapsed policy is reinstated or when an existing policy is replaced with a new one. Significant policy changes that require new underwriting may also trigger a new exclusion period.

Can a life insurance claim for suicide be appealed?

Yes, a life insurance claim for suicide can be appealed. If a claim is denied, beneficiaries can request a detailed explanation from the insurer, review the policy wording, and provide additional supporting documents if necessary. If they believe the claim was incorrectly denied, they may request a formal review or appeal the insurer’s decision.

Does the suicide clause apply to no medical life insurance?

Yes, no medical life insurance policies, including simplified issue and guaranteed issue plans, include a suicide exclusion period similar to traditional life insurance policies. However, the exact terms and exclusions vary by insurer, so it’s important to review the policy wording before purchasing coverage.

Is MAID considered suicide for life insurance?

Whether Medical Assistance in Dying (MAID) is considered suicide for life insurance purposes depends on the insurer. Some Canadian insurers classify MAID as a separate category from suicide, while others treat it as a death resulting from an illness. In either case, many insurers will pay the death benefit if the policy is valid and all terms and conditions have been met. Because insurer policies differ, it’s important to review your policy wording or speak with your insurance advisor to understand how MAID-related claims are handled.

Which is the key document in Canada that proves the cause of death?

The main document in Canada that officially records and proves the medical cause of death is the Medical Certificate of Death (often ordered as part of a Certified Copy of Death Registration when specific medical details are required). This document is issued and signed by an attending physician or a coroner, detailing both the direct medical cause of death and the manner of death.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much does life insurance cost in Canada in 2026?

The average cost of life insurance in Canada starts at around $7 per month for a healthy young adult purchasing a basic term life insurance policy. Depending on the type of policy, coverage amount, age, health, and insurer, premiums can range from $7 to over $3,276 per month. Individuals who smoke, have pre-existing medical conditions, work in high-risk occupations, or require larger coverage amounts generally pay higher costs. On the other hand, young and healthy applicants typically qualify for lower rates.

Quick summary: Average life insurance costs in Canada

Cost category Average cost (per month)
By plan type
  • Term life: $14-$200
  • Permanent life: $71-$382
  • No medical: $39-$380
By coverage amount
  • $100,000: $7-$44
  • $250,000: $10-$98
  • $500,000: $13-$177 
  • $1,000,000: $21-$330
  • $10,000,000: $166-$3276
By applicant category
  • Smokers: $42-$504
  • Seniors: $15-$267
  • Children: Starts at $100
  • Couples: $33-$1283
By term length
  • 10-year: $22-$40
  • 20-year: $28-$70
  • 30-year: $42-$144
By insurers
  • Sun Life: $16-$230
  • Manulife: $17-$213
  • Empire Life: $14-$200
  • Equitable Life: $14-$200
  • Canada Life: $16-$204

Disclaimer: The premiums shown above are illustrative estimates based on specific applicant profiles and policy assumptions, and your actual life insurance cost may vary depending on several factors such as your age, gender, health, smoking status, medical history, coverage amount, policy type, term length, and the insurer’s underwriting guidelines.

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Factors affecting life insurance cost in Canada

The cost of life insurance in Canada is mainly driven by factors like age, gender, health, coverage amount, and more. Some of these factors include: 

  • Age: The age of the individual directly affects the life insurance cost. The older the individual, the higher the premium
  • Gender: Life insurance costs may vary by gender, with women generally paying lower premiums than men
  • Coverage amount: The higher the coverage amount you choose, the higher the life insurance rates will be
  • Health: An individual’s health also affects life insurance rates. A healthy individual, compared to someone with a history of medical conditions, qualifies for lower rates
  • Smoking status: Any insurance company in Canada will charge a higher premium if you are a smoker. This is because the health risks associated with smoking are higher than those for a non-smoker
  • Lifestyle: If you are involved in high-risk activities as a result of your hobby or occupation, then the insurer views you as higher risk. This increased liability will also result in you paying higher premiums
  • Insurer: Life insurance rates can vary between insurers because each company has its own underwriting guidelines, pricing, and risk assessment

Why do men pay more for life insurance than women?

Men pay higher premiums than women because insurers consider life expectancy and mortality risks when setting life insurance premiums. Generally, men have lower life expectancy than women, which can increase the insurer’s expected cost of providing coverage over the policy term. Moreover, the exact difference in premiums will also vary depending on the insurer and their underwriting rules, along with the other factors listed above.

Learn more about the different types of life insurance in Canada
life insurance cost

Life insurance costs by policy type

The type of policy you choose is one of the biggest factors affecting your life insurance rates. In general, term life insurance is the most affordable option, while permanent policies, such as whole life insurance, cost more because they provide lifelong coverage and can build cash value. No-medical life insurance also tends to have higher premiums since insurers assume more risk by offering coverage without requiring a medical exam.

What is the cost of term life insurance in Canada?

The cost of term life insurance in Canada with $500,000 in coverage can range from $14 to $200 per month, depending on the applicant’s age, gender, and health. Because term life insurance provides coverage for a fixed period and does not build cash value, it is the most affordable type of life insurance. It is well-suited for individuals and families looking to protect their income, cover a mortgage, or provide financial security during their highest-earning years.

Term life insurance cost in Canada

Age Male Female
20 years $22 $14
30 years $22 $15
40 years $27 $19
50 years $61 $45
60 years $200 $145

*Illustrative monthly cost of term life insurance for a 10-year period for individuals of various ages with $500,000 in coverage

What is the cost of whole life insurance in Canada?

In Canada, participating whole life insurance with $100,000 in coverage costs between $139 and $382 per month, whereas a non-participating policy may cost between $71 and $320 per month, depending on the applicant’s age and insurer. The cost of whole life insurance is generally several times more expensive than an equivalent term life policy because it provides lifelong coverage and builds cash value. 

Participating whole life insurance may also pay policy dividends, depending on the insurer’s dividend performance. It is commonly chosen for estate planning, wealth transfer, tax-advantaged savings, and leaving a guaranteed financial legacy.

Cost of whole life insurance in Canada

Age Participating ($100k coverage) – Paid Up additions Non-participating ($100k coverage)
20 years $139 $71
30 years $178 $100
40 years $229 $142
50 years $293 $224
60 years $382 $320

*Illustrative monthly costs for a male individual of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

What is the cost of a no-medical life insurance policy in Canada?

The cost of a 20-year no-medical life insurance policy with $500,000 in coverage ranges from $39 to $380 per month. While no-medical policies offer faster approval and do not require a medical exam, they generally cost more than fully underwritten life insurance because insurers take on greater underwriting risk. These policies are often suitable for individuals with pre-existing health conditions, those who may not qualify for traditional life insurance, or applicants who need coverage quickly.

Cost of a no-medical life insurance policy

Age Male Female
20 years $50.40 $39.15
30 years $54.90 $45.90
40 years $52.65 $41.40
50 years $105.30 $87.75
60 years $380.25  $280.35

*Illustrative monthly cost of a 20-year no-medical plan with $500,000 in coverage

Life insurance rates chart by coverage amount

The amount of term life insurance coverage you choose has a direct impact on your monthly premium. Higher coverage amounts generally cost more, although the premium increase is not always proportional. The cost of a $100,000 term life insurance policy will be much lower than that of a $250,000 term life policy. The coverage amount in the section below details the cost of different coverage amounts in Canada.

How much does a $100,000 life insurance policy cost?

A $100,000 term life insurance policy in Canada costs approximately $7 to $44 per month. While premiums remain relatively affordable for younger applicants, they increase significantly with age due to the higher insurance risk. A $100,000 policy may be suitable for people looking to cover final expenses, smaller debts, or supplement existing life insurance. However, it may not provide enough coverage for someone with a mortgage, dependents, or significant income replacement needs.

Cost of a $100,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $9.45 $7.71
30 years $9.45 $8.19
40 years $10.53 $9.72
50 years $18.00 $15.12
60 years $44.10 $33.57

*Illustrative monthly cost of term life insurance for a 10-year plan with $100,000 in coverage for a male/female non-smoker

How much does a $250,000 life insurance policy cost?

The cost of a $250,000 term life insurance policy ranges from approximately $10 to $98 per month. A $250,000 coverage is a popular choice for individuals and families looking to cover obligations such as a portion of their mortgage, income replacement, children’s education costs, outstanding debts, or other long-term expenses.

Cost of a $250,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $13.94 $10.35
30 years $13.94 $10.58
40 years $16.87 $13.50
50 years $34.20 $26.55
60 years $98.33 $71.55

*Illustrative monthly cost of term life insurance for a 10-year plan with $250,000 in coverage for male/female non-smoker

How much does a $500,000 life insurance policy cost?

A $500,000 term life insurance policy costs between $13 and $177 per month for healthy non-smokers. The exact premium will vary, with younger applicants typically qualifying for significantly lower rates. A $500,000 coverage can help cover major financial obligations.

Cost of a $500,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $21.60 $13.95
30 years $21.60 $14.85
40 years $26.55 $18.90
50 years $57.60 $44.55
60 years $176.85 $133.20

*Illustrative monthly cost of term life insurance for a 10-year plan with $500,000 in coverage for male/female non-smoker

How much does a $1,000,000 life insurance policy cost?

The cost of a life insurance policy with $1,000,000 in coverage is between $21 and $330 per month. This coverage amount is commonly chosen by high-income earners, homeowners, parents with young children, business owners who need substantial coverage to replace income, pay off significant debts, fund future education costs, or leave a substantial financial legacy.

Cost of a $1,000,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $35.99 $21.15
30 years $35.54 $22.95
40 years $45.90 $31.05
50 years $108.00 $78.75
60 years $330.30 $253.80

*Illustrative monthly cost of term life insurance for a 10-year plan with $1,000,000 in coverage for male/female non-smoker

How much does a $10,000,000 life insurance policy cost?

The rates for life insurance with $10,000,000 in coverage range from $166 to $3,276 per month. Premiums are substantially higher than those for lower-value policies because the insurer assumes a much larger financial risk. A $10,000,000 life insurance policy is suitable for high-net-worth families, business owners, executives, and professionals with significant financial obligations, business succession needs, or those with complex estate planning goals.

Cost of a $10,000,000 life insurance policy

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $310.50 $166.50
30 years $310.50 $184.50
40 years $426.60 $292.50
50 years $1,044.00 $725.40
60 years $3,276.00 $2,394.00

*Illustrative monthly cost of term life insurance for a 10-year plan with $10,000,000 in coverage for male/female non-smoker

Find affordable life insurance with the right coverage.

Get the cheapest life insurance rates in Canada from top providers.

Life insurance costs by applicant category

Life insurance premiums can vary significantly depending on your personal circumstances and risk profile. In general, smokers, seniors, and individuals with health conditions tend to pay higher life insurance rates because they present a greater insurance risk. Couples may have the option to reduce costs through certain joint life insurance policies, although individual policies may be more cost-effective in some cases.

How much is life insurance per month for smokers and non-smokers?

The cost of $500,000 in term life insurance for smokers ranges from $42 to $504 per month, while comparable coverage for non-smokers ranges from $21 to $177 per month. Smokers pay premiums that are often 2 to 4 times higher than non-smokers because tobacco and nicotine use are associated with a higher risk of serious health conditions, including heart disease, stroke, and cancer. 

The difference in premiums becomes more noticeable with age, as the combined impact of smoking and age increases an insurer’s expected risk. Quitting smoking can significantly reduce your premiums, but most insurers require you to remain tobacco-free for at least 12 months before you may qualify for non-smoker rates. The required tobacco-free period may vary by insurer. 

Cost of life insurance for smokers and non-smokers (male) for varying age groups

Age Smoker Non-smoker
30 years $42.30 $21.60
40 years $63.00 $26.55
50 years $180.45 $57.60
60 years $503.55 $176.85

*Illustrative monthly costs for a male individual seeking $500,000 in life insurance coverage for a 10-year policy

How much is life insurance per month for seniors?

The cost of $100,000 in term life insurance for male seniors ranges between $18 and $267 per month, while comparable coverage for female seniors is between $15 and $179 per month. Female applicants generally pay lower premiums than male applicants because they tend to have a longer life expectancy. As you get older, the costs for life insurance for seniors increase due to the higher likelihood of health issues and claims during the policy term.

Cost of life insurance for seniors

Age Male Female
50 years $18.00 $15.12
55 years $26.28 $22.32
60 years $44.10 $33.57
65 years $76.41 $53.73
70 years $133.29 $92.34
75 years $267.48 $178.92

*Illustrative monthly costs for non-smoker seniors in various age ranges seeking a term life insurance policy with $100,000 in coverage

How much is life insurance per month for children?

Children’s whole life insurance typically starts at around $100 per month. Whole life insurance policies for children provide lifelong coverage and can build cash value over time, making them a long-term financial planning tool as well as a source of insurance protection.

Cost of whole life insurance for a female child

Age Monthly premiums Accumulated cash value Death benefit
5 years $100 $0 $180,200
20 years $100 $16,400 $180,200
35 years No payment of premiums after the first 20 years $50,000 $250,000
50 years $130,000 $400,000
70 years $408,000 $713,000

*Illustrative accumulated cash value and death benefit for a $100/month, 20-pay participating whole life insurance policy issued to a healthy 5-year-old girl. Projected cash values and death benefits assume current dividend scales and are not guaranteed; the actual policy values may vary

Cost of whole life insurance for a male child

Age Monthly premiums Accumulated cash value Death benefit
5 years $100 $0 $159,200
20 years $100 $17,000 $159,200
35 years No payment of premiums after the first 20 years $50,000 $218,000
50 years $129,000 $347,000
70 years $401,000 $634,000

*Illustrative accumulated cash value and death benefit for a $100/month, 20-pay participating whole life insurance policy issued to a healthy 5-year-old boy. Projected cash values and death benefits assume current dividend scales and are not guaranteed; the actual policy values may vary

How much is life insurance per month for couples?

The cost of $500,000 in term life insurance for couples typically ranges from $33 to $550 per month for non-smoking couples and from $76 to $1,283 per month for smoking couples. Couples can choose between two individual life insurance policies or a joint life insurance policy, with the latter potentially offering lower premiums in certain situations. Joint policies also simplify policy management by covering both partners under a single contract. However, individual policies may provide greater flexibility and, in some cases, better value depending on the couple’s coverage needs.

Cost of life insurance in Canada for smoking and non-smoking couples

Age group Monthly premium (Non-smoking couples) Monthly premium (Smoking couples)
35 years $33 $76
45 years $64 $185
55 years $168 $518
65 years $550 $1,283

*Quotes based on a $500,000 joint term policy in coverage for smoker and non-smoker couples in regular health seeking coverage for a 10-year term

Life insurance costs by insurance company

The cost of term life insurance from Canada’s leading insurers typically ranges from $14 to over $230 per month for the sample policy shown below. Premium differences occur because each insurer uses its own underwriting guidelines, pricing models, and risk assessment criteria. As a result, two insurers may offer different premiums for the same applicant and coverage amount.

The table below compares illustrative monthly premiums from some of Canada’s leading insurance companies for the same applicant profile.

Life insurance monthly costs by insurer

Applicant age Sun Life Manulife Empire Life Equitable Life Canada Life
20 years Male: $25.20
Female: $16.65
Male: $25.71
Female: $17.06
Male: $22.05
Female: $14.40
Male: $22.04
Female: $14.84
Male: $68.40
Female: $16.19
30 years Male: $25.65
Female: $17.55
Male: $23.28
Female: $16.84
Male: $22.05
Female: $15.30
Male: $22.04
Female: $15.74
Male: $23.38
Female: $16.63
40 years Male: $31.95
Female: $23.40
Male: $29.13
Female: $22.66
Male: $27.00
Female: $19.35
Male: $26.99
Female: $19.79
Male: $29.98
Female: $24.00
50 years  Male: $72.00
Female: $51.30
Male: $67.16
Female: $48.37
Male: $61.65
Female: $45.90
Male: $61.28
Female: $45.89
Male: $67.12
Female: $53.28
60 years Male: $230.85
Female: $161.55
Male: $213.74
Female: $151.20
Male: $199.80
Female: $144.45
Male: $199.78
Female: $144.44
Male: $203.58
Female: $147.43

*Illustrative monthly cost of a 10-year term with $500,000 in coverage for a male/female non-smoker

How does term length affect life insurance premiums?

The cost of term life insurance ranges from about $22 to $144 per month in the example below, depending on your age and the length of the policy. For the same applicant and coverage amount, 10-year term policies are the most affordable, while 20-year and 30-year terms cost more because they provide coverage for a longer period and increase the likelihood of a claim during the term.

Cost of life insurance as per term length

Age 10-year term 20-year term 30-year term
30 years $22.04 $28.80 $42.75
35 years $22.04 $30.15 $53.55
40 years $26.99 $42.75 $85.05
45 years $40.05 $69.30 $143.92

*Illustrative monthly cost of a 10-year, 20-year, and 30-year term life insurance with $500,000 in coverage for a male non-smoker

Do life insurance premiums increase over time?

It depends on the type of life insurance policy. Term life insurance premiums are usually fixed for the length of the term, so your premium generally does not increase during that period. With annually renewable term insurance, premiums can increase each year. On the other hand, whole life insurance premiums are fixed for the life of the policy.

How much life insurance do I need to buy?

The right life insurance coverage depends on your financial responsibilities, income, debts, and family’s needs. Here’s how to estimate the amount:

  • Income replacement: Aim for 7-10 times your annual income. For instance, if you have an annual salary of $70,000, your life insurance coverage should range between $500,000 and $700,000
  • Debt & expenses: The payout should cover the mortgage, loans, funeral costs, and daily living expenses for dependents
  • Future needs: Consider childcare, education, and long-term financial security for your family
  • DIME formula (Debt, Income, Mortgage, Education): Use the DIME formula and add up these expenses for a tailored estimate
  • Affordability: Balance coverage with budget to make sure you purchase a plan that you can afford to pay for

Do individuals with pre-existing health issues pay higher life insurance premiums?

Yes, individuals with pre-existing health conditions generally pay higher life insurance premiums because they pose a greater risk to insurers. The exact increase depends on the type and severity of the condition, how well it is managed, your age, and the insurer’s underwriting guidelines. In some cases, applicants may still qualify for standard premium rates if their condition is stable and well-managed.

Depending on your medical history, insurers typically make one of the following underwriting decisions:

  • Standard premiums: If your condition is minor, stable, and well-managed, you may qualify for standard rates
  • Higher (rated) premiums: If your condition increases the insurer’s risk, you may be approved with a higher premium or an additional rating applied to your policy
  • Guaranteed issue or no-medical life insurance: If you are declined for traditional life insurance due to a serious medical condition, you may still qualify for guaranteed issue or no-medical life insurance. These policies don’t require a medical exam but generally come with higher premiums and lower coverage limits

Which is cheaper: term life or whole life insurance?

Term life insurance is cheaper than whole life insurance because it provides coverage for a set period, such as 10, 20, or 30 years, without building cash value. Whole life insurance provides lifelong coverage and may build cash value, so its premiums are higher. Both serve different financial needs; hence, you should consider other features when choosing the policy type. 

Is life insurance worth the cost in Canada? 

Yes, life insurance is worth the cost in Canada if you have financial dependants or have ongoing loans or any other financial obligations. The value depends on your financial situation and coverage needs. Term life insurance may provide affordable protection for temporary needs, while whole life insurance can offer lifelong coverage and additional features.

10 ways to lower your life insurance premiums

There are several ways to reduce the cost of your life insurance premiums, such as maintaining a healthy lifestyle, choosing the right policy, comparing quotes from multiple insurers, and more. Listed below are the factors that will help you lower life insurance premiums:

  • Buy life insurance early: Purchasing a policy when you are younger and in good health can help you lock in lower premiums for the duration of your coverage.
  • Quit smoking: Most insurers offer significantly lower premiums to applicants who have remained tobacco-free for at least 12 months
  • Maintain good health: Managing your weight, blood pressure, and other health conditions can improve your eligibility for preferred rates
  • Choose the right coverage amount: Buy enough coverage to meet your financial needs without paying for more insurance than necessary
  • Opt for term life insurance: If you only need coverage for a specific period, term life insurance is generally much more affordable than permanent life insurance
  • Consider laddering life insurance policies: Instead of purchasing one large policy, you can combine multiple term life policies with different coverage amounts and durations. This allows your coverage to decrease as your financial obligations reduce, helping lower overall premium costs.
  • Choose riders carefully: Only add optional riders, such as critical illness, child, or disability riders, if they meet a specific need. Unnecessary riders can increase your premium
  • Select a shorter policy term: Shorter term lengths usually cost less than longer-term policies with the same coverage amount
  • Pay your premiums annually: You may reduce your overall cost when you pay annually instead of making monthly payments
  • Compare quotes from multiple insurers: Compare and find the best life insurance policy for your needs

To get the most affordable life insurance quotes, reach out to our expert advisors at PolicyAdvisor. Our advisors will help you get quotes from the top life insurance providers in Canada and choose the one that best fits your needs and budget.

Looking for expert assistance?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently Asked Questions

What are life insurance premiums?

Life insurance premiums are the payments policyholders make to maintain their coverage. They can be paid monthly, quarterly, or annually, depending on the policy. The cost of your premium will be based on factors like age, health, smoking status, coverage amount, policy type, and the insurer.

What is the average cost of life insurance in Canada?

The cost of life insurance in Canada starts at around $7 per month for a healthy young adult purchasing a basic term insurance policy. The premiums can range from $7 to over $3,276 per month, depending on your age, health, coverage amount, policy type, and insurer.

What is the cheapest life insurance in Canada?

Term life insurance is generally the cheapest life insurance in Canada. Because it provides coverage for a fixed period and does not build cash value, premiums are significantly lower than those for whole life or universal life insurance.

Why are life insurance premiums different for men and women?

Life insurance premiums are generally higher for men because, on average, men have a shorter life expectancy than women. Insurers use actuarial data to estimate risk, which results in lower premiums for female applicants with similar health and lifestyle profiles.

Is it cheaper to buy life insurance when you are younger?

Yes, buying life insurance at a younger age usually results in lower premiums because younger applicants generally have fewer health risks and a longer life expectancy. Purchasing coverage early can help lock in lower rates for the duration of your policy.

Can I get life insurance without a medical exam?

Yes, many insurers offer no-medical or simplified issue life insurance that does not require a medical exam. These policies are easier and faster to obtain but usually have higher premiums and lower coverage limits than fully underwritten life insurance.

How much life insurance do I need?

The amount of life insurance you need depends on your income, financial obligations, and future goals. While it is recommended to get coverage equal to 10-15 times your annual income, the ideal amount varies based on factors such as your mortgage, outstanding debts, living expenses, your children’s future education costs, and any existing savings or life insurance coverage. The easiest way to determine the right amount is to use our life insurance calculator, which estimates your coverage needs based on your unique financial situation and helps you choose a policy that provides adequate protection for your loved ones.

What is the cost of $100,000 term life insurance?

The cost of $100,000 term life insurance for a male non-smoker ranges from  $9 to $44 per month. For females, it can range from $7 to $33 per month. You can compare quotes from multiple insurers to find a policy that fits your coverage needs and budget.

Why does life insurance cost vary by insurer?

Life insurance premiums can vary between insurers because each company uses its own underwriting guidelines and risk assessment. Two insurers may assess the same applicant differently based on factors such as age, health history, occupation, smoking status, and coverage amount. 

Can I be denied term life insurance based on age?

Yes, age can affect whether you qualify for term life insurance, as insurers typically set minimum and maximum age limits for new applicants. Older applicants may have fewer term options available, higher premiums, or may not qualify for certain policy terms. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What are life insurance premiums?

A life insurance premium is the amount you pay the insurer to keep the policy active. The payment can be made monthly or annually. If you stop paying your premiums, your life insurance policy enters a grace period before it lapses. If the overdue premium is not paid within this period, the policy may lapse, and your coverage will end. The exact premium you need to pay is calculated on the basis of different factors such as your age, health history, coverage chosen, demographics, and a few other factors.

Life insurance can be affordable!

Get the best life insurance quotes in Canada!

How are life insurance premiums calculated in Canada?

The cost of life insurance premiums varies greatly from policy to policy, largely because premiums take many different factors into account, such as the insured’s age, health, and lifestyle, as well as policy type (term or whole), length, and size.

Personal factors affecting life insurance premiums

Looking first at how the insured influences policy premiums, the main things that a life insurance company will look at are age, health, gender, and smoking status. 

  • Age: It is recommended you get life insurance coverage earlier in life because premiums will be at their lowest. A healthy 30-year-old male (non-smoker) can pay as little as $9/month for a 10-year term policy with $100,000 in coverage. At the age of 60, the same coverage would cost $44/month
  • Health: Health also factors in. To minimize their risk, life insurance companies can charge higher premiums to those with pre-existing conditions that could become life-threatening. Many life insurance policies require a medical exam for underwriting, which tests for blood pressure, cholesterol, hypertension, and more. There are no medical exam options for life insurance policies, though premiums for this type of coverage are generally higher across the board
  • Gender: Gender will also determine how much you pay for a life insurance policy because the life expectancy for women is higher; they tend to pay less in life insurance premiums than men
  • Smoking status: Whether you smoke or not will have a big influence on how much you pay for life insurance premiums. Smoking has adverse effects on health and is directly linked to many life-threatening medical conditions, so smokers pay significantly higher premiums. A 30-year-old non-smoker can pay $21.60 for $500,000 in life insurance coverage for a 10-year policy, while a smoker of the same profile ends up paying $42.30, which is double
  • Lifestyle habits and occupation: High-risk activities, hazardous occupations, frequent travel, alcohol or drug use, and other lifestyle factors may affect eligibility or premiums. The effect depends on the activity, frequency, and insurer’s underwriting rules.

Policy factors affecting life insurance premiums

Beyond the details of the insured person, policy type and coverage also help to determine how much you pay in premiums. 

  • Policy type: A term life insurance policy will typically have lower premiums than a permanent life insurance policy, because the latter offers coverage for your entire life. For example, a term life insurance policy with $100,000 in coverage for a 20-year-old non-smoker male can cost as low as $9 per month, while the same coverage for a non-participating whole life insurance policy can cost $70 per month
  • Coverage amount: The more coverage you get, the higher your premiums will be. For example, a policy with a $250K death benefit will cost less than a policy with a $1M benefit
  • Term length: For term insurance, longer coverage periods can cost more because the insurer is protecting longer. The premium may remain level during the initial term but can increase when the policy renews unless the policyholder converts, replaces, or terminates the coverage
  • Premium structure: Permanent policies can have different premium-payment periods and features that affect their cost. For instance, 20-pay whole life insurance will be cheaper than a 10-pay policy. This is because the premiums for 20-pay are spread over a longer duration
  • Optional benefits or riders: Optional benefits added to a policy can increase the overall premium. Examples include child coverage, waiver of premium, guaranteed insurability, accidental death benefits, and other policy-specific add-ons

You can use our life insurance calculator to get an idea of how much insurance coverage you might need, and get instant quotes to find out what your premiums would be.

How much is a life insurance premium: Term vs. whole life insurance costs

As mentioned, life insurance premiums in Canada vary widely depending on your age, health, smoking status, coverage amount, policy type, and insurer. For a $100,000 policy, costs can range from about $7 to $44 per month for term life insurance, while whole life insurance can range from about $57 to $382 per month.

Cost of a $100,000 term life insurance policy:

Age (in years) Male (non-smoker) Female (non-smoker)
20 years $9.45/month $7.71/month
30 years $9.45/month $8.19/month
40 years $10.53/month $9.72/month
50 years $18.00/month $15.12/month
60 years $44.10/month $33.57/month

*Illustrative term life insurance cost of a 10-year plan with $100,000 in coverage for a male/female non-smoker

Cost of $100,000 whole life insurance policy:

Age (in years) Male (Non-participating) Male (Participating) Female (Non-participating) Female (Participating)
20 $70.74/month $138.42/month $57.24/month $118.89/month
30 $100.35/month $177.84/month $88.74/month $156.15/month
40 $141.66/month $228.96/month $127.53/month $207.00/month
50 $223.83/month $292.23/month $181.71/month $270.81/month
60 $319.41/month $382.14/month $277.92/month $351.81/month

*Illustrative monthly premiums for non-smoking males and females of various age ranges seeking a whole life insurance policy with $100,000 in coverage for a 20-pay premium option

More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Which has cheaper premiums: term life or whole life insurance?

Term life insurance is generally cheaper because it provides coverage for a fixed period, such as 10, 20, or 30 years, while whole life insurance is designed to provide lifetime coverage and can build cash value. 

Whole life premiums account for the insurer providing a death benefit for life, along with the policy’s cash value component and, for participating policies, potential dividends. Hence, the premiums for a whole life insurance policy will be comparatively higher.

However, the cheapest option is not automatically the most suitable; choose based on the length of coverage you need, your financial goals, and your budget.

Who pays my life insurance premium?

Whether monthly or annually, life insurance premiums are paid by the policyholder. For individual policies, this usually means that the insured will pay their own premiums. 

However, a person may own a policy on someone else. For instance, if you have life insurance coverage through workplace benefits, your employer will pay the policy premiums. If a child has life insurance coverage, the premiums are likely being paid by a parent or grandparent. A policyholder may also pay premiums for their spouse or ex-partner, depending on separation agreements.

Are life insurance premiums refundable?

No, life insurance premiums are generally not refundable once paid. However, you may receive a refund in certain situations, such as cancelling a policy during the free-look period. The free-look period for life insurance policies in Canada is generally 10 days. The amount and eligibility for refunds depend on the policy terms and insurer.

Are life insurance premiums tax deductible?

No, life insurance premiums are generally not tax-deductible in Canada for individual life insurance. The Canada Revenue Agency (CRA) considers these insurance premiums a personal expense, and hence they are not tax-deductible. There are limited exceptions, such as certain business-owned life insurance policies used as collateral for a business loan, where a specific portion may be considered tax-deductible.

Will life insurance premiums increase with time?

Whether or not the life insurance premium will increase with time depends on the policy you have bought. The premiums for a term life insurance policy stay the same during the entire term; however, they can increase when the policy is renewed, depending on the policy’s renewal terms. On the other hand, whole life insurance plans have premiums that remain level if you pay the premiums on time. 

What is the difference between a premium, death benefit, and cash value?

The three terms describe different parts of a life insurance policy:

  • Premium: The amount you pay monthly, annually, or according to your policy’s payment schedule
  • Death benefit: The amount your beneficiaries receive after your death
  • Cash value: The accumulated value of certain permanent policies, such as whole life and universal life insurance. Term life insurance does not have cash value

Where do I find quotes for insurance premiums?

You can compare life insurance quotes from multiple Canadian insurers with PolicyAdvisor. Our licensed advisors can help you compare premiums based on your age, health, coverage needs, and policy type, rather than looking at a single insurer’s premium. You can also get personalized life insurance quotes and discuss your options before choosing a policy. Schedule a call now to get started!

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions 

What happens when I stop paying life insurance premiums?

If you stop paying your life insurance premiums, the policy may eventually lapse, and your coverage can end. Most policies have a grace period to allow you to make a missed payment, while permanent life insurance may have options such as using the policy’s cash value to cover premiums, depending on the contract.

How accurate are life insurance calculators for premiums?

A life insurance calculator can give you a very good idea as to how much you will pay in premiums for a given policy. The more accurately you answer initial questions, the more accurate your quote will be. It is wise to expect some degree of variation, however, because the underwriting process can reveal additional risk factors that can influence premiums.

Can you pay insurance premiums with a credit card?

Yes, you can pay life insurance premiums via a credit card in Canada. But the exact payment and credit card requirements will vary from insurer to insurer. 

Can I lower my life insurance premiums?

Yes, you may be able to lower your life insurance premiums. Some of the useful tips to lower the premiums include choosing an appropriate coverage amount and policy term, maintaining good health, avoiding tobacco and nicotine use, avoiding unnecessary riders, and comparing quotes from multiple insurers. 

Are life insurance premiums cheaper for non-smokers?

Yes, non-smokers pay lower life insurance premiums than smokers because insurers consider tobacco and nicotine use when assessing mortality risk. The exact difference also depends on factors such as your age, health, coverage amount, policy type, and the insurer’s underwriting rules.

How much is life insurance in Canada per month?

The average cost of life insurance in Canada depends on the policy you choose. For term life insurance, it ranges from $7 to $44 per month for $100,000 coverage. On the other hand, for whole life insurance, it will range from $57 to $382 per month for $100,000 coverage and 20-pay policy. 

Why can two people pay different premiums for the same coverage?

Two people can pay different premiums for the same amount of life insurance because insurers assess each applicant’s age, health, smoking status, occupation, lifestyle, policy type, and coverage term differently. Insurers may also use different underwriting guidelines and pricing, so premiums can vary even when the coverage amount is the same.

How often do you pay life insurance premiums?

Life insurance premiums are typically paid monthly or annually, although some insurers may offer other payment frequencies. Your payment schedule depends on the policy and insurer. Paying annually may sometimes result in a lower total cost than making monthly payments, depending on the insurer’s payment terms.

What happens to premiums if I convert term insurance to permanent insurance?

When you convert a term life insurance policy to permanent insurance, your premium will generally increase because permanent insurance provides lifelong coverage and may include a cash value component. The new premium depends on the permanent policy you choose and the insurer’s conversion terms. Depending on the policy, you may be able to convert without providing new medical evidence.

Is a life insurance quote the same as the final premium?

No, a life insurance quote is not the same as the final premium. A life insurance quote is an estimate of your expected premium based on the information provided when you request the quote. The final premium is determined after the insurer completes its underwriting process. Your final premium may therefore be higher, lower, or the same as the initial quote.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Canada Life whole life insurance review (2026)

Canada Life is one of Canada’s leading providers of participating whole life insurance. Its current lineup includes Wealth Achiever, Balanced Achiever, and Estate Achiever, giving policyholders options designed around different priorities, from earlier cash value growth to long-term estate value. All three plans provide lifelong coverage and offer guaranteed premium payment options of Max 10, Max 20, and Pay to age 100. Canada Life also offers a unique participating plan, My Par Gift, which is designed in a way that the designated charity receives the death benefits. 

Quick review:

  • PolicyAdvisor ratings: 5/5
  • Best for: Those who want a choice between three participating whole life strategies, from early cash value to balanced growth or long-term estate value, plus dedicated charitable giving through My Par Gift
  • Skip if: You are looking for a standalone non-participating whole life plan
Affordable Coverage for You and Your Loved Ones

Find the lowest whole life insurance rates in Canada within minutes!

About Canada Life

Canada Life has the largest participating account in Canada, and its participating life insurance policies maintain a dividend scale interest rate of 6.00% for 2026. Additionally, Canada Life has consistently paid dividends since 1848, and its participating account has never missed a distribution year. This is a remarkable record that reflects the insurer’s financial resilience and reliability across economic cycles.  Canada Life is a member of Assuris, an organization that protects the policyholders against the loss of benefits if a member life insurance company fails financially.

Canada Life’s financial strength:

AM Best Rating A+
Participating account fund size $62.8 billion
LICAT ratio 130%
Dividend scale interest rate (DSIR) 6.00%

Disclaimer: Figures and ratings are based on the latest available information and may change over time

What is Canada Life whole life insurance?

Canada Life whole life insurance provides permanent life insurance coverage that can remain in place for your lifetime. Its participating whole life insurance lineup includes three participating whole life insurance products: Wealth Achiever, Balanced Achiever, and Estate Achiever. Each is designed around a different priority: stronger early cash value accumulation, a balance of cash value and long-term death benefit value, or a greater focus on long-term estate value. 

Canada Life offers My Par Gift plan, a participating life insurance product specifically designed for charitable giving. It requires a single premium payment, is owned by the registered charity, and builds cash value over time. 

Key features of Canada Life whole life insurance:

Plan names
  • Wealth Achiever
  • Balanced Achiever
  • Estate Achiever
  • My Par Gift
Policy issue age (min & max) Wealth, Balanced, Estate Achiever:

  • Max 10: 0-85 years
  • Max 20: 0-80 years
  • Pay to age 100: 0-85 years
  • Juvenile policies: 0-17 years

My Par Gift: 18-75

Minimum coverage amount $25,000

$10,000 for My Par Gift single premium

Coverage options
  • Single life
  • Joint first to die
  • Joint last to die

My Par Gift: can insure more than one person

Payment options
  • Max 10
  • Max 20
  • Pay to age 100

My Par Gift: One time single premium that fully pays up the policy

Dividend options
  • Cash payment
  • Paid-up additional coverage
  • Enhanced coverage
Additional benefits
  • Premium offset with full, variable, or level offset options
  • Additional deposit option (ADO)

My Par Gift: Registered charity owns and controls the policy and can access the policy’s cash value through a loan or withdrawal

Riders
  • Term benefit 10/20/30 rider
  • Child’s term life insurance rider
  • Accidental death benefit rider
  • Guaranteed insurability rider 
  • Business growth protection rider
  • Death and disability waiver of premium benefits

The riders are not applicable to My Par Gift

Who is eligible for Canada Life whole life insurance?

Canada Life whole life insurance is available to a wide range of applicants, with eligibility primarily determined by age, coverage amount, policy structure, and underwriting requirements.

  • Age eligibility: The age for Canada Life whole life insurance will vary depending on the payment period you choose:

– Max 10: Ages 0-85 for single-life coverage and 18-85 for joint-life coverage

– Max 20: Ages 0-80 for single-life coverage and18-80 for joint-life coverage

– Pay to 100: Ages 0-85 for single-life coverage and 18-85 for joint-life coverage

– Children under age 18 may be eligible for juvenile coverage

  • Coverage amount: You will be eligible for Canada Life’s participating whole life insurance policy if you choose minimum coverage of $25,000
  • Underwriting requirements: You must meet the underwriting requirements of Canada Life, such as health, medical history, lifestyle, and financial circumstances

What are the benefits of Canada Life’s whole life insurance?

Canada Life’s whole life policies provide lifelong coverage while building guaranteed cash value that you can use during your lifetime. They also allow you to pay off your policy quickly (in 10 or 20 years) or spread payments over a longer period of time (until age 100). Key benefits include:

  • No maximum coverage: Canada Life’s whole life policies have no set upper limit, meaning you can get as much coverage as you need, subject to financial underwriting. However, amounts over $50 million require special underwriting
  • Multiple dividend options: Dividends can be received in the form of cash payments, paid-up additions, and enhanced insurance. Dividends are not guaranteed
  • Additional deposit option (ADO): You can increase your policy’s coverage and cash value by making extra payments. However, ADO is subject to MTAR limits, so excess payments may be restricted once the policy is close to the tax-exempt shelf
  • Flexibility with premium offset: You can cover some or all of your premium payments using dividends. However, you must bear in mind that premium offset is not guaranteed and depends on participating account performance and available dividends.
  • Optional coverage: Canada Life lets you customize your whole life insurance policy with a range of riders, including term benefit rider, child’s term life insurance rider, accidental death benefit rider, guaranteed insurability rider, business growth protection rider, and death and disability waiver of premium benefits

Types of whole life insurance offered by Canada Life

Canada Life offers three participating whole life insurance plans and a unique My Par Gift plan. 

  • Wealth Achiever: Designed for lifelong insurance protection with a focus on strong early cash value accumulation. This plan also gives you the flexibility to access the cash value as your financial needs evolve
  • Balanced Achiever: It provides a balance between cash value growth and long-term payout on death. It offers greater flexibility than the Estate Achiever plan and greater long-term wealth value than Wealth Achiever 
  • Estate Achiever: This permanent whole life insurance option is designed for maximizing long-term payout on death, making it particularly suited to long-term estate planning objectives
  • My Par Gift: A participating life insurance solution designed specifically for charitable giving. The charity is the policy owner, and they can use the dividends to get additional coverage or take them as cash

What are the pros and cons of Canada Life’s whole life insurance?

Canada Life’s whole life policies offer several benefits, from unlimited coverage to multiple payment and dividend options. However, they also have some limitations. Let’s take a closer look at them:

Pros Cons
Three options available: Wealth Achiever, Balanced Achiever, and Estate Achiever ADO payments may be restricted, including when the policy has a loan or is on premium offset
You can choose Max 10, Max 20, or Pay to age 100 Premium offset availability depends on the participating account’s earnings
Offers flexibility to increase coverage and cash value through the additional deposit option (ADO)
Allows you to offset some or all of your premiums using dividends 

What is the cost of Canada Life’s participating whole life insurance plan?

The cost of Canada Life’s participating whole life insurance plan ranges from $378 to $1021 for an individual seeking $100,000 in coverage for a participating whole life insurance for 20-pay policy. The actual cost will vary depending on your gender, health profile, age, and a few other factors.

Cost of Canada Life whole life insurance (2026):

Age (in years) Male Female
20 $406.35/month $378.90/month
30 $487.89/month $459.00/month
40 $587.52/month $552.24/month
50 $703.89/month $664.20/month
60 $843.12/month $793.80/month
70 $1,021.23/month $952.29/month

*Illustrating monthly cost of $100k coverage for a participating whole life insurance for 20-pay

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

What riders does Canada Life offer on their whole life plans?

Canada Life offers several additional benefits or riders on its whole life policies, including:

  • Death and disability waiver of premium benefits: Depending on the rider selected, required premiums may be waived if the person insured under the rider dies or becomes totally disabled according to the rider terms. The insured must become continuously disabled before the policy anniversary nearest their 60th birthday to qualify for the benefits
  • Accidental death benefit: Provides a higher payout if death is caused by certain types of accidents. This can help beneficiaries manage unexpected payments that may arise due to the covered accident
  • Guaranteed insurability rider: Allows you to obtain new permanent policies on the insured person without new evidence of insurability
  • Business growth protection rider: Allows you to purchase additional permanent policies on the insured person over a 10- or 15-year period. To qualify for this coverage, the business must be headquartered in Canada and must be in operation for at least 3 consecutive years
  • Children’s term life insurance rider: Provides term life insurance coverage for your children, including adopted and stepchildren. The minimum coverage amount available with this rider is $10,000, and the maximum is $25,000
  • Canada Life Term benefit: This rider provides additional temporary coverage if the insured dies during the policy term. The available terms include 10, 20, or 30 years, with features available like term conversion with reset

What are the coverage options available with Canada Life’s whole life insurance plans?

When it comes to coverage structures, Canada Life offers several options for Wealth Achiever, Balanced Achiever, and Estate Achiever, including:

  • Single life: Covers one person and pays a death benefit when the insured person dies
  • Joint-first-to-die: Covers two people under one policy and pays a death benefit when the first insured person dies. The surviving person remains covered for an additional 60 days, during which they can buy a new policy on their life, with no underwriting
  • Joint-last-to-die (premiums to first death): Covers two people with premiums payable until the death of the first insured person. Premium payments are higher under this plan
  • Joint-last-to-die (premiums to last death): Covers two people with premiums payable until the death of the second insured person. Premium payments are lower under this plan

What are the different limited-pay options offered by Canada Life?

Canada Life offers its participating whole life policies with three standard premium payment structures: 10-pay, 20-pay, and pay-to-age-100. The first two are true limited-pay designs, while pay-to-100 is a lifetime premium schedule that is often grouped with them as a third option. This is not applicable to My Par Gift plan.

  • Max 10 (10-pay): All required premiums are paid over 10 years. After year 10, the base policy is fully paid-up as long as no new riders or additional deposits are added
  • Max 20 (20-pay): Premiums are level and payable for 20 years. After year 20, the base policy becomes paid-up for life
  • Pay to age 100: Premiums remain level and continue until age 100. This is not a limited-pay option in the strict definition, but it is one of the three standard payment patterns available

Canada Life’s participating whole life insurance plan can be issued using any of the three premium schedules (Max 10, Max 20, or pay-to-100) for both single-life and joint-life structures. Policyholders can later use features such as premium offset, where dividends cover ongoing premiums, to reduce or eliminate out-of-pocket payments. Contractually, however, the three payment structures listed above are the available choices at issue.

What are the different whole life dividend options that Canada Life offers?

Canada Life offers three dividend options for its participating whole life policies, allowing policyowners to choose how any declared dividends are used:

  • Cash payments: Dividends can be received as cash payouts, providing immediate flexibility, though the amount received may be taxable depending on the policy’s adjusted cost basis
  • Paid-up additions: Dividends are used to buy paid-up additional permanent coverage, which increases the death benefit, guaranteed cash value, and future dividend-earning potential
  • Enhanced coverage: This option combines paid-up additions with a term insurance component, offering higher initial death benefit while gradually transitioning to permanent paid-up coverage as the policy matures

How are dividends for Canada Life’s participating policies distributed

Dividends in Canada Life’s participating policies are distributed based on the earnings of the participating (or “par”) account. This account combines premiums from all participating policyholders and invests them in a diverse portfolio of assets.

“Par” account earnings depend on several factors, including investment returns, policy cancellations, insurance claims, and operational costs. When the account outperforms expectations, Canada Life shares the excess earnings with policyholders through dividends. 

While dividends are not guaranteed and can vary, Canada Life has a strong track record of maintaining its dividend scale, having paid annual dividends at an interest rate of 5.25% to 6.00% over the past few years.

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%

How are Canada Life whole life insurance premiums invested?

Premiums from Canada Life participating whole life policies go into the participating account, which is invested across a diversified portfolio of assets. Canada Life manages this account with two investment objectives:

  • Provide stable, Long-term growth
  • Provide returns that are partially responsive to changing economic conditions

The account uses a disciplined asset–liability matching strategy to ensure that investment income can reliably support guarantees, cash values, and dividends.

Canada Life participating account: Asset mix (June 30, 2025)


Asset class % of Account What it means for policyholders
Fixed income (Total 60.0%) Stable returns that support guarantees
Public bonds 28.3% Long-term stability and predictable income
Private placements 14.9% Higher yield with controlled risk
Mortgages 9.8% Strong cash flow and diversification
Cash & equivalents 7.0% Liquidity for claims and guarantees
Non-fixed income (Total 30.7%) Helps support future dividend potential
Public equity 13.7% Market growth participation
Real estate 12.3% Inflation hedge and rental income
Private equity 4.7% Long-term growth with low correlation
Other assets 9.3% Derivatives and other holdings used for risk management


Source: Canada Life Combined Open Participating Account – June 30, 2025

Are “par” account investments affected by market conditions?

Yes. While Canada Life employs a long-term investment strategy and “smoothing” mechanism to spread investment gains and losses over several years, changes in interest rates, stock prices, and real estate can still affect the “par” account’s investments.

How can I access my Canada Life whole life cash value?

You can access your policy’s cash value through:

  • Cash withdrawals: You can withdraw part or all of your cash value. A full withdrawal will result in your policy’s cancellation
  • Policy loans: You can borrow against your cash value. However, you won’t be able to make Additional Deposit Option (ADO) payments while your loan is active
  • Collateral loan: You can use your policy as collateral for a loan or line of credit from a third-party lender, subject to the lender’s approval
  • Premium offset: If you have enough cash value, you can use it to pay part or all of your due premiums. Premium offset is not guaranteed

Our advisor’s take on Canada Life whole life insurance

One of our advisors recently worked with a 45-year-old business owner who wanted permanent life insurance that could protect their family while also building cash value they could potentially access later. The client also wanted to keep their business protected as it grew, making the ability to secure additional permanent coverage in the future an important consideration. They were particularly interested in a solution that could support both long-term estate planning and future business needs.

Client profile:

  • Age: 45-year-old non-smoking businessman
  • Coverage need: $1 million in permanent life insurance for family protection and long-term financial planning
  • Primary concern: Building cash value while maintaining flexibility to access policy funds and increase coverage as the business grows
  • Our comparison: We compared Canada Life’s participating whole life plans with products from other leading Canadian insurers, focusing on early cash value growth, guaranteed values, dividend options, premium flexibility, and access to policy value

Why Canada Life stood out:

  • Flexible access to cash value: Canada Life provides several ways to access policy value, including cash withdrawals, policy loans, collateral loans, and premium offset, giving the client flexibility as their financial needs change
  • Flexible dividend options: The client could choose how to use participating dividends, including taking them as cash, reducing premiums, purchasing paid-up additional coverage, or selecting enhanced coverage. This gave them greater control over how the policy could support their changing financial goals
  • Largest participating account in Canada: Canada Life has the largest participating account in Canada, with approximately $62.8 billion in assets. For the client, the size and established history of the account were important considerations when choosing a participating whole life policy
  • Business growth protection rider: As a business owner, the client could add this rider to purchase additional permanent life insurance in the future without having to provide new medical evidence. This gave an opportunity to increase their coverage as their business and financial needs evolved

How to apply for Canada Life’s whole life insurance with PolicyAdvisor?

You can get a personalized whole life insurance quote for Canada Life through PolicyAdvisor, where you can compare different plans and policies from Canada’s top providers. Schedule a free consultation with our licensed advisors to explore the best options to protect your legacy.

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Is Canada Life’s whole life insurance worth it?

Yes, Canada Life’s whole life insurance policy may be worth considering if you want lifelong protection with cash value growth that you can access in many ways. With Canada Life, you can also choose from multiple payment options, dividend options, cash value access, and riders. 

Does Canada Life offer participating policies with dividends?

Yes. Canada Life offers participating whole life policy plans. The available participating whole life insurance policies include Wealth Achiever, Balanced Achiever, and Estate Achiever. It also offers My Par Gift, a participating life insurance product designed specifically for charitable giving. Dividends are not guaranteed.

Do I need medical underwriting for a Canada Life whole life insurance plan?

Yes, Canada Life whole life applications are subject to underwriting, which can vary depending on the applicant and the coverage requested. If your policy includes the Guaranteed Insurability Rider, you may be able to apply for additional permanent life insurance on specified option dates without providing new evidence of insurability, including health.

How does the Canada Life participating account work?

Canada Life’s participating account pools premiums from all participating policyholders and invests them in a diversified portfolio of assets. The account’s earnings are influenced by various factors, including investment returns, mortality claims, policy cancellations, and operational expenses. Canada Life may distribute a portion of those earnings as policyowner dividends, although dividends are not guaranteed.

What is the children’s term life insurance rider?

The children’s term life insurance rider is an optional add-on to Canada Life’s whole life insurance policies. It provides term life coverage for your biological, adopted, and stepchildren. 

What happens if I stop paying my premiums?

If you miss a payment on your Canada Life whole life insurance policy, you have 31 days to make it up. If the premium remains unpaid after this period, Canada Life will automatically take out a policy loan on your behalf, provided your policy has enough cash value. This loan will keep your policy active as long as there’s sufficient cash value to cover future premiums and interest charges.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Wawanesa whole life insurance review (2026)

Wawanesa whole life insurance offers two participating permanent life insurance plans: 20 Pay Whole Life and Whole Life – Pay to Age 100. Both plans provide lifetime coverage, guaranteed level premiums, and guaranteed cash values; these cash values can begin accruing as early as the fifth policy year. Wawanesa is also one of the few insurers in Canada that prices premiums on the current age. The cost of Wawanesa whole life insurance for $100,000 in coverage ranges from $132 to $547 per month for a 20-pay premium option.

Quick review:

  • PolicyAdvisor ratings: 4/5
  • Best for: Straightforward whole life insurance policy
  • Skip if: You want more flexibility or more policy designs
Compare whole life quotes from Canada’s top insurers.

Talk to a licensed advisor today.

About Wawanesa Insurance

Wawanesa Insurance is one of Canada’s largest mutual insurers and is a subsidiary of The Wawanesa Mutual Insurance Company. As a mutual insurer, it is owned by its policyholders and operates with a focus on their long-term interests. Through Wawanesa Life, it offers term life insurance, whole life, critical illness insurance, group insurance, and investment solutions. 

Wawanesa Life’s participating whole life insurance stands out for its straightforward structure. Its participating account currently has a 6.00% dividend scale interest rate, with dividends available for options such as paid-up additions or cash payments.

Wawanesa Insurance’s financial strength:

AM Best Rating A
Annual revenue $4.1 billion (Wawanesa Mutual Insurance Company)
LICAT ratio 167%
Dividend scale interest rate (DSIR) 6.00%

Disclaimer: Figures and ratings are based on the latest available information and may change over time

What is Wawanesa whole life insurance?

Wawanesa whole life insurance is a permanent life insurance policy that is designed to offer lifelong protection and cash value growth. It offers whole life insurance coverage through its two plans: 20 Pay Whole Life and Whole Life – Pay to Age 100. These whole life insurance plans also give policyholders the potential to earn dividends. The dividends can be used to purchase paid-up insurance, paid in cash or left on deposit. The cash value can be accessed from 5 years onwards. Moreover, these plans can also be customized with riders such as accidental death benefit, child critical illness rider, child protection rider, disability waiver of premium benefit, and a few other riders. 

Key features of Wawanesa whole life insurance:

Plan names
  • 20 Pay Whole Life
  • Whole Life – Pay to Age 100
Policy issue age 
  • 0 – 80 years
  • For juveniles (ages 0-17)
Age calculation Age Last (current age)
Coverage range 
  • $10,000-$20,000,000
  • For juveniles: $10,000 – $1,000,000 (max)
Coverage  Lifetime
Payment options 20-pay or pay to age 100
Dividend options
  • Paid-up additions
  • Cash payments
  • Interest-earning deposits
Guaranteed cash surrender values Develops from 5th year onwards
Riders
  • Accidental death benefit
  • Child critical illness rider
  • Child protection rider
  • Death or disability waiver of premium benefit (only available on Juvenile policies)
  • Disability waiver of premium benefit
  • Mortgage protection benefit

Who is eligible for Wawanesa whole life insurance?

To be eligible to buy Wawanesa whole life insurance, you must:

  • Be aged 15 days to 80 years for standard policies and 15 days to 17 years for a juvenile policy
  • Seek at least $10,000 in coverage
  • Meet the underwriting requirements

What is covered under Wawanesa whole life insurance?

With a Wawanesa whole life insurance policy, you will get coverage for the following:

  • Tax-free death benefit to the beneficiaries in the event of the death of the insured
  • Guaranteed and predictable premiums, meaning that the premiums will remain level and never increase
  • Policyholders may receive annual dividends based on the performance of Wawanesa’s participating account. Dividends are not guaranteed and can be used to purchase paid-up additions, left on deposit to earn interest, or received as cash payments
  • Access to the cash value through policy loans or surrenders
  • Optional coverage through riders such as accidental death benefit, child critical illness, child protection rider, disability waiver of premium benefit, and mortgage protection benefit

What are the different types of Wawanesa whole life insurance?

There are two different whole life insurance plans available with Wawanesa Life: 20 Pay Whole Life and Whole Life – Pay to Age 100. Additionally, Wawanesa also offers juvenile whole life insurance, specifically designed for children. 

Whole Life – Pay to Age 100 and 20 Pay Whole Life both provide more or less the same benefits. The key difference is the premium payment period: Pay to Age 100 requires premiums until age 100, while 20 Pay Whole Life requires premiums for only 20 years, after which the policy is paid up. Both plans also have the potential to earn annual dividends, which can be used to purchase paid-up additions, received in cash, or left on deposit. Policyholders can also access accumulated cash value from the 5th year.  

Wawanesa juvenile whole life insurance

Wawanesa Juvenile Whole Life provides guaranteed lifelong coverage with level, guaranteed premiums for children ages 15 days-17 years. To be eligible for this juvenile whole life insurance, newborns must be at least 15 days old and should have been discharged from the hospital before the whole life insurance application process starts. 

Like the other two participating policies, the juvenile whole life insurance policy also builds guaranteed lifelong coverage with level, guaranteed premiums for children ages 15 days -17 years. Moreover, juvenile policies also offer customization through riders. However, the only rider option available is the death or disability waiver of premium benefit.

Pros and cons of Wawanesa whole life insurance

Pros  Cons
Lifelong coverage with guaranteed premiums and a guaranteed death benefit Limited premium payment options: 20-pay or pay to age 100
Flexible dividend options: paid-up additions, cash, or leaving dividends on deposit Juvenile whole life insurance offers customization through only the death or disability waiver of premium benefit rider
Juvenile whole life insurance plan provides permanent coverage for children
One of the few insurers that bases the premium on your actual age

How much does Wawanesa whole life insurance cost?

The cost of Wawanesa whole life insurance ranges from $146 to $547 per month for a male applicant seeking $100,000 in coverage for 20-pay. For a female applicant with the same coverage and payment period, premiums range from $132 to $483 per month.

Cost of Wawanesa whole life insurance (2026):

Age (in years) Male Female
20 $146.16/month $132.30/month
30 $183.87/month $168.30/month
40 $234.63/month $216.27/month
50 $299.43/month $277.65/month
60 $393.30/month $361.53/month
70 $547.20/month $482.94/month

*Illustrating monthly cost of $100k coverage for a participating whole life insurance for 20-pay

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

What riders are available with Wawanesa whole life insurance policy

Wawanesa whole life insurance can be customized with a range of riders, including accidental death benefit rider, child critical illness rider, child protection rider, mortgage protection benefit, disability waiver of premium benefit, and death or disability waiver of premium benefit.

  • Accidental death benefit rider: Provides an additional death benefit of $250,000 if the insured dies solely from an accident. This benefit will terminate after the insured’s 70th birthday
  • Child critical illness rider: Provides $10,000 or $20,000 of coverage for children diagnosed with one of 15 specified critical illnesses. The child must be under age 21 at the time of the diagnosis of the critical illness
  • Child protection rider: Provides life insurance coverage for eligible children, with coverage ranging from $5,000 to $30,000. It also provides an option for the child to purchase additional coverage later without medical evidence
  • Mortgage protection benefit: Helps protect against mortgage obligations if the insured is diagnosed with a disability. The rider has a 60-day waiting period before the benefits commence and is available with a 2-year or 5-year benefit period
  • Disability waiver of premium benefit: Waives premiums if the insured becomes disabled, subject to the policy conditions. The insured must be disabled for 4 consecutive months to be eligible for this benefit
  • Death or disability waiver of premium benefit: It is applicable for juvenile policies only and waives premiums if the person paying the premiums dies or becomes disabled, helping keep the child’s coverage in force

How are the premiums priced for Wawanesa whole life insurance?

Wawanesa uses an Age Last (current age) pricing method to calculate whole life insurance premiums. This means your premium is based on your current age when you apply, rather than your age being rounded up to your nearest birthday. For example, some insurers may consider you one year older if you are within six months of your next birthday. Wawanesa does not use this approach, so applying before your next birthday may help you qualify for a lower premium. 

Is whole life insurance for juveniles customizable through riders?

Yes, Wawanesa’s juvenile whole life insurance policy can be customized through riders. However, there’s only one rider available with the juvenile policy: Death or Disability Waiver of Premium Benefit. This rider keeps the child’s policy in force if the policy owner, who is paying the premiums, dies or becomes disabled. The benefit will only be applicable if the policy owner dies before the age of 60. 

What are the dividend options available with Wawanesa whole life insurance?

Wawanesa participating whole life policyholders may receive annual dividends, although dividends are not guaranteed. The available dividend options are:

  • Paid-up additions: Use dividends to purchase additional permanent coverage, increasing the policy’s death benefit and cash value
  • Cash payments: Receive dividends directly as cash
  • Left on deposit: Keep dividends on deposit to accumulate interest, with the accumulated amount available for withdrawal

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%

How does Wawanesa compare to other whole life insurance providers?

Wawanesa offers a straightforward approach to participating whole life insurance with two main options: 20 Pay Whole Life and Whole Life – Pay to Age 100. Both provide lifelong coverage, guaranteed level premiums, guaranteed cash values, and the potential to receive dividends.

You can use dividends to purchase paid-up additions, take them as cash, or leave them on deposit to earn interest. Wawanesa also offers juvenile whole life coverage for children and uses an Age Last pricing method when calculating premiums. To compare Wawanesa with other leading insurers, read our guide to the best whole life insurance companies in Canada.

Our advisor’s take on Wawanesa whole life insurance

At PolicyAdvisor, one of our advisors recently worked with a client looking for permanent life insurance with guaranteed cash value growth, dividend potential, and predictable premiums. The client preferred a straightforward whole life policy without overly complex plan structures.

Client profile:

  • Age: 42-year-old non-smoking Canadian
  • Coverage need: $750,000 in permanent life insurance for family protection and long-term financial planning
  • Primary concern: Guaranteed policy values, dividend potential, and predictable premiums
  • Our comparison: We compared Wawanesa’s 20 Pay Whole Life and Whole Life – Pay to Age 100 with participating whole life products from other leading Canadian insurers, focusing on cash value growth, dividend options, premium payment periods, and policy flexibility

Why Wawanesa stood out:

  • Straightforward product structure: Wawanesa offers two main participating whole life plans, making it easier for clients who prefer a simple choice between 20-pay and pay-to-age-100 coverage
  • Guaranteed policy values: Both plans provide lifelong coverage, guaranteed level premiums, and guaranteed cash values that can develop from the fifth policy year
  • Current-age pricing: Wawanesa uses an Age Last pricing approach, meaning premiums are based on the applicant’s current age rather than rounding up to the nearest age
  • Flexible dividend options: Policyholders can use dividends to purchase paid-up additions, receive them as cash, or leave them on deposit to accumulate interest

How to buy Wawanesa whole life insurance with PolicyAdvisor?

Get covered with Wawanesa whole life insurance in three easy steps with PolicyAdvisor:

  • Speak with our licensed advisors
  • Review Wawanesa’s whole life insurance options alongside plans from other leading Canadian insurers
  • Receive a personalized illustration and finalize your application online

Schedule a call now to get started!

Need whole life insurance?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Is Wawanesa whole life insurance participating?

Yes, both policies offered by Wawanesa are participating whole life insurance policies. This means that through Wawanesa whole life insurance, policyholders may receive annual dividends based on the performance of its participating account. However, dividend payments are not guaranteed and may vary over time.

What is the minimum coverage for Wawanesa whole life insurance?

Wawanesa whole life insurance starts at $10,000 in coverage, while coverage can go up to $20,000,000. The maximum coverage available depends on the type of policy and the insured’s eligibility.

Can I borrow against my Wawanesa whole life insurance policy?

Yes, you can access accumulated cash value through policy loans once the policy has developed cash value. But it is important to remember that the outstanding policy loans and interest can reduce the amount payable to beneficiaries if they remain unpaid.

Does Wawanesa offer whole life insurance for children?

Yes, Wawanesa offers Juvenile Whole Life for children ages 15 days to 17 years. The policy provides permanent coverage with guaranteed premiums and cash value growth, like other whole life insurance policies, along with a Death or Disability Waiver of Premium Benefit rider.

How long do I have to pay premiums for Wawanesa whole life insurance?

Wawanesa offers two payment structures: 20 Pay Whole Life, where premiums are paid for 20 years, and Whole Life – Pay to Age 100, where premiums are paid until age 100. Both options provide lifelong coverage after the required premium payments are made.

Does Wawanesa whole life insurance have guaranteed cash value?

Yes, Wawanesa’s whole life policies build guaranteed cash value, which can develop as early as the fifth policy year. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Equitable whole life insurance review (2026)

Equitable offers a wide range of permanent life insurance for Canadians seeking extended coverage alongside value-added benefits. The insurer offers participating whole life insurance through its Equimax product line, with two plans designed for different cash-value goals. 

Equimax Estate Builder focuses on higher long-term value for estate and legacy planning, while Equimax Wealth Accumulator is designed to provide higher early cash values for individuals seeking to use it in their financial planning.

Quick review of Equitable Whole Life Insurance

  • PolicyAdvisor rating: 5/5
  • Best for: Canadians looking for participating whole life insurance from a mutual insurer, with a choice between long-term estate value and higher early cash-value accumulation
  • Skip if: You specifically want a non-participating whole life policy or lower-cost temporary coverage
Best for mutual company
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Plans offered
Equimax Estate Builder
Equimax Wealth Accumulator
Payment options
10-pay
20-pay
Life Pay
A.M. Best financial strength rating
N/A
Dividend Scale Interest Rate (DSIR)
6.40%

About Equitable Life Insurance

The Equitable Life Insurance Company of Canada is a Canadian mutual life insurer that was founded in 1920. Since its inception, the insurer has prioritized long-term policyholder interests, thanks to its mutual structure. As of December, 2025, Equitable has maintained a 6.40% Dividend Scale Interest Rate (DSIR) across its participating whole life policies.

Equitable’s financial strength

AM Best Rating N/A
Participating account fund size $3.2 billion
LICAT ratio 159%
Dividend scale interest rate (DSIR) 6.40%

What is Equitable whole life insurance?

Equitable whole life insurance is permanent life insurance that offers lifelong coverage as long as required premiums are paid. Equimax Estate Builder and Wealth Accumulator are participating policies, providing a guaranteed death benefit, guaranteed cash value and non-guaranteed dividends during the policy period. 

A key strength of Equitable’s whole life insurance is its Participating Account, which holds over $3.2 billion in assets, as of December 2025. Equimax is available as single-life, joint first-to-die, or joint last-to-die coverage, offering enhanced flexibility and customization for Canadians.

Key features of Equitable whole life insurance

Category Details
Plan names Equimax Estate Builder

Equimax Wealth Accumulator

Issue ages Single life: 

  •  Life Pay and 10 Pay: age nearest 0–85 for
  • 20 Pay: 0–80 

Joint life: 

  • Life Pay and 10 Pay: age nearest 18–85 for
  • 20 Pay: 18–80 
Coverage amount
  • Single life: $10,000 minimum basic Equimax coverage. 
  • Joint life: $25,000 minimum total Equimax coverage

Maximum coverage varies by product and is subject to age, eligibility, and applicable underwriting requirements.

Coverage types
  • Single life
  • Joint first-to-die
  • Joint last-to-die
Premium payment options
  • Life Pay
  • 10 Pay (Available only with Estate Builder)
  • 20 Pay
Guaranteed cash value
  • Wealth Accumulator: typically available at the end of policy year 1
  • Estate Builder: typically available at the end of policy year 5
Dividend options
  • Paid in cash
  • Premium reduction
  • On deposit
  • Paid-up additions
  • Enhanced protection
Premium offset Available. Uses the policy’s built-up value to help pay future premiums
Optional riders
  • Additional accidental death benefit (life pay premium option only)
  • Children’s protection rider
  • Disability waiver of premium provision
  • EquiLiving® critical illness insurance
  • Term life insurance (on the life insured under a single life policy only)

Offered only on children’s policies:

  • Children-only applicant waiver
  • Guaranteed insurability
Built-in features KIND benefits, providing support at claim time, include:

• Compassionate advance (not contractual)

• Bereavement counselling benefit

• Snap advance (not contractual)

• Living benefit (formerly called the disability benefit disbursement)

• Reduced paid-up insurance

• Option to elect individual policies (available on joint policies)

• Survivor benefit (joint first-to-die policies only)

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Who is eligible for Equitable whole life insurance?

Equitable whole life insurance is available to individuals meeting the following criteria:

  • Canadians meeting Equitable’s underwriting requirements
  • Individuals between the ages of 0 and 80 (minimum 15 days for children’s policies)
  • Single-life coverage starts at a $10,000 minimum, while joint-life coverage starts at $25,000

What is covered under Equitable whole life insurance?

Equitable Equimax Estate Builder and Equimax Wealth Accumulator offer permanent life insurance while building cash value over the years. Beyond this core role of financial protection, the policies offer a series of valuable features that make them more flexible than many traditional whole life insurance products.

Here are the primary benefits included with Equitable whole life insurance policies:

  • Guaranteed death benefit: Policies offer a guaranteed basic death benefit as long as required premiums are paid
  • Lifetime coverage: Your policy remains in force for life as long as premiums are paid
  • Guaranteed premiums: Premium payments stay fixed throughout the selected premium-pay period
  • Guaranteed cash value: Policies build guaranteed cash value over time, which may be accessed while the policy is in force
  • Dividend potential: Eligible policies may receive non-guaranteed annual policyholder dividends
  • Access to cash value: Policyholders may access available cash through policy loans and eligible withdrawals
  • Optional additional deposits: EDO can accelerate paid-up additions and policy value on eligible policies
  • Built-in support benefits: KIND provides benefits such as Compassionate Advance, Snap Advance, Bereavement Counselling, and a Living Benefit
  • Mutual company advantage: As a mutual insurer, Equitable Life operates without shareholders, meaning participating policyholders share in the company’s long-term success through dividends and stable account management

What is the Equimax KIND program?

New Equimax participating whole life policies include Equitable’s built-in KIND program, which provides compassionate and snap advances, access to policy cash value in cases of severe disability, and bereavement counselling benefits.

Here is a quick rundown of the primary benefits offered with the KIND program:

  • Compassionate advance: Access up to 50% of your coverage to a maximum amount of $100,000 if the insured becomes terminally ill
  • Bereavement counselling: Benefit for beneficiaries up to $1,000 total
  • Snap advance: Offers immediate access (if needed) to a portion of the death benefit up to the lesser of the policy cash value or $25,000 when a death claim is submitted. However, the policy must be in effect for at least 24 months before the date of death
  • Living benefit: Tax-free access to the policy cash value in the event of severe disability
Read more about how a whole life insurance policy works in Canada

Types of Equitable whole life insurance

Equimax is Equitable Life’s flagship participating whole life insurance product, designed to provide lifelong protection while steadily building cash value. It combines guaranteed coverage and level premiums with the potential for long-term financial growth through annual participating dividends.

Equimax is available in two plan options tailored to different financial goals: 

  • Equimax Estate Builder: ideal for long-term wealth transfer and legacy planning
  • Equimax Wealth Accumulator: suited for individuals or business owners seeking higher early cash values and financial flexibility

Here is an overview of the two plans offered by Equitable whole life insurance:

Equimax Estate Builder: Best for long-term estate value

Equitable Equimax Estate Builder is designed for Canadians seeking higher long-term value and more tax-efficient estate planning. The insurer positions it for legacy planning and helps in offsetting taxes and other costs that arise after death.

  • Long-term focus: Guaranteed cash value typically begins at the end of policy year 5, focusing on long-term value
  • Premium options: Life Pay, 10 Pay, or 20 Pay
  • Dividend options: Cash, premium reduction, on deposit, paid-up additions, or enhanced protection
  • Best for: Estate planning, wealth transfer, and policyholders who prioritize long-term policy value over early liquidity

Equimax Wealth Accumulator: Best for early cash value

Equimax Wealth Accumulator is designed for Canadians who want higher early cash values in the early years of their policy. It is beneficial for business owners and incorporated individuals who wish to use the cash value in their business or as part of a larger financial plan involving liquidity.

  • Cash-value focus: Guaranteed cash value is available at the end of policy year 1
  • Premium options: Life Pay or 20 Pay
  • Dividend options: Cash, premium reduction, on deposit, paid-up additions, or enhanced protection
  • Best for: Business planning, early liquidity, supplemental retirement strategies, and Canadians seeking access to policy value sooner

Key differences between Equimax Estate Builder and Equimax Wealth Accumulator

Category Equimax Estate Builder® Equimax Wealth Accumulator®
Primary focus Designed for long-term estate planning, wealth transfer, and legacy growth Focused on higher early cash values and short-to-medium-term liquidity
Ideal for Individuals and families aiming to grow and transfer wealth tax-efficiently Business owners or professionals who value early access to cash within 20 years
Cash value growth Cash value begins at end of policy year 5 Higher early cash values, available at end of policy year 1
Death benefit growth Higher long-term death benefit to offset estate or capital gains taxes Moderate death benefit growth, emphasizing cash accessibility
Dividend options
  • Paid in cash
  • Premium reduction
  • On deposit
  • Paid-up additions (PUAs)
  • Enhanced protection (with lifetime enhancement guarantee)
  • Paid in cash
  • Premium reduction
  • On deposit
  • Paid-up additions (PUAs)
  • Enhanced protection (with lifetime enhancement guarantee)
Premium payment options Available as 10 Pay, 20 Pay, or Life Pay Available as 20 Pay or Life Pay
Liquidity and collateral use Strong long-term value, typically used for estate purposes or future borrowing High early cash values make it well-suited for collateral loans or funding business opportunities
Child or grandchild coverage Ideal for lifelong coverage with gradual value growth for education or inheritance Offers earlier access to cash values for education or financial milestones
Business protection Works well for long-term shareholder or key-person protection with stable growth Better for businesses that prioritize early liquidity and short-term funding options
Coverage availability
  • Single Life
  • Joint First-to-Die
  • Joint Last-to-Die
  • Single Life
  • Joint First-to-Die
  • Joint Last-to-Die
Minimum sum insured
  • $10,000 (single)
  • $25,000 (joint)
  • $10,000 (single)
  • $25,000 (joint)
Maximum sum insured Up to $25,000,000 (higher coverage amount available by special quote)  Up to $25,000,000 (higher coverage amount available by special quote)

Pros and cons of Equitable whole life insurance

Pros:
✓Mutual-company structure aligns participating business with policyholder interests
✓Excelerator Deposit Option allows additional tax-deferred contributions to enhance the policy’s cash value growth
✓Variable dividend options provide flexibility to increase the death benefit, reduce premiums, earn interest, or receive cash
✓Tax-advantaged growth offers long-term savings potential and typically tax-free death benefits for beneficiaries
✓Single-life and joint-life structures support family, estate, and business planning
Cons:
✗Equitable does not have a non-participating whole life insurance option to choose from
✗It is not ideal for short-term goals or individuals seeking immediate returns
✗No cash value with Estate Builder in years 1-4

How much does Equitable whole life insurance cost?

The cost of Equitable whole life insurance for a 20-pay policy with $100,000 in coverage ranges from $162.48 to $576.82 per month. Your premiums depend on the coverage amount and personal factors, such as gender, age, smoking status, and health.

Cost of Equitable whole life insurance (2026)

Age (in years) Male Female
20 $97.06 $86.92
30 $130.97 $117.49
40 $180.85 $160.66
50 $246.29 $223.18
60 $333.21 $305.62
70 $490.51 $428.82

*Sample monthly cost of $100k coverage for a participating whole life insurance for 20-pay

Learn more about the cost of whole life insurance in Canada

What riders are available with Equitable whole life insurance?

Equitable whole life insurance can be customized with multiple optional riders, including accidental death benefit, children’s protection, applicant’s death and disability waiver of premium, and others. These add-ons provide additional protection and benefits for individuals and families, offering well-rounded coverage.

Here is an overview of the riders available with an Equitable whole life insurance policy:

Optional benefit What it does
Additional accidental death benefit

(available with Life Pay)

Pays an additional benefit following a qualifying accidental death
Children’s protection rider Provides term life insurance for eligible children and includes a conversion privilege without new evidence of insurability, subject to limits
Disability waiver of premium Waives qualifying policy premiums if the insured under the rider becomes totally disabled for the required period
Applicant’s death and disability waiver of premium Children’s-plan rider that may waive premiums if the payor/applicant dies or becomes totally disabled
Flexible guaranteed insurability option Children’s-plan rider allowing specified future purchases of additional life insurance without new evidence of insurability
EquiLiving critical illness insurance Provides a lump-sum payment for qualifying covered critical illnesses, with several premium and coverage-duration options
Term life insurance rider Adds Term 10, Term 20, or Term 30/65 temporary coverage to a single-life Equimax policy

What are the different limited-pay options offered by Equitable?

Equitable Life offers two limited-pay structures for its participating whole life insurance plans, Equimax Estate Builder and Equimax Wealth Accumulator, letting policyholders finish paying premiums early while keeping lifetime coverage:

  • 10-pay: Premiums are paid for 10 years. Once the payment period ends, the policy is fully paid up, and lifelong coverage continues with no further premiums. However, this option is available only for the Equimax Estate Builder plan
  • 20-pay: Premiums are paid for 20 years, after which the policy is fully paid up for life

Does Equimax help with tax payouts during death?

Yes, the Equimax Estate Builder whole life plan can help with tax liabilities upon death. This specific plan is designed to provide a larger death benefit, which can be used to offset estate taxes and other final expenses. 

The death benefit is typically paid out tax-free to beneficiaries, providing them with the funds needed to settle the estate without the burden of additional tax liabilities.

The Equimax Estate Builder whole life plan provides a death benefit that can be used to:

  • Cover taxes and fees at death: The death benefit can help beneficiaries pay for estate taxes, ensuring the full value of the estate is passed on without forcing them to liquidate assets
  • Leave a legacy behind: The policy ensures that the financial legacy you leave behind remains intact, allowing your beneficiaries to inherit more

What is the Excelerator Deposit Option on Equitable Equimax policies?

The Excelerator Deposit Option (EDO) allows eligible Equimax policyholders to make optional payments above their required guaranteed premium. These payments essentially purchase participating paid-up additional insurance, which can increase both cash value and the death benefit. Additionally, this amount is also eligible to receive dividends.

Does Equitable whole life insurance offer premium offset?

Yes, Equitable Equimax policies using the on-deposit, paid-up additions, or enhanced protection dividend option may eventually qualify for premium offset. With this feature, policyholders can use dividends to help cover required premiums if the policy value is sufficient. However, this feature is not guaranteed.

However, the premium offset is subject to certain conditions:

  • Policy loans are not available if the policy is on premium offsets
  • Future dividends and non-guaranteed cash value must be sufficient to pay all future premiums
  • Policy is not eligible for premium offset while there is an outstanding loan balance

What are the various dividend options on an Equimax whole life insurance plan?

Equitable’s participating whole life insurance has several dividend options to choose from, including cash payout, premium reduction, paid-up additions, on-deposit, and enhanced protection.

  • Paid in cash: Dividends are paid directly to the policyholder each year
  • Premium reduction: Dividends reduce future premiums, lowering out-of-pocket costs while keeping coverage intact
  • On deposit: Dividends are held in an interest-bearing account with Equitable Life and can be withdrawn anytime
  • Paid-Up Additions (PUA): Dividends buy additional permanent coverage that grows cash value and death benefit tax-deferred
  • Enhanced protection: Combines base permanent coverage with a one-year renewable term (OYT) layer. Dividends first pay OYT costs; any remainder buys PUAs that gradually replace the term layer

Where does Equitable whole life insurance invest the participating account?

Equitable has structured its investments across each asset class to meet the long-term objectives, liabilities, and liquidity requirements of its participating policies. 

Here is how the investments are allocated:

Asset type Allocation
Bonds 29%
Equity 25%
Private placements 12%
Real estate 12%
Policy loans 11%
Mortgages 9%
Cash and equivalents 2%

How does Equitable determine whole life insurance dividends?

Equitable Life’s whole life insurance dividends are determined by the performance of its participating (PAR) account. The financial performance of PAR accounts can depend on factors like investment returns, mortality payouts, premium lapses, and tax obligations. 

Strong investment performance, fewer claims, and lower premium lapses can lead to higher dividends, while the opposite may result in lower payouts. 

Dividends are paid at the sole discretion of Equitable Life’s board of directors. As such, dividends can vary from year to year depending on the insurer’s performance. The decision to distribute dividends is made with the aim of ensuring steady, predictable returns while minimizing volatility.

Equitable Life Dividend Scale Interest Rate (DSIR): 2020–2025

Year DSIR
2025 6.40%
2024 6.40%
2023 6.25%
2022 6.05%
2021 6.05%
2020 6.20%

Equitable Life dividend scale over 30 years

Equitable PAR account return Equitable dividend scale interest rate
5 years 7.05% 6.23%
10 years 6.56% 6.29%
20 years 6.79% 6.77%
30 years 7.23% 7.46%
Standard deviation over 30 years 1.74% 1.70%

Source: Equitable dividend scale interest rate, 2024

Which Equitable whole life plan type is right for you?

Equitable’s Estate Builder and Wealth Accumulator plans are built to suit the diverse needs of policyholders. From long-term goals to immediate cash value accumulation, individuals can choose the right Equimax plan for them based on their individual needs.

Here’s how you can determine the right policy for yourself:

What you are looking for Equimax Estate Builder Equimax Wealth Accumulator
Higher long-term benefits for planning your estate ✓ ✘
Higher death benefit that can reduce tax burden during transfer of property ✓ ✘
Affordable insurance coverage to secure the financial future of your children or grandchildren ✓ ✓
Build immediate cash value to start a business ✓ ✓
Make philanthropic donations but also reduce your tax implications ✓ ✓
Create a steady retirement fund ✓ ✓
Quick access to higher cash value through a policy loan or collateral loan ✘ ✓

Why should you purchase Equitable Life whole life insurance for children?

By purchasing Equitable’s whole life insurance policies for a child or grandchild, policyholders can help set the foundation for that child’s financial future. Equitable Life whole life insurance for children offers permanent coverage at children’s rates, with paid-up options in 10 or 20 years.

It provides tax-advantaged cash value growth, offering financial flexibility through loans or withdrawals for future needs. Additionally, ownership can transfer tax-free to the child upon adulthood, securing their financial foundation.

For example, if you buy a 20-pay whole life insurance policy for a 5-year-old child at an annual premium of $1,200, the policy’s value will continue to grow without further premium payments after the first 20 years. By paying $100 a month, parents can help secure their children’s financial future, ensuring they have enough coverage to support important life events and emergencies and to leave funds for future generations.

What is the living benefit offered by Equimax whole life insurance?

The living benefit offered by Equimax whole life insurance allows policyholders to access a portion of their policy’s cash value if the life insured becomes severely disabled due to a physical or mental impairment. 

This benefit can be applied once per policy year and is subject to Equitable Life’s administrative guidelines. It is worth noting that any payment made under the Living Benefit will reduce the policy’s death benefit. 

Individuals with life-threatening conditions such as cancer, AIDS, coronary artery disease, myocardial infarction, and Alzheimer’s disease may be eligible to receive Living Benefits under their whole life insurance policy. However, the insured individual must have been disabled for 90 days for the benefit to be triggered.

How does Equitable compare to other whole life insurance providers?

Equitable’s Equimax stands out for its participating lineup that focuses on estate preservation and wealth accumulation. The insurer’s mutual structure, multiple dividend options, and the ability to purchase additional coverage through EDO make it a strong contender for Canadians seeking flexibility in their coverage. 

Additionally, KIND benefits, paired with a range of riders, make Equitable Equimax a strong choice for Canadian families, business owners, and individuals seeking lifelong coverage and wealth preservation.

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%
Find out about the best whole life insurance companies in Canada
Let us help you choose the best Equitable whole life plan

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Our advisor’s take on Equitable whole life insurance

At PolicyAdvisor, we recently helped a 42-year-old business owner compare Equitable Life’s permanent life insurance options. They were seeking lifelong coverage for estate planning and access to cash value for business purposes. Based on these goals, Equimax Wealth Accumulator was the stronger fit since it combines participating whole life protection with early access to cash value.

Client profile

  • Age: 42 
  • Family: Incorporated business owner with a spouse and two children 
  • Coverage goal: $500,000 of permanent life insurance 
  • Primary concern: Lifetime protection with access to cash value for future business or retirement needs 

Why we recommended Equimax Wealth Accumulator:

  • Guaranteed cash value available from the end of the first policy year, supporting early access to liquidity
  • 20 Pay option provides a defined premium period, allowing the family to finish paying early while maintaining lifetime protection
  • Paid-up additions dividend option and EDO can be used to direct additional cash flow toward growing the policy’s value

How to purchase Equitable Equimax whole life insurance in Canada?

PolicyAdvisor’s licensed advisors can help you compare Equitable whole life insurance plans based on your age, budget, health, coverage needs, and financial goals.

Whether you are looking to protect your family or secure tax-advantaged wealth transfer planning, our advisors at PolicyAdvisor can help you choose the right plan, coverage amount, and optional riders to fit your financial needs. 

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

Can I transfer ownership of my Equitable whole life insurance policy to my children or grandchildren? 

Yes, Equitable allows you to transfer ownership of your whole life insurance policy to your children or grandchildren when they reach the age of majority. 

This is one way to build generational wealth, as the new owner can access the policy’s cash value for future expenses such as education or a down payment on a house. Whether you are living in Ontario, British Columbia, or Alberta, you can purchase whole life insurance for your children and secure their future.

Can I add extra coverage to my Equitable whole life insurance policy in the future? 

Yes, Equitable offers various options to increase your coverage over time. With features like paid-up additions, you can use dividends to purchase additional life insurance, increasing your death benefit and cash value. This flexibility allows you to tailor your policy as your life circumstances evolve, ensuring that you always have the coverage you need.

What happens to my Equitable whole life policy if I stop making premium payments? 

If you stop making premium payments on your Equitable whole life policy, it won’t necessarily lapse immediately. The policy’s cash value can be used to cover the premiums for a period of time, depending on how much cash value you’ve accumulated. However, once the cash value is exhausted, your coverage may likely end. It is important to keep track of your policy’s status from time to time.

Can a person with pre-existing conditions be eligible for the Living Benefit of a whole life insurance policy?

No, a person with pre-existing conditions may not be eligible for the Living Benefit under Equitable’s whole life insurance policy if the condition existed at the time the policy was first issued or at the date of the last reinstatement.

Can I borrow against my Equimax cash value?

Yes, you can borrow against your Equimax cash value. Policyholders can access up to 90% of their available cash value, minus any outstanding loans. However, unpaid loans and interest reduce the death benefit.

Is premium offset guaranteed on Equimax?

No, premium offset depends on future non-guaranteed dividends and policy values. If the offset is unavailable for a period, policyholders will have to pay their premiums out of pocket.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

iA whole life insurance review (2026)

IA Financial Group offers several permanent life insurance options for Canadians seeking lifelong coverage alongside cash value growth. Its lineup includes non-participating whole life insurance and two participating policies, the iA PAR Estate and Wealth plans. 

iA Whole life insurance offers guaranteed premiums, a guaranteed death benefit, and guaranteed surrender values. Meanwhile, the iA PAR Estate and Wealth plans also offer permanent coverage and guaranteed cash values, with the added potential to earn annual dividends, which are not guaranteed.

Quick review

  • PolicyAdvisor rating: 4/5
  • Best for: Broad whole life choices with both guaranteed non-participating and participating cash-value options
  • Skip if: You want more flexibility in how long you pay premiums outside IA’s available fixed options
Best for Health Accommodation
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Whole life insurance policies offered
Non-participating policy, PAR Estate, PAR Wealth
Dividend Scale Interest Rate (DSIR)
6.35%
AM Best Rating
A+

About iA Financial Group

Industrial Alliance Insurance and Financial Services Inc., commonly known as iA Financial Group, was established in the year 1892. Since then, the insurer has offered a wide range of insurance and wealth management products The whole life insurance roster offers both participating and non-participating insurance plans. As of 2026, iA Financial Group has a 6.35% dividend scale interest rate (DSIR) across its participating whole life policies.

iA Financial Group’s financial strength (As of 2026)

AM Best Rating A+ (Superior)
Participating account fund size $100 billion
LICAT ratio 134%
Dividend scale interest rate (DSIR) 6.35%

What is your Whole Life Insurance worth?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$100K

What is iA Whole Life Insurance?

iA whole life insurance provides permanent coverage with a level face amount that is guaranteed for life. iA PAR Estate and Wealth are the insurer’s participating whole life insurance plans, offering guaranteed cash value and non-guaranteed dividends during the policy period. Meanwhile, iA Whole Life is the non-participating policy.

A key strength of iA’s whole life insurance is its Participating Account, which holds approximately 263.5 million in invested assets. The policies offer single-life and joint-life structures, giving Canadians more choice.

Key features of iA whole life insurance

Plan names
  • iA Whole Life
  • iA PAR Estate 
  • iA PAR Wealth
Policy issue age iA Whole Life

  • L10/L20/L100: ages 0–70
  • L65: ages 0–54

iA PAR Estate and Wealth

  • 10-pay: ages 0–85
  • 20-pay: ages 0–80
  • Pay-to-100: ages 0–75
Minimum coverage amount
  • iA Whole Life: $10,000
  • iA PAR Estate and Wealth: $25,000
Coverage options
  • Individual
  • Joint first-to-die (Available in iA Whole Life only)
  • Joint last-to-die
Payment options iA Whole Life

  • L10: pay for 10 years
  • L20: pay for 20 years
  • L65: pay to age 65
  • L100: pay to age 100

iA PAR Estate and Wealth

  • Pay 10
  • Pay 20
  • Pay to 100
Dividend options

(Only with iA PAR Wealth and Estate)

  • Paid-up additions
  • Annual premium reduction
  • Cash
  • Deposit with interest
Premium offset Available with iA PAR when using the paid-up additions strategy. Uses the policy’s built-up value to help pay future premiums
Riders
  • Term life insurance
  • Critical illness
  • Child critical illness
  • Child Module
  • Accidental death
  • Accidental death and dismemberment
  • Disability Credit
  • Waiver of premium benefits
  • Accidental fracture
  • Supplementary Income (available only in whole life)
  • Guaranteed Insurability (available only in whole life)
  • Hospitalization (available only in whole life)

Who is eligible for iA Whole Life insurance?

iA whole life insurance is available to individuals meeting the following criteria:

  • Individuals meeting iA’s residency and underwriting requirements
  • iA Whole Life requires at least $10,000 in coverage, while iA PAR Estate and iA PAR Wealth start at $25,000
  • For joint policies, the ages of both individuals should be at least 15 years
  • Approval depends on factors such as age, health status, smoking status, and coverage amount. Additional medical information or testing may be requested depending on the application

Age eligibility for iA Whole Life insurance:

  • iA Whole Life (L10, L20, and L100): 0–70
  • iA Whole Life (L 65): 0–54

Age eligibility for iA PAR Estate and iA PAR Wealth: 

  • 10-pay: 0–85 
  • 20-pay: 0–80
  • Pay-to-100: 0–75

What is covered under iA Whole Life insurance?

iA Whole Life, iA PAR Estate, and iA PAR Wealth provide permanent life insurance with guaranteed coverage and level premiums for policyholders. Beyond this core financial protection, the policies offer several features that make them more flexible than many traditional whole life insurance products.

Here are the primary benefits included with iA Whole Life insurance:

  • Guaranteed premiums: Premiums are fixed throughout the selected premium-payment period
  • Guaranteed cash value: Your policy builds guaranteed cash value over time, which may be accessed while the policy is in force
  • Dividend potential (for participating plans): iA PAR Estate and iA PAR Wealth may receive non-guaranteed annual dividends. This can be used for paid-up additions, premium reduction, cash, or a deposit with interest
  • Access to cash value: Policyholders may access available cash through policy loans and eligible withdrawals
  • Flexible riders and additional benefits: Depending on the plan, coverage can be made more comprehensive with term life, critical illness, child coverage, disability protection, accidental death benefits, and premium-waiver options
  • Flexible payment terms: iA Whole Life offers pay 10, pay 20, pay 65, and pay to 100 options, while iA PAR Estate and Wealth offer 10-pay, 20-pay, and pay-to-100

Types of iA whole life insurance

iA Financial offers both participating and non-participating whole life insurance policies, allowing Canadians to choose between lifelong coverage and greater long-term growth potential. 

Here’s an overview of the different plans offered by iA whole life insurance:

iA Whole Life

iA Whole Life is iA’s non-participating permanent life insurance option, offering a guaranteed level death benefit, guaranteed premiums, and guaranteed cash surrender values while providing lifelong coverage to policyholders.

  • Coverage range: $10,000 to $10 million
  • Premium payment options: Pay 10, Pay 20, Pay 65, or Pay to 100 
  • Cash surrender value: Available starting from the 11th policy anniversary
  • Optional riders: Term life, critical illness, child coverage, disability credit, supplementary income, guaranteed insurability, and waiver of premium benefits 
  • Best for: Canadians seeking straightforward permanent coverage with guaranteed costs and no exposure to dividend fluctuations

iA PAR Estate

iA PAR Estate is a participating whole life policy designed to prioritize long-term growth of the policy’s surrender value and death benefit. Apart from lifelong coverage and cash value growth, the policy also offers non-guaranteed dividends.

  • Cash value accumulation: Guaranteed cash surrender value begins from the 5th policy anniversary, with additional growth possible through paid-up additions 
  • Coverage range: $25,000 to $25 million, with issue ages up to 85 
  • Premium payment options: 10-pay, 20-pay, or pay to 100 
  • Optional riders: Term life, critical illness, child coverage, disability credit, accidental death and AD&D, accidental fracture, and waiver of premium benefits 
  • Best for: Canadians seeking long-term estate growth, legacy planning, and participating policy dividends

iA PAR Wealth

iA PAR Wealth is iA’s participating whole life policy that prioritizes early cash value accumulation and liquidity while providing permanent coverage and long-term growth potential. The policy also allows a guaranteed cash surrender value from the first policy anniversary, making it ideal for policyholders seeking earlier access to policy value. 

  • Cash value accumulation: Guaranteed cash surrender value begins from the 1st policy anniversary, with additional growth possible through paid-up additions 
  • Coverage range: $25,000 to $25 million, with issue ages up to 85 
  • Premium payment options: 10-pay, 20-pay, or pay-to-100 
  • Optional riders: Term life, critical illness, child coverage, disability credit, accidental death and AD&D, accidental fracture, and waiver of premium benefits 
  • Best for: Canadians seeking earlier cash value growth and liquidity, such as business owners and incorporated professionals

Here’s a comparison of iA Whole Life, iA PAR Estate, and iA PAR Wealth:

Feature iA Whole Life iA PAR Estate iA PAR Wealth
Policy type Non-participating whole life Participating whole life Participating whole life
Best for Predictable permanent coverage and guaranteed values Long-term estate and legacy growth Early cash value and liquidity
Premium options Pay-10, Pay-20, Pay-65, or Pay to 100 10-pay, 20-pay, pay-to-100 10-pay, 20-pay, pay-to-100
Coverage range $10,000–$10 million $25,000–$25 million $25,000–$25 million
Guaranteed premiums Yes Yes Yes
Participating dividends No Yes (non-guaranteed) Yes (non-guaranteed)
Dividend options N/A
  • Paid-up additions
  • Annual premium reduction
  • Cash

Deposit with interest

  • Paid-up additions
  • Annual premium reduction
  • Cash

Deposit with interest

Coverage structure Individual, joint first-to-die, joint last-to-die Individual or joint last-to-die Individual or joint last-to-die
Policy loans Available once sufficient surrender value exists Available based on the policy’s surrender value Available based on the policy’s surrender value
Reduced paid-up insurance Available with L20, L65 and L100 from the 11th policy anniversary. Not available with L10 Available from the 10th contract anniversary, subject to policy provisions Available from the 10th contract anniversary, subject to policy provisions

Learn more about how whole life insurance works in Canada

Pros and cons of iA whole life insurance

Pros:
✓iA offers flexibility with four dividend options, allowing customization of coverage
✓A variety of riders are available for both non-participating whole life and iA PAR
✓iA PAR policyholders can make extra contributions to purchase paid-up insurance with Additional Deposit Option
✓Five guaranteed non-PAR payment structures, including pay-to-65
Cons:
✗The disability benefit is available only in the PAR plans.
✗iA Whole Life guaranteed surrender value begins from the 11th policy anniversary

How much does iA whole life insurance cost?

The cost of iA whole life insurance for a 20-pay whole life insurance policy with $100,000 in coverage ranges from $910 to $7,358 per month. Your premiums depend on the coverage amount and personal factors, such as gender, age, smoking status, and health.

Cost of IA whole life insurance (2026)

Age (in years) Male Female
20 $94.68 $81.90
30 $114.03 $104.13
40 $177.03 $147.96
50 $251.73 $210.15
60 $366.75 $303.75
70 $662.22 $560.88

*Sample monthly cost of $100k coverage for a non-participating whole life insurance for 20-pay

What riders are available with iA whole life insurance?

iA whole life insurance can be customized with multiple optional riders, such as AD&D, Guaranteed Insurability, waiver of premiums, critical illness coverage, and more. These add-ons provide additional protection and benefits for individuals and families, offering well-rounded coverage.

Here’s an overview of the riders available with iA whole life insurance in Canada:

Rider/benefit What it does Availability
T10 Renewable & Convertible Adds 10-year term life insurance that can be renewed or converted to eligible permanent coverage, subject to policy terms iA PAR Estate & Wealth
T20 Renewable & Convertible Adds 20-year term life insurance that can be renewed or converted to eligible permanent coverage, subject to policy terms iA PAR Estate & Wealth
Pick-A-Term T25 Adds term life insurance coverage for 25 years iA PAR Estate & Wealth
Pick-A-Term T30 Adds term life insurance coverage for 30 years iA PAR Estate & Wealth
Critical Illness Pays a lump-sum benefit following diagnosis of an eligible covered critical illness or medical condition, subject to policy requirements iA Whole Life, PAR Estate & Wealth
Child Critical Illness Provides a lump-sum benefit if an insured child is diagnosed with an eligible covered illness or medical condition iA Whole Life, PAR Estate & Wealth
Child Module Provides term life insurance for existing and future children, generally until the child reaches age 25 or the parent/insured reaches age 65 iA Whole Life, PAR Estate & Wealth
Child Module PLUS Includes the Child Module’s term life coverage plus accidental fracture protection for children iA PAR Estate & Wealth
Disability Credit Provides a predetermined benefit if the insured meets the rider’s disability definition and is unable to perform their primary occupation for the required period iA Whole Life, PAR Estate & Wealth
Supplementary Income (SI) Provides a monthly benefit following qualifying total disability caused by an accident or illness iA Whole Life only
Guaranteed Insurability (GI) Allows eligible insureds to purchase additional permanent life insurance without new evidence of insurability, subject to conditions iA Whole Life only
Accidental Death (AD) Pays an additional benefit if the insured dies as a result of a qualifying accident iA PAR Estate & Wealth
Accidental Death & Dismemberment (AD&D) Pays an additional benefit for accidental death or a percentage of the selected amount for qualifying dismemberment or loss of use iA PAR Estate & Wealth
Accidental Fracture (AF) Pays a benefit if the insured suffers a qualifying bone fracture caused by an accident iA PAR Estate & Wealth
Applicant Disability (WPDis) Waives eligible policy premiums if the applicant becomes totally disabled  iA Whole Life, PAR Estate & Wealth
Insured Disability (WPIDis) Waives eligible policy premiums if the policyholder becomes totally disabled  iA Whole Life, PAR Estate & Wealth
Applicant Death (WPD) Waives eligible premiums if the applicant dies before the age specified in the benefit iA Whole Life, PAR Estate & Wealth

Which limited-pay whole life insurance plans are available from iA Financial?

iA Financial offers limited pay options across its whole life plans, letting policyholders finish premiums early while keeping lifetime coverage.

Here’s a quick overview of the limited-pay options under each iA whole life insurance plan:

iA Whole Life:

  • 10 Pay
  • 20 Pay
  • 65 Pay

iA PAR Estate and PAR Wealth:

  • 10 Pay
  • 20 Pay
Whole life insurance can be affordable!

Get the best whole life insurance rates in Canada today.

How can you access dividends in iA whole life insurance?

iA Financial Group offers four different dividend strategies, including paid-up additions, annual premium reduction, cash payouts and deposits with interest for their participating whole-life insurance plans:

  • Paid-up additions: Dividends are used to purchase additional paid-up insurance, increasing both the policy’s face amount and its cash surrender value
  • Annual premium reduction: Dividends are applied to reduce the amount of the next annual premium payable, lowering the out-of-pocket cost for the policyholder
  • Payable in cash: Dividends are paid directly to the policy owner, providing immediate liquidity. This option may have tax implications 
  • Deposit with interest: Dividends are deposited into a savings account managed by iA Financial Group, where they earn interest. The interest earned is taxable at the end of the year

Taxation of iA whole life dividends

The taxation of dividends on an iA whole life insurance policy depends on the option you have selected. It will vary if you have opted for paid-up additions, cash, or any other available option. Here’s a breakdown of how taxation applies to each option:

  • Paid-up additions: No tax applies if the full dividend buys paid‑up additions. If any portion is paid to the policyowner, cash payment tax rules apply
  • Payable in cash: Any amount exceeding the adjusted cost base (ACB) is taxed
  • Annual premium reduction: Dividends are used to reduce the premium; the ACB remains unaffected. No tax applies in this case
  • Deposit with interest: Dividends that are held on deposit and earn interest are taxable; the interest credited is taxed annually

How are dividends for iA whole life participating policies distributed?

The participating account in iA whole life is managed by the iAGAM team, who are experienced in handling bonds, equities, asset allocation, alternative assets, and risk management. The participating account in an iA whole life policy is supported by a diversified mix of assets.

Here’s how the investment is spread out:

Asset type Target Allocation (As of Dec. 31, 2025)
Government bonds 10%
Corporate bonds 15%
Private debt 20%
Commercial mortgages 10%
Preferred Shares 5%
Common Shares 10%
Real estate investments 10%
Private equity and infrastructure  20%

Explore the top whole life insurance companies in Canada in 2026

How does iA calculate dividends?

Dividends are not guaranteed and may differ from one year to another based on the performance of iA’s participating (PAR) account. Each year, iA’s Board of Directors approves the dividend amount based on the company’s dividend policy, which ensures fair distribution among policyholders.

The dividend amount depends on the dividend scale, which reflects the financial performance of the participating account. This performance is influenced by factors such as investment returns, mortality rates, policy lapses, and expenses related to iA’s participating contracts. 

The dividend scale can go up or down based on these factors. Once dividends are declared, they are paid to the policyholder on the policy’s contract anniversary.

Additional deposit option in iA whole life insurance policies

iA Par policies also have an additional deposit option, which means that policyholders can make extra contributions to purchase additional paid-up insurance. The policyholder must select the paid-up additions dividend option to use the ADO.

The minimum contribution is $100 annually or $10 monthly, which gets added to the existing paid-up insurance. It is worth noting that this is not available with the 10-year premium payment option, and the contribution needs to be specified in the insurance application form.

Can I get a loan against my iA whole life insurance policy?

Yes, you can take out a loan against your iA whole life insurance policy through two types of policy loan advances: the cash loan advance and the automatic loan advance. 

Both types of loan advances allow the policyholder to access the cash value of the policy while still maintaining eligibility for dividend payments, though there are some important details and limitations to consider.

Cash loan advance

  • The policy owner can request a cash loan advance at any time in writing
  • The loan amount cannot exceed 90% of the surrender value of the basic coverage (including any reduced paid-up insurance, if applicable) plus 90% of the surrender value of any paid-up insurance, minus any amounts owed to iA

Automatic loan advance

  • iA may initiate an automatic loan advance if premiums are due and have not been paid by the end of the grace period
  • The automatic loan advance cannot exceed the total surrender value of the policy, which includes the surrender value of the basic coverage, any reduced paid-up insurance, the surrender value of the paid-up insurance, and the balance of the dividend deposit account (if applicable)
  • The total outstanding loan balance, including any other amounts owed to the company, cannot exceed the policy’s total surrender value
Find out if whole life insurance is worth your money

How does iA compare with other whole life insurance providers?

iA offers both participating and non-participating whole life insurance, giving policyholders several ways to structure permanent coverage based on their long-term goals.

Within its participating lineup, iA PAR Estate and iA PAR Wealth are designed for different priorities. PAR Estate focuses on long-term estate growth and provides guaranteed cash surrender value from the fifth contract anniversary, while PAR Wealth prioritizes higher surrender values in the earlier years of the policy and provides guaranteed cash surrender value from the first policy anniversary. 

The multiple joint-life options alongside various premium payment terms make iA whole life insurance a comprehensive choice for Canadian families, businessmen, and individuals.

Dividend Scale - Participating Whole Life Insurance

Compare dividend rates from top Canadian insurers

2022 2023 2024 2025 2026
Equitable 6.05% 6.25% 6.40% 6.40% 6.40%
Manulife 6.10% 6.35% 6.35% 6.35% 6.35%
iA Financial Group 5.75% 6.00% 6.25% 6.35% 6.35%
Desjardins Insurance 5.75% 6.20% 6.30% 6.30% 6.30%
RBC Insurance 6.00% 6.00% 6.25% 6.30% 6.30%
Sun Life 6.00% 6.00% 6.25% 6.25% 6.25%
Empire Life 6.00% 6.00% 6.00% 6.25% 6.25%
Foresters Financial 5.50% 5.50% 5.50% 6.25% 6.25%
Co-operators 5.90% 5.90% 6.00% 6.00% 6.00%
Assumption Life 5.75% 5.75% 5.75% 5.75% 5.80%
Canada Life 5.25% 5.50% 5.50% 5.75% 6.00%

Our advisor’s take on iA whole life insurance in Canada

At PolicyAdvisor, we recently helped a 48-year-old business owner compare iA’s permanent life insurance options. They were seeking lifelong coverage for estate planning and long-term wealth transfer, alongside building accessible policy value. Based on these goals, iA PAR Estate was the stronger fit since it combines participating whole life protection with long-term growth and cash surrender value through dividends.

Client profile

  • Age: 48
  • Occupation: Business owner 
  • Family: Married with adult children 
  • Primary concern: Estate preservation and tax-advantaged wealth transfer 
  • Coverage goal: $1 million in permanent life insurance 
  • Additional priority: Growing long-term policy value rather than maximizing early liquidity

Why we recommended iA PAR Estate:

  • iA PAR Estate is structured to optimize the long-term growth of both total surrender value and total life insurance coverage
  • 20-year premium payment option lets the policyholder complete premium payments and enjoy lifelong coverage
  • The Additional Deposit Option allows the individual to make additional contributions, purchase paid-up insurance, and further build policy value

How to buy iA whole life insurance in Canada?

Ready to explore iA whole life insurance? Get a personalized whole life illustration and compare it to top Canadian insurers with PolicyAdvisor’s licensed experts. Our advisors can help you compare iA Whole Life, iA PAR Estate, and iA PAR Wealth based on your age, budget, coverage needs, cash-value priorities, and long-term financial goals.

Whether you are looking for permanent coverage, long-term estate growth, or advanced access to cash value, our advisors at PolicyAdvisor can help you choose the right plan, coverage amount, and optional riders to align with your financial goals.

Get whole life insurance for your loved ones

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Can I modify my iA whole life insurance policy as my needs change?

Yes, both iA Whole Life and iA PAR offer flexibility to make certain changes as your needs evolve. Depending on the type of plan and its provisions (such as age eligibility), you may be able to make adjustments after issue, such as decreasing or increasing your face amount or modifying riders. However, some changes may require evidence of insurability or be subject to iA’s administrative rules.

Does iA whole life insurance offer tax advantages?

Yes, iA whole life insurance provides significant tax advantages. The cash value grows tax-deferred, meaning you won’t pay taxes on the gains as long as they remain within the policy. 

Additionally, the death benefit is typically paid out tax-free to your beneficiaries, making it an excellent tool for estate planning and wealth transfer.

How does iA ensure that my policy remains affordable long-term?

iA whole life insurance comes with level and guaranteed premiums, which means your monthly or annual payments won’t increase after the policy is issued, regardless of changes in your health or the economy. 

This stability makes budgeting easier and ensures that your policy remains affordable as you age. Additionally, participating policies with dividends can offset costs, offering even greater value over the life of the policy.

What are the dividend options available with iA whole life insurance?

Dividends in iA whole life insurance can be applied to purchase paid-up additions (PUAs), reduce or fully pay future premiums, receive them as cash each year or leave them with iA to accumulate with interest.

Can I get joint iA whole life insurance?

Yes. iA’s non-participating policy can be structured as joint first-to-die or joint last-to-die coverage. Meanwhile, iA PAR Estate and Wealth offer joint last-to-die coverage for up to two insureds.

Which iA whole life plan has the earliest guaranteed cash value?

iA PAR Wealth offers the earliest guaranteed basic cash surrender value, which begins from the first contract anniversary. Meanwhile, iA PAR Wealth begins in the fifth year.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */