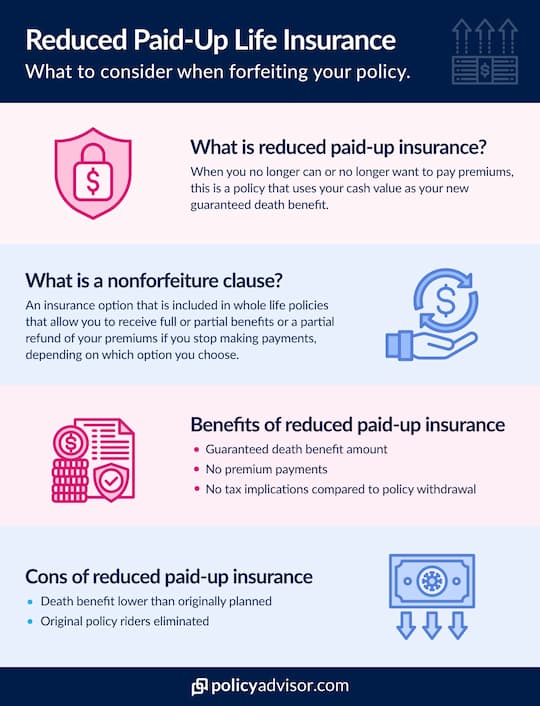
What is reduced paid-up insurance?

Reduced paid-up insurance lets you exchange your whole life policy for a reduced guaranteed death benefit that doesn’t require monthly payments. This type of policy is ideal if you’ve built a steady amount of cash value in your whole life policy and no longer want or can’t afford to pay your monthly premiums. 

While this may seem like an easy way to utilize a whole life policy’s cash value and get away with not having to foot your insurance bill later in life, it may mean the death benefit your family gets is significantly lower than you originally planned. PolicyAdvisor is in the business of providing policies, but we also want to help you reach your financial goals. If you use your cash surrender value to purchase a reduced paid-up policy, it’s vital to understand the terms and conditions of the transactions and what your alternatives are. 

This article explains the details of reduced paid-up policies and goes over situations where it may be beneficial for your financial situation.

What is reduced paid-up insurance?

Reduced paid-up insurance is a non-forfeiture option available with many permanent life insurance policies, including some whole life and universal life policies. It lets you stop required premium payments while retaining a lower amount of life insurance coverage.

The insurer uses the policy’s accumulated cash value to calculate the reduced paid-up death benefit. The new death benefit is not necessarily equal to the cash value; it depends on the insurer’s calculation, the policy’s guarantees, the insured’s age, and the policy’s terms.

Once the reduced paid-up option is selected, no further premiums are required. The policy remains in force with the reduced death benefit, subject to its terms.
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is a non-forfeiture clause?

A non-forfeiture clause is a provision in many permanent life insurance policies that provides options if you stop paying premiums. Rather than allowing the policy to lapse automatically, it may let you use the policy’s accumulated value to retain some benefit.

Common non-forfeiture options include:

  • Cash surrender: Receive the policy’s cash surrender value in cash, subject to policy terms and potential tax consequences.
  • Extended term insurance: Use the policy’s value to purchase term life insurance, generally with the same or similar death benefit for a limited period.
  • Reduced paid-up insurance: Stop premiums while retaining a lower amount of paid-up permanent coverage.
  • Premium loan or automatic premium loan: Use available policy value to cover premiums temporarily, where available.

Non-forfeiture clauses are available with universal life insurance, as well. However, with universal life policies, you choose a pre-selected investment portfolio based on your risk tolerance.  As a result, the cash value of your universal life policy changes depending on the performance of the investment portfolio and can change the death benefit of a reduced paid-up policy or the term of an extended-term life policy. 

Ultimately, non-forfeiture clauses are a great way to protect yourself in the event you’re unable to pay further premiums. It provides options on converting the cash value you’ve worked so hard to build.
More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

How does reduced paid-up insurance work?

Reduced paid-up insurance works by using an eligible permanent life insurance policy’s available cash value to calculate a lower paid-up death benefit. Once selected, no further premiums are required, while the policy remains in force at the reduced coverage amount, subject to its terms.

If you can no longer afford premiums or no longer want to continue paying them, you may be able to use the reduced paid-up non-forfeiture option on an eligible permanent life insurance policy.

The insurer uses the policy’s available cash value to calculate a new, reduced paid-up death benefit. Once this option is selected, no further premiums are required, and the policy remains in force with the lower death benefit, subject to its terms.

Reduced paid-up insurance is generally available with some permanent life insurance policies, including certain whole life and universal life policies. Availability, eligibility rules, minimum policy duration, and the calculation method vary by insurer and product.

Term life insurance does not build cash value and therefore does not offer a reduced paid-up non-forfeiture option. A term policy’s death benefit is generally payable if the insured dies while the policy is in force during the selected term.

Our advisors’ take on the reduced paid-up policy process

Suppose you purchased a whole life policy seven years ago with a death benefit of $200,000. It has built up significant cash value over this time of around $50,000. 

You’re planning to retire in the next year. Your income will significantly drop, so you’ll have to reduce your monthly expenses as well. You speak with a life insurance advisor to see how you can reduce your monthly premiums. 

In this discussion, your advisor might suggest using your whole life policy’s cash value to purchase a reduced paid-up policy. This reduces your guaranteed death benefit to $50,000 but also eliminates premium payments. 

Such a solution is ideal for retirement because children are often grown up (meaning you no longer have financial dependents). Further, retirees commonly have little or no debts. If having a significant death benefit paid to your beneficiaries isn’t as important to you or you have estate funds saved up separately and you’d rather have the extra premium payments in your pocket, this might be a good option for you.

What’s the difference between reduced paid-up insurance and paid-up additions?

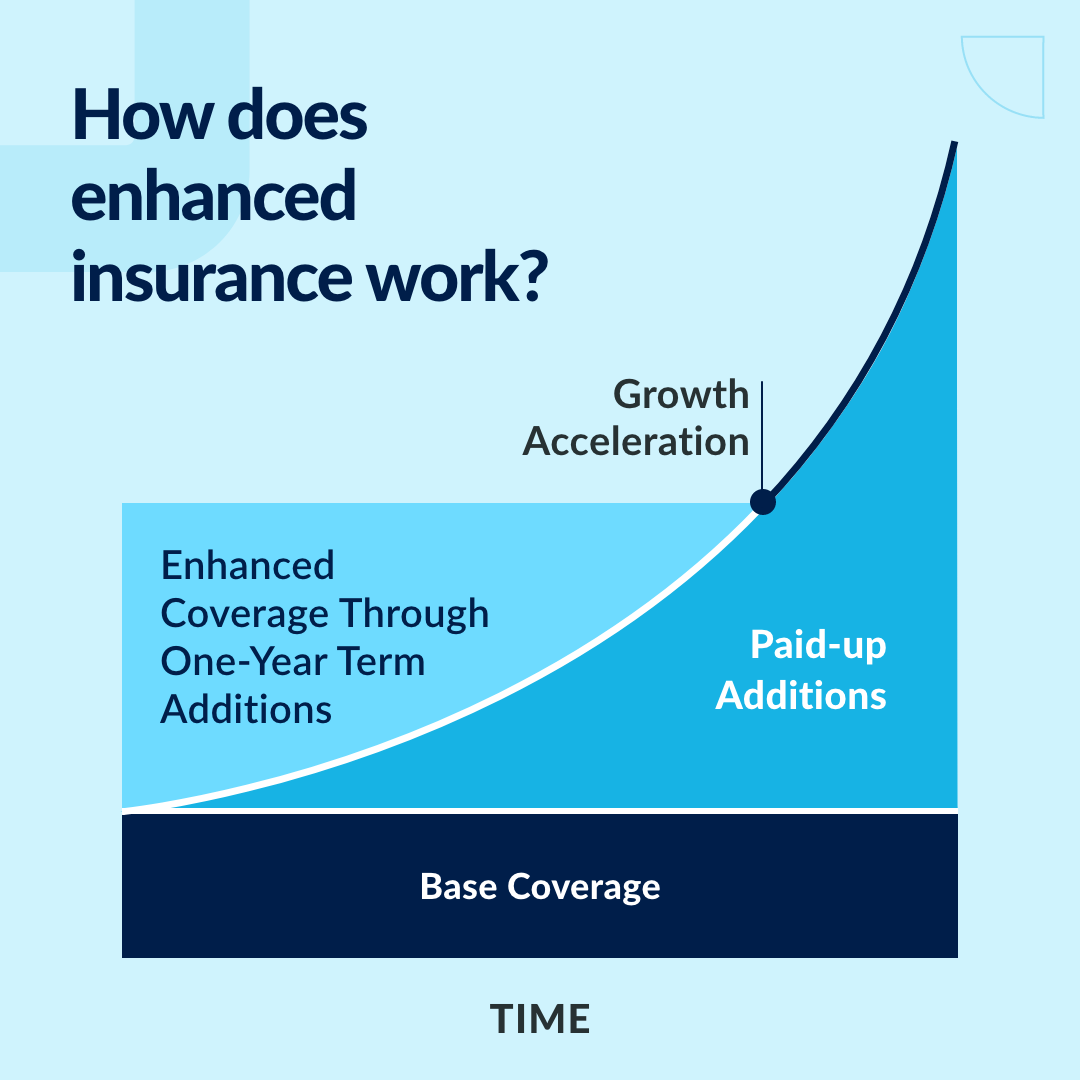
Reduced paid-up insurance and paid-up additions both involve paid-up life insurance, but they serve opposite purposes. Reduced paid-up insurance lets you stop required premiums while keeping a lower paid-up death benefit. Paid-up additions use declared dividends to add coverage to a participating whole life policy that generally remains in force, potentially increasing its death benefit and cash value.

Reduced paid-up insurance

Reduced paid-up insurance is a non-forfeiture option. If you stop paying premiums on an eligible permanent life insurance policy, the insurer may use the policy’s available cash value to calculate a new, lower paid-up death benefit. Once selected, no further premiums are generally required. The policy remains in force at the reduced coverage amount, subject to its terms.

The new death benefit is not necessarily equal to the policy’s cash value. It depends on the insurer, policy, insured’s age, policy duration, available cash value, outstanding loans, and any applicable non-guaranteed values.

Paid-up additions

Paid-up additions let you swap your whole life policy’s dividends for additional life insurance coverage. Unlike reduced paid-up insurance, you still pay the monthly premium to your original whole life policy, as your whole life policy is still in force, just with an increased death benefit amount.  

Paid-up additions are usually bought as a policy rider to your initial whole life insurance purchase. A rider is an optional add-on that supplements your whole life policy. In contrast, reduced paid-up insurance is a non-forfeiture clause option. Ultimately, paid-up additions are for someone who wants a larger death benefit without paying additional premiums. 

Feature Reduced paid-up insurance Paid-up additions
What it does Changes an existing eligible policy’s status after premiums stop Adds coverage to a policy that generally remains in force
Premiums on the base policy Stop Generally continue
Source of funding Policy’s available cash value Declared policy dividends, where available
Effect on death benefit Usually lowers it May increase it
Effect on cash value The original policy no longer continues accumulating cash value in the same way May increase the policy’s cash value
Best for Someone who cannot or does not want to continue paying premiums but wants some coverage Someone receiving dividends who wants to increase coverage

Paid-up additions

What’s the difference between reduced paid-up insurance and extended-term insurance?

Reduced paid-up insurance and extended-term insurance are both non-forfeiture options for eligible permanent life insurance policies. The main difference is that reduced paid-up insurance retains a lower amount of permanent coverage for life, while extended-term insurance uses the policy’s available value to provide term coverage for a limited period.

Reduced paid-up insurance

With reduced paid-up insurance, the insurer uses the policy’s available cash value to calculate a new, lower paid-up death benefit. Once selected, no further premiums are generally required, and the policy remains in force with the reduced coverage amount, subject to its terms.

The new death benefit is not necessarily equal to the policy’s cash value. It depends on the insurer, policy, insured’s age, policy duration, available cash value, outstanding loans, and any applicable non-guaranteed values.

Extended-term insurance

Extended-term policies provide a term life insurance policy that no longer requires premium payments. The cash value that has been accumulated from a whole life insurance policy is used to purchase term life insurance with a death benefit as close to your original whole life death benefit as possible. Because it’s a term life policy, the death benefit is only payable if you pass away during a particular period.

For example, say you had a whole life policy with a death benefit of $100,000 and an accumulated cash value of $10,000. With extended-term policies, the insurance provider would calculate how many years it would take for premium payments of $10,000 (your cash value) to equal $100,000 (your death benefit) in coverage. Say this takes 20 years. Therefore, you would exercise the non-forfeiture clause to purchase a term 20 policy with a death benefit of $100,000 and pay no premiums at all, it’s already paid for by your cash value. 

Feature Reduced paid-up insurance Extended-term insurance
Type of coverage after the change Permanent paid-up life insurance Term life insurance for a limited period
Premiums after the change None None
Death benefit Lower permanent death benefit Often closer to the original death benefit
Coverage duration Generally for life, subject to policy terms Limited period determined by the insurer’s calculation
Best for Lifelong coverage at a reduced amount Higher temporary coverage for a defined period

enhanced insurance
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

What’s the difference between reduced paid-up insurance and a cash surrender?

Reduced paid-up insurance and a cash surrender both use a permanent life insurance policy’s available cash value, but they produce very different outcomes. Reduced paid-up insurance lets you stop premiums while retaining a lower paid-up death benefit; a cash surrender ends the policy and provides its available surrender value in cash.

Reduced paid-up insurance

Choose reduced paid-up insurance if you can no longer afford or no longer want to pay premiums but still want a guaranteed death benefit for your beneficiaries. The coverage amount will be lower than the original policy, and the policy will no longer continue accumulating cash value in the same way.

Cash surrender

Choose a cash surrender if you no longer need life insurance coverage and want to receive the policy’s available surrender value in cash. Before surrendering, ask the insurer for the cash surrender value, outstanding loan balance, adjusted cost basis, and an estimate of any potential taxable policy gain.

Feature Reduced paid-up insurance Cash surrender
Premiums after the change None None
Death benefit A lower paid-up death benefit remains; it is calculated using the available cash value and is not necessarily equal to it No life insurance coverage remains
Cash received No Yes, the policy’s cash surrender value, subject to policy terms
Coverage continues Yes, at a reduced amount No
Potential tax outcome Generally, selecting the option is not itself a taxable disposition, but policy-specific rules apply A surrender may create taxable income if the amount received exceeds the policy’s adjusted cost basis
Best for Someone who still wants some life insurance coverage Someone who no longer needs coverage and wants to receive the policy’s available surrender value

Pros and cons of reduced paid-up insurance

Pros Cons
Lets you stop required premium payments The death benefit is usually much lower than the original coverage amount
Retains some life insurance coverage rather than surrendering the policy Reduces or ends further cash-value accumulation under the original policy structure
May preserve a guaranteed death benefit May not provide enough coverage for current or future dependants
Can help someone manage expenses during retirement or an income reduction Once selected, the decision may be difficult or impossible to reverse
May be available without a new medical underwriting process Availability and calculation methods vary by insurer and policy
Death benefit paid to a named individual beneficiary is generally tax-free Later loans, withdrawals, or surrender can have tax consequences

Who should consider reduced paid-up insurance?

Reduced paid-up insurance may suit someone who:

  • Can no longer afford premiums but wants to retain some life insurance coverage.
  • No longer needs the full original death benefit because debts have been repaid or dependants no longer rely on their income.
  • Wants permanent coverage rather than temporary extended-term coverage.
  • Wants to avoid surrendering the policy and losing all life insurance protection.
  • Has sufficient cash value for the insurer to calculate a meaningful reduced paid-up death benefit.

It may not be suitable if:

  • You still need the original death benefit for income replacement, mortgage protection, estate liquidity, or business planning.
  • Your cash value is too low to produce a useful reduced paid-up death benefit.
  • You want access to the policy’s cash value now.
  • You can afford to continue premiums and want to preserve the policy’s original coverage and cash-value growth.

Tax treatment of reduced paid-up insurance in Canada

In Canada, choosing reduced paid-up insurance is generally a non-forfeiture option rather than a surrender of the policy. As a result, selecting this option does not automatically create taxable income.

However, tax treatment can depend on the policy’s adjusted cost basis, prior loans or withdrawals, policy ownership, and whether the policy remains exempt under the Income Tax Act. A later surrender, withdrawal, or policy loan may have tax consequences; any amount above the policy’s adjusted cost basis may be taxable income.

A death benefit paid to a named individual beneficiary is generally received tax-free. Corporate-owned policies involve additional tax considerations, including the adjusted cost basis and capital dividend account.

Because tax rules and policy terms can be complex, obtain confirmation from the insurer and consult a qualified tax professional before making a decision.

Should you purchase reduced paid-up insurance?

Reduced paid-up insurance is a good option if you don’t want to continue premium payments but still want a death benefit for your beneficiaries. Just remember that the death benefit is usually reduced when compared to your whole life policy’s original payout amount.

This type of insurance is ideal if you no longer need the total amount of your whole life policy’s death benefit because you have fewer debts and/or financial dependents now. You might also consider it if you can no longer afford your whole life insurance premiums.

Whether you should purchase a reduced paid-up policy depends on your life circumstances, similar to any life insurance policy. Speak to one of PolicyAdvisor’s licensed insurance advisors today to determine whether a reduced paid-up insurance policy is right for you.

Frequently asked questions

What is reduced paid-up insurance?

Reduced paid-up insurance is a non-forfeiture option that lets you stop paying premiums on an eligible permanent life insurance policy while keeping a lower amount of paid-up coverage. The insurer uses the policy’s cash value to calculate the new death benefit.

Is the new death benefit equal to my cash value?

No. The insurer uses the cash value to calculate a reduced paid-up death benefit, but the new death benefit is not necessarily equal to the cash value. The calculation depends on the policy, insurer, insured’s age, and policy terms.

Does reduced paid-up insurance last for life?

Reduced paid-up insurance is generally permanent coverage, so it remains in force for life once selected, subject to the policy terms. Unlike extended-term insurance, it is not designed to expire after a fixed period.

Can I choose reduced paid-up insurance on a term policy?

Generally, no. Term life insurance usually does not build cash value and therefore does not offer a reduced paid-up non-forfeiture option. Reduced paid-up insurance is generally associated with permanent life insurance policies.

Is reduced paid-up insurance taxable?

Choosing reduced paid-up insurance does not automatically create taxable income in Canada. However, later withdrawals, policy loans, or a surrender may have tax consequences, particularly if the amount accessed exceeds the policy’s adjusted cost basis.

Can I reverse reduced paid-up insurance?

Usually, no. Once reduced paid-up insurance is selected, it may be difficult or impossible to restore the original policy. Ask the insurer about reinstatement rules, deadlines, and whether a new application or underwriting is required.

The information above is intended for informational purposes only and is based on PolicyAdvisor’s own views, which are subject to change without notice. This content is not intended and should not be construed to constitute financial or legal advice. PolicyAdvisor accepts no responsibility for the outcome of people choosing to act on the information contained on this website. PolicyAdvisor makes every effort to include updated, accurate information. The above content may not include all terms, conditions, limitations, exclusions, termination, and other provisions of the policies described, some of which may be material to the policy selection. Please refer to the actual policy documents for complete details. In case of any discrepancy, the language in the actual policy documents will prevail.  All rights reserved.

If something in this article needs to be corrected, updated, or removed, let us know. Email editorial@policyadvisor.com.
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Life Insurance for Self-employed in Canada

Self-employment is a significant part of Canada’s workforce, with about 2.7 million Canadians working for themselves in 2026, according to Statistics Canada’s Labour Force Survey. This includes both incorporated and unincorporated business owners. Unlike employees who may have access to workplace life insurance, life insurance can be important for self-employed Canadians too, who have dependants, debts, or business obligations. Some of the best companies offering life insurance for self-employed include Equitable Life, Manulife, Canada Life, RBC, Desjardins, and BMO Insurance.

Life insurance can be affordable!

Get the best life insurance quotes for self-employed in Canada!

What type of life insurance do self-employed people need in Canada? 

Most self-employed Canadians start with term life insurance for income and debt protection, then consider permanent coverage for lifelong needs, estate planning, or business succession. Term life insurance is often suitable for replacing income, covering a mortgage, or protecting dependants during working years. 

Many self-employed buyers combine a longer term for income replacement with shorter terms for specific debts, then convert part of the coverage later if needs become permanent. Whole life insurance can also be a good option for self-employed Canadians who want lifelong coverage, guaranteed cash value growth, and support for long-term estate or business planning.

Other types of life insurance available for self-employed individuals

Depending on how your business is structured and what you want to protect, you may also consider the following types of life insurance:

  • Universal life insurance: Combines permanent life insurance with an investment component and offers flexibility in premiums and coverage. However, investment performance and policy costs can affect the policy’s cash value
  • Business-owned life insurance: A corporation may own a policy on a business owner or key employee to help fund succession plans, repay business debts, or support a buy-sell agreement

Best life insurance companies for self-employed Canadians

The best life insurance companies for self-employed Canadians include RBC Insurance, Canada Life, Manulife, BMO Insurance, Desjardins, and Equitable Life.

★★★★★
Best for self-employed professionals interested in permanent life insurance and cash-value growth READ REVIEW
★★★★★
Best for self-employed business owners who want life insurance coverage that can grow with their business READ REVIEW
★★★★★
Best for incorporated business owners and business succession planning READ REVIEW
★★★★★
Best for high-income business owners who need substantial coverage and flexible protection READ REVIEW
★★★★★
Best for small businesses looking for bundled coverage READ REVIEW
★★★★★
Best for freelancers and sole proprietors who value a bank‑backed insurer READ REVIEW

1. Equitable Life

Equitable Life offers permanent life insurance with options to combine term and critical illness protection, making it suitable for self-employed Canadians who want to address multiple financial risks under one insurance strategy.

  • Term insurance options: Its term options include 10-Year Renewable Convertible, 20-Year Renewable Convertible, and Term 30/65
  • Permanent coverage: For lifelong coverage and wealth planning, Equimax Wealth Accumulator and Equimax Estate Builder participating whole life policies provide different approaches to cash value growth and estate planning. These options may appeal to established self-employed professionals who want their life insurance to serve a broader financial or legacy-planning purpose
  • Term insurance riders: Eligible permanent life policies can include additional term coverage, allowing business owners to insure temporary obligations, such as outstanding business loans, while maintaining lifelong protection
  • Critical illness riders: Its EquiLiving critical illness insurance rider provides coverage for 26 critical illnesses. A qualifying claim provides a lump-sum payment that can help cover household expenses or business obligations during recovery. EquiLiving provides a payment equal to 15% of the critical illness coverage amount, up to $50,000, for each qualifying early detection condition, without reducing the main critical illness benefit
  •  Best for: Self-employed professionals interested in permanent life insurance and cash-value growth
Equitable Life term life pricing

The cost of Equitable Life term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.89/month.

Equitable Life whole life pricing

The illustrative cost of Equitable participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $266.34 per month with a 20-pay option and paid-up additions as the dividend choice.

2. Manulife

Manulife life insurance plans are a good choice for self-employed individuals whose coverage needs can change as their family or income grows.

  • Term insurance option: Manulife’s Family Term is available for Term 10, Term 20, Term 65, or Term Life. It lets self-employed individuals choose from multiple coverage structures depending on their family circumstances
  • Business value protection rider: This rider allows business owners to purchase additional life insurance coverage based on increases in business value, without further medical underwriting
  • Whole life insurance: Manulife’s participating whole life insurance provides guaranteed premiums, guaranteed cash value growth, and the potential to earn annual dividends. Manulife’s current DSIR of 6.35% can appeal to those looking to build long-term cash value and support estate planning or business succession
  • Flexible funding options: Manulife’s Deposit Option allows policyholders to make additional deposits within their policy’s limits to increase coverage without further medical underwriting
  • Best for: Self-employed business owners who want life insurance coverage that can grow with their business
Manulife term life pricing

The cost of Manulife term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $9.47/month. 

Manulife whole life pricing

The illustrative cost of Manulife participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $331.71 per month with a 20-pay option.

3. Canada Life

Canada Life offers a broad range of life insurance options that can suit self-employed Canadians as their personal and business responsibilities grow. 

  • Term life plans: The flagship term life insurance plan, My Term, provides coverage starting from $100,000, ideal for temporary protection
  • Term lengths: My Term offers coverage periods from 5 to 50 years, with guaranteed premiums throughout the initial term. This allows business owners to match their life insurance coverage to the repayment period of a commercial loan, mortgage, or other financial obligation
  • Business growth protection rider: Available on My Term policies with 10- or 15-year options, this rider lets you purchase additional coverage without new medical underwriting, subject to the rider’s terms. It can help business owners increase coverage as their business insurance needs grow
  • Whole life plans: Canada Life also has a strong portfolio of participating plans, including Wealth Achiever, Balanced Achiever, and Estate Achiever. These plans are designed for early cash value growth and maximizing long-term payouts. It may be less suitable if you specifically want a non-participating permanent policy
  • Self-employed disability income enhancement: Eligible applicants with at least 20% business ownership may qualify for a 20% increase in insurable earned income, capped at $40,000 annually, when applying for disability insurance. This can increase the income considered when determining eligible monthly disability benefits
  • Best for: Incorporated business owners and business succession planning
Canada Life term life pricing

The cost of Canada Life term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $12.36/month.

Canada Life whole life pricing

The illustrative cost of Canada Life participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $587.52 per month with a 20-pay option and paid-up additions as the dividend choice.

4. RBC Insurance

RBC Insurance is a strong option for high-income self-employed professionals and business owners who need substantial coverage to protect their families, business loans, or ownership interests. Here’s why it is a good choice:

  • Term policy coverage: RBC YourTerm offers coverage from $100,000 to $25 million, making it a good fit for high business liabilities and shareholder agreements
  • Term policy length: It is available in terms of 10 to 40 years, allowing self-employed applicants to match protection to long-term financial obligations as their income keeps fluctuating
  • Conversion features: YourTerm term policies can also be converted to permanent insurance without new medical underwriting before the policy anniversary nearest age 71. This conversion feature helps business owners maintain coverage as their priorities shift from income replacement to estate planning
  • Whole life insurance plans: RBC also offers Growth Insurance and Growth Insurance Plus, participating whole life plans that combine permanent coverage with the potential to earn policyholder dividends
  • Dividend options: Both plans offer five dividend options, giving policyholders flexibility in how they use dividends to support their long-term financial goals. Self-employed business owners can choose paid-up additions to increase their policy’s cash value and death benefit over time, helping build lasting value for estate planning and wealth transfer
  • Best for: High-income business owners who need substantial coverage and flexible protection 
RBC term life pricing

The illustrative cost of RBC term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately around $13.41/month. 

RBC whole life pricing

The illustrative cost of RBC participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $285.39 per month with a 20-pay option and paid-up additions as the dividend choice.

5. Desjardins

Desjardins is a strong option for self-employed Canadians who want life insurance that can grow alongside their business, with solutions for succession planning, key person protection, and disability income replacement.

  • Term insurance plans: Its term insurance portfolio includes Term 10/15/20/25/30 or Term to 65, with fixed premiums and the option to convert to permanent coverage. This can give freelancers and business owners room to adjust their protection as their income, debts, and family obligations evolve
  • Whole life insurance: For those looking beyond term insurance, Desjardins offers participating and permanent solutions such as 5-Pay PAR, Estate Enhancer, and Accelerated Growth. Desjardins is one of the very few insurers in Canada that offers a 5-pay limited pay policy
  • Business insurability coverage: This optional rider on life insurance policies allows business owners to increase their coverage based on the growth in their business, up to three times the original coverage amount during the first 10 policy years, without new medical underwriting. This is particularly useful when a growing business requires more insurance to fund a shareholder buyout or protect an increasingly valuable company
  • SOLO disability income insurance: Designed specifically for self-employed individuals, including sole proprietors, partners, incorporated business owners, and agricultural producers. This provides a separate income protection solution for those who cannot rely on employer-sponsored disability benefits
  • Best for: Small businesses looking for bundled coverage
Desjardins term life pricing

The cost of Desjardins term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $12.15/month. 

Desjardins whole life pricing

 The illustrative cost of Desjardins participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $269.73 per month with a 20-pay option and paid-up additions as the dividend choice.

6. BMO Insurance

BMO Insurance offers life insurance options for self-employed Canadians to protect their families, manage financial obligations, and gain additional financial flexibility in the event of a terminal illness.

  • Term insurance plan: BMO Insurance offers term life insurance with 10-, 15-, 20-, 25-, and 30-year terms and up to $30 million in coverage for eligible applicants. Its dedicated Business Guaranteed Insurability option can also help business owners increase coverage as their business grows
  • Financial hardship life advance: Permanent life insurance policyholders with a life expectancy of five years or less may apply for an advance of up to $250,000, payable over five years. This may help self-employed individuals manage expenses while facing serious health and financial challenges
  • Whole life insurance plan: For permanent coverage, BMO’s Estate Protector and Wealth Accelerator whole life plans offer guaranteed cash values and level premiums. These can support long-term estate planning or provide greater access to cash value for self-employed individuals
  • Performance bonus: BMO’s non-participating whole life insurance policies offer a Performance Bonus that can help freelancers or other self-employed Canadians build policy value while maintaining permanent life insurance coverage. This can support long-term financial planning and provide a financial legacy for their families
  • Best for: Freelancers and sole proprietors who value a bank‑backed insurer
BMO term life pricing

The cost of BMO term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $11.16/month.

BMO whole life pricing

The cost of BMO non-participating whole life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage is $252.63 per month with a 20-pay option and paid-up additions as the dividend choice.

Comparing the best life insurance companies for self-employed in Canada

Features Equitable Life Manulife Canada Life RBC Desjardins BMO
PolicyAdvisor Ratings 5/5 5/5 4.5/5 4.5/5 4.5/5 4.5/5
Cost for a 40-year-old male non-smoker($100,000 in coverage for 10-year term) $10.89/month $9.47/month $12.36/month $13.41/month $12.15/month $11.16/month
Life insurance options Term 10, Term 20, Term 30/65, participating whole life Family Term 10, Term 20, Term 65, Term-Life, participating whole life My Term and participating whole life YourTerm and participating whole life Term 10-30, Term to 65, participating and permanent life insurance Term 10–30, non-participating whole life
Business-owner suitability Term riders for temporary business debts Business Value protector rider Business growth protection rider High coverage limits for high-earning self-employed Business insurability coverage and SOLO disability income insurance Business guaranteed insurability option
Coverage options and flexibility Convertible term plans, permanent coverage, and critical illness rider options Multiple term structures, conversion to permanent coverage, and additional deposits Range of term lengths; conversion options and participating whole life plans 10-40 year terms, high coverage limits, conversion options Multiple term lengths, conversion to permanent coverage, and business-specific riders Multiple term lengths, guaranteed cash values under whole life plans, and a performance bonus
AM Best Rating A A+ A+ A A A

Our methodology for ranking the best life companies for self-employed

Our 2026 rankings for the best term life insurance companies or whole life insurance for self-employed individuals in Canada are based on pricing, product features and financial strength. We evaluated the top Canadian insurers to identify the best 6 options for freelancers, sole proprietors, incorporated business owners, high-income business owners, and other self-employed individuals with different financial responsibilities and long-term goals.

1. Pricing (30%)

We compared premiums for a $100,000, 10-year term life insurance policy for a 40-year-old male non-smoker. We considered affordability and how each insurer’s pricing compares with the other companies in our rankings. Lower premiums received higher scores, provided the policy offered suitable coverage.

Insurer name Male (non-smoker)
Equitable Life $10.89/month
Manulife $9.47/month
Canada Life $12.36/month
RBC $13.41/month
Desjardins $12.15/month
BMO Insurance $11.16/month

Term life cost for self-employed Canadians

Term premiums are illustrative monthly costs for a 40-year-old non-smoker male seeking $100,000 of coverage for a 10-year term. Actual premiums vary by age, sex, health, smoking status, product, coverage amount, and underwriting. All premiums listed on Y-azix are in CAD (CA$).

2. Product features and financial strength (70%)

We assessed each insurer on the criteria below and the listed weights:

Evaluation criteria What we assessed Weightage
Life insurance options Availability of term and permanent life insurance, including participating whole life policies, to meet different personal, business, and estate-planning needs 20%
Business-owner suitability Business-focused features, such as options to increase coverage as a business grows, protection for business debts, and support for business continuity and succession planning 20%
Coverage options and flexibility Available term lengths, conversion privileges, coverage limits, riders, and options to adapt coverage as income, family responsibilities, and business needs change 20%
AM Best Rating AM Best Rating to indicate company’s financial strength 10%

Pricing30%
Life insurance options20%
Business-owner suitability20%
Coverage options and flexibility20%
AM Best Rating10%

How we further assessed the ratings:

We assigned each insurer a score out of five for every evaluation criterion based on its available products, features, pricing, and financial strength. We then applied the respective ratings for each feature to come up with the overall rating. The final ratings reflect the combined weighted scores across all five criteria.

Equitable Life and Manulife received 5/5 ratings for their broad product options, flexible coverage, and product features. Canada Life received 4.5/5 for its participating whole life plans and business succession features, while RBC and Desjardins received 4.5/5 for their flexible coverage options and business-owner protection features. BMO also received 4.5/5, reflecting its competitive term pricing, business coverage options, and non-participating plans.

PolicyAdvisor ratings for the best companies for self-employed:

Features Pricing (30%) Life insurance options (20%) Business-owner suitability (20%) Coverage options and flexibility (20%) AM Best Rating (10%) Final ratings
Equitable Life 5/5 5/5 4.5/5 5/5 4.5/5 5/5
Manulife 5/5 5/5 4.5/5 5/5 5/5 5/5
Canada Life 4.5/5 5/5 4.5/5 5/5 5/5 4.5/5
RBC 4.5/5 5/5 4.5/5 4.5/5 4.5/5 4.5/5
Desjardins 4.5/5 4/5 4.5/5 4.5/5 4.5/5 4.5/5
BMO  4.5/5 4/5 4.5/5 4.5/5 4.5/5 4.5/5

Ratings are based on PolicyAdvisor’s weighted methodology and illustrative 2026 pricing. Actual premiums, eligibility, and product features vary by applicant and policy. Rankings are for comparison purposes and do not indicate the best or cheapest insurer for every individual. Pricing scores consider the illustrative term and permanent premiums together with minimum available coverage amounts. The score is not based on term premiums alone.

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Why do self-employed people need life insurance?

Life insurance is a crucial financial tool for self-employed Canadians, including freelancers or gig workers. Here are some of the reasons why you should have it:

  • No workplace life insurance: Self-employed individuals do not have access to employer-sponsored life insurance, so they need to arrange their own coverage 
  • Business debts: Life insurance can provide funds to help repay business loans, lines of credit, or other outstanding obligations after the owner’s death
  • Lost income: A death benefit can help replace the income the family depends on and cover ongoing household expenses
  • Estate liabilities: The proceeds from whole life insurance can provide liquidity to help cover taxes, debts, and other estate-related liabilities without forcing the family to sell assets
  • Business continuity: Coverage can help the business manage the financial impact of losing an owner or key person
  • Key-person risk: If a business relies on the owner’s expertise, relationships, or leadership, life insurance can help cover the financial disruption caused by their death, including recruitment costs and lost revenue
  • Buy-sell agreements: Business partners can use life insurance to fund a buy-sell agreement, allowing surviving owners to buy the deceased owner’s share from their estate and helping the business maintain continuity

Life insurance for self-employed by life stage

Life insurance needs can change as a self-employed person’s income, family responsibilities, debts, and business grow. The type and amount of coverage should reflect both personal financial needs and, where applicable, business obligations.

Life stage Life insurance considerations Life insurance policy to consider
20s: Starting a career or business Protect income, cover debts, and secure coverage while premiums are generally lower Term life insurance with lower coverage but longer policy term
30s: Growing income and family Protect dependants, mortgage payments, childcare costs, business debts, and future income Term life insurance or laddered term policies
40s and 50s: Established business and financial commitments Account for higher income, business debts, family obligations, and growing business value Term life insurance for temporary needs and whole life insurance for lifelong coverage
60s and beyond: Retirement and succession Focus more on estate planning, business succession, taxes, and leaving an inheritance Permanent life insurance, such as whole life or universal life

Life insurance for freelancers vs. incorporated business owners

Both freelancers and incorporated business owners may need life insurance to protect their families and financial commitments.

Considerations Freelancers / sole proprietors Incorporated business owners
Primary need Protect personal income and dependants Protect personal finances and business interests
Policy ownership Personally owned Can be personally or corporately owned, depending on the policy’s purpose
Key coverage considerations Income, mortgage, debts, dependants, and business expenses Income, dependants, corporate debts, shareholders, succession, and estate needs
Amount of coverage Moderate Higher than freelancers
Estate planning Primarily focused on family and personal assets May also involve corporate assets, shares, and estate planning

How much life insurance coverage do self-employed people need? 

Self-employed Canadians need life insurance coverage of at least 7-10 times their income. As they lack employer-sponsored coverage, they must take into account both business expenses and personal financial obligations to choose an adequate coverage amount. 

You can use the DIME method to estimate your life insurance needs. DIME stands for debts, income, mortgage, and education. The calculation considers your total debts, the income your family would need to replace and for how many years, your outstanding mortgage, and your children’s future education costs.

Let’s understand this with an example.

Suppose a self-employed person has:

  • Debts: $50,000
  • Annual income: $100,000
  • Income replacement period: 10 years
  • Mortgage: $400,000
  • Children’s education: $100,000

Using the DIME method:

$50,000 + ($100,000 × 10) + $400,000 + $100,000 = $1,550,000

Based on these figures, they would need approximately $1.55 million in life insurance coverage. In case you have existing savings or investments, you can choose a lower coverage amount. You can also use our life insurance calculator to get exact estimates of the premium you need to pay. 

How is life insurance taxed for self-employed Canadians?

The tax treatment of life insurance depends on how the policy is owned, who pays the premiums, and why the coverage is being used. Key points for self-employed Canadians include:

  • Personal life insurance premiums: Generally, premiums for personally owned life insurance are not tax-deductible, even if you are self-employed
  • Death benefit: Life insurance death benefits are tax-free to the beneficiary when paid after the insured person’s death
  • Business-owned policies: When a corporation owns a life insurance policy, the tax treatment can differ from a personally owned policy. The corporation generally cannot deduct premiums as a regular business expense if the business benefits from the death benefit
  • Corporate death benefit: When a corporation receives the death benefit, the proceeds can generally be credited to the Capital Dividend Account (CDA), allowing eligible amounts to be distributed to shareholders as tax-free capital dividends.

Corporate ownership, shareholder benefits, estate planning, and the CDA can create complex tax consequences. Self-employed business owners should consult a qualified tax professional before structuring or claiming tax treatment for a life insurance policy.

What mistakes should self-employed people avoid when buying life insurance?

Self-employed individuals can face fluctuating income. Here are the mistakes they should avoid when buying life insurance in Canada:

  • Not updating beneficiary details: Not reviewing beneficiary designations after marriage, divorce, children, or business changes
  • Underestimating business debts: Include business loans, lines of credit, and personal debts when calculating coverage, even if personal and business finances are kept separate
  • Ignoring the lack of workplace coverage: Self-employed individuals cannot rely on employer-sponsored life insurance and need to arrange sufficient personal coverage. They might have to choose higher coverage amounts 
  • Buying only enough coverage for personal needs: Business owners may also need coverage for business continuity, key-person protection, or a buy-sell agreement
  • Choosing the wrong policy type: Term insurance may suit temporary income-replacement needs, while permanent insurance may be more appropriate for lifelong coverage or certain estate and business-planning needs
  • Overlooking policy laddering: Buying multiple term policies with different durations can provide higher coverage while financial obligations are greatest and reduce coverage as those obligations decline
  • Choosing the cheapest policy without comparing features: Premiums are important, but self-employed or freelancers should also compare coverage amounts, term lengths, policy features, exclusions, and insurer underwriting requirements

Why is life insurance more important for self-employed than employees?

Life insurance can be especially important for self-employed Canadians because they do not have access to employer-sponsored life insurance or workplace benefits. They are responsible for arranging their own coverage to protect their family and income. Life insurance for self-employed individuals can help them cover business debts, replace lost income, support business continuity, and provide funds for estate liabilities. For business owners, adequate coverage can therefore protect both their family’s financial security and the future of their business.

Can life insurance protect a business partner or co-owner?

Yes, life insurance can protect business partners or co-owners. Each partner can have life insurance coverage that provides money to the surviving partners if one partner dies. The proceeds can then be used to buy the deceased partner’s share of the business. This can help keep the business with the existing owners and give the deceased partner’s family fair value for their ownership.

Can a corporation be the owner of my life insurance policy?

Yes, a corporation can generally own a life insurance policy. This is commonly referred to as corporate-owned life insurance (COLI). However, corporate ownership has different tax and estate-planning implications than personally owned insurance. The corporation may be the policyholder and beneficiary, and the death benefit may create a credit to the corporation’s Capital Dividend Account (CDA).

Our advisor’s take on the best life insurance for self-employed individuals

At PolicyAdvisor, we recently helped a 35-year-old self-employed consultant who had built a growing business while also supporting a young family. He had a house loan, business loan, and no employer-sponsored life insurance, so he wanted coverage that could protect both his family’s income and his business obligations if he died unexpectedly. We recommended RBC Insurance’s YourTerm to our client.

Client profile:

  • Age: 35
  • Occupation: Self-employed consultant
  • Family: Married with two young children
  • Primary concern: Income replacement, mortgage, and business debt
  • Coverage goal: $1 million of life insurance
  • Additional priority: Coverage that could adapt as the business and family grow

Why we recommended RBC Insurance’s YourTerm:

  • Flexible term options: He could choose a term length from 10-40 years that matched his mortgage, business debt, and peak earning years.
  • Adequate coverage limits: RBC YourTerm offers coverage for $1 million for eligible applicants, allowing him to insure both personal and business financial obligations
  • Conversion option: He can convert term coverage to permanent insurance without new medical evidence, helping preserve coverage if his long-term needs change
  • Term laddering strategy: He could combine policies with different term lengths to provide higher coverage while his mortgage, business debt, and income-replacement needs are highest, then reduce coverage as those obligations decline
  • Participating whole life option: If his needs later shift toward permanent coverage and cash-value growth, RBC Growth Insurance offers participating whole life insurance with potential dividends. RBC’s 2026 dividend scale interest rate is 6.30%, although dividends will not be guaranteed
Quotes Icon Author Photo
Jason Goveas
Life insurance advisor
We recommended RBC Insurance’s YourTerm for its high coverage limits, flexible term options, and ability to convert or exchange coverage as his needs change.

How to purchase life insurance for self-employed people in Canada?

With PolicyAdvisor, you can compare quotes from 30+ insurers and work with licensed advisors to find coverage that fits your personal and business needs. Here are the steps you need to follow to get the best whole life insurance or term life insurance:

  • Calculate your coverage needs: Consider income replacement, mortgage, personal and business debts, education costs, and business obligations
  • Choose your policy type: Compare term life, participating life, and non-participating whole life insurance based on your financial goals
  • Compare quotes: Our advisors at PolicyAdvisor help you compare premiums and coverage options from multiple insurers
  • Apply for coverage: Complete your application and any required medical underwriting
  • Review your policy: Reassess your coverage as your income, business, debts, and family responsibilities change

Schedule a call now with one of our licensed advisors to get started!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Do self-employed people need life insurance in Canada?

Yes, self-employed Canadians need life insurance. They do not have employer-sponsored life insurance, so they need to arrange their own coverage. Life insurance can help their beneficiaries replace lost income, cover personal and business debts, and protect the family or business after the insured person dies.

Is term or whole life insurance better for self-employed people?

The answer to whether term or whole life is better for self-employed people depends on their financial obligations. Term insurance can provide cost-effective income replacement and debt protection, while whole life or universal life may be more appropriate for lifelong coverage, estate planning, or certain business needs. So, analyse your coverage and budget and pick the right policy.

Can life insurance cover business debts?

Yes, life insurance can provide funds to help repay outstanding business loans and other obligations after the owner’s death. The appropriate ownership and beneficiary structure will depend on the business and purpose of the coverage.

Can freelancers get life insurance in Canada?

Yes, freelancers and independent contractors can apply for life insurance like other Canadians. Insurers may consider factors such as income, occupation, health, lifestyle, and the amount of coverage requested when assessing their life insurance application.

Can I use life insurance to protect my business partner?

Yes, your life insurance contract can be used to protect your business partner. The policy can provide funds to purchase the deceased partner’s ownership interest and help the business continue operating.

Should self-employed people consider term life insurance laddering?

Yes, self-employed people can consider the term insurance laddering feature. The laddering option can be useful when financial obligations are expected to decline over time. For example, you could combine policies with different terms so that coverage is higher while mortgages, business debts, and income-replacement needs are greatest.

What are the best life insurance companies for self-employed people in Canada?

Some of the top life insurance companies for self-employed Canadians include Canada Life, RBC Insurance, BMO Insurance, Desjardins, Manulife, and Equitable Life. The right insurer depends on your coverage needs, business structure, income, financial obligations, and whether you need term or permanent life insurance.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is limited pay life insurance?

Limited pay whole life insurance is a type of permanent life insurance that provides coverage for life while allowing you to complete premium payments over a fixed period, commonly 10 or 20 years, or until a chosen age such as 65. Once the payment period ends, the policy is fully paid up: no further premiums are required, but the death benefit and cash value can continue.

It differs from traditional life-pay whole life insurance, where premiums are generally payable for life. Since limited-pay policies concentrate premiums into fewer years, their annual premiums are usually higher, but they may appeal to Canadians who want permanent protection without a lifelong premium commitment.

This guide explains how limited pay whole life insurance works in Canada, what it costs, how its cash value and tax treatment work, and when it may be a better fit than term life or traditional whole life insurance.

How does limited pay whole life insurance work?

Limited pay whole life insurance lets you pay premiums for a limited period while maintaining permanent coverage. Once the payment period ends, the policy becomes fully paid up, meaning no further premiums are required.
Here’s how the process typically works:

  • Choose a whole life insurance policy: Select a policy that meets your coverage, cash-value, and long-term financial goals.
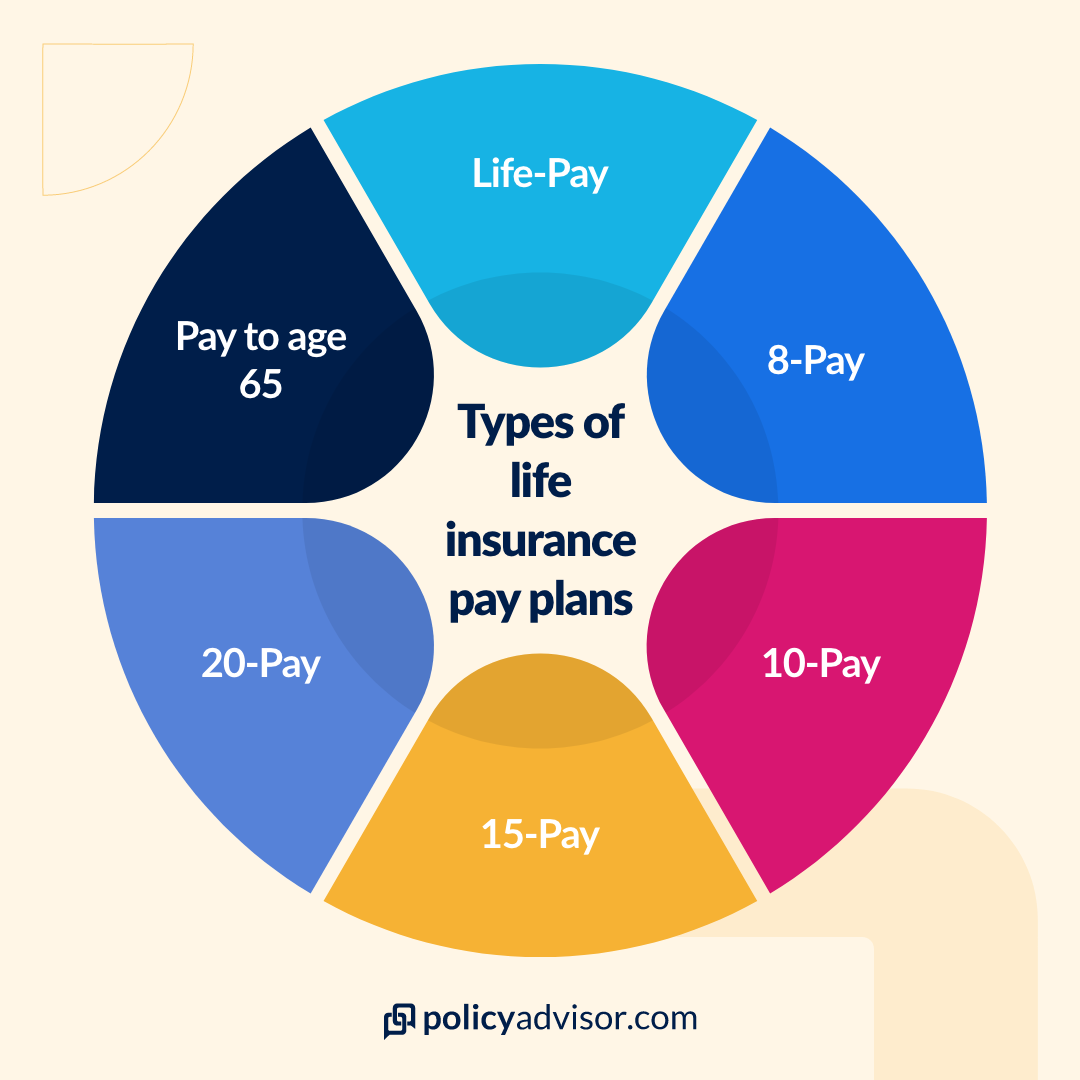
  • Select a payment period: Choose how long you want to pay premiums, such as 5-pay, 10-pay, 15-pay, 20-pay, pay-to-65, or another available structure. The payment period determines how quickly you fund the policy.
  • Apply and complete underwriting: Submit an application and provide the information the insurer needs to assess your age, health, lifestyle, coverage amount, and final premium.
  • Pay premiums for the selected period: Pay level premiums annually, monthly, or on another available frequency for the chosen limited-pay period.
  • Build cash value and maintain coverage: Premium payments help fund the policy’s cash value and support the death benefit payable to your beneficiaries. The death benefit is generally in place from the policy’s effective date, subject to its terms.
  • Cash value may grow over time: If the policy qualifies as exempt under Canada’s Income Tax Act, its cash value may grow without annual accrual taxation. Non-exempt policies may be subject to annual accrual taxation under the applicable rules. Participating policies may also receive dividends, although dividends are not guaranteed.
  • Access cash value if needed: Once sufficient value has accumulated, you may be able to borrow against or withdraw from the policy, subject to its terms. Loans and withdrawals can reduce the cash value and death benefit. For tax purposes, a loan or withdrawal is treated as a disposition, and any amount above the policy’s adjusted cost basis may be taxable income.
  • The policy becomes fully paid up: When you complete the selected payment period, no further premiums are required. The policy remains in force for life, subject to its terms.
  • Lifetime coverage continues: The policy remains in force for your lifetime, and a death benefit is generally paid tax-free to a named individual beneficiary. Corporate-owned policies involve additional tax considerations, including the adjusted cost basis and capital dividend account.
Learn about some of the most affordable whole life insurance plans in Canada.

See how much whole life insurance coverage you can get

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500

Key features and benefits of limited pay whole life insurance

Limited pay whole life insurance offers permanent coverage, premiums that end after a defined period, and the potential to build cash value for long-term goals without paying premiums for life. It is designed for Canadians who want lifetime coverage without a lifelong premium commitment.

Here are its key features and benefits:

  • Short premium payment window: Lifetime protection with a compressed, level premium payment period
  • Guaranteed cash value: Builds steadily every year. Growth is generally tax-deferred for exempt policies, while non-exempt policies are taxed annually on the increase
  • Dividend accumulation: Participating policies earn dividends that enhance coverage or cash value. Dividends are not guaranteed and depend on company’s performance
  • Paid-up additions: Dividends can be used to buy extra insurance for compound growth
  • Tax advantages: Exempt policies enjoy tax-deferred cash value growth and generally tax-free death benefits; non-exempt policies are taxed on growth, and some corporate or policy loan situations may affect death benefits

Types of limited pay whole life insurance in Canada

Limited pay whole life insurance is available in several payment structures. 10-pay and 20-pay are among the more common options, while 5-pay, 8-pay, 15-pay, and pay-to-65 may have more limited availability depending on the insurer and product.

Each structure determines how long you pay premiums before the policy becomes fully paid up. After that, no further premiums are required, while coverage and any accumulated cash value continue under the policy’s terms.

5-pay whole life: 

With 5-pay whole life insurance, you pay premiums for five years. This is a short, high-commitment structure that may suit high-income earners or people using the policy for estate or business planning who want to complete premium payments quickly. Because the same permanent coverage is funded over only five years, annual premiums are usually higher than with longer payment periods.

8-pay whole life:

8-pay whole life insurance spreads premiums over eight years. It may be available from a limited number of insurers and can offer a shorter premium-commitment period without concentrating payments as heavily as a 5-pay policy. It may suit business owners or professionals who want permanent coverage and an earlier paid-up status while managing annual premium costs.

10-pay whole life:

With 10-pay whole life insurance, you pay premiums for 10 years. This is one of the more commonly offered limited-pay structures. It may suit people who want a clear end date for premium payments before retirement and are comfortable with higher annual premiums in exchange for completing payments sooner. Cash value may build according to the policy’s guaranteed schedule, but early cash value can still be limited.

15-pay whole life:

15-pay whole life insurance spreads premiums over 15 years. It can offer a middle ground between completing payments relatively early and keeping annual premiums more manageable. Availability may be more limited than for 10-pay or 20-pay policies. It may suit mid-career professionals who want to complete premium payments before or around retirement while balancing cash flow.

20-pay whole life:

With 20-pay whole life insurance, you pay premiums over 20 years. This is one of the more common limited-pay options because it spreads the cost of permanent coverage over a longer period. It may suit younger buyers who want permanent coverage and a defined end date for premiums, while keeping annual costs lower than a 5-pay, 8-pay, or 10-pay structure.

Pay-to-65 whole life:

Pay-to-65 whole life insurance requires premium payments until age 65. This structure aligns the payment period with many people’s working years. Once you reach age 65, required premiums stop and the policy remains in force for life, subject to its terms. It may suit people who want permanent coverage but prefer to spread premiums across their career rather than complete them earlier.

To see how these payment terms work in practice, let’s look at a real-life example of a 20-pay policy.

Jack, age 35, buys a $100,000 20-pay whole life insurance policy. He pays a level premium for 20 years. At age 55, he completes the scheduled premium period and the policy becomes fully paid up. From that point, no further premiums are required. The policy remains in force for life, subject to its terms.

If the policy is participating and dividends are declared, Jack may choose an available dividend option. Dividends are not guaranteed and may be used, where available, to purchase paid-up additions, accumulate with interest, reduce premiums, or remain within the policy.

The actual premium, cash value, death benefit, and dividend results depend on the insurer, product, Jack’s age and health, smoking status, coverage amount, payment frequency, and the insurer’s current dividend scale.

Type of limited pay
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Limited pay vs. traditional whole life insurance

Limited pay whole life insurance lets you complete premium payments over a fixed period, while traditional whole life generally requires premiums for a longer period, often to age 100. Limited pay policies usually have higher annual premiums but can eliminate required premiums earlier; traditional policies usually have lower annual premiums but involve a longer payment commitment.

Difference between limited pay and traditional whole life insurance plans


Feature Limited pay whole life insurance Traditional whole life insurance
Premium payment period Pay premiums for a fixed payment term (5,10 or 20 years) Pay premiums for life (no fixed term)
Premium amount Higher annual premiums due to the shorter payment term Lower annual premiums spread over a lifetime
Cash value growth Builds faster due to front-loaded payments Gradual
Ideal for  Business owners, high-income earners, parents funding policies for children, pre-retirees, and those who are focused on estate planning Those who prefer smaller, ongoing premium payments and those seeking lower-cost lifetime coverage using whole life for final-expense needs

The trade-off is that limited pay plans cost more in the short term but deliver payment-free coverage for life. Traditional plans cost less annually but keep you tied to premiums for decades. For Canadians who value financial independence before retirement, limited pay options often strike the right balance between cost, flexibility, and lifetime protection.

To see how this works, here is an illustration depicting a non-smoking 30-year-old female paying $10k annually in premiums:

Features 10-Pay 20-Pay Life Pay
Annual Premium $10,000 $10,000 $10,000
Total Premiums Paid $100,000 $200,000 $700,000
Years Paying Premiums 10 years 20 years Life Pay
Cash Value at Year 20 $145,524 $227,186 $232,021
Death Benefit at Year 20* $605,336 $992,012 $1,591,999
Cash Value at Year 30 $271,563 $429,421 $549,016
Death Benefit at Year 30* $673,570 $1,065,111 $1,612,803
Cash Value at Year 40 $486,605 $776,676 $1,080,086
Death Benefit at Year 40* $887,092 $1,415,896 $2,110,007

Limited pay whole life vs. term life insurance

Limited pay whole life insurance and term life insurance both provide a death benefit, but they solve different problems. Limited pay whole life is permanent coverage with cash value and a defined premium-payment period; term life is lower-cost coverage for a fixed period, such as 10, 20, or 30 years, with no cash value.

Feature Limited pay whole life Term life insurance
Coverage period Lifetime, subject to policy terms Fixed term, commonly 10–30 years
Premium payment period Fixed limited period, such as 10 or 20 years Usually throughout the selected term
Annual premium Higher because premiums are concentrated Lower for the same initial death benefit
Cash value Yes; guaranteed cash value may build over time No
Dividends Possible with participating policies; not guaranteed No
Best for Estate planning, lifelong dependants, business planning, long-term wealth transfer Income replacement, mortgage protection, and temporary family needs

Pros and cons of limited pay whole life insurance

Pros Cons
Provides permanent coverage rather than coverage that expires after a selected term Annual premiums are higher than life-pay whole life and substantially higher than comparable term coverage
Premium payments end after the selected limited-pay period Requires a strong, predictable cash-flow commitment during the funding years
Builds guaranteed cash value, subject to the policy’s terms Cash value is usually limited in the early policy years
May receive dividends if it is a participating policy; dividends are not guaranteed Dividends, loan interest, and non-guaranteed values can make illustrations more complex
Can support estate planning, business continuity, or coverage for a child Once issued, the payment schedule may be difficult or impossible to change
Death benefit is generally paid tax-free to a named beneficiary Accessing cash value through withdrawals or loans can reduce the death benefit and may create taxable income

How much does limited pay whole life insurance cost?

Limited pay whole life insurance usually costs more per year than traditional life-pay whole life because the same permanent coverage is funded over fewer years. A 10-pay policy generally has the highest annual premium, while a 20-pay policy spreads the cost over twice as long.

Pay-to-65 or pay-to-100 designs may have lower annual premiums but require payments for longer. Your premium depends on your age, sex as used for underwriting, smoking status, health, coverage amount, policy type, and whether the policy is participating or non-participating.

Insurer name 10-pay 20-pay Pay-to-100
Sunlife $335.93/month $238.86/month $124.02/month
Desjardin $418.59/month $216.18/month $131.67/month
IA $388.08/month $215.01/month $120.06/month
Empire Life $318.87/month $177.84/month $105.12/month

*Illustrative monthly whole life insurance cost for 30-year old male non-smoker seeking $100k coverage for a participating whole life insurance for 10-pay, 20-pay, and pay-to-100.

Tax treatment of limited pay whole life insurance

In Canada, the tax treatment of a limited pay whole life policy depends largely on whether it qualifies as an exempt policy under the Income Tax Act. For an exempt policy, cash-value growth inside the policy is generally not subject to annual accrual taxation.

A death benefit paid to a named beneficiary is generally received tax-free. However, accessing the policy’s cash value can have tax consequences: a policy loan or withdrawal is treated as a disposition for tax purposes, and any amount above the policy’s adjusted cost basis may be taxable income.

Corporate-owned policies have additional considerations. A corporation may receive the death benefit tax-free, and the portion of the death benefit above the policy’s adjusted cost basis may be credited to its capital dividend account, subject to the applicable rules. Tax outcomes can also change if a policy ceases to be exempt, is transferred, or is surrendered.

Limited pay whole life insurance providers in Canada

Limited pay whole life insurance is not a single standardized product. Availability, payment periods, guaranteed values, dividend options, and policy features vary by insurer. Common structures include 10-pay and 20-pay participating whole life, while some insurers offer 5-pay, 8-pay, 15-pay, pay-to-65, or pay-to-100 designs.

Canadian insurers offering limited-pay options include Equitable Life, Manulife, Empire Life, Sun Life, BMO Insurance, Canada Life, Desjardins, iA Financial Group, RBC Insurance, and Wawanesa Life. Learn more about the best limited pay whole life insurance companies in Canada.

Who should consider limited pay whole life insurance in Canada?

Limited pay whole life insurance may suit high-income professionals, business owners, parents buying coverage for children, retirement planners, and people with estate-planning goals. It is generally best for people who need permanent coverage, have predictable income, and can afford higher annual premiums in exchange for completing premium payments within a defined period.

Who benefits most:

  • High-income professionals: Ideal for individuals who want to finish paying premiums early and enjoy retirement without ongoing expenses. Doctors, lawyers, and executives often use 10-pay or 15-pay plans for efficient wealth planning
  • Business owners: Great for entrepreneurs looking to fund policies quickly and use them as corporate assets. Paid-up policies may also support succession or shareholder protection, though tax treatment depends on Capital Dividend Account (CDA), Adjusted Cost Base (ACB), and other factors
  • Parents or grandparents: Useful for those buying policies for children or grandchildren. A 10-pay or 20-pay plan can lock in coverage early, leaving the next generation with fully paid-up lifetime protection
  • Retirement planners: Perfect for anyone aiming to eliminate financial obligations before retirement. Pay-to-65 structures align naturally with working years, ensuring a stress-free transition into retirement
  • Estate planners: Favoured by individuals building long-term legacy plans. Fully funded policies ensure guaranteed coverage and predictable estate value with no premium surprises later in life

Limited pay whole life insurance offers valuable long-term benefits, but it’s not right for everyone. Understanding its limitations helps you make an informed decision. It may not be ideal for the following reasons:

  • Higher short-term costs: Premiums are compressed into fewer years, so annual costs are higher. This can strain cash flow if income is inconsistent
  • Reduced flexibility: Once you choose a payment schedule (10-pay, 20-pay, etc.), most policies don’t allow changes. Some may offer reduced paid-up coverage or premium offsets
  • Commitment required: Missing payments during the funding period can impact cash value and performance. These plans work best for buyers with predictable income
  • Limited early liquidity: Cash value growth is modest in the first few years, especially for shorter pay periods
  • Opportunity cost: Large early premiums may reduce your ability to save elsewhere or manage debt.

How to choose the right limited pay option

Choosing the right limited pay option means matching the payment period to your budget, age, income stability, and long-term financial goals. The right choice is not only about finding the lowest annual premium; it also depends on how quickly you want to complete premium payments and how much cash flow you can comfortably commit. Consider these factors before choosing a limited-pay structure:

  • Your budget: Shorter payment periods, such as 5-pay or 10-pay, generally require higher annual premiums. Longer structures, such as 20-pay or pay-to-65, spread premiums over more years but may require payments for longer.
  • Your age and retirement timeline: If you want required premiums to end before retirement, consider whether a 10-pay, 15-pay, 20-pay, or pay-to-65 structure will finish before your target retirement age.
  • Income stability: Limited pay whole life insurance works best when you can maintain premium payments consistently during the funding period. A payment structure that is affordable in a strong income year may become difficult to sustain if income is variable.
  • Cash-value and liquidity goals: If you may need access to cash value sooner, compare the guaranteed cash-value schedule, loan provisions, and withdrawal rules. Early cash value may still be limited, particularly relative to premiums paid.
  • Estate or business-planning goals: If the policy is intended to support estate planning, succession planning, or shareholder protection, consider the ownership structure, beneficiary designation, and tax rules that apply to corporate-owned policies.
  • Participating-policy features: If you are considering a participating policy, review how dividends work, whether they are guaranteed, and how they may be used. Dividends are not guaranteed and can change over time.

If your priority is… A potentially suitable structure Why
Completing premiums as quickly as possible 5-pay or 8-pay These structures concentrate premiums into a short period, but annual premiums are usually higher
Ending premiums before retirement 10-pay, 15-pay, or 20-pay The right option depends on your current age and target retirement date
Lower annual premiums 20-pay or pay-to-65 These structures spread premiums over a longer period
Aligning payments with working years Pay-to-65 Required premiums generally continue until age 65
Balancing permanent coverage and cash flow 15-pay or 20-pay These may offer a middle ground between earlier paid-up status and more manageable annual premiums

A 35-year-old who wants required premiums to end by age 55 may consider a 20-pay policy. Someone aged 45 who wants premiums to end by age 65 may instead consider a 20-pay policy or a pay-to-65 structure, depending on their budget and coverage needs.

The appropriate option depends on more than age. Compare illustrations using the same coverage amount, health assumptions, and payment frequency, and review both the guaranteed values and any non-guaranteed dividend values.

A licensed PolicyAdvisor advisor can help you compare limited-pay options, review policy illustrations, and assess which payment period may align with your budget and long-term goals.

Schedule a call for visitor insurance

Find a plan that fits your goals.

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

What is limited pay whole life insurance?

Limited pay whole life insurance is a permanent policy where you pay premiums for a set number of years, such as  5, 10, 15, 20, or until age 65, instead of for your entire life. Once the payment term ends, the policy becomes fully paid-up, and your coverage continues for life. This structure suits Canadians who want to finish payments early while keeping lifelong protection and building guaranteed cash value.

How does limited pay whole life insurance differ from traditional whole life insurance?

The key difference between limited pay and a whole life insurance plan is how long you pay premiums. With limited pay whole life insurance, payments end after a fixed term, while traditional whole life requires ongoing payments for life. Both offer lifetime coverage and cash value, but limited pay policies cost more annually since you pay them off sooner.

What is paid-up life insurance?

Paid-up life insurance is a policy that no longer requires premium payments but continues to provide lifetime coverage. You can reach paid-up status by completing the limited pay term or electing reduced paid-up status. Some policyholders also use premium offset, where dividends or cash value cover future premiums, though the policy isn’t fully paid-up in that case. It’s a useful option for policyholders who want lifelong coverage without ongoing costs.

Can I convert my existing whole life policy into a limited pay plan?

No, most existing whole life insurance policies cannot be directly converted into limited pay plans. However, some insurers allow premium offset, where dividends cover future premiums, or policy exchanges under certain conditions. It’s best to review your policy terms or consult your advisor to confirm what’s possible with your provider.

What happens after I finish paying premiums on a limited pay plan?

Once you’ve completed your payment term, your policy becomes fully paid-up. You no longer need to make premium payments, but your coverage continues for life. You can also access your policy’s cash value through loans or partial withdrawals, depending on your insurer’s rules.

Who should consider a limited pay whole life policy?

Limited pay whole life insurance is ideal for professionals, business owners, and families who want permanent protection but prefer to pay premiums before retirement. It is also a good fit for those who want to use life insurance for estate planning or tax-efficient wealth transfer.

How can I make limited pay whole life insurance more affordable?

You can make your limited pay plan more affordable by choosing a longer pay term or improving your insurability. You can also use policy features like paid-up additions (PUAs), which let you use dividends to buy extra coverage, boosting your policy’s value without increasing out-of-pocket costs. Some policies also allow additional deposits (ADO), which do require extra payments.

What’s the difference between limited pay and paid-up additions?

Limited pay determines how long you make premium payments, whereas paid-up additions (PUAs) let you use dividends to purchase extra coverage. PUAs may accelerate when a policy reaches paid-up status, but they do not always make the base policy fully paid-up. Instead, they primarily increase your death benefit and cash value without lengthening the payment period.

Can businesses buy limited pay whole life insurance?

Yes, corporations in Canada can use limited pay whole life insurance through corporate-owned life insurance (COLI) to create a valuable corporate asset. The company pays premiums over a set term, and the policy can support buy-sell funding, executive compensation, or long-term financial planning.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Life Insurance Companies in Alberta (2026)

Alberta is one of Canada’s fastest-growing provinces with a population of over 5.1 million in 2026, making financial protection increasingly important for residents. From mortgage protection in Calgary to family income security in Edmonton, every resident has different financial obligations to protect. Based on our analysis of applicants from Alberta, Sun Life, Manulife, Canada Life, RBC Insurance, BMO Insurance and Empire Life are the six best insurers you can go with.

Life insurance can be affordable!

Get the best life insurance quotes in Canada!

What are the best life insurance companies in Alberta?

★★★★★
Families seeking comprehensive coverage READ REVIEW
★★★★★
Flexible term and permanent insurance READ REVIEW
★★★★★
Comprehensive life insurance options READ REVIEW
★★★★★
Estate planning and wealth preservation READ REVIEW
★★★★★
Flexible term life insurance READ REVIEW
★★★★★
Guaranteed permanent protection READ REVIEW

Choosing the best life insurance company in Alberta requires you to compare premiums, coverage flexibility, policy benefits, and features that align with your long-term financial goals. Below, we have shortlisted six leading insurers based on their products, pricing, and suitability for Alberta homeowners, families, and business owners.

1. Manulife: Best for families seeking comprehensive protection in Alberta

Manulife stands out for Albertan families seeking flexible coverage for multiple household members and protection against different financial risks. The insurer offers Family Term, Manulife Par and its flagship product Synergy, which combines life, critical illness and disability insurance into one comprehensive policy.

For example, 65.4% of Edmonton homeowner households had a mortgage based on a 2021 census. Manulife’s Family Term can be particularly useful for Albertan families with a mortgage and children who depend on them. Rather than purchase separate policies for each partner, eligible members can be seamlessly insured under one policy.

Manulife’s Synergy can also be an ideal choice for self-employed individuals and business owners in cities like Calgary and Edmonton who want to protect themselves from financial liability in case of a serious illness, disability, or even death. 

Our advisor’s take:

We gave Manulife 5/5 for its combination of competitive term pricing, family-oriented coverage and diverse permanent insurance options. The Family Term plan can cover multiple eligible family members under one policy, making it great for Albertans seeking a hassle-free solution. The Synergy plan also offers a wider range of coverage options for individuals who want critical illness insurance and disability insurance as well.

Manulife term life pricing

For a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term, the illustrative cost of Manulife term life insurance is $11.13 per month. This is the second-lowest quoted premium among the six insurers we compared, making it a strong choice for families seeking affordable coverage alongside value-added benefits such as Vitality and Synergy.

2. Empire Life: Best for flexible term and permanent coverage in Alberta

Empire Life is a strong choice for Alberta residents who want to start off with term life insurance while having the option to convert to permanent life insurance in the future. The insurer’s Solution series includes renewable and convertible term products, with six term lengths that let policyholders align coverage with outstanding obligations like mortgages or replacing income through key working years.

Meanwhile, the EstateMax and OptiMax policies can be used to complement long-term estate protection and cash value, respectively. This combination of term and whole life policies can appeal to Alberta families looking to initially protect temporary coverage and later switch to a permanent policy for lifelong coverage.

Our advisor’s take:

We gave Empire Life 5/5 for its competitive term insurance pricing, flexible conversion options and participating whole life plans. The Solution series is ideal for Albertans looking to start out with life insurance through term policies and eventually convert to a permanent option without additional medical underwriting. The EstateMax and Optimax Wealth are also well-suited for residents who want to make the policy a part of their financial planning or retirement strategy.

Empire Life term life pricing

For a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term, the illustrative cost of Empire Life term life insurance is $10.89 per month. This is the lowest premium among the six insurers we compared, making Empire Life particularly attractive for budget-conscious Albertans who also value flexible term lengths and conversion options for future coverage needs.

3. Sun Life: Best for comprehensive life insurance options in Alberta

Sun Life is a strong choice for Alberta residents who want the flexibility to choose between temporary protection and lifelong insurance. The insurer offers term life insurance, participating whole life insurance, and non-participating permanent life policies, making it suitable for different stages of financial planning.

According to the 2021 census, 65.2% of Calgary homeowner households had a mortgage, highlighting the importance of protecting debts. Sun Life’s Evolve Term can help these homeowners protect their mortgages and replace income during key working years, while the SunSpectrum Permanent Life II policy may suit the financial strategy of established professionals and business owners in Calgary or Lethbridge.

Our advisor’s take:

We give Sun Life a strong 4.5/5 rating for its comprehensive selection of term, participating whole life and non-participating permanent insurance plans. We particularly like the Evolve Term plan for its customizable term lengths and conversion privileges, which may appeal to Calgary or Edmonton homeowners who are looking to protect their mortgage. The Sun Par and SunSpectrum plans also offer strong options for established business owners and individuals.

Sun Life term life pricing

For a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term, the illustrative cost of Sun Life term life insurance is $13.05 per month. The insurer is worth considering for its extensive selection of term, participating whole life, and non-participating insurance plans.

4. Canada Life: Best for estate planning and wealth preservation in Alberta

Canada Life is a strong option for Albertans who want to combine flexible term coverage with long-term financial and estate planning. The insurer offers the My Term term life policy, while the whole life portfolio includes Wealth Achiever, Balanced Achiever and Estate Achiever.

The participating whole life policies by Canada Life are designed for different financial priorities that can align well with Albertans seeking lifelong protection or planning to leave a legacy. According to a recent statistic, Alberta had 137,182 small employer businesses, accounting for 98.3% of employer businesses in the province. 

Our advisor’s take:

We gave Canada Life 4.5/5 due to its strong participating whole life portfolio and flexible term insurance options. The wide range of plans, such as Wealth Achiever, Balanced Achiever and Estate Achiever, offers different benefits catering to various financial needs of Albertans. For an established business or high-net-worth individual in Calgary or Wood Buffalo, the Long-term estate protection and wealth transfer features of Estate Achiever can be a particularly good fit.

Canada Life term life pricing

For a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term, the illustrative cost of Canada Life term life insurance is $12.36 per month. While this is slightly higher than Manulife, Empire Life, and BMO Insurance, Canada Life is worth considering for its flexible My Term coverage and participating whole life plans aimed at estate planning and cash-value growth.

5. RBC Insurance: Best for flexible term life insurance in Alberta

RBC Insurance is a particularly strong option for Alberta residents who are seeking term life insurance that aligns with financial obligations such as mortgages, debts, or car loans. The insurer’s YourTerm plan allows eligible individuals to select term lengths between 10 and 40 years, making it easier to match required coverage duration.

This can be particularly useful for Edmonton residents or Calgary homeowners who want their life insurance policy to closely cover the years remaining on their mortgage or home loan. Additionally, the participating RBC Growth Insurance and RBC Growth Insurance Plus can be ideal for St. Albert or Sherwood Park residents looking for a whole life insurance policy to complement their investment strategy.

Our advisor’s take:

We gave RBC Insurance 4.5/5 for its flexible term insurance options and permanent coverage alternatives. The insurer’s standout features are the conversion and exchange privileges, which may appeal to young Albertans still figuring out their financial goals. While premiums are the highest among the other insurers, it can be well-suited for those seeking a policy that grows with their needs.

RBC Insurance term life pricing

For a 40-year-old male non-smoker seeking $100,000 in term life coverage, the illustrative cost of RBC term life insurance is $13.41 per month. Although it costs more than Empire Life, Manulife, and BMO Insurance, RBC Insurance remains a strong option for Albertan homeowners who want customizable term lengths and the flexibility to adjust coverage as financial obligations change.

6. BMO Insurance: Best for guaranteed permanent protection in Alberta

BMO Insurance is a strong choice for Alberta residents looking for permanent protection with a relatively straightforward policy structure. The insurer offers term life insurance, Term 100, and non-participating whole life insurance. The Term 100 policy offers lifelong protection with level premiums payable until age 100, making it great for individuals who want long-term protection without any cash value benefit.

For Albertans looking to complement their portfolio with cash value growth, the whole life Estate Protector and Wealth Accelerator can provide tax-advantaged estate planning and wealth transfer. BMO’s permanent insurance policies may also appeal to established business owners in Lethbridge, where small businesses accounted for 95.4% of businesses in 2025.

Our advisor’s take:

We gave BMO Insurance 4.5/5 thanks to the insurer’s competitive term pricing and strong non-participating options. The Term 100 policy is worth considering for Albertans who want lifelong coverage without cash value growth, while the non-participating policies are ideal for long-term protection for homeowners and business owners.

BMO Insurance term life pricing

The illustrative cost of BMO term life insurance for a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term is $11.16 per month. This is just slightly higher than Empire Life and Manulife, but the insurer is still worth considering thanks to its competitive pricing, term conversion privileges, and guaranteed permanent coverage options.

Comparing the top life insurance companies in Alberta

Insurer Manulife Empire Life Sun Life Canada Life RBC Insurance BMO Insurance
PolicyAdvisor rating 5/5 5/5 4.5/5 4.5/5 4.5/5 4.5/5
Cost for a 40-year-old male non-smoker ($100,000, 10-year term) $11.13/month $10.89/month $13.05/month $12.36/month $13.41/month $11.16/month
Life insurance options
  • Term
  • Participating whole life
  • Term
  • Participating whole life
  • Term
  • Participating whole life
  • Non-participating permanent
  • Term
  • Participating whole life
  • Term
  • Participating whole life
  • Term
  • Term 100
  • Non-participating whole life
Policy features and flexibility
  • Family Term
  • Multiple insureds
  • Renewal and conversion privileges
  • Solution Series (10, 15, 20, 25, 30 years and ART)
  • Conversion options
  • Evolve Term (5–40 years)
  • Conversion privileges
  • Multiple permanent options
  • My Term (5–50 years)
  • Conversion privileges
  • Three participating whole life plans
  • YourTerm (10–40 years)
  • Customizable terms
  • Exchange and conversion privileges
  • Term (10–30 years)
  • Renewability
  • Conversion and exchange privileges
Standout feature
  • Synergy combination protection
  • Vitality wellness rewards
  • Competitive sample pricing
  • Term-to-permanent flexibility
  • Comprehensive permanent insurance lineup
  • Wealth Achiever
  • Balanced Achiever
  • Estate Achiever
  • Flexible term lengths in one-year increments
  • Performance Bonus
  • Guaranteed whole life cash values
LICAT ratio (Q2 2026) 136% 159% 133% 128% 134% 132%
AM Best financial strength rating A+ Not currently rated A+ A+ A A
Best for Families and multiple coverage needs Affordable term and permanent flexibility Comprehensive life insurance options Estate planning and wealth preservation Flexible term life insurance Guaranteed permanent protection

 Actual premiums vary by age, sex, smoking status, health, coverage amount, product, and underwriting. Minimum coverage varies by product and eligibility. 

How we selected the best life insurance companies in Alberta

Our 2026 ranking of the best life insurance companies in Alberta is based on illustrative term life insurance quotes and factors such as term and permanent options, coverage flexibility, conversion privilege, underwriting requirements, and additional policy benefits. We compared 30+ leading Canadian insurers and shortlisted these six: Sun Life, Manulife, Canada Life, RBC Insurance, BMO Insurance and Empire Life.

Our methodology gives 40% weight to pricing and 60% to product features and suitability, considering the importance of choosing coverage based on long-term financial needs rather than just the cheapest option.

1. Pricing competitiveness (40%)

Our advisors compared sample term life insurance premiums for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term across all six insurers. Using the same applicant profile helped us understand the difference in premiums across different insurance companies. The quoted monthly premiums range from $10.89 for Empire Life to $13.41 for RBC Insurance.

Insurer name Male (non-smoker)
Manulife $11.13/month
Empire Life $10.89/month
Sun Life $13.05/month
Canada Life $12.36/month
RBC Insurance $13.41/month
BMO Insurance $11.16/month

Term life insurance cost in Alberta

Term premiums are illustrative monthly costs for a 40-year-old non-smoker male seeking $100,000 of coverage for a 10-year term. Actual premiums vary by age, sex, health, smoking status, product, coverage amount, and underwriting. All premiums listed on Y-azix are in CAD (CA$).

2. Product features and suitability (60%)

In terms of product features and suitability, we assessed the following important factors:

  • Product range and coverage options (15%): We compared the availability of term life, participating whole life, non-participating and other plans
  • Coverage flexibility (15%): Coverage limits, customizable term lengths, premium payment options and renewability
  • Underwriting and accessibility (10%): Underwriting requirements, eligibility criteria and options for a wide range of health or occupational profiles
  • Conversion privileges and riders (5%): Term-to-permanent conversion options, exchange privileges, children’s coverage and other additional benefits
  • Permanent Policy benefits (5%): We assessed important features such as guaranteed cash value, participating dividends, as well as benefits for estate planning and tax-advantaged wealth transfer
  • LICAT ratio (5%): We reviewed each insurer’s Life Insurance Capital Adequacy Test (LICAT) ratio as an indicator of regulatory capital adequacy
  • AM Best rating (5%): We considered available AM Best financial strength ratings to assess insurers’ ability to meet their ongoing insurance obligations

How we assigned insurer ratings:

The five-point rating system considered each insurer’s strengths and weaknesses in different areas. For example, Manulife and Empire Life received a 5/5 rating thanks to their combination of competitive premiums, coverage flexibility, and range of permanent life insurance policies. Meanwhile, insurers like Sun Life and RBC received 4.5/5 based on their product’s alignment with the needs of Albertans.

In addition, we consider how these features can address common financial obligations among Alberta homeowners, families and business owners. Our recommendations reflect overall product suitability rather than the insurer with the lowest premiums or most favourable underwriting outcome. PolicyAdvisor’s licensed advisors are salaried and do not earn commissions, ensuring that our recommendations focus on your coverage needs, financial goals, and best interests rather than financial incentives.

Disclaimer: The premium comparison represents one applicant profile and one term policy configuration. It does not establish which insurer is cheapest for every age, health category, coverage amount, or policy type. Empire Life’s AM Best rating was withdrawn at its request in 2021; being unrated does not indicate poor financial strength. The final rating excludes the unavailable AM Best component and is calculated using the remaining weighted criteria.

After shortlisting the six strongest companies, we ranked each insurer individually using the same weighted criteria to show where one company may be stronger than another.

Pricing competitiveness40%
Product range and coverage options15%
Coverage flexibility15%
Underwriting and accessibility10%
Conversion privileges and riders5%
LICAT Ratio5%
AM Best Rating5%

Comparing PolicyAdvisor ratings:

Insurer Pricing (40%) Product range (15%) Coverage flexibility (15%) Underwriting

(10%)

Conversion

and

riders (5%)

Permanent benefits (5%) LICAT (5%) AM Best (5%) Final rating
Sun Life 4/5 5/5 5/5 4/5 4.5/5 5/5 4/5 5/5 4.5/5
Manulife 5/5 5/5 4.5/5 4.5/5 5/5 5/5 4.5/5 5/5 5/5
Canada Life 4.5/5 5/5 5/5 4/5 4.5/5 5/5 4/5 5/5 4.5/5
RBC Insurance 4/5 4.5/5 5/5 4/5 5/5 4.5/5 4.5/5 4.5/5 4.5/5
BMO Insurance 5/5 4/5 4.5/5 4/5 4.5/5 4.5/5 4.5/5 4.5/5 4.5/5
Empire Life 5/5 4.5/5 5/5 4/5 5/5 5/5 5/5 N/A 5/5

Disclaimer:  PolicyAdvisor’s ratings are based on our comparative evaluation of insurer premiums, coverage options, policy flexibility, unique benefits, and financial strength. Individual scores reflect our assessment and may not apply equally to every applicant. Quoted premiums are illustrative and depend on factors such as age, health, smoking status, coverage amount, and policy terms. LICAT ratios and AM Best ratings may change over time and are based on the relevant reporting periods and insurance entities. Final scores are rounded to the nearest 0.5 and do not guarantee an insurer’s performance or suitability for individual coverage needs.

Cost of life Insurance in Alberta

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

How to choose the best life insurance company in Alberta

The best life insurance company should provide the required coverage at an affordable premium, while offering flexibility and benefits that can suit your financial requirements. 

Here are some important factors to keep in mind when choosing the best life insurance company in Alberta:

  • Compare premiums across insurers: The cost of life insurance varies by insurer, even for applicants with the same profile. Our advisors can help you choose coverage from leading Canadian insurers to find a plan that suits your needs
  • Look for coverage and term flexibility: If you are protecting an outstanding debt or obligation, it is important to find an insurer that offers a term which aligns with your needs. For example, RBC’s 10- to 40-year durations with one-year increments can be better for a family with 13 years left on their mortgage
  • Check conversion and exchange privileges: A conversion privilege can allow you to change eligible term coverage into a permanent policy without new evidence of insurability. This is ideal if your priorities change in the future or you wish to have lifelong coverage
  • Consider financial strength: For permanent policies, it is essential to compare cash values, premium payment periods, dividend options, and the insurer’s financial strength. This can help you choose a policy with the best financial benefits.

Does life insurance cost more in different Alberta cities?

Life insurance premiums in Alberta generally do not differ simply because you live in Calgary, Edmonton, Red Deer, Lethbridge, or another city. Unlike home or auto insurance in Canada, life insurance premiums primarily depend on individual factors such as age, health, smoking status, coverage amount, and other underwriting criteria.

How to purchase life insurance in Alberta?

PolicyAdvisor’s licensed life insurance advisors can help Alberta residents compare term and whole life insurance policies from 30+ Canadian insurers based on their age, budget, health, coverage needs, and long-term financial goals.

Whether you are protecting a mortgage in Calgary, securing your family’s future in Edmonton, or planning for long-term wealth transfer in Red Deer, Lethbridge, Fort McMurray, Medicine Hat, or Grande Prairie, our advisors can help you find suitable coverage. 

Our team at PolicyAdvisor also assists residents in Airdrie, Cochrane, Okotoks, Chestermere, St. Albert, Sherwood Park, Spruce Grove, Leduc, Beaumont, Camrose, Lloydminster, Canmore, Banff, Brooks, Wetaskiwin, and other Alberta communities in comparing insurers, premiums, and policy options to find the right life insurance for their needs.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently Asked Questions

What is the best life insurance company in Alberta?

The best life insurance company in Alberta depends on factors such as your coverage needs, financial priorities, and your health. Based on our experience assisting residents of Alberta, Sun Life, Manulife, Canada Life, RBC Insurance, BMO Insurance and Empire Life are six companies worth considering in 2026.

Is life insurance more expensive in Alberta than in other provinces?

No, life insurance is not necessarily more expensive in Alberta than in other provinces. However, your premiums can change based on personal factors such as occupation, lifestyle and other underwriting information.

What is the best life insurance for first-time homebuyers in Alberta?

Term life insurance is often a suitable option for first-time homebuyers since it can provide substantial coverage during the years when mortgage obligations are highest. As a new homeowner in Calgary, Lethbridge, or Edmonton, RBC YourTerm, Canada Life My Term and Sun Life Evolve Term are worth comparing due to their flexible term options.

Can I get life insurance in Alberta without a medical exam?

Yes, some insurers offer no-medical-exam or simplified issue life insurance to eligible Alberta residents. These policies typically have lower coverage amounts and higher restrictions than traditionally underwritten life insurance policies in Canada.

Is my life insurance death benefit taxable in Alberta?

Life insurance death benefits are typically not taxable in Alberta. However, the payout may be taxable if it is paid to an estate instead of the beneficiary or is part of a related investment income. Alberta residents should carefully review their beneficiary designations and consult a qualified tax advisor to determine their taxability.

How can I compare life insurance quotes in Calgary or Edmonton?

Our licensed advisors at PolicyAdvisor can help Calgary and Edmonton residents compare quotes from leading Canadian life insurance companies through easy-to-use online tools that can help them find the right life insurance coverage.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Life Insurance for Young Adults in Canada (2026)

As a young adult in your 20s and 30s, life insurance may not be the first financial product you think about. However, major obligations like buying a home, getting married, starting a family, or taking on shared debt can quickly create a need for coverage to protect your beneficiaries in case you pass away unexpectedly.

For many young adults in Canada, term life insurance can be a practical starting point since it covers you for a set period and generally costs less than permanent life insurance. However, the right plan depends on your financial priorities, debts, and your budget.

Quick view:

  • Empire Life (5/5): Best for adaptable long-term coverage
  • Equitable Life (5/5): Best for conversion and hybrid coverage
  • RBC Insurance (4.5/5): Best for customizable high coverage
  • Manulife (4.5/5): Best for wellness rewards and growing family needs
  • Desjardins (4.5/5): Best for life plus critical illness
  • Canada Life (4.5/5): Best for flexible term lengths
Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Top 6 best life insurance companies for young adults in Canada

★★★★★
Best for adaptable long-term coverage READ REVIEW
★★★★★
Best for conversion and hybrid coverage READ REVIEW
★★★★★
Best for customizable high coverage READ REVIEW
★★★★★
Best for wellness rewards and growing family needs READ REVIEW
★★★★★
Best for life plus critical illness coverage READ REVIEW
★★★★★
Best for flexible term lengths READ REVIEW

While many insurers offer great benefits, companies such as Empire Life, Canada Life, and RBC Insurance offer greater flexibility, built-in benefits, and features that make them particularly suitable for individuals in their 20s and 30s embarking on their financial planning.

Here’s an overview of the six best life insurance companies for young adults in Canada:

1. Empire Life

Empire Life offers a lot of flexibility for young adults whose insurance needs can change as they take on responsibilities like buying a home, starting a family, or building their careers. If you are unsure of what your financial responsibilities will look like in five or ten years, the policy’s flexibility can come in handy. The Solution Series offers terms from 10 to 30 years, and eligible 10,15, 20, and ART policies can be exchanged for longer terms (within the first seven policy years) in case you undertake responsibilities like a mortgage or a loan.

The insurer also offers a carry-over term feature when eligible term coverage is converted to permanent insurance, allowing temporary coverage to continue alongside the new permanent policy. In terms of permanent coverage, EstateMax and OptiMax Wealth can offer long-term estate benefits and better cash-value growth, respectively, making these options suitable for those seeking lifelong protection. These features can make Empire Life one of the best term life insurance policies for young adults in Canada

Empire Life term life pricing

The illustrative cost of Empire Life term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $9.45/month, increasing to $9.90/month at age 30.

Empire Life whole life pricing

The illustrative cost of Empire Life whole life insurance for a 20-year-old male seeking $100,000 in coverage with a 20-pay option is approximately $138.42/month, increasing to $221.94/month at age 30.

  • Best for: Young adults looking for highly customizable coverage that can adapt as their needs change
  • Plans: Solution 10, Solution 15, Solution 20, Solution 25, Solution 30, Solution ART, EstateMax, OptiMax Wealth
  • Minimum term coverage: $25,000
  • Minimum whole life coverage: $25,000
  • Policy types: Term life and participating whole life
  • Term lengths: ART, 10, 15, 20, 25, and 30 years
  • Standout feature: Solution ART, 10, 15, and 20 policies can be exchanged for longer terms within the first seven policy years, providing additional flexibility as financial responsibilities or income grow

2. Equitable Life

Equitable Life also offers plans tailored to young adults in their 20s and 30s embarking on their financial journey. Its term life offers Term 10, Term 20, and Term 30/65, with guaranteed renewability and conversion to permanent insurance that can help policyholders retain coverage if their needs or health change later.

The optional child rider in the Equimax plans can cover eligible existing and future children, and they may later purchase coverage for an individual policy between ages 21 and 25 for up to five times the rider amount without new medical underwriting. This makes it a strong fit if you are looking to start a family and protect your children’s interests down the road.

Equitable’s Equimax also lets eligible policyholders combine permanent insurance with substantial term riders, helping policyholders avoid purchasing permanent coverage to protect temporary needs. This hybridity makes it easier to have a comprehensive coverage strategy. For those seeking whole life coverage, the Equimax Wealth Accumulator and Equimax Estate Builder can help with earlier cash value accumulation within 20 years and long-term estate planning, respectively.

Equitable Life term life pricing

The illustrative cost of Equitable Life term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $9.45/month, increasing to $9.74/month at age 30

Equitable Life whole life pricing

The illustrative cost of Equitable Life whole life insurance for a 20-year-old male seeking $100,000 in coverage with a 20-pay option is approximately $176.35/month, increasing to $215.62/month at age 30

  • Best for: Young adults with growing families looking for adaptable coverage
  • Plans: Term 10, Term 20, Term 30/65, Equimax Wealth Accumulator, Equimax Estate Builder
  • Minimum term coverage: $50,000
  • Minimum whole life coverage: $10,000
  • Policy types: Term life and participating whole life
  • Term lengths: 10 years, 20 years, and Term 30/65
  • Standout feature: Equitable offers both flexible term coverage with guaranteed renewability and two distinct participating whole life options focused on either earlier cash-value growth or long-term estate value

3. RBC Insurance

RBC Insurance works well for young adults in their 20s and 30s who want a large amount of term coverage with enough customization options. The YourTerm plan lets applicants choose coverage of up to $25 million for 10 to 40 years in one-year increments, making it easier to match coverage with a mortgage, income-replacement period, or other long-term financial obligation.

Eligible Term 10 policies can also be exchanged for longer coverage without new medical underwriting, making it ideal for young Canadians who have undertaken new responsibilities like starting a family or buying a new house. The ability to convert part of the term policy into permanent also makes it suitable for lifelong protection if you wish to protect your dependents. The optional child rider also strengthens the policy’s value if you are about to start a new family or have a child.

If you are looking for lifelong protection for you and your loved ones, the RBC whole life insurance Growth Insurance plan is designed for long-term cash accumulation, while the Growth Insurance Plus is aimed at earlier cash value growth.

RBC Insurance term life pricing

The illustrative cost of RBC term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.98/month, increasing to $11.25/month at age 30

RBC Insurance whole life pricing

The illustrative cost of RBC whole life insurance for a 20-year-old male seeking $100,000 in coverage with a 20-pay option is approximately $198.54/month, increasing to $236.41/month at age 30.

  • Best for: Young professionals seeking high coverage limits and customizable term lengths
  • Minimum term coverage: $100,000 
  • Minimum whole life coverage: $25,000 
  • Plans: YourTerm, RBC Growth Insurance, RBC Growth Insurance Plus
  • Policy types: Term life and participating whole life
  • Maximum coverage: Up to $25 million through eligible term coverage
  • Term lengths: 10 to 40 years in one-year increments
  • Standout feature: YourTerm combines high coverage limits with highly customizable term lengths, term exchange options, and permanent conversion flexibility

4. Manulife

Manulife is a strong option for young adults in Canada who expect their life insurance needs to grow as their income and family responsibilities grow. The Family Term lineup includes multiple term options, including Term 10, Term 20, and Term to Age 65. Eligible policies can be converted to permanent coverage without new proof of insurability, making it ideal for long-term planning. The optional Guaranteed Insurability Option makes it easier for you to purchase additional coverage to meet new financial demands without requiring new underwriting.

In addition, Manulife’s Vitality Plus plan is well-suited for young adults and their dynamic lifestyle. Eligible family term policies can receive up to 15% in savings through health and wellness activities, promoting good health and offering savings on multiple partner brands.

In terms of permanent coverage, Manulife Par offers limited-pay options, allowing you to finish paying premiums early and enjoy lifelong coverage. These policies can also be paired with a term rider to protect temporary needs and debts, instead of purchasing a separate policy. The child protection and guaranteed insurability options make it a solid choice for new families looking for comprehensive long-term coverage.

Manulife term life pricing

The illustrative cost of Manulife term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $9.47/month, increasing to $9.70/month at age 30.

Manulife whole life pricing

The illustrative cost of Manulife non-participating whole life insurance for a 20-year-old male seeking $100,000 in coverage is approximately $246.20/month, increasing to $291.59/month at age 30.

  • Best for: Wellness rewards and growing family needs
  • Plans: Family Term, Family Term with Vitality Plus, Manulife Par
  • Minimum term coverage: $100,000
  • Minimum whole life coverage: $100,000
  • Policy types: Term life and participating whole life
  • Coverage: Up to $20 million with standard Family Term and up to $25 million with Family Term with Vitality Plus
  • Standout feature: Vitality Plus can provide eligible policyholders with premium savings of up to 15%, while Guaranteed Insurability and child-protection options help coverage adapt as family needs grow

5. Desjardins

Desjardins is another strong contender for young adults in Canada who want to build broader protection rather than just purchasing a life insurance policy. The term life lineup offers 10- to 30-year terms, alongside a Term to 65 option, which can make it easy for young homeowners to match coverage with their mortgage or align with a loan. 

These plans have fixed premiums and a conversion privilege to permanent insurance before age 70, allowing applicants to switch to whole life if their financial goals change down the line. Meanwhile, the permanent lineup includes 5-Pay PAR, Estate Enhancer, and Accelerated Growth, offering benefits ranging from earlier cash-value access to long-term estate priorities. 

Young adults in Canada can also pair their Desjardins life insurance plan with Health Priorities critical illness coverage, which covers 26 illnesses and health conditions, offering a more comprehensive protection solution.

Desjardins term life pricing

The illustrative cost of Desjardins term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.44/month, increasing to $10.89/month at age 30.

Desjardins whole life pricing

The illustrative cost of Desjardins whole life insurance for a 20-year-old male seeking $100,000 in coverage with a 20-pay option is approximately $78.21, increasing to $105.66 per month at age 30.

  • Best for: Young adults looking to combine life insurance with broader health protection
  • Plans: Term 10, 15, 20, 25, 30, Term to 65, 5-Pay PAR, Estate Enhancer, Accelerated Growth
  • Minimum term coverage: $25,000
  • Minimum whole life coverage: $10,000
  • Policy types: Term life and participating whole life
  • Term lengths: 10, 15, 20, 25, 30, and Term to 65
  • Standout feature: Desjardins combines a broad term and permanent lineup with the option to add Health Priorities critical illness coverage
  • Critical illness option: Health Priorities provides benefits for 26 covered critical illnesses and health conditions

6. Canada life

Canada Life is an ideal choice for young adults in Canada seeking coverage which evolves with their financial responsibilities. My Term offers customizable terms from 5 to 50 years, allowing applicants to align protection with outstanding debts or mortgages. The optional Guaranteed Insurability Rider can allow eligible policyholders to purchase a new permanent policy without any proof of insurability, making it great for future-proofing your protection.

Depending on eligibility, each option amount is subject to a $25,000 minimum and a maximum equal to the lesser of twice the base coverage or $300,000, making it valuable for young adults as their financial responsibilities and priorities change down the line. For individuals seeking lifelong coverage and cash value growth, the Wealth Achiever provides early cash values, while Estate Achiever and Balanced Achiever can aid in long-term estate planning.

Canada Life term life pricing

The illustrative cost of Canada Life term life insurance for a 20-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $10.53/month, increasing to $10.80/month at age 30.

Canada Life whole life pricing

The illustrative cost of Canada Life whole life insurance for a 20-year-old male seeking $100,000 in coverage with a 20-pay option is approximately $406.35/month, increasing to $487.89/month at age 30.

  • Best for: Young adults looking for future coverage increases as needs grow
  • Plans: My Term, Wealth Achiever, Estate Achiever, Balanced Achiever
  • Minimum term coverage: $100,000 
  • Minimum whole life coverage: $25,000 
  • Policy types: Term life and participating whole life
  • Term lengths: 5 to 50 years through My Term
  • Standout feature: My Term allows applicants to select highly customizable coverage periods instead of being limited to standard 10-, 20-, or 30-year terms

Comparison of the six best life insurance companies for young adults in Canada

Insurer Monthly term premiums Minimum coverage Future policy flexibility Term flexibility Family/life-stage benefits
Empire Life $7.74–$9.90
  • Term $25K
  • Whole $25K
  • Term exchange
  • Carry-over term after eligible conversion
ART, 10, 15, 20, 25, 30 Optional critical illness integration
Equitable Life $7.73–$9.74
  • Term $50K
  • Whole $10K
Term exchange and conversion on eligible coverage 10, 20, 30/65
  • Equimax child rider
  • Future conversion options
RBC Insurance $8.91–$11.25
  • Term: $100K
  • Whole $25K
  • Eligible term exchange
  • Partial and permanent conversion
10–40 years in one-year increments Child rider
Manulife $7.71–$9.70
  • Term:$100K
  • Whole:$100K
  • Guaranteed Insurability Option
  • Term to permanent conversion
10, 20, to age 65 plus eligible options
  • Child protection Benefit
  • Vitality Plus offers up to 15% savings
Desjardins $8.55–$10.89 Term $25K

Whole $10K

Eligible permanent conversion 10, 15, 20, 25, 30, to 65 Health Priorities Critical Illness add-on with 26 covered conditions
Canada Life $8.55–$10.80 Term $100K

Whole $25K

  • Guaranteed Insurability Rider
  • Term-to-permanent conversion
5–50 years
  • Child’s term life insurance rider
  • Future insurability

Sample premiums reflect the 2026 young-adult quote for $100,000 in term coverage for a 10-year term. Actual premiums vary by age, sex, smoking status, health, coverage amount, product, and underwriting. Minimum coverage varies by product and eligibility. 

How we chose the best life insurance companies for young adults in Canada

At PolicyAdvisor, our advisors reviewed more than 30 Canadian life insurance companies and shortlisted the six that stood out most for young adults. We looked at whether each insurer offered competitive pricing and accessible entry-level coverage, since many young adults in their 20s and 30s are still building their careers, managing new expenses, or purchasing their first life insurance policy.

Next, we considered whether the plans offered features that can remain useful and support long-term planning for young adults in Canada as their financial responsibilities and income grow. This included flexible term lengths, term exchange and conversion options, guaranteed insurability, child and family benefits, coverage increases, and permanent insurance options.

After shortlisting the six strongest companies, we ranked each insurer individually using the same weighted criteria to show where one company may be stronger than another.

Pricing and entry-level affordability30%
Future policy flexibility25%
Term and coverage flexibility20%
Family and life-stage benefits15%
Permanent and hybrid options10%

Rating factor Weight What we considered
Pricing and entry-level affordability 30% Sample premiums for young adults and minimum coverage amounts for applicants starting with smaller budgets
Future policy flexibility 25% Guaranteed insurability, coverage increases, term exchange, conversion, partial conversion, and other options to adapt coverage later
Term and coverage flexibility 20% Available term lengths, customization, coverage limits, and ability to match insurance to mortgages or income-replacement needs
Family and life-stage benefits 15% Child riders, future family coverage, critical illness integration, wellness benefits, and other features that become useful as responsibilities grow
Permanent and hybrid options 10% Whole life options and the ability to combine temporary term protection with permanent coverage

After selecting the six insurers, we scored each company out of 5, using the same weighted factors. A 5/5 insurer performs especially well across both pricing and policy flexibility, while a 4.5/5 insurer remains a strong option but may have higher sample premiums, fewer term choices, or fewer standout features. The underlying weighted result was then rounded to the nearest 0.5 for the displayed overall rating.

PolicyAdvisor ratings for the six best life insurance companies for young adults in Canada

Insurer Pricing 30% Future adaptability 25% Term flexibility 20% Family/life-stage 15% Permanent/

hybrid 10%

Final rating
Empire Life 5/5 5/5 4.5/5 4.5/5 4.5/5 5/5
Equitable Life 5/5 5/5 4/5 5/5 5/5 5/5
RBC Insurance 4/5 5/5 5/5 5/5 4.5/5 4.5/5
Manulife 4/5 5/5 4.5/5 5/5 5/5 4.5/5
Desjardins 5/5 4.5/5 4.5/5 5/5 4.5/5 4.5/5
Canada Life 3.5/5 5/5 5/5 5/5 4.5/5 4.5/5

Ratings are based on PolicyAdvisor’s weighted methodology and illustrative 2026 pricing. Actual premiums, eligibility, and product features vary by applicant and policy. Rankings are for comparison purposes and do not indicate the best or cheapest insurer for every individual. Pricing scores consider the illustrative term and permanent premiums together with minimum available coverage amounts. The score is not based on term premiums alone.

Why do young adults need life insurance in Canada?

Young adults in Canada may need life insurance if they have significant financial obligations or if they want to protect their beneficiaries from outstanding debts like mortgages or home loans. Major life events like marriage, buying a home, having children, or starting a business can prompt you to purchase coverage in your 20s or 30s.

Here are situations where life insurance may make sense for a young adult:

  • Your spouse or partner relies on your income
  • You have children or are starting a family
  • You have a mortgage with a spouse or partner
  • You financially support parents or other family members
  • You own a business
  • You want protection for a financial commitment that will last several years
  • You want to secure coverage earlier while your age and health are more favourable

Types of life insurance available for young adults in Canada

Young adults in Canada can choose between temporary and permanent life insurance. For many young adults in their 20s and 30s in Canada, term life insurance is usually the best starting point since it offers affordable coverage for temporary needs such as mortgages, income replacement, or other debts.

Here’s an overview of the types of life insurance available for young adults in Canada:

Term life insurance

Term life insurance provides coverage for a specific period, typically 10, 20, 25, or 30 years. You pay premiums during this period to keep the policy in force, and the insurer pays a death benefit if you pass away during that time.

Whole life insurance

Whole life insurance is a form of permanent insurance designed to remain in force throughout your lifetime as long as premiums are paid and policy requirements are met. These policies include a cash value component, which grows over the years. Participating whole life policies may pay non-guaranteed dividends, which can increase cash value or death benefit over time.

Blue bulb

Life Insurance Tip

Term life insurance offers young adults affordable coverage without the higher premiums of whole life insurance.

Should young adults in Canada choose term or whole life insurance?

For many young adults in Canada, term life insurance is the more practical starting point when the primary goal is to protect temporary financial responsibilities, such as a mortgage, income replacement, or other debts. Whole Life insurance may make sense only if you have specific lifelong needs, such as providing for your partner or estate planning and tax-advantaged wealth transfer. 

When is term life insurance better for young adults?

Term life insurance usually makes the most sense when your insurance needs are expected to decline or disappear after a specific number of years. It is aimed at covering temporary obligations, such as a mortgage, income replacement, or raising children. It can also suit young Canadians early in their careers who need a larger death benefit on a limited budget or expect their coverage needs to decline over time.

When can whole life insurance make sense for young adults?

Whole life insurance can make sense when the financial need is expected to last for life, such as supporting a lifelong dependant, planning for business succession, or leaving an inheritance. It is meant for Canadians seeking coverage throughout their lives or for individuals who wish to use it as part of a tax-advantaged estate or wealth-transfer strategy.

How much life insurance coverage do young adults need?

For many Canadians, a general rule of thumb is to purchase life insurance that is equal to about five to 10 times your annual income. However, this is just a baseline and should be adjusted based on your financial situation, debts, and other factors.

Here are certain things to keep in mind before you decide how much life insurance coverage you need:

  • Mortgage balance
  • Other debts
  • Income replacement
  • Child-care requirements
  • Existing savings and investments
  • Existing workplace or personal life insurance

Still confused? Use our life insurance calculator to estimate how much coverage you need.

Do I need life insurance as a young adult in Canada if I already have coverage through work?

Yes, you may need life insurance even if you have coverage through an employer-sponsored group plan. These policies typically provide limited coverage and end if you change employers, leaving you without coverage if you change jobs. An individual insurance policy is tied to you, allowing you to customize benefits and riders to fit your financial needs. However, it is also worth noting that some plans may provide a limited conversion option.

Do young adults need life insurance for student loans?

Whether student debt requires protection depends on the type of loan and how it was taken. Under the Canada Student Financial Assistance Act, a borrower’s obligations for eligible federal student loans terminate if the borrower dies. A family member or estate representative can contact the National Student Loans Service Centre after the student passes away.

However, this is different for private student lines of credit, where the borrower may need a parent or another person to co-sign the line of credit. In this case, a young adult student or researcher may consider a life insurance policy to help cover the financial burden if they pass away unexpectedly.

Life insurance for young adults in Canada by life stage

Life insurance priorities for young adults in Canada change with financial responsibilities: students may focus on co-signed debt and final expenses, homeowners on mortgage protection, parents on income replacement and childcare, and business owners on debt protection and succession planning.

Here’s how life insurance priorities for young adults change by life stage in Canada:

Life stage Potential life insurance priority Coverage to consider
Student or recent graduate
  • Co-signed private debt
  • Financial support for family
  • Final expenses
  • A smaller term policy can cover temporary debts or other financial obligations
  • Permanent coverage is generally less relevant unless there is a specific lifelong need
Single professional
  • Mortgage
  • Support for parents
  • Business obligations
  • Structure term life coverage around the length of major debts 
  • Permanent insurance may be considered for lifelong estate or business needs
Newly married or common-law
  • Shared income
  • Debts
  • Household expenses
  • Separate term policies for each partner
  • Permanent insurance may be added if either partner has a lifelong coverage need
First-time homeowner
  • Mortgage
  • Co-borrower protection
Term life insurance matched to the mortgage timeline
New parent
  • Income replacement
  • Childcare
  • Mortgage
  • Future education expenses
  • Structure the policy to protect the family through the years children are financially dependent
  • Convertible term coverage can provide the option to move to permanent insurance later
Self-employed professional
  • Family income
  • Debts 
  • Financial obligations without employer coverage
  • Individual term life insurance for income replacement and temporary personal debts
  • Permanent insurance may be considered for longer-term estate or business-planning needs
Business owner
  • Family protection,
  • Business debts
  • Succession or ownership obligations
  • Combination of term and permanent insurance
  • Term coverage can protect temporary loans or income needs
  • Permanent coverage may be appropriate for long-term objectives

How much does life insurance cost for young adults in Canada?

The cost of a life insurance policy  for young adults in their 20s and 30s ranges from $7.71 to $487.89. Premiums depend on the plans chosen and the coverage, as well as personal factors such as age, smoking status, and health.

Here’s an overview of term life and whole life prices for young adults in Canada:

Insurer Term life monthly cost Whole life monthly cost
Canada Life $8.55–$10.80 $378.90–$487.89
RBC Insurance $8.91–$11.25 $184.04–$236.41
Empire Life $7.74–$9.90 $118.89–$221.94
Desjardins $8.55–$10.89 $78.21–$105.66
Equitable Life $7.73–$9.74 $162.48–$215.62
Manulife $7.71–$9.70 $226.04–$291.59

Term Life cost for Young Adults by age

Whole Life cost for Young Adults by age

Term premiums are illustrative monthly costs for male and female non-smokers ages 20 and 30 seeking $100,000 of coverage for a 10-year term. Whole life premiums are illustrative monthly costs for $100,000 of coverage for a 20-pay policy. Actual premiums vary by age, sex, health, smoking status, product, coverage amount, and underwriting. All premiums listed are in CAD (CA$).

Cost of life Insurance for young adults in Canada

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

What mistakes should young adults avoid when buying life insurance?

As a young adult in Canada, you can often unlock affordable life insurance thanks to your age and health. However, choosing a policy based on premiums or purchasing too little coverage can result in insufficient protection for your beneficiaries if you pass away unexpectedly.

Here are some common mistakes to avoid when buying life insurance as a young adult in Canada:

  • Purchasing based on the lowest premium: The cheapest term 10 policy may not be the best choice if you need protection for longer periods or if you are missing out on important benefits or riders
  • Buying too little coverage: A low premium is not useful if the death benefit would leave your family unable to manage outstanding financial obligations. If budget is limited, term coverage may allow you to prioritize a higher death benefit for temporary needs. 
  • Choosing the wrong term: You should match your term to the duration of the financial obligation you are protecting to ensure that there is no financial burden on your beneficiaries
  • Waiting too long: Applying earlier can help because age and current health are major underwriting factors. If your health changes later, the same coverage may cost more or require exclusions
  • Ignoring conversion and renewability options: Conversion can become valuable if you wish to change all or part of your coverage for lifetime protection. Guaranteed renewability can be equally helpful if you develop health conditions in the future
  • Relying entirely on workplace coverage: Employer-sponsored group coverage may end when you leave your job and may not sufficiently cover your actual financial needs. However, some plans may offer limited conversion options.
  • Purchasing permanent coverage without a clear purpose: Lifetime coverage should have a clear financial purpose. If your needs are temporary, it is better to use that premium to purchase a larger term policy
  • Not reviewing the policy after life changes: It is recommended to review your policy or purchase additional coverage after major life events like marriage, children, or purchasing a new home.

Our advisor’s take on the best life insurance for young adults in Canada

At PolicyAdvisor, we recently helped a 28-year-old employed individual who just purchased a home with his partner and wanted enough coverage to protect the mortgage and replace income if he passed away. 

He wanted $1 million of coverage to help protect the mortgage and replace income, but he also expected his needs to change as he started a family. Since he expected to start a family in the next few years, he was also looking for a policy that could provide long-term protection without having to commit to the higher premiums of a whole life policy. 

We compared insurers based on premium, term length, conversion options, and the ability to extend coverage later. Empire Life’s Solution Series stood out since it offered him several term choices today while retaining the ability to restructure his coverage as his mortgage and family responsibilities changed.

Client profile

  • Age: 28
  • Occupation: Full-time professional
  • Family: Common-law partner, planning to have children
  • Primary concern: Mortgage protection and income replacement
  • Coverage goal: $1 million of life insurance
  • Additional priority: Flexible coverage that could adapt as the family and financial needs change

Why we recommended Empire Life’s Solution Series

  • Term matched to his current needs: Solution 10, 15, 20, 25, and 30 gave him several options for aligning coverage with his mortgage and key income-earning years
  • Term exchange flexibility: During the first seven years, he can exchange eligible terms for a longer term without a medical exam, giving him the flexibility to extend his coverage
  • Permanent conversion option: If some of his insurance needs become permanent, he can convert eligible term coverage to permanent life insurance, helping him maintain protection without providing new medical evidence
  • Carry-over term coverage: The carry-over term coverage lets him maintain the remaining portion of his term coverage as a rider on the new policy without medical evidence, helping him retain temporary protection alongside permanent coverage
  • Option to combine additional protection: He can also enhance term life coverage with optional critical illness coverage for himself and his partner under one plan with a single policy fee, making it easier to manage.
Quotes Icon Author Photo
Jason Goveas
Life insurance advisor
We recommended Empire Life’s Solution Series for its flexible term lengths, exchange and permanent conversion options, allowing him to adapt coverage as his mortgage and family needs change.

How to purchase life insurance for young adults in Canada

PolicyAdvisor’s licensed life insurance advisors can help young adults compare quotes from leading Canadian insurers based on age, health, smoking status, coverage requirements, term length, and budget.

Whether you are buying your first home, starting a family, or reviewing existing coverage, our licensed advisors at PolicyAdvisor can help you find coverage that fits your current and future financial responsibilities.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently Asked Questions

What is the best life insurance for young adults in Canada?

For many young adults in Canada, a term life insurance policy is recommended since it offers affordable coverage for a set period and can protect against temporary needs such as a mortgage, income replacement, or raising children.

What is the best age to buy life insurance in Canada?

Life insurance usually becomes more relevant when you take on financial responsibilities such as marriage, children, a mortgage, shared debt, or business ownership. However, purchasing coverage at a younger age can help you unlock lower premiums and better underwriting outcomes.

Do I need life insurance if I am single with no children?

Being single does not automatically remove the need for life insurance as a young adult in Canada. You may still need protection if you own a home with a co-signer, support your parents, or want to leave funds for final expenses.

Can young adults get life insurance without a medical exam?

Yes, several Canadian insurers offer simplified or no-medical options when purchasing life insurance. However, these policies may have lower coverage limits and often cost more than comparable fully underwritten coverage for a healthy applicant.

Can I increase or change life insurance as my family grows?

Yes, many policies from leading Canadian insurers let you convert a term policy into permanent insurance within a specified period. Additionally, some policies may let you purchase additional coverage, add certain riders, or exchange an eligible shorter term for longer coverage. Some insurers may require you to provide new evidence of insurability when increasing your death benefit.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Life Insurance Companies in Ontario (2026)

The best life insurance companies in Ontario include Manulife, BMO, Canada Life, Equitable Life, Canada Protection Plan, and Beneva. These companies specialize in specific coverage needs, from term life insurance and non-participating whole life policies to participating plans with dividend potential and no-medical life insurance. Our advisors have compared the quotes from 30+ insurers and listed the best 6 life insurance companies that you can consider buying in Ontario.

Life insurance can be affordable!

Get the best life insurance quotes in Canada!

Which is the best life insurance company in Ontario?

Ontario accounts for roughly 41% of the Canadian life insurance market. With so many options available, choosing the right provider requires balancing your coverage needs, budget, and long-term financial goals. In the section below, we have listed some of the popular choices for those buying life insurance in Ontario.

★★★★★
Best for dividend payouts and cash-value growth READ REVIEW
★★★★★
Best for multiple plan options and a wellness rewards program READ REVIEW
★★★★★
Best for estate planning READ REVIEW
★★★★★
Best for non-participating policies READ REVIEW
★★★★★
Best for no-medical policies READ REVIEW
★★★★★
Best for bundled disability protection READ REVIEW

1. Equitable Life

Equitable Life is a Canadian mutual company offering participating whole life insurance with lifelong coverage, cash-value growth, and potential annual dividends. Its 6.40% dividend scale interest rate (DSIR) for 2026 is the highest in the whole life insurance market. Its KIND program adds support through benefits such as compassionate advances of up to $100,000 for terminal illness and bereavement counselling reimbursements of up to $1,000. 

Equitable Life is particularly a good choice for homeowners in the Greater Toronto Area managing large mortgages. Its affordable term policies offer excellent temporary protection, while its participating whole life policies suit established professionals looking for tax-advantaged growth.

Our advisor’s take:

We rate Equitable Life 5/5 and recommend it for clients who want participating whole life insurance with strong long-term cash value potential. Its Equimax or participating policies have credited dividends every year since 1936. It offers five dividend options, including paid-up additions that can increase both cash value and the death benefit. Moreover, we also recommend its term life insurance plans for those who want to bundle their coverage through a laddering strategy.

Equitable Life term life pricing

The illustrative cost of Equitable Life term life insurance policy is $10.89 per month for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term. This is the lowest price of all the companies we have used in our rankings.

2. Manulife

Manulife is a strong option for Ontario residents looking for a range of life insurance products, including term and permanent coverage. It offers term life insurance plans including Manulife Family Term and Manulife Family Term with Vitality Plus coverage starting at $100,000 for single-life, joint first-to-die, and joint last-to-die policies. For families focused on an active lifestyle in urban centers like Ottawa or Mississauga, Manulife’s Vitality program offers tangible rewards for healthy living alongside robust coverage. 

For lifelong protection, Manulife also offers participating whole life insurance, backed by a participating account with $15.98 billion in assets. These policies can build cash value and may receive dividends, although dividend payments are not guaranteed.

Our advisor’s take:

We give Manulife 5/5 because it offers a wide range of life insurance products under one roof. It is also one of the first companies in Canada that took the life insurance application online. Along with its term and permanent product lineup, Manulife also offers Synergy, which combines life, critical illness, and disability insurance in one policy. Manulife’s Vitality program is another differentiator. It rewards eligible policyholders for participating in health and wellness activities, with benefits depending on the product and program terms.

Manulife term life pricing

For a 40-year-old male non-smoker purchasing a $100,000, 10-year term policy, the illustrative cost for Manulife term life insurance is around $11.13/month. Across the six companies we compared, this is the second-lowest premium rate.

3. Canada Life

Canada Life is a strong option for Ontario residents seeking permanent life insurance for family protection, wealth transfer, and mainly estate planning. It also offers a My Term plan that provides flexible coverage periods from 5 to 50 years, with guaranteed renewal and the option to convert to permanent insurance before age 70. 

For lifelong protection, Canada Life offers three participating whole life plans, which is also amongst the highest in the industry: Wealth Achiever, designed for earlier cash value growth; Balanced Achiever, which balances cash value and long-term death benefit growth; and Estate Achiever, which focuses on maximizing long-term estate value. These options make Canada Life worth considering for established professionals and families planning for long-term wealth transfer and estate preservation in Toronto and other cities in Ontario. 

Our advisor’s take:

We give Canada Life 4.5/5 because it offers multiple participating whole life policies suited for estate planning and other financial goals. We recommend Estate Achiever for estate planning benefits and those who want to leave a larger long-term death benefit to beneficiaries. We also recommend Canada Life for its financial stability, as it has consistently paid dividends to its eligible policyholders since 1848. It also has the largest participating account fund size in Canada, which is approximately around $62.8 billion.

Canada Life term life pricing

The cost of Canada Life term life insurance plan for a 40-year-old male who is a non-smoker and wants $100,000 in coverage for a 10-year policy term is around $12.36 per month. The cost is slightly higher than Equitable Life and Manulife, but it’s worth considering Canada Life’s My Term plan for its features.

4. BMO

BMO offers two non-participating whole life plans: Estate Protector, designed for long-term estate planning, and Wealth Accelerator, which focuses on higher early cash values. Both provide guaranteed cash values, level premiums, and an annual Performance Bonus (6.00% as of 2026) that can increase cash value and the death benefit without relying on traditional dividends. 

BMO also offers term life insurance with 10- to 30-year terms, offering guaranteed renewability, conversion, and exchange features. Its combination of guaranteed permanent coverage and flexible term protection can suit homeowners in Ottawa, Brampton, and Hamilton,  looking to protect their families while planning for future financial obligations.

Our advisor’s take:

We give BMO Insurance a strong 4.5/5 rating for its guaranteed non-participating whole life and term life insurance options. Like the other insurers listed above, we do not give it a full score because it does not offer participating whole life plans, which limits options for those seeking potential policy dividends. However, BMO is an excellent choice for those who prioritize predictable premiums, guaranteed cash values, and a guaranteed death benefit. We also like its conversion and exchange features offered with the term life insurance plans, along with its compassionate bereavement support benefits.

BMO term life pricing

BMO term life insurance for a 40-year-old male non-smoker seeking $100,000 in coverage for a 10-year term is approximately $11.16 per month. The price is slightly higher than Equitable Life, but it’s still worth considering for its flexible term length options.

5. Canada Protection Plan

Canada Protection Plan (CPP), part of Foresters Financial, specializes in simplified-issue life insurance for those who want to avoid medical exams or have health conditions that make traditional coverage harder to obtain. Its term insurance lineup includes Deferred Elite Term, Simplified Elite Term, Preferred Term Life, Express Elite Term, and Preferred Elite Term Insurance, with select term plans offering up to $1 million in coverage.  

Our advisor’s take:

We give Canada Protection Plan a strong 4/5 rating for its wide range of no-medical life insurance options. What sets CPP apart is its ability to serve applicants with different health profiles, from Deferred Elite for those with less serious health concerns to Preferred Elite for healthier applicants seeking competitive rates without a medical exam. We recommend this insurer to clients with health issues because it does not ask whether they have previously been declined or postponed by another insurer. Since it requires almost no medical tests, its premium is on the higher side.

Canada Protection Plan term life pricing

The illustrative cost of a Canada Protection Plan term life insurance policy is $20.16 per month for a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term. While its price is the highest of all the insurers we have compared, it still remains a good choice for those who want to avoid medical exams or have difficulty qualifying for traditional coverage.

6. Beneva

Beneva stands out for its Term Plus policy, which offers coverage from $25,000 to $10 million across terms of 10 to 40 years. Its standout feature is the built-in Extreme Disability Benefit that can advance up to $250,000 of the death benefit if you experience a qualifying disability. In addition, it also offers flexible term lengths, multiple coverage options, a guaranteed insurability benefit, and a few more. For working professionals and growing families in Mississauga and other Ontario cities, this combination of life insurance and additional disability-related protection can help address both long-term family security and unexpected changes in earning capacity.

Our advisor’s take:

We rate Beneva 4/5 because Term Plus offers useful flexibility, but its main strength is term life insurance rather than a broad selection of permanent coverage options. We particularly recommend considering it if you want to secure coverage for an extended period or combine life insurance with optional protection against critical illness and disability. However, those seeking participating whole life insurance and the potential for policy dividends may find Equitable Life or Manulife more suitable.

Beneva term life pricing

The illustrative cost of a Beneva Term life insurance policy is $11.18 per month for a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term. The price is on the higher side compared to Manulife, Equitable Life, or BMO for the same profile.

Comparing the top life insurance companies in Ontario

Insurer Equitable Life Manulife Canada Life BMO Canada Protection Plan Beneva
PolicyAdvisor rating 5/5 5/5 4.5/5 4.5/5 4/5 4/5
Cost for a 40-year-old male non-smoker($100,000 in coverage for 10-year term) $10.89/month $11.13/month $12.36/month $11.16/month $20.16/month $11.18/month
Life insurance options Whole life and term life  Multiple whole life and term life My Term and 3 participating whole life insurance Non-participating whole life and term life Limited options; specializes in simplified-issue coverage Primarily term-focused plans
Policy features and flexibility – Multiple term lengths (10, 20, 30, 65)

– 5 dividend options

– Term-to-permanent conversion options

– Layering feature

– Multiple term lengths

–  Single-life and joint coverage options for term and whole policies

– Term renewal and conversion privileges

– Multiple limited-pay options and riders

– 5 to 50 years term length

– Conversion to permanent insurance

– Three participating whole life plans

– Business-owner specific rider

– 10- to 30-year term options

– Term-to-permanent conversion and exchange features

– Multiple whole life insurance riders

– Multiple term plans for different health profiles

– Renewal or conversion features available

– Multiple riders for term policy including hospital cash and critical illness rider

– Flexible term lengths from 10-40 years

– Guaranteed insurability benefit

– Term exchange feature

Standout feature 6.40% 2026 dividend scale interest rate (DSIR) Vitality wellness rewards and Synergy coverage Flexible term life plans Performance Bonus and guaranteed cash values Broad range of no-medical plans Extreme Disability Benefit and bereavement benefits included with Term Plus
LICAT Ratio 159% 136% 130% 134% 188% 163%
AM. Best Rating A A+ A+ A A A
Best for Long-term cash-value accumulation and participating policy benefits Multiple plans and to earn rewards for leading a healthy lifestyle Those looking for estate planning Guaranteed values through non-participating policies Those with existing health conditions or prefer a simpler application Bundled disability protection

 Actual premiums vary by age, sex, smoking status, health, coverage amount, product, and underwriting. Minimum coverage varies by product and eligibility. 

Our methodology for ranking the best life insurance in Ontario

Our 2026 rankings of the best life insurance companies in Ontario are based on illustrative term and whole life insurance quotes and an assessment of each insurer’s product features, coverage flexibility, and suitability for different customer needs. We evaluated 30+ insurers and shortlisted the following six providers: Equitable Life, Manulife, Canada Life, BMO Insurance, Canada Protection Plan, and Beneva. We divided our methodology into two main areas: pricing (40%) and product features and suitability (60%).

1. Pricing (40%)

We compared term life insurance premiums using a consistent applicant profile: a 40-year-old male non-smoker purchasing $100,000 in coverage for a 10-year term. We assessed relative pricing across the six insurers under the same assumed circumstances. The quoted monthly premiums ranged from $10.89 for Equitable Life to $20.16 for Canada Protection Plan.

Insurer name Male (non-smoker)
Equitable Life $10.89/month
Manulife $11.13/month
Canada Life $12.36/month
BMO $11.16/month
Canada Protection Plan $20.16/month
Beneva $11.18/month

Term life insurance cost in Ontario

Term premiums are illustrative monthly costs for a 40-year-old non-smoker male seeking $100,000 of coverage for a 10-year term. Actual premiums vary by age, sex, health, smoking status, product, coverage amount, and underwriting. All premiums listed on Y-azix are in CAD (CA$).

2. Product features, suitability, and financial strength (60%)

We assessed each insurer based on the following criteria, using the following weights:

Evaluation criterion Weightage What we assessed
Life insurance options 20% Availability of term, participating whole life, non-participating whole life, and simplified-issue or no-medical coverage
Policy features and flexibility 20% Available term lengths, coverage amounts, dividend options, renewal and conversion privileges, and opportunities to adjust coverage
Standout features 10% Distinctive benefits such as wellness rewards, guaranteed cash values, no-medical underwriting, and disability-related benefits
LICAT Ratio 5% LICAT ratio as an indicator of capital adequacy
AM Best Rating 5% To determine an insurer’s financial strength

After shortlisting the six strongest companies, we ranked each insurer individually using the same weighted criteria to show where one company may be stronger than another.

Pricing and entry-level affordability40%
Life insurance options20%
Policy features and flexibility20%
Standout features10%
LICAT Ratio5%
AM Best Rating5%

How we further assigned insurer ratings:

We used the pricing comparison and product-feature assessment to identify each insurer’s strengths, limitations, and best-fit customer profiles. Our final ratings reflect the relative value of each provider’s offerings rather than price alone.

For example, Equitable Life and Manulife received 5/5 ratings for their broad product options and permanent insurance features. BMO and Canada Life received 4.5/5 ratings for their strengths in guaranteed non-participating coverage and whole life insurance plans, respectively. Canada Protection Plan and Beneva received 4/5 for their no-medical and term-focused offering and disability-related benefits, respectively, with a more limited range of permanent insurance options.

Comparing PolicyAdvisor ratings:

Insurer Pricing 40% Life insurance options (20%) Policy features and flexibility (20%)  Standout features (10%) LICAT Ratio (5%) AM Best Rating (5%) Final rating
Equitable Life 5/5  5/5  5/5  5/5  5/5  4/5 5/5
Manulife 4.5/5 5/5  5/5   5/5  4.5/5 5/5  5/5
Canada Life 4.5/5 5/5  5/5  4.5/5 4.5/5 5/5  4.5/5
BMO 4.5/5 4/5 4.5/5 4.5/5 4.5/5 4/5 4.5/5
Canada Protection Plan 3.5/5 4/5 4/5 4.5/5 5/5  4/5 4/5
Beneva 4.5/5  4/5  3.5/5  4/5  4.5/5 4/5  4/5

Disclaimer: The ratings reflect PolicyAdvisor’s assessment of each insurer’s pricing, product options, policy flexibility, standout features, and financial strength. Component scores are comparative assessments and may not represent every applicant’s experience. Premiums are illustrative and vary by age, health, smoking status, coverage amount, and policy terms. LICAT ratios and AM Best ratings are subject to change and reflect the applicable reporting dates and rated entities. Final ratings are rounded assessments and should not be interpreted as guarantees of policy performance or suitability.

Cost of life Insurance in Ontario

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Can I get life insurance in major Ontario cities?

Yes, you can easily get life insurance in major Ontario cities such as Toronto, Ottawa, Mississauga, Brampton, Hamilton, Windsor, and others. Your city or province does not directly affect life insurance coverage or costs. The overall cost depends on age, health, smoking status, coverage amount, and policy type, rather than your city alone.

How to buy life insurance in Ontario?

Here are the steps you need to follow to get life insurance in Ontario:

  • Speak with a licensed advisor: Schedule a free call to discuss your financial goals, family responsibilities, budget, and coverage needs with one of our expert advisors
  • Calculate your coverage needs: Our advisors will help you determine how much insurance you need to cover debts, mortgage payments, income replacement, and future expenses
  • Compare insurance plans: Review quotes, premiums, policy features, and eligibility requirements across multiple insurers
  • Complete your application: Apply for your chosen policy and answer the insurer’s health questions. A medical exam may be required, depending on the policy and your profile
  • Review and activate your coverage: Confirm your coverage amount, premiums, exclusions, and policy terms before accepting the policy and maintaining your payments

Schedule a call now to get started with your life insurance application process in Ontario!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Can I get life insurance in Ontario without a medical exam?

Yes, you can get life insurance in Ontario without undergoing a medical exam. There are a few insurers that offer simplified-issue or no-medical life insurance, including Canada Protection Plan. Through these kinds of life insurance policies, you can qualify for life insurance coverage without a medical exam. 

Is life insurance tax-free in Ontario?

Life insurance death benefits paid to a named beneficiary are generally tax-free in Ontario. However, withdrawals or surrenders of permanent life insurance policies may trigger taxes, depending on the policy’s adjusted cost basis and the transaction.

How much life insurance coverage do I need in Ontario?

Your coverage needs depend on your income, outstanding debts, mortgage, dependants, and future expenses. A useful starting point is to estimate your debts, add several years of income replacement and anticipated family expenses, and subtract existing savings and life insurance coverage or simply use our life insurance calculator. 

Can I have more than one life insurance policy in Ontario?

Yes, you can own multiple life insurance policies in Ontario, such as a term policy for mortgage protection and a permanent policy for lifelong coverage. Insurers may assess your total coverage and financial needs when reviewing new applications.

What happens if I miss a life insurance premium payment?

If you miss a premium payment, your policy may enter a grace period during which you can pay the overdue amount and maintain coverage. If you do not pay within the applicable period, the policy may lapse; however, the rules are defined in the policy contract. Some permanent policies may have options to help keep coverage in force, depending on their terms.

Is life insurance through work enough in Ontario?

Employer-provided life insurance may be sufficient for some people, but coverage is often limited to a multiple of your salary or a fixed amount. It may also end when you leave your job and may not be portable. An individual policy can provide additional coverage and greater control over how long your protection lasts.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

What is reinsurance and how does it work?

Reinsurance is a type of insurance that an insurance company can buy from an organization or group ( called a reinsurer) to transfer some or all of the financial risk it has undertaken. To put it simply, it is insurance for insurance companies. This can allow Canadian insurers to manage risk, increase their underwriting capacity, or use their available capital more efficiently. For most policyholders and applicants in Canada, this is something that works behind the scenes.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What is reinsurance?

Reinsurance is insurance that an insurance company purchases from another insurer or reinsurance company to transfer part of the risk it has already accepted. The insurer can transfer part or all of certain risks to another organization. The insurer transferring the risk is also known as the ceding company, cedant, or reinsured. Meanwhile, the company assuming that risk is known as the reinsurer.

Essentially, reinsurance is a type of protection that insurance providers purchase to minimize their risk in the event of major claims, such as a natural disaster. A life insurer may decide that it does not want to retain the financial risk associated with all the policies it issues. Through a reinsurance agreement, the insurer can transfer an agreed portion of the liability or risk to a reinsurer.

Reinsurance allows insurance companies to share liability with other firms or organizations, especially in situations where the primary insurance company does not have enough cash reserves in place to pay out claims. This helps keep insurers afloat when large or multiple claims arise and ensures claimants receive the benefits they are entitled to.

What is a reinsurance company?

A reinsurance company, or reinsurer, is an insurance company that assumes some or all of the insurance risk originally accepted by another insurer. These companies enter into an agreement with an insurer to transfer, or cede, part of the insurer’s assumed risk, helping the insurer reduce liability and free up capital.

Reinsurance spreads the financial risk from one insurer to many other firms.

How does reinsurance work in Canada?

Reinsurance works by allowing an insurance company to transfer an agreed portion of the risks it has accepted to another insurance company. It involves two insurance companies: the insurer that originally accepts the insurance risk and the reinsurer that agrees to take on an agreed portion of that risk. These entities enter into an agreement under which the reinsurer assumes an agreed portion of the insurer’s risk. However, a reinsurance transaction can involve two or more parties, including multiple reinsurers.

An insurance company issues policies to thousands of Canadians but wants to limit how much insurance risk it retains on its own books. The insurer can then enter into a reinsurance contract that specifies the risks being transferred and how much of those risks the reinsurer will assume. If a covered loss occurs, the reinsurance contract determines the amount the reinsurer owes the original insurer. The original insurer can then use it to pay claims or manage financial liabilities.

Here’s how reinsurance works:

  • Insurer accepts a risk: An insurance company issues policies to consumers and assumes the financial risk associated with that coverage
  • Part of the risk is transferred: The insurer may decide to transfer a portion of the risk assumed to a reinsurer
  • Both parties enter into an agreement: The contract lays out which risks are covered and how liability is divided between the insurer and reinsurer
  • A covered claim occurs: If a loss covered by the reinsurance takes place, the reinsurer reimburses the insurer up to the amount or percentage stipulated in the agreement

For example, if a natural disaster destroys or damages thousands of homes in a region where one insurance company provides most home insurance coverage, that company may be hard-pressed to cover all the claims.

By using reinsurance, however, the insurance provider can recover part of the losses from other insurers while avoiding insolvency. In this respect, reinsurance not only protects insurance companies but also helps protect their clients by supporting the insurer’s ability to pay covered claims.

In addition to mitigating risk in extreme circumstances, reinsurance also enables insurance companies to increase their coverage capacity. Insurance companies are better equipped to take on clients with larger policy coverage because reinsurance can mitigate losses if the coverage is claimed. This is particularly useful since it enables insurers to take on more clients without increasing capital reserves accordingly.

when insurers use reinsurance

What are the different types of reinsurance?

While there are many types of insurance one can buy, reinsurance can be structured in two primary ways: treaty reinsurance and facultative reinsurance. 

  • Treaty reinsurance: This is a standing agreement between an insurance company and a reinsurer that covers specified classes or categories of the insurer’s risk. Under most treaty arrangements, eligible risks are automatically ceded to and accepted by the reinsurer, instead of requiring a negotiation each time. The treaty sets out details for the types of risks covered, limits, premiums, and how the insurer and reinsurer will share responsibility.
  • Facultative reinsurance: In this type, reinsurance is arranged for an individual policy or specific risk rather than an entire class of business. Each submission is considered separately, and both the insurer and reinsurer can decide whether to reject or accept that particular risk. Since each risk is individually reviewed and negotiated, facultative reinsurance is more selective than treaty reinsurance.

Here’s a comparison of treaty and facultative reinsurance:

Feature Treaty reinsurance Facultative reinsurance
Scope Covers eligible risks within an agreed class or category Covers an individual policy or specific risk
Acceptance Eligible risks are covered according to the existing treaty terms Each risk is considered separately and on its merits
Review The reinsurer does not separately negotiate every eligible risk The specific risk is individually reviewed
Structure Ongoing agreement covering defined business Individual reinsurance arrangement

Apart from these primary classifications, reinsurance can also be classified in the following ways:

  • Proportional reinsurance: The insurer and reinsurer share an agreed proportion of the premiums and losses of the reinsured company.
  • Non-proportional reinsurance: The reinsurer’s participation depends on the size of the loss. The insurer retains losses up to a specified amount, after which the reinsurer covers eligible losses above that amount, subject to limits and other terms of agreement.
More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

Why do life insurance companies use reinsurance?

Insurance companies primarily use reinsurance as part of their broader financial and risk-management strategy. It can help an insurer reduce insurance risk and financial volatility, stabilize solvency, or withstand catastrophic events that may trigger massive payouts. In addition, reinsurance can support underwriting capacity and provide access to a reinsurer’s expertise.

Here’s a quick overview of why insurance companies use reinsurance:

  • Manage insurance risk: Reinsurance lets an insurer transfer part of the risks it has accepted instead of retaining the entire exposure itself.
  • Increase underwriting capacity: Reinsurance can give an insurer additional capacity to take on insurance risks.
  • Manage capital efficiently: Reinsurance arrangements can also reduce the liability, freeing up more available capital.
  • Reduce financial volatility: Sharing risk with the reinsurer can help prevent financial collapse in the event of a massive payout
  • Protect against large losses: Reinsurance can reduce an insurer’s exposure to large or catastrophic losses
  • Access specialized expertise: Reinsurers can provide medical, actuarial, and risk-assessment expertise that can help insurers evaluate certain applications and claims.
types of reinsurance

How does reinsurance affect your life insurance application and claims?

While reinsurance is primarily an arrangement between insurance companies, it can sometimes play a role in how an insurer evaluates and manages a life insurance application.

Here’s how reinsurance can affect your life insurance application and claims:

  • Additional underwriting capacity: Reinsurance allows insurers to transfer part of the risk they take on. This can increase their capacity to insure larger or more complex risks, broadening their portfolio.
  • Access to specialized underwriting expertise: Reinsurers can provide medical, actuarial, and risk-assessment expertise that can help insurers evaluate certain applications and following claims.
  • Potential for additional application review: Some applications may be referred to a reinsurer for further assessment, allowing the reinsurer to better assess the risk or provide advice
  • Possible impact on the underwriting outcome: Reinsurance can potentially help an insurer consider risks it may not want to retain entirely on its own. This can let the insurer offer coverage to policyholders for higher-risk cases

Can my insurer share my medical information with a reinsurer?

Yes, your medical information may be shared with a reinsurer when it is necessary for insurance underwriting or risk evaluation, depending on the insurer and circumstances. Many insurers state that organizations with which they may share personal information can include other insurance and reinsurance companies.

proportional versus non-proportional reinsurance

Who do you deal with if your life insurance policy is reinsured?

In most cases, the policyholder continues their relationship with the insurance company that issued their policy. However, this may change depending on whether the insurer uses indemnity or assumption reinsurance.

  • Indemnity reinsurance: The reinsurer reimburses the insurance company for eligible claims. The insurer typically continues collecting insurance premiums and administering the policy, so policyholders do not deal directly with the reinsurer.
  • Assumption reinsurance: The reinsurer takes over responsibility for the affected policies, including eligible financial obligations and policy administration. Policyholders may be required to pay premiums to the reinsurer and receive coverage through them.

Insurance vs. reinsurance: what is the difference?

Insurance and reinsurance both transfer financial risk, but they serve different purposes and involve different parties. While insurance concerns individuals or businesses, reinsurance helps insurance companies manage their risks.

Here’s a quick comparison of insurance and reinsurance:

Feature Treaty reinsurance Facultative reinsurance
Scope Covers eligible risks within an agreed class or category Covers an individual policy or specific risk
Acceptance Eligible risks are covered according to the existing treaty terms Each risk is considered separately and on its merits
Review The reinsurer does not separately negotiate every eligible risk The specific risk is individually reviewed
Structure Ongoing agreement covering defined business Individual reinsurance arrangement

Which are the biggest reinsurance companies?

Many of the world’s largest reinsurers operate across multiple countries and work with insurance companies in several markets.

According to S&P Global, the top 10 biggest reinsurance companies based on gross premiums written for pure reinsurance business in S&P Global’s 2026 ranking:

  • Munich Reinsurance Co. (Germany)
  • Swiss Re AG (Switzerland)
  • Hannover Re (Germany)
  • Lloyd’s (United Kingdom)
  • Berkshire Hathaway Insurance Group (United States)
  • SCOR SE (France)
  • Reinsurance Group of America (RGA) (United States)
  • China Reinsurance (Group) Corp. (China)
  • Everest Group Ltd. (Bermuda)
  • RenaissanceRe Holdings Ltd. (Bermuda)
Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently Asked Questions

What does reinsurance mean?

Reinsurance is when an insurance company transfers part of the insurance risk it has accepted to another insurer or organization, known as a reinsurer. It is commonly referred to as insurance for insurance companies.

What are the main types of reinsurance?

Treaty reinsurance and facultative reinsurance are the two main types of reinsurance in Canada. Treaty reinsurance is a standing agreement between an insurance company and a reinsurer that covers specified classes or categories of the insurer’s risk, while facultative reinsurance is arranged for an individual policy or specific risk rather than an entire class of business.

Does reinsurance affect my life insurance policy?

Usually, reinsurance operates between your insurance company and its reinsurer rather than changing your direct relationship with the insurer. Typically, there is no change in where policyholders pay premiums.

Can my life insurance company share my application with a reinsurer?

An insurer may share relevant personal information with a reinsurance company for underwriting or risk assessment. This can happen when the insurer wants additional expertise or needs to determine how much of the risk it can retain itself versus transfer to a reinsurer.

Can reinsurance help an insurer offer more life insurance coverage?

Reinsurance can increase an insurance company’s underwriting capacity by allowing it to transfer part of its insurance risk. This can be especially relevant when an applicant is requesting a large amount of life insurance or when the insurer does not want to retain the full risk on its own.

What are the two types of reinsurance?

The two primary types of reinsurance used by insurers are treaty and facultative reinsurance. Treaty reinsurance covers a defined class of eligible risks, while facultative reinsurance considers each risk individually.

What is treaty reinsurance?

Treaty reinsurance is an agreement between the insurer and the reinsurer to cover a defined class or group of insurance business. It may automatically accept a portion of the insurer’s liability for specified classes of insurance.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

How much life insurance do I need in Canada?

According to a 2026 report published by LIMRA, the new annualized premiums reached a record $2.3 billion in 2025, up 9% year over year, while policy sales increased 4%. This data highlights how more people are now getting life insurance coverage in Canada. You should get at least 5 to 10 times your income in life insurance coverage; however, choosing the right amount also depends on factors such as your income, debts, mortgage, dependants, savings, and long-term financial goals.

How much life insurance should you have in Canada?

There is no one-size-fits-all amount of life insurance coverage in Canada. A common rule of thumb is to have 5 to 10 times your annual income in life insurance. However, this can be too little or too much depending on your financial situation. A family with a large mortgage and young children may need significantly more coverage than a single person with substantial savings and few financial obligations.

Example: Calculating life insurance needs for someone earning $100,000 a year

Yearly income $100,000
Mortgage $400,000
Other debts $30,000
Children’s future education $100,000
Savings $100,000
Existing life insurance coverage through employer $200,000
Estimated coverage $1,000,000 + $400,000 + $30,000 + $100,000 − $100,000 − $200,000 = $1.23 million

In this example, about $1.23 million of additional life insurance could provide a reasonable starting point. Your result will depend on your circumstances and the assumptions used. Use our life insurance calculator to get a personalized estimate, then compare policies that fit your needs.

Calculate your life insurance needs!

Compare quotes from Canada’s top insurers.

How do I calculate how much life insurance I need?

The amount of life insurance you need depends on how much financial support your family would require if you died. Rather than relying on a single rule of thumb, consider the different expenses and financial obligations your policy may need to cover, along with the savings and insurance you already have.

The best way to figure out how much insurance you need is to use a life insurance calculator. These calculators perform an instant assessment of your personal and financial situation. They look at both your assets and liabilities. Then they estimate how much insurance you need to cover those liabilities.

To understand how that estimate is calculated, ask yourself these questions:

Outstanding debts

Your outstanding debts are one of the first things to consider because they could become a financial burden for your family after your death. Add up your mortgage, car loans, lines of credit, credit cards, and other outstanding loans to determine how much would need to be repaid. Life insurance can provide your beneficiaries with a lump sum they can use to pay these obligations without having to sell assets or rely on their regular income to make debt payments.

Family’s living expenses

After accounting for your debts, consider the ongoing expenses your family would still need to pay. These can include housing, food, utilities, childcare, transportation, insurance, and other household costs.

A dependent is anyone who needs your financial support. If you are the primary breadwinner in your household and/or have kids, then you already have dependents. You may also have elderly parents or disabled family members who depend on you financially. Their needs should all be considered when calculating the coverage amount. They will be the beneficiaries of the life insurance payout.

Future expenses

Once you have considered your debts and your family’s ongoing expenses, estimate how much of your income they would need to replace if you were no longer there.

Your family may not need to replace 100% of your after-tax income. Consider what percentage would be enough to maintain their lifestyle and meet their financial obligations.

For example, if you earn $100,000 annually and estimate your family would need 70% of that income, you would plan around $70,000 in annual income replacement. The number of years this support is required will depend on your age, dependants, retirement plans, and other household income.

Existing savings

Do you have any savings? Whether it’s in your bank account, an investment portfolio, an RRSP you opened at 19, or wads of cash stuffed under your mattress, any assets you have stored away can help reduce your life insurance coverage needs.

While some people reduce their life insurance coverage because they have savings, others may buy life insurance to protect it. That way, your dependents would not need to dip into savings that have been allocated for long-term growth (like investments) or sell assets.

Discuss with your dependents

Your coverage calculation should also reflect what your family would actually need. Discuss your finances with your spouse or other dependents and consider how your death would affect the mortgage, household expenses, childcare, education, retirement plans, and other financial commitments. This conversation can help identify expenses that may be missed in a basic calculation and give you a better idea of the financial cushion your life insurance should provide.

expanding on the DIME method for life insurance needs

How to calculate life insurance coverage using the DIME method

A life insurance calculator provides a more personalized estimate, but you can also use common rules of thumb to get a quick starting point.

DIME Method

The DIME method is often used by brokers and financial advisors to determine your life insurance needs on the fly. It stands for four major aspects that you should consider in your financial strategy: Debt, Income, Mortgage, and Education. 

  • Debt: Add your outstanding debts other than your mortgage
  • Income: Estimate how many years of income your family would need to replace
  • Mortgage: Include the amount required to repay your outstanding mortgage
  • Education: Estimate future education costs for your children

The DIME method is useful as a starting point, but it does not account for everything that can affect your coverage needs. It may overlook your savings, existing life insurance, funeral expenses, investments, childcare costs, and other future financial obligations.

Is 10 times my annual income enough life insurance?

Another common rule of thumb is to buy 5 to 10 times your annual income in life insurance coverage. For example, someone earning $100,000 a year might consider $1 million to $1.5 million of coverage.

This approach is quick, but it does not account for individual circumstances. Someone with a large mortgage and young children may need considerably more coverage than another person with the same income but substantial savings and no dependants.

What type of life insurance should I choose?

The right type of life insurance depends on how long you need coverage, your budget, and the financial needs you want the policy to address. The main options include:

  • Term life insurance: Provides coverage for a set period, such as 10, 20, or 30 years. It is often suitable for covering temporary needs such as a mortgage, income replacement, or children’s financial support
  • Whole life insurance: Provides lifelong coverage and builds cash value. Whole life insurance may suit people looking for permanent protection, estate planning, or a guaranteed death benefit
  • Universal life insurance: Combines permanent life insurance with an investment component, offering more flexibility in premiums and coverage. It can be useful for estate planning and other long-term financial needs

Tips for choosing the right amount of life insurance

When choosing the right coverage, you need to factor in a lot of factors apart from your debts, income, and other financial obligations. Here are some other tips to consider to get the right life insurance coverage:

  • Consider laddering your policies: You don’t necessarily need to buy your entire coverage amount through one policy. Laddering involves combining policies with different coverage amounts and terms to match different financial needs. For example, you could combine a $750,000 20-year term policy with a $250,000 10-year policy. As shorter-term obligations end, the smaller policy expires while the larger policy continues
  • Use group coverage to supplement individual insurance: Employer-provided life insurance can form part of your overall coverage, but it may have a relatively low benefit limit and may not follow you when you leave the employer. Calculate your total protection using both group and individual policies, then determine whether you need additional coverage
  • Build in a financial cushion: Your coverage calculation is an estimate, and your family’s actual expenses may be higher than expected. Adding a reasonable buffer can help account for unexpected costs or changes in circumstances
  • Choose coverage you need: The largest possible policy isn’t necessarily the best choice if the premiums become difficult to sustain. Consider whether the premium fits comfortably within your long-term budget
  • Compare policy features, not just the death benefit: Two policies with $1 million in coverage can differ in premiums, renewability, conversion options, exclusions, dividend payout, and available riders. Consider these features alongside the coverage amount when comparing policies

How much does life insurance coverage cost in Canada?

Life insurance coverage in Canada can cost as little as $8 per month for $100,000 of 10-year term coverage for a young, healthy non-smoker. As the coverage amount increases, so does the premium; in the illustration below, $1 million costs $35.54/month for a male non-smoker and $22.95/month for a female non-smoker, while $10 million costs $310.50 and $184.50 per month, respectively.

Cost of term life insurance (2026):

Coverage amount Male (non-smoker) Female (non-smoker)
$100,000 $9.45/month $8.19/month
$250,000 $13.94/month $10.58/month
$500,000 $21.60/month $14.85/month
$1,000,000 $35.54/month $22.95/month
$10,000,000 $310.50/month $184.50/month

*Illustrative term life insurance cost of a 10-year plan with $100,000-$10,000,000 in coverage for male/female non-smoker

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

How long should my life insurance coverage last?

Your life insurance should generally last as long as your family would depend on your income or as long as the financial need you are protecting remains. For many Canadians, this means choosing a term that covers the years until their mortgage is paid off, children become financially independent, or they reach retirement. 

For example, if you have young children and expect to need income replacement for the next 20 years, a 20-year term policy may be appropriate. If you have a financial need that will continue for your entire lifetime, such as estate planning or leaving a legacy, permanent life insurance may be more suitable.

How to get life insurance coverage in Canada?

Getting life insurance in Canada typically involves determining how much coverage you need, comparing policies and insurers, completing an application, and going through underwriting. Here are the simple steps you need to follow to get life insurance coverage in Canada with PolicyAdvisor:

  • Calculate your coverage needs: Start by estimating your income replacement, debts, future expenses, and other financial obligations
  • Compare your options: Our advisors will help compare life insurance quotes from 30+ Canadian insurers to help identify policies that fit your coverage needs and budget
  • Complete your application: We will help you submit your application and provide guidance on the information and documents required
  • Complete underwriting: Depending on your application, the insurer may request medical questions, a medical exam, blood or urine tests, or additional records
  • Review your application: Once the insurer assesses your application, you will receive your coverage details, including the premium and policy terms
  • Policy gets active: Once you pay the premiums and complete the required steps, your policy becomes active 

Schedule a call now to get free life insurance quotes!

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

How is life insurance coverage calculated?

Life insurance coverage needs can be calculated by adding the money your family may need for income replacement, debts, living expenses, and future expenses, then subtracting resources such as savings, investments, and existing life insurance. Methods such as the DIME method and income multiples can provide quick estimates.

Can I have more than one life insurance policy in Canada?

Yes, you can have multiple life insurance policies if you qualify for the coverage. Having more than one policy can be useful for laddering, where policies with different coverage amounts and terms address financial needs that expire at different times.

Does employer-provided life insurance count toward how much coverage I need?

Yes, you should include your group life insurance when calculating your total coverage. However, you must check its benefit amount and whether it remains available if you leave your employer. You may need an individual policy to supplement workplace coverage and maintain protection independently of your employment.

Is $500,000 enough life insurance for a family in Canada?

Whether $500,000 is enough life insurance coverage for a family in Canada or not depends on their financial obligations, income, and a few other factors. It may be sufficient for someone with limited debt and substantial savings, while a family with a large mortgage, young children, and significant income-replacement needs may require a higher coverage amount.

How much life insurance do I need based on my salary?

A common starting point is 5 to 10 times your annual income, but your actual needs depend on your debts, dependants, living expenses, future financial goals, savings, and existing life insurance coverage. You can use our life insurance calculator to get the actual estimates.

Can I increase my life insurance coverage later?

Yes, you may be able to increase your coverage, depending on your policy and insurer. Some policies offer options such as additional coverage, policy conversion, or guaranteed insurability riders. If your financial needs change significantly, you may also apply for a new policy, although your age and health at that time can affect the premium.

How much life insurance do I need if I am single?

If you are single and you are planning to get life insurance in Canada, you will require lower coverage. This is because you don’t have dependants who rely on you financially. However, you should consider whether you have any ongoing debts, final expenses, and other outstanding obligations to estimate the right coverage amount. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Cheapest life insurance in Canada (2026)

The cheapest life insurance policy in Canada is term life insurance, with premiums starting as low as $10 per month for young and healthy applicants. However, the most affordable life insurance policy for you depends on your age, health, coverage amount, and the insurer you choose. Some of the cheapest life insurance providers in Canada include Beneva, BMO, Canada Life, Desjardins, and a few others. 

Quick summary:

Cheapest for Company name
Term life insurance Beneva
Whole life insurance Foresters
No-medical life insurance  UV Insurance
Seniors Canada Life

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

Which type of life insurance is cheapest?

Term life insurance is the most affordable life insurance in Canada. The cheapest term life insurance rates for a healthy, non-smoking Canadian: a 20-year term policy with $100,000 in coverage starts at just $10.08 per month at age 20, compared to $70.74 per month for a 20-pay whole life policy and $14.40 per month for a no-medical life insurance policy. Premiums increase with age for all policy types; term life remains the most affordable option across every age group.

Term life insurance is the most affordable option for four primary reasons:

  • No cash value: Unlike whole life insurance, term life insurance does not build cash value or investment savings, keeping premiums focused on the death benefit
  • Temporary coverage: It protects for a fixed period, such as 10, 20, or 30 years. If you outlive the term, the policy simply expires unless you renew or convert it
  • Simple policy design: Term life focuses solely on providing a death benefit without additional features like dividends
  • Lower claim risk: Because term life covers you for a fixed period, insurers are less likely to pay a death benefit than with lifelong coverage

The table below compares the monthly cost of term life, whole life, and no-medical life insurance for non-smokers across different age groups. As age increases, premiums rise for all policy types, but term life remains the lowest-cost option at every age.

Term life vs Whole life vs No-medical life insurance costs:

Age (in years) Term life insurance Whole life insurance  No-medical insurance 
20 $10.08 $70.74 $14.40
30 $10.35 $100.35 $15.30
40 $14.13 $141.66 $19.26
50 $29.43 $223.61 $41.40
60 $86.85 $317.15 $131.13

Disclaimer: Premiums shown are illustrative monthly rates for a healthy, non-smoking male purchasing $100,000 in coverage for a 20-year term. Actual premiums vary based on factors such as age, gender, medical history, lifestyle, insurer, and more.

What factors affect life insurance costs in Canada?

The key factors affecting life insurance premiums include age, gender, smoking status, overall health, and a few others. Here are the key factors that affect your premium:

Personal risk profile:

  • Age: Your premiums increase as you get older because the likelihood of developing health conditions and making a claim rises with age
  • Health and medical history: Insurers assess your current health, pre-existing medical conditions, family medical history, height, weight, and prescription medications to determine your level of risk
  • Smoking status: Smokers and tobacco users typically pay significantly higher premiums than non-smokers due to the increased risk of serious illnesses
  • Occupation: People working in high-risk jobs, such as construction, mining, or aviation, may pay higher premiums due to a greater risk of injury or death
  • Lifestyle and hobbies: Activities such as skydiving, scuba diving, rock climbing, or private aviation may increase premiums because they carry a higher risk of accidental death
  • Gender: Women often pay lower premiums than men because they generally have a longer life expectancy

Policy and payment structure:

  • Coverage amount: Higher coverage limits result in higher premiums because the insurer may have to pay a larger death benefit
  • Policy type: Term life insurance is generally the most affordable option, while whole life and no-medical life insurance cost more
  • Policy term: For term life insurance, longer terms generally cost more than shorter terms because coverage lasts longer
  • Underwriting type: Fully underwritten policies usually offer lower premiums for healthy applicants, while no-medical life insurance costs more because insurers accept more risk without a medical assessment
  • Payment frequency: Paying annually rather than monthly can reduce your overall insurance costs, as some insurers charge an instalment fee for monthly payments
  • Insurance company: Premiums vary between insurers, even for the same applicant profile, because each company uses its own underwriting guidelines and pricing models. Comparing life insurance quotes from multiple insurers can help you find the lowest rate

Does gender affect premiums in Canada?

Yes, gender can affect life insurance premiums in Canada. Women generally pay lower premiums than men of the same age and health profile. This is because women have a higher average life expectancy, which typically translates to a lower risk of the insurer paying a claim earlier. For example, a healthy 30-year-old non-smoking woman can get $100,000 of 20-year term life insurance quote for about $8.19 per month, compared to $9.45 per month for a man.

Which companies offer the cheapest life insurance plans in Canada?

Based on PolicyAdvisor life insurance quote comparisons in mid‑2026, Beneva, BMO, and Canada Life consistently offer some of the lowest premiums for term life insurance, while insurers such as Desjardins and Sun Life are often competitively priced for whole life insurance. If you are looking for no-medical coverage, the most affordable insurers include Assumption Life and UV.

Also, the premium rates shift by age, coverage amount, health class, and province, so the cheapest insurer changes from person to person. As a result, the cheapest insurer for one person may not be the cheapest for another.

Cheapest term life insurance companies

Beneva, BMO, and Canada Life are among the cheapest term life insurance companies in Canada, offering consistently competitive premiums across different age groups. All three insurers provide affordable coverage; they differ in who they suit the most. 

Beneva offers the lowest premiums, with rates starting at $10.80 per month for a healthy 20-year-old non-smoker purchasing $100,000 of 10-year term coverage and rising to $97.11 per month at age 60. BMO closely matches Beneva, with premiums ranging from $10.80 to $103.41 per month, while Canada Life remains competitively priced at $11.36 to $107.46 per month.

Cost of term life insurance by insurers

Age (in years) Beneva BMO Canada Life
20 $10.80 $10.80 $11.36
30 $10.98 $11.34 $11.85
40 $14.85 $14.94 $16.30
50 $32.85 $32.85 $36.80
60 $97.11 $103.41 $107.46

Disclaimer: Illustrative monthly cost of a 10-year term with $100,000 in coverage for a male non-smoker

Cheapest whole life insurance companies

The cheapest whole life insurance companies in Canada include Foresters, Desjardins, Sun Life, and a few others. While all three insurers provide affordable permanent life insurance, they each cater to different needs. For a healthy, non-smoking applicant purchasing $100,000 of 20-pay non-participating whole life insurance, Foresters offers the lowest premiums across all age groups, starting at $70.74 per month at age 20 and increasing to $319.41 per month at age 60. Desjardins follows closely with premiums ranging from $78.21 to $333.72 per month, while Sun Life offers rates between $91.17 and $346.41 per month.

Cost of whole life insurance by insurer

Age (in years) Foresters  Desjardins  Sun Life 
20 $70.74 $78.21 $91.17
30 $100.35 $105.66 $114.21
40 $141.66 $151.29 $166.23
50 $223.83 $235.26 $267.12
60 $319.41 $333.72 $346.41

Disclaimer: Illustrative monthly cost of a non-participating whole life insurance with $100,000 in coverage for a male non-smoker (20-Pay)

Cheapest no-medical life insurance companies

UV Insurance, Assumption Life, and Canada Protection Plan are among the cheapest no-medical life insurance companies in Canada, offering competitive premiums for applicants who want coverage without undergoing a medical exam. These insurers are good options for people with pre-existing health conditions, those who have been declined for traditional life insurance, or anyone looking for a faster and simpler application process. UV offers the cheapest premiums starting at $13.50 per month for no-medical life insurance plans. 

Cost of no-medical insurance by insurers

Age (in years) UV Insurance  Assumption Life Canada Protection Plan (Foresters Life)
20 $13.50 $14.40 $18.00
30 $13.95 $15.30 $18.81
40 $14.85 $19.26 $20.16
50 $25.38 $41.40 $35.64
60 $80.37 $131.13 $87.66

Disclaimer: Illustrative monthly cost of a 10-year no-medical plan with $100,000 in coverage for a male non-smoker

Compare the most affordable life insurance quotes in Canada!

Get instant life insurance quotes with the help of our licensed experts.

What is the cheapest life insurance option for seniors?

Seniors can find the cheapest life insurance in Canada through traditional term life or no-medical exam policies. While the life insurance premiums for seniors are higher due to age and health risks, they can still find affordable coverage by comparing plans and choosing basic coverage amounts. Some of the companies offering cheap life insurance for elderly or seniors include Canada Life, Desjardins, and Sun Life.

A senior citizen can get $250,000 of 10-year term life insurance for about $98.33 per month at age 60. Even at age 70, term life costs $293.40 per month, making it considerably more affordable than whole life insurance, which costs $1192 per month. However, by age 80, many insurers no longer offer new 10-year term policies. Whole life insurance is more expensive but provides lifelong protection. Monthly premiums for a $250,000 20-pay non-participating whole life policy start at $765.45 at age 60 and increase to $2,070.90 by age 80.

Term life vs whole life insurance costs for seniors

Age (in years) 10-Year Term Life  20-Pay Whole Life
60 $98.33 $765.45
65 $173.03 $950.97
70 $293.40 $1,192.75
75 $557.33 $1,525.53
80 – $2,070.90

Disclaimer: Illustrative monthly premiums for non-smoking male purchasing $250,000 of coverage for a 10-year term life policy and a 20-pay non-participating whole life policy. Actual premiums vary based on different factors.

Which is the cheapest life insurance option for individuals with pre-existing conditions?

Individuals with pre-existing conditions can access affordable life insurance through no-medical plans such as guaranteed-issue or simplified-issue policies. These plans do not require medical exams and offer faster approval, making them accessible to those who may not qualify for traditional or fully underwritten coverage. However, premiums are generally higher than traditional life insurance because insurers assume more risk.

No-medical life insurance policies generally fall into two categories:

  • Guaranteed-issue: Coverage is guaranteed regardless of your health, with no medical exam or health questions. Usually imposes a two-year waiting period for non-accidental death
  • Simplified-issue: Applicants answer a short series of health questions but do not need a medical exam. Depending on the insurer and your health history, coverage may begin immediately or include a deferred benefit period.

Some of the providers offering no-medical exam or guaranteed-issue life insurance in Canada include Manulife, Sun Life, Empire Life, Canada Protection Plan, iA Financial Group, and Assumption Life. Insurers evaluate eligibility based on specific conditions, recency, and severity, which may lead them to decline coverage, impose waiting periods, or apply deferred benefits. Some of the pre-existing conditions that these companies commonly cover include:

  • Diabetes 
  • Heart disease or history of heart surgery
  • Cancer history (recently treated or in remission)
  • Chronic obstructive pulmonary disease (COPD) or other chronic respiratory conditions
  • Mental health conditions such as major depressive disorder or bipolar disorder
  • Liver or kidney disease

What is the cheapest life insurance option for estate planning?

Whole life insurance is generally the most suitable option for estate planning, even though it has higher premiums than term life insurance. That is because estate planning requires lifelong coverage, and whole life insurance guarantees a tax-free death benefit whenever you pass away, provided the policy remains in force. 

It can also build guaranteed cash value, making it a valuable financial planning tool. Compared to renewing multiple term policies later in life, purchasing whole life insurance earlier can provide greater long-term value. Based on PolicyAdvisor’s quote comparisons, some of the companies offering the cheapest options for estate planning include Canada Life, Desjardins, and Sun Life, and a few others.

What is the most affordable life insurance option for smokers?

Smokers can get the most affordable life insurance in Canada with term life insurance. Although smokers pay higher premiums than non-smokers, term life still offers the lowest rates compared with other types of life insurance.

Premiums for smokers reflect the increased health risks and shorter life expectancy associated with tobacco use. For example, a 30-year-old smoker male in average health may pay over $60 per month for a 20-year term life policy with $500,000 in coverage. Alternatively, a non-smoker of the same age would pay around $30 per month for the same policy.

Some of the best life insurance companies, like Foresters, iA Financial Group, Beneva, Wawanesa, and a few other insurers, offer competitive term life policies for smokers. Premiums are higher; however, term life insurance remains the most budget-friendly option for smokers seeking substantial coverage at manageable costs.

Our methodology for the cheapest life insurance in Canada

Our cheapest life insurance rankings are based on quote comparisons run in mid-2026 across our network of more than 30 Canadian life insurance providers. We compared premiums for the three most common ways Canadians buy affordable coverage: term life, whole life, and no-medical life insurance. We also looked at specific groups, including seniors, smokers, people with pre-existing conditions, and buyers focused on estate planning.

We kept coverage amount, term length, smoking status, and gender across all comparisons. Unless stated otherwise, rates are for a healthy, non-smoking male buying $100,000 in coverage. Here is what we compared:

  • Premium affordability by policy type: We compared term life, whole life, and no-medical life insurance to identify the lowest-cost option in each category, and considered coverage duration, cash value, and underwriting requirements when interpreting price differences.
  • Insurer-level quote comparisons: We compared premiums from providers including Beneva, BMO, Canada Life, Foresters, Desjardins, Sun Life, UV Insurance, Assumption Life, and Canada Protection Plan. We identified providers with competitive rates for the specific applicant profiles and policies evaluated, rather than assuming one insurer is cheapest for everyone.
  • Consistency across ages. We favoured insurers that stayed competitive across age groups over those that were cheapest at only one age. This is why Beneva, BMO, and Canada Life are highlighted for term life, and Foresters, Desjardins, and Sun Life for whole life
  • Underwriting and health considerations: We distinguished between traditionally underwritten policies and no-medical options. We also considered how smoking status, pre-existing medical conditions, and eligibility requirements can affect premiums and access to coverage

Tips to get the most affordable life insurance premiums in Canada

Your age and health influence how much you pay for life insurance; there are several ways to reduce your costs. Choosing the right policy, comparing quotes from multiple insurers, and applying while you are healthy can help you secure lower rates without compromising on coverage. 

  • Buy life insurance when you are young: Premiums are lowest when you are younger because you are generally healthier and present a lower risk to insurers. Buying a life insurance policy early can save you money compared with buying it later
  • Compare multiple insurers: Life insurance rates can vary significantly between insurance companies for the same applicant profile. Comparing quotes across the top life insurance companies in Canada helps you find the best coverage at the lowest price
  • Choose the right policy duration: Select a policy duration that matches your financial obligations, such as your mortgage or your children’s dependent years. A shorter term generally costs less than a longer one
  • Consider fully underwritten coverage: If you are in good health, a fully underwritten policy usually offers lower premiums than no-medical life insurance because the insurer can better assess your risk
  • Quit smoking before you apply: Non-smokers pay substantially lower premiums than smokers. Many insurers will offer non-smoker rates once you have been tobacco-free for a qualifying period, typically 12 months
  • Buy only the coverage you need: Choosing an appropriate coverage amount based on your income, debts, and your family’s financial needs helps you avoid paying for unnecessary protection
  • Review your coverage regularly: As your mortgage decreases, children become financially independent, or your income changes, you may be able to adjust your coverage to better match your needs and avoid paying for excess insurance

How much does life insurance cost in Canada?

The cost of life insurance in Canada can start from as low as $7 for a male non-smoker seeking $100,000 for a 10-year term policy. However, your actual premium will depend on factors such as your age, health, smoking status, coverage amount, policy type, and insurer. For a detailed breakdown of life insurance costs by coverage amount, age, policy type, and applicant profile, see our guide to how much life insurance costs in Canada.

Our advisor’s take on cheapest life insurance in Canada

At PolicyAdvisor, our licensed advisors help Canadians compare life insurance quotes from over 30 insurers to find the most affordable coverage based on their age, health, budget, and financial goals. Recently, one of our advisors assisted a 35-year-old father who wanted to protect his family’s finances while keeping his monthly premiums as low as possible.

The client profile

  • Age: 35 years old
  • Coverage required: $500,000
  • Health: Healthy, non-smoking male
  • Primary goal: Affordable coverage to replace income and protect his young family

Our advisor recommendation: 

After comparing quotes from several leading Canadian insurers, we found that Beneva offered the most competitive premium for a 20-year term life policy, with BMO and Canada Life close behind. While whole life insurance would have provided lifelong coverage and cash value, the client only needed protection until his mortgage was paid off and his children became financially independent. Based on those goals, term life insurance quotes from Beneva delivered the best value at the lowest cost.

How to buy affordable life insurance through PolicyAdvisor?

You can apply for the most affordable life insurance in Canada by comparing top insurers and choosing a policy that fits your budget and coverage needs. At PolicyAdvisor, we partner with more than 30 top Canadian insurers, including Manulife, Canada Life, and Sun Life, so you can compare the cheapest rates side by side.

Once you find the right policy, you can apply online instantly or speak with a licensed advisor for personalized support. PolicyAdvisor also provides reliable after-sales assistance, helping you manage your policy after purchase. Schedule a call to get life insurance quotes tailored to your needs today!

Compare life insurance quotes in Canada.

Book a call with our licensed experts now!

Frequently asked questions

What is the cheapest type of life insurance policy?

Term life insurance is the cheapest type of life insurance. Since it only covers you for a set period (like 10 or 20 years) and does not build cash value, premiums are significantly lower than permanent policies.

Is the cheapest life insurance always the best option?

No, the cheapest life insurance policy isn’t always the best choice. While affordability is important, the right policy should also provide enough coverage, match the length of time you need protection, and offer features that suit your financial goals. Choosing the lowest premium without considering your needs could leave you underinsured or paying for a policy that doesn’t provide the benefits you require.

How much does the cheapest life insurance cost in Canada?

The cheapest life insurance in Canada is term life insurance, with premiums starting at around $10 per month for a healthy, non-smoking 20-year-old purchasing $100,000 of 20-year term life insurance. Your actual premium depends on factors such as your age, health, smoking status, coverage amount, and the insurer you choose.

Who qualifies for the cheapest life insurance rates in Canada?

The lowest life insurance premiums are typically available to young, healthy non-smokers with no significant medical conditions or high-risk hobbies. Applicants who purchase coverage at a younger age, maintain a healthy lifestyle, and qualify for fully underwritten policies generally receive the best rates.

Which life insurance company is the cheapest in Canada?

There is no single insurer that is the cheapest for everyone. Beneva, BMO, and Canada Life often offer the lowest term life insurance premiums, while Foresters, Desjardins, and Sun Life are competitively priced for whole life insurance.

Can I switch to a cheaper life insurance policy later?

Yes, you can replace your existing life insurance policy with a cheaper one if you qualify. However, your new premium will be based on your current age and health, so switching isn’t always less expensive. It is best to compare quotes and ensure your new policy is active before cancelling your existing coverage.

Should I choose term life or whole life if I want the lowest premiums?

If your goal is to pay the lowest possible premium, term life insurance is the better choice because it offers temporary coverage at a much lower cost than whole life insurance. However, if you need lifelong protection, guaranteed cash value, or estate planning benefits, paying more for whole life insurance may provide better long-term value.

What is the most expensive life insurance policy in Canada?

Permanent insurance and no medical exam insurance are the most expensive types of insurance policies in Canada. A permanent policy gives you lifelong coverage and a cash value component, which contributes to its higher premiums. You can use this cash value to access growth and build wealth during your lifetime. 

No medical exam insurance helps applicants who may not qualify for fully underwritten coverage. Guaranteed-issue plans accept all eligible applicants, though they usually have a waiting period for non-accidental death. Simplified-issue plans ask health questions and may decline applicants; coverage is not guaranteed. Premiums are higher because insurers take on more risk.

Are there affordable life insurance policies in Canada that offer quick approval?

Yes, no-medical life insurance can offer quicker approval because it may not require a medical exam or lab tests. Simplified-issue policies use a short health questionnaire, while guaranteed-issue policies may require no medical questions but can have lower coverage limits or waiting periods.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Best Term Life Insurance in Canada: Company Reviews and Ratings

Term life insurance is one of the simplest ways to protect the people who depend on you. Whether you want to leave a legacy for your family, cover outstanding debts, or protect your business, the right policy can offer real peace of mind.

Every insurer prices and structures term coverage differently. Our licensed life insurance experts reviewed the top providers in Canada so you can compare your options and choose with confidence.

Term life insurance can be affordable!

Get the best term life insurance quotes in Canada!

Which are the best term life insurance companies in Canada?

The best term life insurance companies in Canada for 2026 are Empire Life, Manulife, RBC Insurance, BMO Insurance, and Canada Protection Plan, standing out for financial strength, fast approvals, and competitive pricing. The right choice depends on your age, health, budget, and specific needs.

Quick glance: Best Canadian term life insurance companies

Here are the top 15 term life insurance companies in Canada and what they’re best known for:

Best term life insurance companies in Canada for 2026

1. Empire Life

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Solution 10, 15, 20, 25, 30 +
Annual Renewable Term (ART)
Avg. cost
Female: $225
Male: $325
AM Best Rating
A
LICAT Ratio
150%
Company overview and financial strength:
Empire Life offers a range of term life insurance options through its Solution series, including Term 10, 15, 20, 25, and 30. These plans provide level-premium coverage with flexible renewal and conversion options to permanent policies. Designed to suit different life stages, they work well for covering financial needs like mortgages, income replacement, or short- to mid-term liabilities.

Unique selling point (USP): Empire Life lets you bundle solution series and critical illness coverage for you and your spouse into a single plan, helping reduce overall costs with just a single policy fee.

Our advisor’s take on Empire Life:

We give Empire Life a solid 5/5 and rate them as the best insurer for personalization. They give you a lot of options to choose from based on what works best for you. Their solution series offers Solution 10, 15, 20, 25, and 30. You can get an annual renewable term that lasts for 1-year increments.

For the first 7 years, you can swap a Solution 10 or 15 for a Solution 20 or 30 without a medical exam. If you decide you want to turn part of your term policy into permanent insurance, Empire now allows you to “carry over” the remaining term balance as a rider on the new policy with no medical evidence.

2. Manulife

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, 20, 30 or to age 65
Avg. cost
Female: $250
Male: $346
AM Best Rating
A
LICAT Ratio
136%
Company overview and financial strength:
Manulife’s term life insurance offers flexible protection through options like Family Term and Family Term with Vitality Plus, designed for both individual and multi-life coverage. These plans provide level premiums (Term 10, 20, 30 or to age 65), high coverage limits, and the ability to insure multiple family members under one policy. Both options include useful features like terminal illness benefits, optional riders, and added support such as bereavement counselling.

Unique selling point (USP): The Manulife Vitality program rewards policyholders for maintaining a healthy lifestyle. With Manulife Vitality, policyholders can get gift cards, discounts, and even an Apple Watch!

Our advisor’s take on Manulife:

We give Manulife 5 stars as well and rate them as the best for digital innovation. This company almost needs no introduction. It’s one of the biggest insurers not just in Canada but in the entire world, an industry leader in every sense.

Manulife was one of the first companies to take the life insurance process online in Canada. Their underwriting uses an advanced AI engine (MAUDE) to approve up to $2 million in life insurance without needing a medical exam.

3. RBC Insurance

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10-40 years (custom)
Avg. cost
Female: $244
Male: $330
AM Best Rating
A
LICAT Ratio
135%
Company overview and financial strength:
RBC’s YourTerm Life Insurance stands out for its high level of customization, allowing you to choose any term length between 10 and 40 years to match your exact financial timeline. It supports high coverage amounts (up to $25 million) and offers the flexibility to layer multiple terms within a single policy, helping you align coverage with different needs like mortgages, loans, or income protection.

Unique selling point (USP): RBC offers some of the best term products on the market at the most affordable premiums. Term exchange lets policyholders exchange a Term 10 policy with a Term 15, 20, or 30 policy without additional medical underwriting.

Our advisor’s take on RBC Insurance:

We give RBC Insurance 5 stars and rate them as the best company if you want value for money. They have some of the most competitive premiums in the Canadian life insurance market. The insurance company allows you to convert YourTerm to permanent insurance up to age 71 without a medical exam.

If a policyholder is diagnosed with a terminal illness (less than 12 months to live), RBC automatically includes a provision allowing you to access a portion of the death benefit early to help with medical or living expenses.

4. BMO Insurance

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, 15, 20, 25, 30 years (fixed)
Avg. cost
Female: $220
Male: $330
AM Best Rating
A
LICAT Ratio
134%
Company overview and financial strength:
BMO’s term life insurance is designed to be simple, structured, and easy to manage, offering fixed terms of 10, 15, 20, 25, and 30 years that align with common financial milestones like mortgages or child-rearing years. Despite its straightforward approach, it provides high coverage limits, guaranteed renewals up to age 85, and the option to convert to permanent insurance. The plan also includes a Term Exchange feature, allowing you to switch to a longer term without additional medical underwriting.

Unique selling point (USP): BMO Insurance includes a Business Guaranteed Insurability Option (a rider not commonly available with most insurers), allowing you to increase coverage as your business grows without additional medical underwriting.

Our advisor’s take on BMO Insurance:

We give BMO Insurance 5 stars and rate them as the best company if you’re looking for value for money. Their term life insurance is a great option for just about anyone, like individuals, couples, or business owners.

By combining the speed of Rovr AI for near-instant approvals with their unique Empathy partnership to support grieving families, BMO provides an ideal term plan that consistently delivers the best “value for money” in the Canadian market.

5. Canada Protection Plan

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Express Elite Term
Simplified Elite Term
Deferred Term
Avg. cost
Female: $315
Male: $405
AM Best Rating
NA
LICAT Ratio
188%
Company overview and financial strength:
Canada Protection Plan focuses on simplified and no-medical term life insurance, offering options like Express Elite Term, Simplified Elite Term, and Deferred Term. These plans are designed for quick approval with minimal or no medical requirements, making them ideal for applicants with health concerns or those seeking hassle-free coverage. While coverage may be lower compared to fully underwritten policies, they provide accessible protection with flexible term options and easy online application.

Unique selling point (USP): The company offers simplified, no-medical coverage for applicants across all health categories. Most products are available through a quick, simple online application without any medical tests.

Our advisor’s take on Canada Protection Plan:

We give Canada Protection Plan 5 stars and rate them as the best provider for No-Medical policies. Express Elite is their best product for healthy individuals who just want to skip the medical visit, while Deferred Term is for those with more serious health histories.

It is easy to get their coverage even if you are considered ‘hard to insure’ by other insurers. They are also known for speed and certainty, delivering approvals in as little as 24-48 hours. The company offers their services to temporary residents, including students and work visa holders.

6. Sun Life

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Evolve Term
Term for Diabetes
Bridge Term
Avg. cost
Female: $270
Male: $380
AM Best Rating
A+
LICAT Ratio
143%
Company overview and financial strength:
Sun Life Evolve Term is a highly flexible term life insurance option designed to adapt as your needs change. It offers customizable coverage with higher limits and the ability to convert to permanent insurance without additional medical underwriting. Compared to the simpler Sun Life Go Term (meant for quick, lower-coverage applications), Evolve Term is better suited for long-term planning. It also offers a wide range of term lengths (choose any term between 5 to 40 years). This makes it easier to align coverage with different obligations like mortgages.

Unique selling point (USP): Sun Life stands out for its extensive product range, high coverage limits, flexible term options, and robust living and rider benefits.

Our advisor’s take on Sun Life:

We give Sun Life Insurance 4.5 stars for long-term flexibility, offering custom term lengths from 5 to 40 years alongside underwriting tailored for those managing diabetes. Sun Life term for Diabetes is a first-of-its-kind product for Canadians with diabetes (type 1, type 2, gestational, or pre-diabetes) offering higher approval chances, and access to a Diabetes Care Program through Diabetes Canada. While Sun Life’s term policies have standard features and optional benefits that can compete in the market, their premiums may cost slightly more than those of some other companies.

7. Assumption Life

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
FlexTerm
Golden Protection Term
Platinum Protection Term
Youth Plus
Avg. cost
Female: $245
Male: $345
AM Best Rating
A-
LICAT Ratio
167%
Company overview and financial strength:
Assumption Life offers flexible term life options such as FlexTerm and Platinum Protection, designed for easy access and straightforward coverage. A key highlight is its strong focus on simplified and no-medical plans, allowing faster approvals with minimal underwriting. These plans are well-suited for those looking for quick, hassle-free protection, with options to cover short- to mid-term financial needs and the ability to convert to permanent coverage later on.

Unique selling point (USP): Assumption Life offers a wide range of non-medical policies designed for those looking to qualify without medical underwriting.

Our advisor’s take on Assumption Life:

We give Assumption Life Insurance Company 4.5 stars and rate them as the best term life insurance provider for Simplified Issue policies. These policies do not ask you to do a medical exam, but may have some simple medical questions on the application. Assumption Life offers 4 different types of non-medical policies, making them a great option for people who may have health issues. You can also get bigger amounts of coverage if you opt for full underwriting.

However, when it comes to claims processing, only 62% of claims were processed within their 5-day target timeframe (industry average: 72%). Also, the policy lacks partial access to death benefits for terminal illness (provided by other competitors), hence the 4.5 rating from our side.

8. Industrial Alliance

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Pick-A-Term
Term 10
Term 20
Term 25
Term 30
Term to 100
Avg. cost
Female: $245
Male: $340
AM Best Rating
A+
LICAT Ratio
134%
Company overview and financial strength:
Industrial Alliance offers highly flexible term life insurance through its Pick-A-Term feature, allowing you to choose a custom coverage duration instead of sticking to fixed terms. Options typically range from 10 to 40 years, with level or decreasing coverage structures to match needs like mortgages or income protection. The plans also include conversion options to permanent insurance and added flexibility in premium structure, making them well-suited for those who want more control over how their coverage is designed.

Unique selling point (USP): Industrial Alliance’s Superior Risk Tolerance Program is designed to offer more flexible underwriting for individuals with complex or higher-risk profiles, something not commonly accommodated across insurers.

Our advisor’s take on Industrial Alliance:

We give Industrial Alliance (iA) 4.5 stars and rate them as the best for flexibility. They’re one of the few insurers that let you customize your term length with their unique Pick-A-Term product. You can pick anywhere between 10 and 40 years for term coverage with iA Financial Group, letting you match your term insurance with any specific number of years, like if you’re using life insurance to cover your mortgage. However, the premium rates may be higher than those of some competitors for similar coverage.

9. Canada Life

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
My Term Life Insurance (Term 5 to 50 years)
Avg. cost
Female: $244
Male: $338
AM Best Rating
A+
LICAT Ratio
130%
Company overview and financial strength:
Canada Life offers a wide range of term life insurance options, including Term 10, Term 20, Term 30, Pick-a-Term, and coverage up to age 65. Its standout feature is flexibility, allowing you to tailor coverage duration and convert to permanent insurance as your needs evolve. With options that support long-term planning, business protection, and family coverage, Canada Life’s term plans are well-suited for those looking for adaptable, future-ready protection across different life stages.

Unique selling point (USP): Canada Life’s SimpleProtect offers a faster, simplified application process with digital-first underwriting, allowing eligible applicants to get coverage quickly with fewer medical requirements compared to traditional policies.

Our advisor’s take on Canada Life:

We give Canada Life Assurance Company 4.5 stars for its financial strength. This is to be expected considering they’re the biggest insurance companies in Canada. They’re extremely stable, and they have great life insurance policy options to boot. However, there is a minimum requirement of $100,000 coverage or a $500 annual premium required. There is also limited access to online account features, and hence the 4.5 star rating.

10. Equitable Life

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, 20 and Term 30/65
Avg. cost
Female: $239
Male: $337
AM Best Rating
A
LICAT Ratio
159%
Company overview and financial strength:
Equitable Life offers flexible term life insurance options including Term 10, Term 20, and coverage up to 30 years or age 65. These plans come with guaranteed renewability up to age 85 and full convertibility to permanent insurance, giving long-term flexibility as your needs evolve. Coverage ranges from $50,000 to over $10 million, and policies can be structured as single life, joint first-to-die, or multi-life, making them suitable for individuals, couples, and families looking for adaptable protection.

Unique selling point (USP): They are great for a strategy called “laddering”, where you only pay for coverage as you need it.

Our advisor’s take on Equitable Life:

We give Equitable Life 4.5 stars and rate them as the best company for families. They make it easy for you to add coverage for multiple people on one policy. This helps families save on fees and put some cash back in their wallets. However, they offer fewer term life insurance options than some competitors. The company is also not AM Best rated, which may affect buyer confidence, hence the 4.5 rating from our side.

11. Beneva

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term Plus (Term10, 15,20,25,30 35,40)
Avg. cost
Female: $225
Male: $330
AM Best Rating
A
LICAT Ratio
163%
Company overview and financial strength:
Beneva primarily offers its Term Plus plan, which is designed for flexibility and customization across different life stages. It provides a wide range of term lengths (typically 10 to 40 years), along with features like guaranteed renewability, conversion to permanent insurance, and the ability to extend coverage without new medical underwriting. A key strength of Term Plus is its built-in flexibility, such as the option to increase coverage as your needs grow and an exchange program that allows you to switch to a longer term without medical evidence.

Unique selling point (USP): Beneva includes an Extreme Disability Benefit (EDB) with eligible life insurance policies, an added layer of protection not commonly bundled by default. It also offers coverage starting as low as $25,000, making insurance more accessible.

Our advisor’s take on Beneva:

We give Beneva Life Insurance 4.5 stars and rate them as the top provider if you want combined coverage. Their insurance products, riders, and features let you get a lot of different types of insurance in one place. Beneva includes an Extreme Disability Benefit for free in all of its life insurance plans (which is rare). The only con is longer turnaround times for policy approval, other than no-medical plans.

12. Desjardins

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, 15, 20, 25, 30, and Term to 65
Avg. cost
Female: $235
Male: $320
AM Best Rating
NA
LICAT Ratio
NA
Company overview and financial strength:
Desjardins offers a range of term life insurance options including 10, 15, 20, 25, and 30 years, as well as coverage up to age 65. These plans come with fixed premiums, guaranteed renewability (typically up to age 85), and full convertibility to permanent insurance without medical evidence. Designed for flexibility, they allow you to adjust coverage as your needs change and are well-suited for covering temporary financial responsibilities like mortgages or family protection.

Unique selling point (USP): As part of the Desjardins Group’s cooperative model, the insurer emphasizes community focus, member dividends, and a values-driven approach rather than a purely shareholder profit model.

Our advisor’s take on Desjardins:

We give Desjardins 4 stars and rate them as the best company for seniors. The company offers a breakthrough senior-focused no-medical product with high acceptance rates. However, Desjardins offers just six fixed-term lengths, whereas some other providers provide fully customizable term durations to better suit individual needs. The rates may not be the most affordable, meaning that Desjardins isn’t always the lowest-cost option for younger, healthy applicants, and hence the 4-star rating from our side.

13. Foresters Financial

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, Term 20, Term 30
Avg. cost
Female: $335
Male: $230
AM Best Rating
A
LICAT Ratio
188%
Company overview and financial strength:

Foresters offers straightforward term life insurance with options like Term 10, 20, and 30, designed for affordable, fixed-premium coverage over a defined period. These plans are renewable and convertible to permanent insurance without additional medical underwriting. A key differentiator is its member benefits model, which includes perks like scholarships, financial counselling, and community programs alongside insurance coverage.

Coverage typically ranges from $50,000 to $5 million, with optional riders such as children’s coverage and charitable benefits, adding extra value beyond standard term plans. Foresters also offers Bereavement Assistance, where beneficiaries may be reimbursed up to $1,000 for counselling services to help them deal with their loss.

Unique selling point (USP): The company is known for its charitable benefit feature. In addition to the death benefit, when a claim is paid to the beneficiaries, Foresters will donate 1% (up to a maximum of $100,000) to the eligible designated charitable organization you choose.

Our advisor’s take on Foresters:

We’ve given Foresters Financial 4 stars and rate them as the best company for their charitable benefits. Many of their products come with a unique perk: a charitable benefit feature where they will donate to a charity of your choice on your behalf. Foresters is also a great choice if you have changing needs. Their term insurance is simple and straightforward, but they also have options that give you better coverage if your needs change in the future and you need insurance to match that.

The plans may come with MyForester member benefits, which include grants, scholarships, access to well-being programs, and more, for policyholders. However, there are digital limitations with no online access to view or manage policy details. It is also not AM Best rated, which may concern some buyers. The prices tend to be higher than those of many competitors, and hence the 4/5 rating from our side.

14. Wawanesa

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10, 15, 20, 25, 30 and a unique term to age 80
Avg. cost
Female: $260
Male: $340
AM Best Rating
A
LICAT Ratio
165%
Company overview and financial strength:
Wawanesa offers term life insurance through its Lifetime Term plans, with flexible options including 10, 15, 20, 25, and 30 years, as well as coverage to age 80 or even age 100. These plans come with level premiums, guaranteed renewability, and the option to convert to permanent insurance without medical evidence. Policies can continue beyond the initial term with renewals and eventually provide lifetime coverage, making it a strong fit for those who want affordable term protection with extended security and flexibility over time.

Unique selling point (USP): Wawanesa uses current-age pricing, meaning your premiums are calculated based on your exact age at the time of application. Unlike some insurers that round your age up if you’re close to your next birthday, Wawanesa prices policies using your actual age, which can help lower costs.

Our advisor’s take on Wawanesa:

We give Wawanesa 4 stars and rate them as the best for their prices. Their premiums are often among the lowest in the industry, and you get your pick of either term policies from 10-30 years or up to age 80. Wawanesa can also be a good option if you want to layer your coverage.

You can get a base term plan, then add up to four term life insurance riders with different term lengths. You can do this all in one policy. The term policies are convertible, but the downside is that they can only be converted into non-participating permanent products.

15. Humania Assurance

☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Term life insurance policies offered
Term 10 to 100
Avg. cost
Female: $245
Male: $345
AM Best Rating
A+
LICAT Ratio
184%
Company overview and financial strength:
Humania Assurance offers flexible term life insurance solutions designed for individuals and families looking for customizable long-term protection. Coverage amounts range from $50,000 to $5 million, with term options extending from 10 years up to age 100. The insurer also allows policy conversion to permanent life insurance before age 65 and offers added flexibility through child coverage without eligibility questions, along with optional critical illness and disability coverage for debt protection.

Unique selling point (USP): Humania stands out for its highly flexible coverage structure, offering term lengths up to age 100 along with built-in family-focused benefits like child coverage without medical questions and optional debt protection add-ons.

Our advisor’s take on Humania Assurance:

We’ve given Humania Assurance 4/5 stars and rate them as the best company for quick-issue policies. Their main term life insurance product is designed for quick approvals. You need to simply answer a few eligibility questions. The policies are also competitively priced. However, the conversion option to permanent life insurance is only available up to age 65. Moreover, the provider is also not AM Best rated, which may concern some buyers, and hence the 4-star rating from our side.

Need help choosing an insurer?

Call us at 1-888-601-9980 or book some time with our licensed experts.

Our methodology: How we ranked the best term life insurance companies in Canada

We evaluated the leading Canadian term life insurance companies across pricing, financial strength, policy flexibility, coverage options, conversion features, underwriting accessibility, and other policy benefits to identify which insurers stand out for different types of Canadians.

Our licensed insurance advisors combine product research with their industry expertise to assess each insurer and explain where each company has an advantage and where it may have limitations.

What we evaluated

We assessed each insurer using the following factors:

1. Premium competitiveness

Price is an important consideration when comparing term life insurance. We compare the premiums across insurers and show the average cost figures available for each provider.

Our current comparison includes separate average premium figures for female and male applicants. For example, the insurers featured on this page currently show representative average costs ranging from approximately $220 to $335 for female applicants and $230 to $405 for male applicants, depending on the insurer and product.

These figures are intended for comparison purposes only. Your actual premium will depend on factors such as your age, health, smoking status, coverage amount, term length, and underwriting results.

2. Financial strength

Because life insurance can remain in force for decades, we consider the financial strength of each insurer.

Where available, we include AM Best financial strength ratings and LICAT ratios for the insurers we review. For example, the insurers on our list include companies with AM Best ratings ranging from A- to A+, while reported LICAT ratios on the page range from 130% to 188% where this information is available.

Financial strength is only one part of our assessment, but it provides useful context when comparing insurers that may be responsible for a future claim many years from now.

3. Term length and coverage flexibility

We examine the range of term options offered by each insurer and whether applicants can customize the length of their coverage.

The companies we review offer a wide range of options, from traditional fixed terms such as 10, 20 and 30 years to highly customizable products. For example, RBC offers custom terms between 10 and 40 years, while Sun Life’s Evolve Term allows applicants to choose a term between 5 and 40 years. Canada Life offers terms ranging from 5 to 50 years through My Term Life Insurance.

This matters because the ideal policy length can depend on your mortgage, family responsibilities, income-replacement needs, or other financial obligations.

4. Conversion and renewal options

We examine whether a term policy can be renewed or converted to permanent life insurance without new medical underwriting, as well as any age limits or other restrictions that apply.

Conversion flexibility can be particularly valuable if your health changes during your term and obtaining a new policy later could become more difficult or expensive.

5. Underwriting and accessibility

Not everyone has the same health history or insurance needs. We therefore consider how insurers accommodate applicants who may have difficulty qualifying for traditionally underwritten coverage.

Our comparison includes insurers offering simplified-issue and no-medical options. For example, Canada Protection Plan offers several simplified and no-medical term products, while Assumption Life offers multiple non-medical options.

We also consider factors such as application requirements, approval speed, and whether an insurer provides digital or streamlined underwriting.

6. Policy features and additional benefits

We look beyond the basic death benefit to identify features that can make one policy more useful than another.

For example, our review highlights features such as Empire Life’s flexible conversion options, Manulife’s Vitality program, RBC’s term exchange options, and Foresters’ charitable benefit.

7. Coverage amounts and product range

We consider how much coverage each insurer makes available and whether its products can accommodate different financial needs.

The insurers reviewed on this page cover a broad range of needs, from simplified-issue policies for applicants seeking easier approval to high-coverage policies designed for family income replacement, mortgage protection, business needs, or estate planning.

For example, RBC offers coverage of up to $25 million, while several other insurers offer coverage in the millions depending on the product and underwriting requirements.

8. Advisor expertise and best-fit analysis

There is no single term life insurance company that is best for every Canadian.

Our licensed insurance advisors therefore assess each insurer based on its strengths and limitations and identify where it may be particularly suitable.

Rather than relying solely on price, we provide an advisor’s take for each insurer and identify specific strengths such as personalization, digital innovation, value for money, no-medical coverage, flexibility, family coverage, or simplified underwriting.

How our rankings work

We use the factors above to determine the relative strengths of the insurers featured on this page.

Our rankings are not based on premium price alone. An insurer with a lower premium may not necessarily be the better choice if another company provides greater flexibility, stronger conversion options, broader coverage, more accessible underwriting, or features that better match a particular applicant’s needs.

This is why our list includes both an overall ranking and “best for” recommendations for specific insurance needs.

Keeping our comparison current

Insurance products, premiums, underwriting rules, and insurer financial information can change over time. We therefore review and update the information on this page as new product, pricing, and insurer information becomes available.

The information presented is based on PolicyAdvisor’s research and analysis and should be used as a comparison resource rather than personalized financial advice. Your eligibility, available coverage, and final premium will depend on your individual circumstances and the insurer’s underwriting decision.

If you’re unsure which insurer or policy is right for you, our licensed insurance advisors can help you compare your options and obtain personalized quotes.

How to choose the best term life insurance company in Canada?

Selecting the right life insurance provider is about much more than just finding the lowest monthly premium. You are entering a contract that could last for decades, so you need to ensure the company will be there when your family needs them most.

Here are the five most critical factors to evaluate when comparing Canadian life insurance companies in 2026:

1. Financial strength and stability

Life insurance is a long-term promise. You must ensure the insurer has the financial backing to pay out a massive claim 20 or 30 years from now.

What to look for: Check their AM Best rating (aim for ‘A’ or ‘A+’) and their LICAT ratio (Life Insurance Capital Adequacy Test). A LICAT ratio well above the minimum required by OSFI (Office of the Superintendent of Financial Institutions) means the company has more than enough capital reserves to absorb severe economic shocks.

2. The “Conversion Privilege” rules

Almost all Canadian term policies allow you to convert your temporary coverage into permanent insurance (like whole life) without undergoing a new medical exam. However, the deadlines vary wildly between carriers.

What to look for: The best companies allow you to convert your policy up to age 71. Budget policies may force you to make this decision by age 65. If you develop a health condition in your late 60s, that 6-year difference could determine whether you can leave an inheritance or lose your coverage entirely.

3. Underwriting flexibility and speed

How much friction are you willing to deal with to get approved?

What to look for: If you are young and healthy, look for companies utilizing “Accelerated Underwriting” (like Manulife or digital-first platforms), which can approve you in 24 hours without needles or doctor visits. If you have pre-existing conditions, look for companies like Canada Protection Plan or Assumption Life that specialize in Simplified Issue (no medical exams) policies.

4. Available riders (Policy Add-ons)

Your policy should be able to adapt to your life’s changing circumstances.

What to look for: Check if the provider offers high-value life insurance riders. Can you add a Child Term Rider to protect all your current and future children under one flat fee? Do they offer a Waiver of Premium rider that pays your insurance bill for you if you become totally disabled?

5. Claims reputation and bereavement support

The absolute worst time for your family to experience poor customer service is immediately after you pass away.

What to look for: Research the company’s claims-payout reputation. Top-tier Canadian providers not only pay valid claims quickly (often within 5 to 10 days) but also offer built-in bereavement counseling, charitable benefit donations, or advance payout provisions for terminal illnesses to help your family navigate the hardest moments.

How to get the best term life insurance in Canada?

You can find the best insurance policies for your needs on PolicyAdvisor. Our advanced AI tools help you instantly compare term life insurance quotes from 30 of Canada’s top insurers, all under 60 seconds! 

Some of the AI tools that we have built and implemented are:

  • An AI-powered life insurance calculator that analyzes your unique profile, such as age, health history,and  lifestyle factors, to generate personalized quotes from top Canadian insurers
  • AI-driven advisor support that assesses sentiment and engagement levels during consultations, helping our licensed experts customize policy suggestions based on individual concerns and preferences
  • An AI-assisted scheduling system automatically assigns the right advisor based on availability and expertise, ensuring our customers are matched with specialists who can address their specific insurance needs efficiently

Prefer personalized guidance? Schedule a free, no-obligation call with one of our licensed advisors. Get answers to all your questions without the pressure of making a hurried decision. 

Get started now and take the first step towards securing your family’s future with PolicyAdvisor!

Need help?

Call us at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

What’s the cheapest life insurance in Canada?

Term life insurance is the cheapest type of insurance policy in Canada. Premiums are lower because coverage is temporary, and the policies don’t have extra options like a savings & investment component, the way whole life insurance does.

Which is the top term life insurance company in Canada?

For term life, the best life insurance companies in Canada are Empire Life, Manulife, RBC, BMO and Canada Protection Plan.

What’s the best amount of life insurance to buy?

You should get enough life insurance to cover your family’s needs. The general rule of thumb is to get 10-12 times your annual income. 

The best way to find out how much life insurance you should buy is to use our life insurance calculator. It will ask you some questions and then tell you the best amount for your needs.

How to get the best quotes for term life insurance?

You can find the best quotes for term life insurance on PolicyAdvisor.com. Our online platform lets you easily customize your plan and compare quotes from leading providers in under a minute.
Can non-residents buy term life insurance in Canada, and what are the requirements?

Yes, non-residents can get term plans in Canada, but eligibility depends on factors like residency status, country of citizenship, and medical history. Most insurers require applicants to be in Canada during the application process and undergo medical underwriting.

Some policies may have additional restrictions for applicants from high-risk countries. Proof of ties to Canada, such as property ownership or financial interests, may also be necessary.

What are the tax implications of life insurance payouts in Canada?

In Canada, life insurance death benefits are tax-free for beneficiaries. However, if the policy has a cash value component, any withdrawals or loans taken against it may be taxable. For business-owned policies, taxation depends on how the proceeds are distributed. Additionally, life insurance can play a role in estate planning, helping to offset potential taxes on assets passed to heirs.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */