Empire Life Term Life Insurance Review (2026)

Empire Life offers a versatile range of term life insurance solutions through its Solution Series, including Solution ART, Solution 10, Solution 20, Solution 25, and Solution 30. Whether you need affordable annual renewable coverage or a longer level-term policy, Empire Life provides flexible options with built-in features such as term exchange and term conversion. The cost of an Empire Life term insurance policy starts at $7.74 per month and can go up to $150.84 per month, depending on factors such as your age, health, smoking status, coverage amount, and selected term.

Quick review

  • PolicyAdvisor ratings: 5/5
  • Best for: Bundling multiple term lengths under one policy
  • Skip if: You want built-in wellness rewards
Term life insurance can be affordable!

Get the best life insurance quotes in Canada!

About Empire Life 

Founded in 1923, Empire Life is one of Canada’s top 10 life insurance companies, offering life insurance, investment products, and employee benefits to individuals, families, and businesses. Headquartered in Kingston, Ontario, the company is known for its strong financial strength, personalized service, and flexible plans. Empire Life serves millions of customers across Canada and is a member of Assuris, which protects eligible Canadian policyholders if an insurer fails.

Empire Life’s financial strength

AM Best Rating A
Insurance Revenue $1.4 billion
LICAT Ratio 150%
Total assets $20.8 billion

What is Empire Life term life insurance?

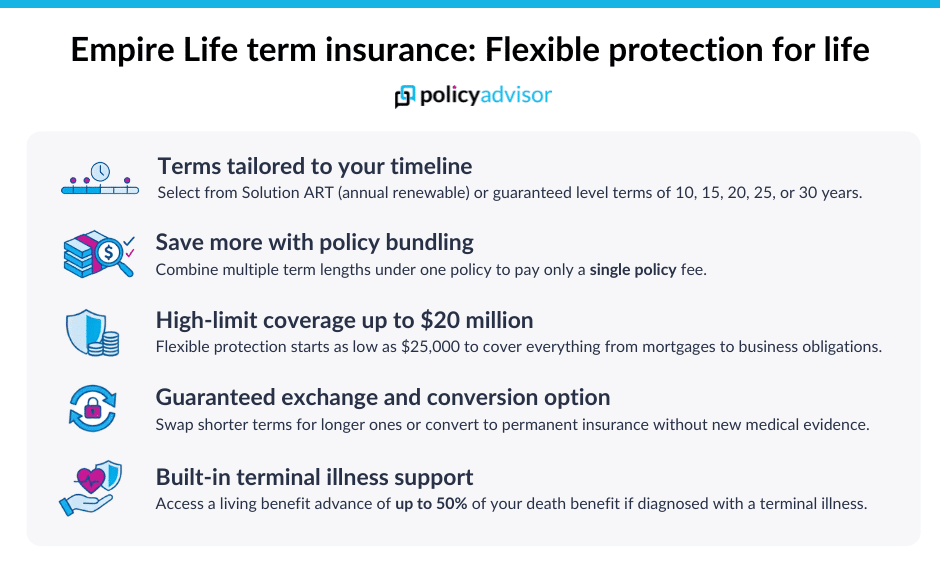
Empire Life term life insurance provides flexible financial protection for a specific period through its Solution Series. You can choose from Solution ART (annual renewable term), Solution 10, Solution 15, Solution 20, Solution 25, and Solution 30, depending on your budget and how long you need coverage. All Solution Series plans are renewable and convertible to eligible permanent life insurance products without additional medical underwriting, making them suitable for protecting mortgages, family income, business obligations, and other temporary financial responsibilities.

The coverage starts at $25,000, with Solution ART offering up to $499,999, and all other Solution Series plans offer up to $20 million in coverage. Unlike many traditional term life insurance policies, Solution Series coverage can continue for life through guaranteed renewals, if premiums continue to be paid. After the policy anniversary nearest age 100, no further premiums are required.

Key features of Empire Life term policy:

Available terms Solution ART, Solution 10, Solution 15, Solution 20, Solution 25, and Solution 30
Policy issue age (min & max)
  • Solution ART: 18-65
  • Solution 10: 18-75
  • Solution 15: 18-70
  • Solution 20: 18-65
  • Solution 25: 18-60
  • Solution 30: 18-55
Coverage duration Lifetime coverage, fully paid up at the policy anniversary nearest to age 100
Coverage range
  • Solution ART: $25,000-$499,999
  • Solution 10, 15, 20, 25 & 30: $25,000-$20,000,000

Note: Applicants aged 66 and older can apply for coverage starting at $10,000

Renewability
  • Solution ART: Level premiums for the first 3 years, then increase annually to age 85 before remaining level to age 100
  • Solution 10, 15, & 20: Level premiums during the initial term. After the initial term, coverage renews for the same term length until the final renewal (after age 75 for Solution 10, age 70 for Solution 15, and age 65 for Solution 20), then premiums remain level to age 100
  • Solution 25 & 30: Level premiums for the initial 25 or 30 years, then increasing annually to age 85 before remaining level to age 100
Term exchange Exchange a shorter term (Solution ART, 10, 15, or 20) for a term at least 10 years longer within the first seven policy years
Convertibility Convertible to eligible Empire Life permanent whole life plan without  additional medical evidence, up to conversion expiry (anniversary nearest to age 75)
Coverage structures
  • Single life
  • Multi-life (2 lives)
  • Joint first-to-die (2 lives)
  • Joint last-to-die (2 lives)
Living benefit advance Up to 50% of the death benefit (maximum $50,000) may be available if the insured is diagnosed with a terminal illness and has a life expectancy of 12 months or less
Riders
  • Waiver of premium
  • Guaranteed insurability
  • Accidental death and dismemberment
  • Children’s life rider
  • Children’s critical illness rider

Who is eligible for Empire Life term life insurance?

To qualify for Empire Life term life insurance, you must meet the insurer’s age, coverage, and underwriting requirements. Eligibility varies slightly depending on the Solution Series plan you choose.

  • Solution ART: Ages 18-65
  • Solution 10: Ages 18-75
  • Solution 15: Ages 18- 70
  • Solution 20: Ages 18-65
  • Solution 25: Ages 18-60
  • Solution 30: Ages 18-55
  • Coverage starts at: $25,000 (applicants aged 66 and older may qualify for coverage starting at $10,000 on eligible plans)
  • Coverage types: Single life, joint first-to-die, joint last-to-die, and multi-life
  • Underwriting: You must satisfy Empire Life’s underwriting requirements, with Preferred and Elite premium classes available on eligible policies with coverage amounts of $1,000,001 or more, subject to underwriting requirements

Types of Empire Life term life insurance plans

Empire Life offers two types of term life insurance under its Solution Series: Solution ART and level term insurance (10, 15, 20, 25 & 30 term lengths). Each option is designed to meet different protection needs, depending on how long you need coverage.

  • Solution ART: Solution ART is an annual renewable term life insurance plan that offers lower initial premiums for short-term protection. The premiums remain level for the first three years, then increase annually until age 85, after which they remain level until the policy is fully paid up at the policy anniversary nearest to age 100. It is well suited for those expecting their insurance needs to change over time or planning to convert to permanent coverage later
  • Solution 10, 15, 20, 25 & 30: Empire Life’s level term plans provide guaranteed level premiums for the initial term you select. Solution 10, Solution 15, and Solution 20 renew for the same term length after the initial term, while Solution 25 and Solution 30 renew annually after their initial term. All plans are renewable and convertible to eligible permanent life insurance without additional medical underwriting. These level term plans are most suited for longer-term financial commitments such as mortgages, raising a family, or business protection
empire life term life insurance

What is covered under Empire Life term insurance?

Empire Life term insurance provides a tax-free lump-sum death benefit to your chosen beneficiaries if you pass away while the policy is in force. The payout can be used for any purpose, helping your family maintain financial stability during a difficult time.

The policy can help cover:

  • Income replacement to support your family’s everyday living expenses
  • Mortgage and debt repayment, including personal loans and lines of credit
  • Education costs for your children or dependents
  • Business obligations, such as business, buy-sell agreements, or key person protection
  • Final expenses

Empire Life term insurance plan also includes a Living Benefit Advance, which may provide up to 50% of the death benefit (maximum $50,000) if you are diagnosed with a terminal illness with a life expectancy of 12 months or less. This allows access to a portion of the death benefit when it may be needed most.

Pros and cons of Empire Life term life insurance

Pros Cons
Offers a wide range of term options, including Solution ART, 10, 15, 20, 25, and 30-year plans No built-in wellness or rewards program
Ability to bundle multiple term lengths under one policy while paying a single policy fee Solution ART premiums increase annually after the first three years
High coverage limits of up to $20 million on eligible Solution Series plans
Includes a non-contractual living benefit advance for eligible terminal illness cases
Fast, digital underwriting process

How much does Empire Life term insurance cost?

Empire Life term life insurance costs for $100,000 coverage and a 10-year term start at $7.74 per month for a 20-year-old female non-smoker and $9.45 per month for a 20-year-old male non-smoker. The actual premium cost may, however, increase based on your age, health history, smoking status, and chosen coverage. 

Cost of Empire Life term life insurance (2026)

Age (in years) Male (non-smoker) Female (non-smoker)
20 $9.45/month $7.74/month
30 $9.90/month $8.19/month
40 $10.89/month $10.08/month
50 $18.99/month $15.75/month
60 $48.96/month $36.36/month
70 $150.84/month $104.04/month

*Illustrative monthly term life insurance cost for male and female non-smoker seeking $100,000 in coverage for 10-year term

How much does Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

What riders are available with Empire Life insurance?

The rider options available with Empire Life term insurance are waiver of premium, payor waiver of premium, guaranteed insurability, accidental death and dismemberment, children’s life rider, and children’s critical illness rider.

  • Waiver of premium rider: If you become totally disabled and meet the policy conditions, Empire Life will waive your future premium payments while keeping your coverage in force. This rider is available if you are aged between 18 and 55 years
  • Guaranteed insurability rider: This rider allows you to increase your life insurance coverage on specified future dates without providing additional medical evidence. It is available for those aged 18 to 40, with coverage increases ranging from $5,000 to the lesser of $50,000 or your total sum insured
  • Accidental death & dismemberment (AD&D) rider: The AD&D rider pays an additional benefit if you die or suffer certain serious injuries due to a covered accident. It can be purchased by those aged 18 to 55; coverage starts at $10,000 and is available up to the lesser of $250,000 or the total sum insured
  • Children’s life rider: This family rider provides life insurance coverage for all eligible children, including future children once they reach 15 days old. It is applicable for children aged 15 days to 17 years; it offers coverage between $1,000 and $25,000
  • Children’s critical illness rider: This family rider provides a lump-sum benefit if an eligible child is diagnosed with one of 15 covered critical illnesses. It covers all eligible children from 30 days old

What is the living benefit advance in Empire Life insurance?

The living benefit advance is a non-contractual benefit offered by Empire Life on eligible life insurance policies. If the insured is diagnosed with a terminal illness and has a life expectancy of 12 months or less, Empire Life may approve an advance payment of up to 50% of the policy’s death benefit, to a maximum of $50,000. The amount paid, along with any applicable interest, is deducted from the death benefit that is later paid to the beneficiaries. Approval is determined on a case-by-case basis.

What is bundling of coverage in Empire Life term policy?

Empire Life allows you to bundle multiple term coverages under a single Solution Series policy, so you can combine different term lengths to match your changing financial needs. 

For example, you might purchase:

  • $500,000 of 20-year term insurance to cover your mortgage
  • $500,000 of 30-year term insurance to replace your family’s income

For the first 20 years, your total coverage would be $1 million. Once the mortgage is paid off, the 20-year coverage ends, leaving you with $500,000 of coverage for the remaining 10 years.

Bundling multiple coverages under one policy can be more cost-effective than purchasing separate policies because only one policy fee applies, reducing overall costs and simplifying policy management. It also gives you the flexibility to maintain different levels of coverage as your financial obligations change over time.

What is term exchange privilege in Empire Life term policy?

Empire Life’s built-in exchange privilege allows eligible policyholders to exchange a shorter term policy for a longer term policy without providing additional medical evidence.  The eligible originating coverages are Solution ART, Solution 10, Solution 15, and Solution 20 and can only be exercised once per coverage.

To qualify, the exchange request must be made before the 7th policy anniversary, the insured must meet the issue age requirements for the new plan, and the new policy must have a term that is at least 10 years longer than the existing one.

Premium rates for the new coverage are calculated using the life insured’s age nearest to the time of the exchange, the rates in effect at that time, and any insurance ratings from the original policy. The new coverage amount can be the same as or lower than the current coverage amount, and because the exchange is treated as a continuation of coverage, the suicide and incontestability periods do not restart.

How does Empire Life term life insurance compare to other providers?

Empire Life stands out for its Solution Series, which includes Solution ART (annual renewable term) and level term options ranging from 10 to 30 years. It also offers flexible features such as bundling multiple term lengths under one policy, a built-in Term Exchange Privilege, a fast underwriting process, and the option to convert eligible policies to permanent life insurance without additional medical evidence. These features make it a strong choice for Canadians seeking customizable, long-term coverage that can adapt to changing financial needs. You can also read our guide on best term life insurance companies in Canada to compare the leading providers.

Our advisor’s take on Empire Life term insurance

One of our advisors recently worked with a 40-year-old homeowner who wanted affordable life insurance to protect a new mortgage while ensuring the flexibility to extend or convert coverage as their financial needs changed over time.

Client profile:

  • Age: 40-year-old non-smoking Canadian
  • Coverage need: $1 million to protect mortgage, replace income, and support young children
  • Primary concern: Flexible term coverage that could adapt to changing financial responsibilities without requiring another medical exam
  • Our comparison: We compared Empire Life’s Solution Series with leading Canadian term life insurers based on premium competitiveness, coverage flexibility, renewal and conversion options, riders, and long-term value. Empire Life stood out for its ability to bundle multiple term lengths under a single policy, along with unique features like the term exchange privilege 

Why we recommended Empire Life term insurance:

  • Offers Solution ART along with 10, 15, 20, 25, and 30-year level term options to suit different protection needs
  • Allows multiple term lengths to be bundled under one policy while charging a single policy fee, helping reduce overall costs
  • Provides guaranteed renewability, conversion to eligible permanent life insurance, and optional riders such as waiver of premium, guaranteed insurability, accidental death & dismemberment, children’s life, and children’s critical illness, making it easy to customize coverage as life changes

How to buy Empire Life term life insurance?

To buy Empire Life term insurance with PolicyAdvisor, here are the steps you need to follow:

  • Our licensed advisors will help you compare Empire Life quotes alongside Canada’s leading life insurance providers to help you find the best value for your needs
  • We assess your budget, financial goals, and coverage requirements to recommend the most suitable Empire Life Solution Series policy
  • Our advisors will guide you through the application process, help you gather the required documents, and assist with any medical underwriting requirements
  • Once your application is approved, our advisors will review your coverage, answer any final questions, and ensure your Empire Life policy is issued smoothly

Ready to get started? Book a free consultation with a PolicyAdvisor expert today and get an Empire Life insurance quote.
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Is Empire Life insurance convertible?

Yes, eligible Empire Life Solution term policies can be converted to eligible Empire Life permanent life insurance products, including EstateMax or Optimax. There is no medical underwriting required to convert to permanent options. The conversion option is available until age 75. 

How much does life insurance from Empire Life cost?

The cost of Empire Life life insurance depends on factors including the insured’s age and lifestyle, coverage amount, and policy term. Typically, the cost for an Empire Life term insurance ranges between $7.74/month and $151/month for non-smokers purchasing $100,000 of 10-year term life insurance coverage.

What is the difference between Solution ART and Solution 20?

Solution ART is an annual renewable term plan with premiums that remain level for the first three years before increasing annually. Solution 20 offers guaranteed level premiums for 20 years, making it a better choice if you want predictable long-term costs.

Can I combine multiple term lengths under one Empire Life policy?

Yes, you can combine multiple term lengths under one Empire Life term policy. Empire Life lets you bundle multiple Solution Series term coverages under a single policy. This allows you to match different financial obligations with different coverage periods while paying only one policy fee.

Does Empire Life offer a living benefit advance?

Yes, Empire Life offers a Living Benefit Advance. It is a non-contractual benefit that may provide up to 50% of the death benefit (maximum $50,000) if the insured is diagnosed with a terminal illness and has a life expectancy of 12 months or less. Approval is determined on a case-by-case basis. Any amount paid, along with applicable interest, is deducted from the death benefit payable to the beneficiaries.

Can I exchange my Empire Life term policy for a longer term?

Yes, you can exchange your Empire Life term policy for a longer term. You can use Empire Life’s term exchange privilege to exchange your existing term policy for a longer-term plan without providing new medical evidence. To qualify, the request must generally be made before the 7th policy anniversary, and the new term must be at least 10 years longer than the current coverage. The insured must also meet the issue age requirements for the new plan, and the new coverage amount must be equal to or lower than the current coverage amount.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Beneva Term Life Insurance Review (2026)

Beneva offers term insurance through its flagship product, Term Plus. It is a flexible term life insurance policy with coverage ranging from $25,000 to $10 million and multiple rider options to enhance the benefits. The cost of Beneva term life insurance starts at $7.83/month and goes up to $150.93/month, the exact cost varying based on age, gender, policy term, coverage amount, and a few other factors. 

Quick review:

  • PolicyAdvisor ratings: 4/5
  • Best for: Built-in Extreme Disability Benefit
  • Skip if: You are looking for a critical illness rider that covers more conditions
Term life insurance can be affordable!

Get the best term life insurance quotes in Canada!

About Beneva 

Beneva is one of Canada’s largest mutual insurance companies, formed through the merger of La Capitale and SSQ Insurance in 2020. With roots spanning more than 80 years, the company serves millions of Canadians through life insurance, health insurance, group benefits, savings, retirement, and investment solutions. Beneva’s Term Plus policy focuses on flexibility, allowing you to combine multiple term lengths and choose between level or decreasing coverage. 

Beneva’s financial strength

AM Best Rating A
Insurance Revenue $4.8 billion
LICAT Ratio 163%
Total assets $29.2 billion

What is Beneva term life insurance?

Beneva Term Plus is a flexible term life insurance policy designed to provide affordable financial protection for individuals, families, business owners, and borrowers. It pays a tax-free death benefit if the insured dies during the policy term and offers coverage amounts ranging from $25,000 to $10 million.

You can choose terms of 10, 15, 20, 25, 30, 35, or 40 years, with the option of either level coverage or decreasing coverage that’s designed for mortgages and other loans. It also comes with a built-in Extreme Disability Benefit rider, which can provide an advance payment of part of the death benefit if the insured experiences a qualifying extreme disability.

Key features of Beneva Term Life Insurance:

Available terms
  • Term Plus: 10, 15, 20, 25, 30, 35, and 40 years
  • Simplified Term: 10 and 20 years
Policy issue age (min & max) Term Plus:

  • T10: 18-75 years
  • T15: 18-70 years
  • T20: 18-65 years
  • T25: 18-60 years
  • T30: 18-55 years
  • T35: 18-50 years
  • T40: 18-45 years

Simplified Term: 

  • T10: 18-70 years
  • T20: 18-60 years
Coverage range Term Plus: $25,000 – $10,000,000

Simplified Term: 

• Ages 18-50: $25,000-$500,000

• Ages 51-60: $25,000-$249,999

• Ages 61-70 (Term 10 only): $25,000-$99,999

Renewability
  • Term Plus: Renewable every 5 years after the initial term, up to age 85
  • Simplified Term: Renewable every 5 years after the initial term, up to age 80, without new evidence of insurability.
Term exchange Available with Term Plus only: Extend to a longer eligible term after the first and before the fifth policy anniversary without new evidence of insurability
Convertibility
  • Term Plus: Convertible to an eligible permanent life insurance plan before age 71, without new evidence of insurability
  • Simplified Term: Convertible only to a Simplified Whole Life insurance plan before age 71, without evidence of insurability.
Underwriting
  • Term Plus: Fully underwritten
  • Simplified Term: Simplified issue (no medical exam required)
Coverage structures
  • Term Plus: Individual or multi-life, or joint-first-to-die (2 to 5 lives)
  • Simplified Term: Individual only
Extreme Disability Benefit Advance payment of up to 50% of your level coverage (or 25% of decreasing coverage), to a maximum of $250,000, if you experience a qualifying extreme disability for 6 consecutive months
Riders
  • Total disability rider 
  • Critical illness rider 
  • Child rider 
  • Waiver of premium in case of total disability
  • Accidental death and dismemberment rider

Who is eligible for Beneva term life insurance?

You may be eligible for Beneva Term Plus if you meet the insurer’s age and underwriting requirements. The key eligibility criteria include:

  • Minimum entry age: 18 years for all term lengths
  • Maximum issue age: Depends on the selected term:
    • Term 10: Up to age 75
    • Term 15: Up to age 70
    • Term 20: Up to age 65
    • Term 25: Up to age 60
    • Term 30: Up to age 55
    • Term 35: Up to age 50
    • Term 40: Up to age 45
  • Coverage amount: Choose between $25,000 and $10 million, subject to underwriting approval
  • Coverage type: Available as individual, multi-life, or joint first-to-die coverage

Beneva also offers a separate Simplified Term Life plan for applicants seeking coverage without a medical exam. It is available in 10- and 20-year terms, offers coverage from $25,000 to $500,000, and has different eligibility requirements, including lower maximum issue ages.

Types of Beneva term life insurance plans

Beneva offers two term life insurance products: Term Plus and Simplified Term Life. Its flagship Term Plus policy can be tailored to different protection needs through a range of coverage options. You can choose individual coverage for one insured person, multi-life coverage for up to six insured persons under a single policy (with a maximum of 20 coverages), or joint first-to-die coverage for two to five insured individuals. 

The policy also lets you select level coverage, where the death benefit remains the same throughout the term, or decreasing coverage, where the death benefit gradually reduces to 50% of the initial amount, making it well suited for mortgages and other declining debts. For even greater flexibility, Beneva allows you to combine different term lengths and coverage amounts within a single Term Plus policy.

Can I get simplified issue plans with Beneva?

Yes, Beneva simplified life insurance is available for those who want a faster application process or may prefer not to undergo a medical exam. However, it comes with lower coverage amounts ($25,000 to $500,000) than the standard Beneva Term Plus policy and does not include the same level of customization or optional riders.

The key features of the simplified term plan include:

  • Approval in as little as 60 minutes for eligible applicants
  • No medical exam required
  • Coverage from $25,000 to $500,000 (maximum coverage depends on the applicant’s age)
  • Renewable every 5 years after the initial term, up to age 80
  • Convertible to an eligible permanent life insurance plan before age 71
  • Does not include additional coverage options or optional riders available with Beneva Term Plus
Beneva term life insurance

What is covered under Beneva life insurance?

Beneva Term Plus provides a tax-free lump-sum death benefit to your beneficiaries if you pass away while the policy is in force. Depending on the coverage options you choose, the policy also includes several built-in benefits and optional protections.

  • Tax-free death benefit: Pays your selected coverage amount (from $25,000 to $10 million) to your beneficiaries if you die during the policy term
  • Conversion privilege: Convert your term policy to an eligible Beneva permanent life insurance policy before age 71 without a medical exam
  • Insurability benefit: Increases your coverage at certain life events without additional medical underwriting, if the benefit is selected when the policy is issued
  • Extreme Disability Benefit coverage: Receive an advance payment of up to 50% of your initial level coverage or 25% of your initial decreasing coverage. The maximum coverage amount under extreme disability rider is $250,000 if you experience a qualifying extreme disability for six consecutive months

Pros and cons of Beneva term life insurance

Pros Cons
It has coverage starting as low as $25,000 Simplified Term Life offers no optional riders and is available only as individual coverage
Built-in Extreme Disability Benefit (EDB) Critical illness rider is limited to three covered conditions (cancer, heart attack, and stroke)
Term Plus offers 7 term lengths (10, 15, 20, 25, 30, 35, and 40 years) to suit different financial needs
Available as individual, multi-life, or joint first-to-die coverage
Choose between level and decreasing coverage, with the option to combine multiple terms under one policy
Exchange to a longer eligible term within the first five policy years without providing new evidence of insurability

How much does Beneva term life insurance cost?

The cost of Beneva Term Plus starts at $7.83 per month for a 20-year-old female non-smoker and $9.45 per month for a 20-year-old male non-smoker purchasing a $100,000, 10-year term policy. Your premium will vary based on factors such as your age, gender, smoking status, health, coverage amount, and selected policy term. The table below shows illustrative monthly premiums across different age groups.

Cost of Beneva term life insurance (2026)

Age (in years) Male (non-smoker) Female (non-smoker)
20 $9.45/month $7.83/month
30 $9.90/month $8.55/month
40 $11.16/month $10.35/month
50 $18.99/month $15.93/month
60 $48.96/month $36.36/month
70 $150.93/month $104.04/month

*Illustrative term life insurance cost for male and female non-smokers purchasing $100,000 in coverage for a 10-year term

How much does term life insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

What are the riders available with Beneva life insurance?

Beneva Term Plus riders include disability rider, critical illness rider, child rider, accidental death & dismemberment (AD&D), waiver of premium, and fracture benefit riders. These optional add-ons allow you to customize your policy with extra protection based on your financial needs and life stage.

  • Disability rider: Provides a monthly disability benefit if you become totally disabled and are unable to work, helping you replace income while you are unable to work. Available to those aged 18 to 60, the rider offers monthly benefits from $300 to $3,500 (subject to policy limits) and includes built-in medical assistance services, such as second medical opinions and referrals
  • Critical illness rider: Pays a $20,000 lump-sum benefit if you are diagnosed with cancer, severe heart attack, or stroke and survive the required 30-day waiting period. The rider is available to applicants aged 18 to 60 and includes access to medical assistance services.
  • Child rider: Provides life insurance coverage for all eligible dependent children from 15 days old to age 25, with coverage ranging from $5,000 to $25,000 per child. It also offers the option to convert to permanent life insurance without evidence of insurability, subject to policy limits
  • Accidental death & dismemberment (AD&D) rider: Pays an additional benefit if death or certain serious injuries result from a covered accident. Benefits can be up to 100% of the insured amount for accidental death, the loss of two limbs, or permanent paralysis, with coverage available up to $500,000
  • Waiver of premium rider: Waives eligible policy premiums if you become totally disabled for the required waiting period, allowing your Term Plus coverage to remain in force without additional premium payments during the disability
  • Fracture benefit rider: Pays a lump-sum benefit if you suffer a covered accidental fracture or severance. Depending on the severity and type of fracture, benefits range from $750 to $5,000, provided the injury is diagnosed within 30 days of the accident

What is Beneva’s extreme disability benefit rider?

The extreme disability benefit is a built-in feature of Beneva Term Plus that allows eligible policyholders to receive an advance payment of a portion of their death benefit if they experience a qualifying state of extreme disability. This benefit is designed to help cover medical expenses or other financial needs while the insured is still living.

Some of the things to know about the extreme disability benefit rider are as follows:

  • You must be under age 60 at the time of claim
  • You must have been in a qualifying state of extreme disability for at least six consecutive months
  • You may receive an advance payment up to 50% of the initial coverage amount for level coverage, or 25% for the initial decreasing coverage
  • The maximum advance payment is $250,000
  • Any amount paid under this benefit is deducted from the death benefit ultimately paid to your beneficiaries

Does Beneva’s child rider include newborn coverage?

Yes, Beneva’s Child Rider includes an Automatic Newborn Benefit. This provides coverage for children born after the rider takes effect. Newborns are automatically covered from 15 days after birth or from the date they are discharged from the hospital, whichever is later, with no additional premium required for this protection. This feature gives growing families immediate life insurance coverage for eligible newborn children without the need to purchase a separate policy right away.

What is fracture benefit offered under Beneval life insurance?

The benefit in case of fracture rider provides a lump-sum payment if you suffer a covered accidental fracture or severance. It is available to those aged 18 to 60. This benefit pays $5,000 for severe fractures involving the skull, spine, pelvis, or femur, $1,500 for fractures of bones such as the radius, humerus, tibia, or fibula, and $750 for other eligible bone fractures. To qualify, the fracture or severance must be diagnosed within 30 days of the accident.

Can I exchange my Beneva term life insurance policy?

Yes, Beneva allows eligible Term Plus and Simplified Term Life policyholders to exchange their existing policy for a longer eligible term without providing new medical evidence. For Term Plus, the exchange must be requested after the first policy anniversary and before the policy anniversary nearest the insured’s 60th birthday. The new policy cannot have a higher coverage amount than the original policy.

The available exchange options for Term Plus include:

  • Term 10 → T15, T20, T25, T30, T35, T40
  • Term 15 → T20, T25, T30, T35, T40
  • Term 20 → T25, T30, T35, T40
  • Term 25 → T30, T35, T40
  • Term 30 → T35, T40
  • Term 35 → T40

How does Beneva term life insurance compare to other providers?

Beneva Term Plus stands out for its flexible policy design, offering term lengths from 10 to 40 years, level or decreasing coverage, and the ability to combine multiple terms under a single policy. It also includes unique features such as a built-in Extreme Disability Benefit, an insurability benefit, policy exchange options, and coverage structures like individual, multi-life, and joint first-to-die, making it a strong choice for families, homeowners, and business owners seeking customizable protection. However, it’s worth comparing quotes, features, and pricing from multiple insurers before making a decision. 

Read our guide to the best term life insurance companies in Canada to compare the leading providers side by side.

Our advisor’s take on Beneva term life insurance

One of our advisors recently assisted a 42-year-old father of two who wanted affordable life insurance to protect his family’s mortgage and future education costs while keeping the option to increase coverage later without another medical exam.

Client profile:

  • Age: 42-year-old non-smoking Canadian
  • Coverage need: $750,000 to replace income and cover long-term family expenses
  • Primary concern: Finding flexible term coverage with future conversion options and valuable built-in benefits
  • Our comparison: We compared Beneva Term Plus with several leading Canadian insurers based on coverage flexibility, term lengths, conversion options, riders, and long-term value. Beneva’s term plan stood out for its ability to combine multiple term lengths under one policy, to offer both level and decreasing coverage, and to provide other features.

Why we recommended Beneva Term Plus:

  • Offers term lengths from 10 to 40 years with the flexibility to combine multiple terms under one policy
  • Includes guaranteed renewability, conversion to permanent insurance, and a term exchange option without new medical evidence (subject to eligibility)
  • Provides a built-in Extreme Disability Benefit, a feature not commonly available with many Canadian term life insurance policies
  • Supports individual, multi-life, and joint first-to-die coverage with optional riders such as total disability rider, child rider, AD&D, and waiver of premium, allowing the policy to adapt to changing family needs

How to buy Beneva term life insurance?

Buying Beneva term life insurance through PolicyAdvisor is simple and quick. Here are the steps you need to follow to buy Beneva life insurance with us:

  • Compare quotes online: Our licensed advisors will help you compare Beneva life insurance quotes with policies from Canada’s top life insurance companies
  • Assess your needs: Our experts assess your coverage needs, budget, and long-term goals to recommend the most suitable policy
  • Complete your application: We will help you complete the application, gather the required documents, and guide you through any underwriting requirements
  • Review and approve your policy: Once your application is approved, our advisors will review your coverage details with you before your policy is issued

So, why delay? Schedule a call today to buy Beneva term life insurance with us today!

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

What is the extreme disability benefit in Beneva life insurance?

Beneva’s extreme disability benefit is a built-in feature that provides an advance of up to 50% of the initial level coverage (or 25% of the initial decreasing coverage), to a maximum of $250,000. This is applicable if the insured requires assistance with basic daily activities for at least 6 consecutive months. Any amount paid is deducted from the policy’s death benefit.

Can I convert my Beneva term life insurance to permanent life insurance?

Yes, Beneva allows Term Plus policyholders to convert their term life insurance into an eligible permanent life insurance policy before age 71, without providing new medical evidence. This feature is valuable if your insurance needs change over time, such as when you want lifelong coverage for estate planning, final expenses, or leaving an inheritance.

Does Beneva require a medical exam for term life insurance?

Beneva does not always require a medical exam for term life insurance. Beneva also offers simplified issue term life insurance options. For the standard Term Plus policy, you may be asked to complete medical underwriting depending on factors such as your age, health, and the amount of coverage you apply for. However, Beneva also offers a Simplified Term Life Insurance plan that requires no medical exam and may provide approval in as little as 60 minutes for eligible applicants, but with a lower coverage amount of up to $500,000.

Does Beneva offer joint term life insurance?

Yes, Beneva offers Joint First-to-Die coverage. This coverage option allows 2 to 5 people to be insured under a single policy. The death benefit is paid when the first insured person passes away, making this option popular for couples, business partners, and families with shared financial obligations.

Is Beneva Term Plus a good choice for families?

Yes, Beneva Term Plus can be a strong option for families. It is ideal for families seeking flexible, customizable life insurance. It offers coverage from $25,000 to $10 million, multiple term lengths, joint and multi-life coverage options, and valuable features such as conversion to permanent insurance and an Extreme Disability Benefit. Families can also enhance their protection by adding optional riders, including child rider, total disability rider, and an accidental death and dismemberment rider, helping ensure the policy adapts as their needs change.

Does Beneva offer decreasing term life insurance?

Yes, Beneva offers decreasing term life insurance. In addition to traditional level term coverage, Beneva offers decreasing term life insurance, where the death benefit gradually reduces over time until it reaches 50% of the original coverage amount. This type of coverage is designed primarily for financial obligations that decrease over time, such as mortgages or personal loans.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

RBC Life Insurance Review (2026)

RBC’s term life insurance offers YourTerm and Simplified Term, two policies that provide customizable term lengths, guaranteed renewability, and conversion to permanent life insurance without a medical exam. They provide flexible coverage ranging from $100,000 to $25 million, with customizable term lengths from 10 to 40 years in one-year increments and several optional riders to enhance protection. 

The cost of a YourTerm term policy from RBC ranges between $9.36 and $180.99, depending on your age, gender, health, smoking status, coverage amount, selected term, underwriting class, and other related factors.

Quick review

  • PolicyAdvisor ratings: 5/5
  • Best for: Individuals seeking a flexible policy with customizable term lengths and high coverage amounts
  • Skip if: You are looking for the cheapest term life insurance premium rather than flexible policy features
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

About RBC Life Insurance

RBC Insurance is the insurance division of the Royal Bank of Canada (RBC), one of Canada’s largest financial institutions. Operating since the 1960s, the insurer offers a broad range of insurance solutions, including life, critical illness, disability, and travel insurance, as well as creditor protection products.

The life insurance portfolio of RBC Insurance includes both term and permanent coverage, allowing Canadians to choose policies that match different life stages, budgets, and financial goals. With the backing of the historic Royal Bank of Canada, it is one of the more popular insurers in Canada.

RBC Insurance’s financial strength

AM Best Rating A
Insurance Revenue $2.3B
LICAT Ratio 135%
Total assets $28.6B

What is RBC Insurance term life insurance?

RBC YourTerm is a renewable and convertible term life insurance policy that provides financial protection for a selected period. If the policyholder passes away while the policy is active, RBC Insurance pays the policy’s death benefit to the named beneficiary, subject to the terms and conditions.

Unlike permanent life insurance, RBC term life insurance focuses solely on financial protection for the beneficiaries. The policy does not accumulate cash value or pay policy dividends. The death benefit is usually paid out tax-free and can be used to pay off debts and other financial obligations.

Key features of RBC Insurance term life insurance

Term product name
  • YourTerm Life Insurance 
  • Simplified Term Life Insurance
Term length options
  • YourTerm: 10 to 40 years
  • Simplified: Fixed term options
Policy issue age
  • Term 10–15: Age 18–70
  • Term 16–40: 85 minus the selected term
Coverage range YourTerm: 

$100,000 to $25 million (higher amounts available by special quote)

Simplified: 

Ages 18–55: $50,000 to $1 million

Ages 56+: $50,000 to $499,999

Renewability Guaranteed renewable without evidence of insurability. After the initial term, coverage renews automatically with guaranteed renewal rates as long as premiums are paid.
Term exchange Yes, available for YourTerm
Convertibility Convertible to eligible RBC permanent life insurance before the policy anniversary nearest age 71, without evidence of insurability (For YourTerm only)
Underwriting
  • YourTerm: Fully underwritten policies
  • Simplified: Medical exam may not be required
Coverage structures
  • YourTerm: Available as single life and joint first-to-die 
  • Simplified: Single Life only
Premiums
  • Guaranteed for each term and renewal period
  • Premiums stop at the policy anniversary nearest age 100 while coverage continues
Riders (For YourTerm only)
  • RBC YourTerm rider
  • Children’s term rider
  • Accidental death benefit rider
  • Total disability waiver of premium benefit rider
  • Payor death and disability waiver of premium benefit rider

Who is eligible for RBC Insurance term life insurance in Canada?

RBC term life insurance is available to Canadian residents who meet the insurer’s age and underwriting requirements. Eligibility depends on the term length selected and your ability to satisfy RBC’s underwriting criteria.

To qualify for RBC term life insurance, applicants must:

  • Be 18 to 70 years old for Terms 10–15.
  • Meet the maximum issue age requirement for Terms 16–40 (calculated as 85 minus the selected term)
  • Meet RBC Insurance’s underwriting requirements, which may include completing a health and lifestyle questionnaire
  • Provide additional evidence of insurability, such as a medical exam or other underwriting requirements, depending on their age and the amount of coverage requested

Types of RBC Insurance term insurance plans

RBC offers the RBC YourTerm Life Insurance, which is designed for individuals and families seeking higher life insurance coverage and greater flexibility. It offers customizable term lengths, higher coverage limits, and valuable features such as guaranteed renewability and convertibility.

Within the YourTerm life insurance policy, applicants have two coverage options:

  • Single Life
  • Joint First-to-Die

Here’s a quick overview of the YourTerm term insurance plan by RBC Insurance:

Feature RBC YourTerm Life Insurance
Coverage amount (ages 18–55) $100,000–$25 million (higher amounts available by special quote)
Underwriting Fully underwritten
Renewability Guaranteed renewable without evidence of insurability. After the initial term, the policy renews annually with guaranteed renewal rates, provided premiums are paid.
Term length options Flexible terms from 10 to 40 years, including (Available in one-year increments)
Review period 10-day free look with full refund
Coverage options Single Life and Joint First-to-Die

RBC Insurance also offers a Simplified Term Life Insurance policy for individuals seeking coverage without extensive medical underwriting. However, this plan offers less flexibility and is more expensive than YourTerm policies. For applicants seeking broader coverage and more term choices, RBC YourTerm Life insurance is usually the more comprehensive option.

What is covered under RBC term life insurance?

RBC offers two term life insurance plans, each designed to provide a tax-free lump-sum death benefit to your beneficiaries if you pass away while the policy is in force. While both plans provide financial security for your loved ones, they offer different features and benefits, such as accidental death benefits, flexible term lengths, and more.

Here’s a brief overview of the major offerings of both term life plans by RBC Insurance:

  • Tax-free death benefit: Your beneficiary receives a tax-free lump-sum death benefit if you pass away while your RBC YourTerm or Simplified Term policy is in force.
  • Renewable coverage: Both YourTerm and Simplified Term provide guaranteed renewable coverage without requiring new evidence of insurability. YourTerm renews annually after the initial term, with premiums increasing according to the guaranteed renewal schedule
  • Term exchange option: Eligible RBC term policies can be exchanged for a longer term without new medical evidence during the applicable exchange period
  • Optional coverages: RBC YourTerm can be customized with riders such as the Children’s Term Rider, Accidental Death Benefit Rider, and the Total Disability Waiver of Premium Benefit Rider 

Pros and Cons of RBC Term Life Insurance

Pros:
Choose any term from 10 to 40 years
Coverage available up to $25 million, with larger amounts available by special quote
Convertible to eligible RBC permanent life insurance before age 71 without a medical exam
Five underwriting classes, including Preferred Smoker and Optimum Non-Smoker
RBC YourTerm offers several optional riders and joint first-to-die coverage
Cons:
Renewal premiums increase annually after the initial term expires
Conversion privilege ends at the policy anniversary nearest age 71
RBC Simplified Term offers fewer coverage options and policy features than RBC YouTerm

How much does RBC Insurance term life insurance cost?

The monthly cost of RBC term life insurance ranges between $9.36 and $180.99 for the sample policy shown below. Your premiums depend on the coverage amount and personal factors, such as gender, age, smoking status, and health. 

Here is a sample term life insurance rate for $100,000 in coverage for a 10-year term:

Age (in years) Male (non-smoker) Female (non-smoker)
20 $10.98 $9.36
30 $11.25 $8.91
40 $13.41 $11.79
50 $22.68 $18.14
60 $62.10 $42.75
70 $180.99 $134.01

How much does Term Life Insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

RBC Term life insurance payment options and lapse protection

In terms of premium payments, RBC insurance offers the following payment options:

  • Monthly pre-authorized debit (PAD)
  • Annual premium payments

Additionally, if a premium is not paid when due, RBC provides a 31-day grace period during which the policy generally remains in force. However, if your policy lapses, the insurer also provides an option for reinstatement, subject to the following terms:

  • You may be able to reinstate it within two years of the lapse date
  • Provide satisfactory evidence of insurability
  • Pay outstanding premiums and any applicable interest

What riders are available with RBC Insurance term life insurance?

RBC YourTerm can be customized with several optional riders to enhance your coverage based on your personal or family needs. Policyholders can choose from the Children’s Term Rider, Accidental Death Benefit Rider, Total Disability Waiver of Premium Benefit Rider, and Payor Death and Disability Waiver of Premium Benefit Rider.

Here’s a quick overview of each rider available with RBC term life insurance:

Rider What it covers Eligibility / Coverage
RBC YourTerm Rider 
  • Adds renewable and convertible term life insurance to an eligible RBC life insurance policy without a separate policy fee
  • Can cover the base insured or a second person as single-life or joint-life coverage 
  • Available on eligible RBC life insurance plans
  • Coverage becomes paid-up at the policy anniversary nearest age 100
  • YourTerm 10 riders can be exchanged to YourTerm 15, 20, or 30 riders
Children’s Term Rider
  • Provides term life insurance for eligible natural or legally adopted children
  • Each child can convert to permanent insurance without medical evidence (up to 10× rider coverage, max. $150,000) 
  • Issue age: 14 days–20 years
  • Coverage: $5,000–$30,000 per child
  • Expires: Policy anniversary nearest child’s 25th birthday
Accidental Death Benefit Rider Pays an additional death benefit if the insured dies due to a covered accident within 90 days of the accident
  • Issue age: 18–60
  • Coverage: Lesser of sum insured and $250,000
  • Expires: Policy anniversary nearest age 65
Total Disability Waiver of Premium Benefit Rider Waives premiums for the base policy, riders, and policy fee if the insured becomes totally disabled for six consecutive months and remains disabled.
  • Issue age: 18–55
  • Expires: Policy anniversary nearest age 60
Payor Death and Disability Waiver of Premium Benefit Rider Waives policy, rider, and policy fee premiums if the premium payor becomes totally disabled for six consecutive months or dies
  • Available when someone other than the insured pays the premiums
  • Expires: Policy anniversary nearest the payor’s age 60

RBC life insurance riders

RBC term life insurance underwriting and premium classes 

One of RBC’s biggest strengths is its flexible underwriting structure, which makes it a popular choice for a wide range of applicants. Instead of offering only standard smoker and non-smoker rates, the insurer offers five premium classes, allowing healthier applicants to qualify for lower premiums.

Here’s a brief overview of the different premium classes available to applicants under RBC term life insurance:

Premium class Who qualifies?
Optimum Non-Smoker Applicants with exceptional health and lifestyle habits, including no tobacco or nicotine use in the past 24 months, excellent blood pressure and cholesterol levels, and a favourable personal and family medical history
Preferred Non-Smoker Healthy non-smokers with no tobacco or nicotine use in the past 12 months and above-average health and lifestyle
Standard Non-Smoker Non-smokers with average health and lifestyle profiles
Preferred Smoker Tobacco users with otherwise favourable health and lifestyle characteristics
Standard Smoker Tobacco users with average health and lifestyle profiles

Can you convert RBC YourTerm to permanent life insurance? 

Yes, one of RBC YourTerm’s biggest advantages is its guaranteed conversion privilege, which allows eligible policyholders to convert some or all of their term coverage to an eligible RBC permanent life insurance policy without providing new medical evidence of insurability.

For example, if you are diagnosed with a medical condition during your term, you may still be able to convert your coverage to permanent life insurance before the deadline without undergoing another medical exam or qualifying under new underwriting requirements.

Here’s an overview of the conversion feature of RBC term life insurance:

Feature Details
Medical exam required? No, you can convert without providing new evidence of insurability
What can be converted? All or part of the policy’s death benefit
Conversion deadline
  • Before the policy anniversary nearest the insured’s 71st birthday
  • For Joint First-to-Die policies, conversion must occur before the oldest insured reaches this limit
Eligible permanent policies Any permanent RBC life insurance plan available for conversion at the time 

RBC Growth Insurance, RBC Growth Insurance Plus, RBC Universal Life, and Term 100 (subject to product availability).

Premium requirement All premiums must be paid up to the conversion date
Full conversion The original term policy ends when the new permanent policy takes effect.
Partial conversion
  • You can convert part of your coverage to an eligible permanent policy
  • Under RBC’s Term Partial Conversion and Carryover option, the remaining term coverage may be carried over as a new RBC YourTerm rider on the permanent policy without evidence of insurability

Can you exchange your RBC term life insurance policy?

Yes, you can exchange your RBC term life insurance policy under certain circumstances. If you purchase an eligible RBC YourTerm 10 policy, you can exchange it for a longer eligible RBC YourTerm policy without providing new medical evidence. This allows policyholders to extend their level-premium period after purchasing the original policy.

The exchange must take place before the earlier of:

  • The fifth policy anniversary, or
  • The policy anniversary nearest the insured’s:
    • 70th birthday (to exchange to Term 15)
    • 65th birthday (to exchange to Term 20)
    • 55th birthday (to exchange to Term 30)

Can you increase or decrease your coverage?

Yes, RBC term life insurance offers flexibility even after the policy is issued. The change is subject to the policy terms and administrative rules:

  • Increase your coverage: You can apply to increase your death benefit in minimum increments of $50,000. Each increase requires new evidence of insurability and is treated as additional coverage with its own premium and coverage date.
  • Decrease your coverage: You can reduce your death benefit at any time in minimum increments of $10,000, provided your premiums are up to date, and the remaining coverage meets RBC’s minimum requirements.
More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

How does RBC Insurance compare to other insurance providers?

RBC YourTerm Life Insurance stands out for the flexibility of its term lengths, high coverage limits, and comprehensive underwriting options. RBC YourTerm offers fully underwritten coverage from $100,000 to $25 million, with applicants able to choose any term from 10 to 40 years in one-year increments. It also provides guaranteed renewability, conversion to eligible permanent coverage, and a term exchange option for eligible policies. 

Meanwhile, RBC Simplified Term Life Insurance offers a streamlined underwriting alternative for applicants seeking a simpler application process with fewer underwriting requirements than YourTerm. Paired with renewable and convertible coverage, RBC’s term insurance options are well suited for homeowners, growing families, professionals, and business owners seeking flexible coverage and multiple benefits.

Read our guide to the best term life insurance companies in Canada to compare leading insurers side by side.

Our advisor’s take on RBC term life insurance

At PolicyAdvisor, we recently helped a 38-year-old homeowner secure RBC YourTerm Life Insurance to protect their family’s finances while paying off a long-term mortgage. They were seeking flexible coverage that could adapt as their needs changed, alongside an option to convert to permanent life insurance later without undergoing another medical exam.

Client profile

  • Age: 38
  • Family: Married with one child
  • Primary concern: Mortgage protection and income replacement
  • Coverage goal: $1.5 million in flexible term life insurance

Why we recommended RBC YourTerm Life Insurance

  • Flexible 25-year term that closely matched the client’s remaining mortgage period
  • Guaranteed conversion privilege, allowing them to switch to permanent life insurance later without new medical evidence if their long-term needs change
  • Guaranteed renewal if they need coverage beyond the initial term
  • Option to increase or decrease coverage in the future as their financial obligations evolve
  • High coverage limits that comfortably meet the family’s income replacement and debt protection needs

How to purchase RBC insurance term life insurance in Canada

PolicyAdvisor’s licensed life insurance advisors can help you compare different term life policies offered by RBC Insurance based on your age, budget, health, coverage needs, and financial goals.

Whether you are looking to protect your family, cover your mortgage, or secure affordable coverage for a specific period, our advisors at PolicyAdvisor can help you choose the right term length, coverage amount, and optional riders to fit your needs.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently Asked Questions

How much coverage can I get with RBC YourTerm?

RBC YourTerm offers coverage amounts from $100,000 to $25 million, with higher coverage available by special quote.

What policy terms does RBC YourTerm offer?

RBC YourTerm term life insurance allows applicants to choose any term length between 10 and 40 years in one-year increments.

Is RBC YourTerm available for couples?

Yes, RBC offers joint first-to-die coverage as Joint First-to-Die coverage. This option pays the death benefit when the first insured person dies and includes survivor conversion privileges for eligible policies.

Can I convert RBC YourTerm to permanent life insurance?

Yes, eligible RBC YourTerm policies can be converted to an eligible RBC permanent life insurance policy without providing new evidence of insurability before the policy anniversary nearest the insured’s 71st birthday. Partial conversions may also be available, subject to RBC’s policy rules.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Canada Life Term Life Insurance Review (2026)

Canada Life term life insurance plan comes with coverage starting at $100,000. There is no stated maximum base coverage amount, but a special quote is required for coverage exceeding $25,000,000. With multiple riders and coverage options available, the My Term plan offers flexibility to match your term life insurance needs. 

Quick review

  • PolicyAdvisor ratings: 5/5
  • Best for: Business owners and individuals who require high term life insurance coverage for income replacement, estate planning, or business protection
  • Skip if: Those who want multi-life coverage (more than 2 insured under one policy)
Term life insurance can be affordable!

Get the best term life insurance quotes in Canada.

About Canada Life 

Canada Life is one of Canada’s largest and oldest insurance providers, with over 175 years of experience helping individuals, families, and businesses protect their financial future. Today, it serves millions of Canadians through a broad range of life insurance, health insurance, retirement, investment, and wealth management solutions. Known for its strong financial strength, flexible products, and nationwide advisor network, Canada Life remains a trusted choice for long-term financial protection.

Canada Life’s financial strength

AM Best Rating A+
Insurance Revenue $21.0 billion
LICAT Ratio 130%
Total assets $461.2 billion

What is Canada Life term life insurance?

Canada Life term insurance is a temporary life insurance policy that provides affordable financial protection for a fixed period, 5 to 50 years. If the insured person passes away during the selected term, the policy pays a tax-free lump-sum death benefit to their beneficiaries. 

The death benefit can be used to replace lost income, pay off outstanding debts such as a mortgage or loans, cover children’s education expenses, or meet other financial obligations. The plan also offers flexible renewal and conversion options, allowing policyholders to extend coverage or convert to permanent life insurance without a medical exam before the policy anniversary nearest age 70.

Key features of Canada Life term life insurance

Term product name My Term Life Insurance
Term length options 5 to 50 years
Policy issue age Min. age: 15 years (smokers) & 18 years (non-smokers)

Max. age: 85 years

Coverage range $100,000 minimum; no stated maximum base coverage amount (special quote required for coverage over $25 million)
Renewability Guaranteed annual renewal without medical evidence, up to the policy anniversary nearest age 85
Term-to-term conversion Yes, available (new term must be at least 10 years longer; eligibility requirements apply)
Convertibility Convertible to eligible permanent life insurance without new medical evidence before the policy anniversary nearest the insured person’s 70th birthday
Coverage structures Single life, Joint first-to-die (up to 2 insureds)
Premiums
  • Guaranteed level premiums for the initial term
  • Renewal premiums increase yearly but remain guaranteed
Riders
  • Accidental death benefit
  • Child’s term life rider
  • Disability waiver of premium 
  • Guaranteed insurability rider
  • Business growth protection rider

Who is eligible for Canada Life term life insurance?

Canada Life My Term Life Insurance is available for the following:

  • Applicants aged 15 and older (or 18 for non-smoker rates), subject to the maximum issue age for the selected term length
  • Must be a Canadian resident
  • Should require at least $100,000 in coverage

Types of Canada Life term insurance plans

Canada Life offers a single term plan, which is My Term. It is a customizable term life insurance product that lets you choose your coverage amount and policy duration based on your financial needs. Rather than offering multiple term life plans, Canada Life My Term provides flexibility through a wide range of term lengths, renewal options, conversion privileges, and coverage structures. My Term is available as either a single-life or joint first-to-die policy and can be enhanced with optional riders for more comprehensive protection.

canada life term life insurance

What is covered under Canada Life term life insurance?

Canada Life Term Life Insurance provides financial protection through the following:

  • Tax-free death benefit paid to your beneficiaries if you pass away during the policy term
  • Coverage for terms ranging from 5 to 50 years, allowing you to match protection with your financial obligations
  • Level premiums that remain unchanged throughout your selected term
  • Guaranteed renewal at the end of the term without requiring a medical exam (subject to the maximum renewal age)
  • Guaranteed conversion to an eligible permanent life insurance policy without medical evidence before the conversion age
  • Coverage available through Single Life and Joint First-to-Die options
  • Optional riders such as Child’s Term Life Insurance, Accidental Death Benefit, Disability Waiver, Business Growth Protection Rider, and Guaranteed Insurability Benefit for added protection

Pros and cons of Canada Life term life insurance

Pros Cons
Available with no maximum coverage limit After the initial term, renewal premiums rise annually
Can be converted to eligible permanent life insurance without a new medical exam before the policy anniversary nearest the insured person’s 70th birthday* Requires a minimum $100,000 coverage amount 
Flexible term lengths from 5 to 50 years 
Wide range of optional riders, including business-focused benefits (available for joint first-to-die policies)

How much does Canada Life term life insurance cost?

Canada Life term life insurance costs start at approximately $8.55 per month and can exceed $146.90 per month for a $100,000 policy with a 10-year term. The exact cost can vary based on factors such as your age, gender, health, smoking status, and coverage amount. Younger, healthier applicants typically qualify for the lowest premiums, while rates increase with age. 

Cost of Canada Life term insurance (2026)

Age (in years) Male (non-smoker) Female (non-smoker)
20 $10.53/month $8.55/month
30 $10.80/month $8.82/month
40 $12.36/month $11.46/month
50 $20.40/month $16.66/month
60 $48.50/month $35.38/month
70 $146.90/month $101.78/month

*Illustrative term life insurance cost for male and female non-smokers seeking $100,000 in coverage for a 10-year term life insurance coverage

How much does term life insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

What riders are available with Canada Life term life insurance?

The riders available with Canada Life’s term policy include Accidental Death Benefit Rider, Child’s Term Life Insurance Rider, Guaranteed Insurability Benefit Rider, Disability Waiver Rider, and Business Growth Protection Rider. Canada Life My Term can be customized with optional riders that enhance your coverage based on your personal and family needs.

  • Accidental Death Benefit: Pays an additional death benefit if the insured dies as a result of a covered accidental injury before the rider expires and within the specified time period following the injury
  • Child’s Term Life Insurance Rider: Provides life insurance coverage for eligible children and can often be converted to a term or permanent coverage in the future without medical evidence
  • Guaranteed Insurability Benefit (GIB): Lets you purchase additional life insurance at specified future dates without undergoing a medical exam, regardless of changes in your health
  • Total Disability Waiver: Waives eligible policy premiums if you become totally disabled and meet the rider’s conditions, helping keep your coverage in force while you are disabled
  • Business Value Protection Rider: Designed for business owners, this rider helps protect against the financial impact of a decline in business value following the death of a key individual

Please note that all the above riders are available for single-life policies. The joint first-to-die policy only includes Child’s Term Life Insurance and Business Growth Protection riders.

What is Canada Life’s preferred underwriting option?

Preferred underwriting is an assessment process that evaluates various health and lifestyle factors to determine an applicant’s life insurance risk level. Canada Life considers smoking habits, body build (height and weight ratio), blood pressure, cholesterol levels, personal and family medical history, occupation, high-risk activities (avocations), and driving record. Applicants who qualify for preferred underwriting may receive lower premiums than standard rates, making coverage more affordable for those who present a lower insurance risk.

What conversion options are available with Canada Life term life insurance?

Canada Life My Term offers several conversion options that allow policyholders to adapt their coverage as their financial needs change, often without providing new medical evidence.

  • Term-to-term conversion: Convert your existing My Term policy to a longer term (for example, from a 10-year term to a 20-year term) before reaching the policy anniversary nearest your 70th birthday. The new premium is based on your age at the time of conversion, without requiring a medical exam. Also, the new term must be at least 10 years longer than the original term
  • Term-to-permanent conversion: Convert your My Term policy to an eligible permanent life insurance plan before the policy anniversary nearest your 70th birthday. No medical evidence or health questions are required, making it easier to secure lifelong coverage as your needs evolve
  • Term conversion with reset: This option lets you convert your policy to a combination of temporary and permanent life insurance while resetting the term length and renewal date of the new temporary coverage. It can be completed without medical underwriting, allowing you to extend your temporary coverage and add permanent protection with a single conversion. Please note that at least 40% of the converted amount must become permanent base coverage

Can I exchange my Canada Life term insurance policy?

Yes, Canada Life offers the following policy exchange options under My Term:

  • Joint policy exchange: If you have a Joint First-to-Die policy, you can exchange it for one or two separate single-life permanent life insurance policies. Each new policy can provide up to 50% of the original joint policy’s base coverage amount, provided it meets Canada Life’s age limits at the time of the exchange. This exchange must be completed before the policy anniversary nearest the older insured’s 71st birthday and does not require new evidence of insurability for the base coverage
  • 12-month exchange: During the first 12 months of your policy, you can apply to change your My Term policy to a different term plan or a participating permanent life insurance plan. Premiums under the new plan are based on the insured person’s age on the policy date before the exchange. The coverage amount must remain the same or be lower, and the request is subject to Canada Life’s approval and product availability

How does Canada Life term life insurance compare to other providers?

Canada Life Term Life Insurance stands out for its wide range of term lengths (5 to 50 years), flexible term-to-term and permanent conversion options, and Term Conversion with Reset, a feature not commonly offered by many Canadian insurers.

It also provides guaranteed renewal, customizable riders, and joint first-to-die coverage, making it a strong choice for individuals, families, and business owners seeking long-term flexibility. However, it’s worth reviewing multiple providers before making a decision. Read our guide to the best term life insurance companies in Canada to compare leading insurers side by side.

Our advisor’s take on Canada Life term life insurance

One of our advisors recently assisted a 38-year-old father of two looking for long-term life insurance protection to cover his mortgage, replace his income, and secure his family’s financial future while keeping premiums affordable.

Client profile:

  • Age: 38-year-old non-smoking Canadian
  • Coverage need: $1 million term life insurance
  • Primary concern: Securing long-term coverage with the flexibility to adapt as financial needs change
  • Our comparison: We compared term life insurance policies from several leading Canadian insurers and recommended Canada Life My Term. While many insurers offer standard 10, 20, and 30-year terms, Canada Life stood out for its flexible term options of up to 50 years, guaranteed renewal, multiple conversion options, and Term Conversion with Reset, making it an excellent choice for policyholders who want their coverage to evolve with changing life stages.

Why we recommended Canada Life term life insurance:

  • Offers one of the widest selections of term lengths from 5 to 50 years
  • Includes guaranteed renewal and flexible term-to-term and permanent conversion options without new medical evidence
  • Can be customized with optional riders such as Accidental Death Benefit, Child’s Term Life Insurance, Guaranteed Insurability Benefit, and Total Disability Waiver

How to buy Canada Life term life insurance?

Here are the steps you need to follow to buy Canada Life term insurance:

  • Consult a licensed PolicyAdvisor expert to determine the right coverage amount and policy term
  • Our advisors will help you compare personalized quotes from Canada Life and other top Canadian insurers
  • Customize your policy with optional riders based on your needs
  • Complete your application online with expert guidance throughout the process

So, if you are planning to buy Canada Life Term Life Insurance, consult our licensed PolicyAdvisor. Schedule a call with an advisor today!

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

How do premiums work for Canada Life term life insurance?

Premiums for Canada Life term insurance remain fixed for the initial term length chosen. Once the term ends, the policy automatically renews annually with increasing premiums unless the policyholder cancels or converts the coverage. Payments can be made monthly or annually, depending on the policyholder’s preference.

Can I customize my Canada Life term life insurance policy?

Yes, Canada Life’s My Term™ insurance allows for flexible customization. Policyholders can choose their coverage amount and term length(from 5 to 50 years). Optional riders, such as the child term rider, business growth protection rider, disability waiver, and a few others, can be added for extra protection. Additionally, eligible policies can also be converted to permanent life insurance without providing new medical evidence before the policy anniversary nearest your 70th birthday.

What happens when my term ends?

When the initial term expires, the policy automatically renews each year with guaranteed increasing renewal premiums. This renewal continues until the policy anniversary nearest to your 85th birthday, unless the policyholder cancels or converts the policy to a permanent life insurance plan. Some policyholders may also have the option to adjust their coverage at this stage.

Can I cancel my Canada Life term life insurance policy?

Yes, policyholders can cancel their term life insurance policy at any time. However, cancellation means losing coverage immediately, and no death benefit will be paid out if the insured passes away after the policy is terminated. There are no refunds for past premiums paid.

Can I convert my Canada Life Term Insurance to permanent life insurance?

Yes. Canada Life allows eligible My Term policyholders to convert all or part of their term life insurance to an eligible permanent life insurance policy without providing new medical evidence, provided the conversion is completed before the policy anniversary nearest their 70th birthday. Policies issued at ages 69 and older may be converted within the first two years after the policy date.

Can I renew my Canada Life Term Life Insurance policy?

Yes. Canada Life My Term includes a guaranteed annual renewal option, allowing you to renew your coverage at the end of your term without undergoing a new medical exam, up to the policy anniversary nearest to your 85th birthday. 

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Desjardins Term Life Insurance Review (2026)

Desjardins offers affordable term life insurance for those who want financial protection for a specific period, whether they are raising a family, paying off a mortgage, or protecting a business. It has term options ranging from 10 to 30 years and up to 65; the policy provides guaranteed premiums during the initial term. The cost of Desjardins term life insurance starts at $8.55/month for a 20-year-old female non-smoker seeking $100,000 coverage for a 10-year term. 

Quick review

  • PolicyAdvisor ratings: 4/5
  • Best for: High coverage up to $20 million
  • Skip if: You want fully customizable term durations
Term life insurance can be affordable!

Get the Desjardins life insurance quotes in Canada!

About Desjardins Insurance

Desjardins Insurance is one of Canada’s leading life insurance providers and is part of the Desjardins Group, the largest financial cooperative in North America. The company offers a wide range of insurance and wealth management solutions, including life, health, and casualty insurance. Desjardins is trusted by more than 5 million Canadians for financial protection, as it is also backed by the strength and stability of one of the country’s most well-capitalized financial institutions.

Desjardins’s financial strength

AM Best Rating A
Insurance Revenue $4.3 billion
LICAT Ratio 146%
Total assets  $510.2 billion (Desjardins Group)

What is Desjardins term life insurance?

Desjardins term life insurance is a temporary life insurance policy that provides affordable financial protection for a fixed period of 10, 15, 20, 25, or 30 years, or until age 65. The coverage amounts range from $25,000 to $20 million. If the insured dies during the policy term, beneficiaries receive a tax-free lump-sum death benefit. The policy also offers guaranteed premiums during the initial term, renewal options, and the flexibility to convert to permanent life insurance without proof of insurability.

Key features of Desjardins term policy:

Available terms Term 10 / 15 / 20 / 25 / 30 or Term to 65
Policy issue age (min & max)
  • T10: 18-75 years
  • T15: 18-70 years
  • T20: 0-65 years
  • T25: 0-60 years
  • T30: 0-55 years
  • T65: 0-44 years
Coverage ends at Age 85 (Term 10, 15, 20, 25, and 30); 

Age 65 (Term to 65)

Coverage range $25,000 – $20,000,000
Renewability
  • T10, T15, T25, T30: Every 10 years
  • T20: Every 20 years
  • T65: NA
Term exchange Available within the first 5 years of coverage. Eligible Term 10, Term 15, Term 20, and Term 25 policies can be exchanged for a longer term without evidence of insurability.
Convertibility Convertible to an eligible permanent individual life insurance policy without evidence of insurability, up to age 70.
Coverage structures Individual and joint first-to-die
Premium structure First-term and renewal premiums are guaranteed
Riders
  • Children’s protection benefit
  • Disability waiver of premiums
  • Accidental fracture benefit
  • Guaranteed insurability benefit
  • Children’s accidental fracture benefit
  • Business insurability
  • Accidental death and dismemberment
  • Accidental dismemberment or loss of use

Who is eligible for Desjardins life insurance?

The key eligibility criteria for getting term insurance offered by Desjardins are as follows:

  • Minimum entry age: Varies by plan, from birth (age 0) for select terms to 18 years (T10 and T15) for others
  • Maximum issue age: Depends on the selected term:
    • Term 10 (T10): Up to age 75
    • Term 15 (T15): Up to age 70
    • Term 20 (T20): Up to age 65
    • Term 25 (T25): Up to age 60
    • Term 30 (T30): Up to age 55
    • Term to 65 (T65): Up to age 44
  • Coverage duration: All term plans provide coverage up to age 85, while Term to 65 provides coverage until age 65 and is not renewable
  • Coverage amount: Choose between $25,000 and $20 million, subject to underwriting approval
  • Coverage type: Available as individual or joint first-to-die coverage for T10, T15, T20, T25, and T30. T65 is available as individual coverage only

Types of Desjardins term life insurance plans

Desjardins offers one term life insurance product that can be customized with six term length options to suit your financial goals and coverage needs. You can choose from Term 10 (T10), Term 15 (T15), Term 20 (T20), Term 25 (T25), Term 30 (T30), or Term to 65 (T65). All plans offer coverage amounts from $25,000 to $20 million, with guaranteed premiums during the initial term.

The different term lengths are designed for different financial needs. Term 10 is ideal for short-term obligations; Term 15 and Term 20 work well for mortgages and raising a family, while Term 25 and Term 30 are better suited for long-term financial commitments, such as income replacement and business protection. Term to 65 is designed for those who want affordable life insurance coverage throughout their working years until retirement.

Desjardins term life insurance

What is covered under Desjardins life insurance?

Desjardins Term Life insurance provides a lump-sum and tax-free death benefit to the beneficiaries. The key coverage includes:

  • Tax-free death benefit: Your beneficiary receives a tax-free lump-sum payment if you pass away while the policy is in force
  • Renewable coverage: Most term plans renew automatically without requiring a new medical exam, with adjusted premiums, until age 85 (Term to 65 is not renewable)
  • Convertible coverage: Lets you convert your term policy to an eligible permanent life insurance plan without providing proof of insurability, up to age 70 (up to age 60 for Term 65)
  • Optional coverages: You can customize your policy with riders such as guaranteed insurability, business insurability, waiver of premium for disability, accidental death and dismemberment, accidental fracture, and children’s protection benefit

Can I get an exchange option with Desjardins term life insurance?

Yes, Desjardins allows eligible policyholders to exchange their existing Term 10, Term 15, Term 20, or Term 25 policy for a longer-term plan. The exchange can be done without providing proof of insurability. You can exercise this option within the first five policy years, subject to the applicable age limits for each term. Available exchange options include:

Current term Can be exchanged to
Term 10 Term 15, Term 20, Term 25, or Term 30
Term 15 Term 20, Term 25, or Term 30
Term 20 Term 25 or Term 30
Term 25 Term 30
Term 30 & Term to 65 Not available

Pros and cons of Desjardins term life insurance

Pros Cons
Offers a wide choice of term lengths, including 10, 15, 20, 25, 30 years, and Term to 65 Some optional benefits and conversion privileges have age restrictions
Coverage amounts range from $25,000 to $20 million, suitable for both personal and business needs Rates may not be the most affordable
Includes exchange, conversion, association, and insurability options for added flexibility Term to 65 expires at age 65 and cannot be renewed
Offers several optional riders, including disability waiver, accidental death, children’s protection benefit, and guaranteed insurability
Renewable term plans automatically renew without a medical exam until age 85 (except T65)
Multi-coverage discount when you buy two or more coverages at the same time on the same policy

How much does Desjardins term life insurance cost?

Desjardins Term Life Insurance premiums start at around $8.55 per month for a 20-year-old female non-smoker and $10.44 per month for a 20-year-old male non-smoker for a 10-year term policy with $100,000 in coverage. However, premiums will vary based on age, gender, health, smoking status, coverage amount, and selected term length. Younger, healthier applicants pay lower premiums compared with others. 

Cost of Desjardins term life insurance (2026)

Age (in years) Male (non-smoker) Female (non-smoker)
20 $10.44/month $8.55/month
30 $10.89/month $9.00/month
40 $12.15/month $11.52/month
50 $20.70/month $16.56/month
60 $51.57/month $38.52/month
70 $158.76/month $110.52/month

*Illustrative term life insurance monthly premiums for male and female non-smokers seeking $100,000 in coverage for a 10-year term

How much does term life insurance cost?

Get instant quotes from Canada's top life insurance providers and find the perfect coverage for your family.

$500K

What are the riders available with Desjardins life insurance?

Desjardins life insurance offers several optional riders, including the guaranteed insurability benefit, business insurability benefit, waiver of premium for disability, accidental death and dismemberment (AD&D), accidental fracture benefit, and children’s protection benefit. These life insurance riders are available for an additional premium but let you customize your policy as per your needs.

  • Guaranteed insurability benefit: Lets you purchase additional life insurance at specified dates without providing new medical evidence
  • Business insurability benefit: Allows business owners to increase coverage after qualifying business events without medical underwriting
  • Waiver of premium for disability: Waives your policy premiums if you become totally disabled and meet the policy’s eligibility requirements
  • Accidental death and dismemberment (AD&D): Pays an additional benefit if you die or suffer certain serious injuries due to a covered accident
  • Accidental fracture benefit: Provides a lump-sum payment if you experience a covered bone fracture caused by an accident
  • Children’s protection benefit: Provides term life insurance coverage for your eligible children, with the option to convert to permanent coverage later without medical evidence

What is the association option with Desjardins life insurance?

The association option is an optional feature that allows you to exchange your individual term life insurance coverage for a joint last-to-die permanent life insurance policy. This can be done when you add another insured person. This exchange is available until age 70 for Term 10, Term 15, Term 20, Term 25, and Term 30, and until age 60 for Term to 65. If the new insured does not already have a Desjardins policy with the association option, they must provide proof of good health. This feature is particularly useful for estate planning, helping cover final expenses and taxes that may be payable after the death of the last insured person.

What is the insurability option with Desjardins life insurance?

The insurability option allows couples and business partners to split a joint life insurance policy into two individual permanent life insurance policies without providing proof of good health, provided the change is made before age 65. When this option is exercised, the total coverage amount can be divided equally between both insured individuals. 

If one insured person passes away, the surviving policyowner has 90 days to apply for individual permanent coverage for the original insured amount, as long as they are 65 or younger. If both the insured die within that 90-day period, Desjardins pays the tax-free death benefit to the designated beneficiary or estate.

What is multi-coverage discount on Desjardins term life insurance?

The multi-coverage discount is a premium savings feature offered by Desjardins that lets you pay lower premiums when you purchase two or more eligible insurance coverages at the same time under the same policy. By combining multiple coverages into a single policy, you can receive the protection you need while reducing your overall insurance costs. The eligibility, however, depends on the types of coverage selected and Desjardins’ policy rules.

Do you need a medical exam to get Desjardins term life insurance?

Yes, you may need a medical exam to get Desjardins Term Life Insurance. Applicants seeking higher coverage amounts or those with certain medical conditions are more likely to undergo medical underwriting, while others may qualify by answering health-related questions only.

If you don’t qualify for traditional term life insurance and are over 50 years old, Desjardins also offers Life Insurance Over 50. This is a permanent life insurance product for people aged 50 to 75 that requires no medical exam. Also, there is no waiting period, and the coverage starts right away.

How does Desjardins term life insurance compare to other providers?

Desjardins Term Life Insurance stands out for its flexible term options, high coverage limits of up to $20 million, and built-in exchange and conversion privileges that allow policyholders to adapt their coverage as their needs change. It also offers features such as the Association Option, Insurability Option, and a wide range of optional riders for added flexibility. While Desjardins offers term lengths up to 30 years, some insurers provide longer initial terms or broader digital application options. So, it is always advisable to compare quotes before finalizing one insurer. Refer to our guide on best term life insurance companies in Canada to know more. 

Our advisor’s take on Desjardins term life insurance

One of our advisors recently assisted a 38-year-old business owner looking for affordable life insurance to protect their family’s financial future while maintaining the flexibility to increase or extend coverage as their business and personal responsibilities grew.

Client profile:

  • Age: 38-year-old non-smoking Canadian
  • Coverage need: $1 million to protect family income, cover business liabilities, and repay a mortgage
  • Primary concern: Finding flexible term coverage with the ability to extend or convert the policy without another medical exam
  • Our comparison: We compared Desjardins Term Life Insurance with several leading Canadian insurers based on term lengths, coverage flexibility, conversion and exchange privileges, optional riders, and overall long-term value. Desjardins stood out for its coverage of up to $1 million, flexible term options, and other features

Why we recommended Desjardins term life insurance:

  • Offers six term options (10, 15, 20, 25, 30 years, and Term to 65) 
  • Includes guaranteed renewability, conversion to permanent life insurance, and a term exchange option without proof of insurability
  • Provides unique features such as the association option and insurability option
  • It is available with optional riders such as guaranteed insurability, business insurability, waiver of premium for disability, accidental fracture, and children’s protection benefit, allowing the policy to adapt as your needs evolve

How to buy Desjardins life insurance?

To buy Desjardins term life insurance, you can connect with one of our licensed advisors. At PolicyAdvisor, we will help you compare quotes from 30+ insurers. Here are the steps you need to follow:

  • Contact our advisors and compare term life insurance quotes
  • Our advisors will also help you assess your coverage needs and recommend a suitable policy
  • With our assistance, complete your Desjardins life insurance application form and submit the required documents
  • Review the details before finally submitting your application

Schedule a call today to buy a term insurance policy with PolicyAdvisor!

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Frequently asked questions

Is Desjardins term life insurance worth it?

Yes, Desjardins term life insurance is a good option if you want affordable, flexible coverage with high coverage limits. It offers term lengths from 10 to 30 years or Term to 65, coverage up to $20 million, guaranteed renewability on eligible term plans, conversion to permanent insurance, and several optional riders to customize your policy.

Can I convert my Desjardins term life insurance to permanent life insurance?

Yes, Desjardins term life insurance policies can be converted to an eligible permanent life insurance policy without providing proof of insurability. This option is available up to age 70 for Term 10, Term 15, Term 20, Term 25, and Term 30, and up to age 60 for Term to 65. Converting to permanent life insurance lets you maintain lifelong coverage even if your health changes.

Can I buy Desjardins term life insurance for my spouse?

Yes, you can get coverage for your spouse with Desjardins term life insurance. Desjardins offers both individual and joint first-to-die coverage, allowing spouses to be covered under a single policy. It offers both individual and joint first-to-die coverage for Term 10, Term 15, Term 20, Term 25, and Term 30.

What term lengths does Desjardins offer?

Desjardins offers six term life insurance options: 10, 15, 20, 25, and 30 years, as well as Term to 65, allowing you to choose coverage that matches your financial goals. Shorter terms, such as 10 or 15 years, are ideal for covering temporary debts or personal loans, while 20- and 30-year terms are better suited for long-term commitments like a mortgage, raising children, or income replacement. Term to 65 is designed for those who want coverage until their planned retirement age.

Can I switch to a longer Desjardins term later?

Yes, you can use the term exchange option during the first five policy years to exchange certain term plans for a longer-term policy without providing proof of insurability.

Can I add coverage for my children to a Desjardins life insurance policy?

Yes, Desjardins offers a children’s protection benefit that provides term life insurance coverage for all eligible children up to age 25. If a covered child passes away while the rider is in force, the policy pays a death benefit. The rider also includes a conversion privilege, allowing each child to purchase up to five times the selected basic coverage amount without providing proof of insurability when they become eligible.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Edge Benefits Critical Illness Insurance Review – Updated 2026

We recommend Edge Benefits’ guaranteed issue critical illness insurance. They offer the highest amount of coverage for a guaranteed product with no medical exams or questions. These products are great for those who might not otherwise qualify for standard critical illness insurance products due to pre-existing health conditions.

Read our full review below to find out more about the company, which features they offer, and what we rate their critical illness insurance products.

PolicyAdvisor Rating

AM Best Rating N/A

COMPARE QUOTES

Our Edge Benefits critical illness insurance review & rating

We give Edge Benefits a 5-star rating for their guaranteed critical illness insurance product. While it does not offer the same coverage maximums as a fully underwritten product, it offers the most coverage for a guaranteed product.

Edge Benefits is an insurance provider that partners with other insurance companies such as the Co-operators, Green Shield, Chubb, and Beneva. Edge Benefits offers its guaranteed issue critical illness insurance product through Chubb Insurance, who is known for specialty types of insurance. 

Edge Benefits also offers:

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Edge Benefits critical illness product overview

Edge Benefit offers a high-quality guaranteed critical illness insurance product. This policy offers one of the highest max coverage amounts on the market for a guaranteed product. The product offers coverage for up to 23 full critical conditions and 2 partial conditions as well as optional children’s riders, which adds $10,000 in critical illness coverage for your children (up to age 21) for 4 extra conditions.

Their critical illness insurance is offered in two tiers:

Tier 1 – Guaranteed coverage 

Tier 2 – Simplified coverage 

  • Some simple medical questions
  • Up to $100,000 in coverage

Edge Benefits offers these tiers as a term policy to age 70. Additionally, they will increase the benefit amount by 5% every 5 years up to 25% for the policy. Because of this, we consider this a highly-rated guaranteed critical illness insurance policy.

Edge Benefits Critical Illness Insurance — Product Details

  • Type of coverage: Guaranteed
  • Available term lengths: To age 70
  • Number of illnesses covered: Up to 23
  • Survival period: 30 days
  • Waiting period: 2 years for critical illnesses related to pre-existing conditions only
  • Maximum coverage amount: $50,000 (with a 5% increase every 5 years)
  • Application process: Online
  • Claims contact: Edge Benefits
  • Renewable: No
  • Convertible: No
  • Limited pay options: No
  • Return of premium options: No
  • Partial payouts: Yes — for 2 different conditions, 20% up to $20,000 and only payable once
  • Loss of independent existence coverage: No

Read our Edge Benefits Life Insurance Review

Edge Benefits critical illness insurance pros and cons

Here is what our team ranks as the most and least advantageous features of Edge Benefits guaranteed critical illness insurance products for most Canadians.

✅ Edge Benefits critical illness insurance pros

  • No medical exams, health questions, or medical underwriting needed
  • Fast underwriting
  • Large coverage amounts up to $50,000 guaranteed
  • Comprehensive coverage 23 conditions covered
  • Pays out for up to 2 partial conditions
  • Second event benefits (payout for a second, unrelated condition)
  • Automatic 5% benefit increase after 5 years (up to 25%)
  • Options for simplified plans to increase coverage amount
  • Child critical illness rider available

❌ Edge Benefits critical illness insurance cons

  • No return of premium options if your plan expires or if you cancel without a claim
  • No short-term options
  • No limited pay options
  • Limited coverage compared to fully underwritten policies
  • 2-year waiting period for any condition related to a pre-existing condition (no coverage for the pre-existing condition itself)

Who is Edge Benefits?

Edge Benefits was founded in 1985, making it a relatively new player in the insurance industry (compared to those who have been around for hundreds of years). They initially sold life insurance, living benefits, and other investment products.

In 2013, Edge Benefits transformed the insurance purchasing landscape by eliminating paper applications and introducing a fully electronic application system. Two years later, it became affiliated with The Co-operators Group Limited. Furthermore, in 2019, Edge Benefits augmented its guaranteed issue critical illness insurance to $50,000, setting a new precedent as the highest coverage amount available in Canada. With a client base exceeding 60,000 policyholders, Edge Benefits has disbursed over $200 million in claims over the past 15 years.

Edge Benefits Inc. operates as a strategic partner with insurance companies rather than functioning as an insurance entity itself. The Co-operators, Green Shield Canada, Chubb, and Beneva are among its partnered insurers, ensuring comprehensive protection for Canadian consumers. Edge Benefits issues their life insurance, critical illness insurance, and disability insurance products through Chubb.

Blue bulb

Edge Benefits Insurance Canada: Quick Facts

  • When was Edge Benefits founded? 1985
  • Where is Edge Benefits Insurance headquarters? Newmarket, Ontario
  • AM Best Rating: N/A
  • Better Business Bureau Accreditation and Rating: N/A
  • Assets: – 
  • Annual Premiums: –

Check out more facts about Canada’s biggest life insurance companies
Still looking for the best critical illness insurance rates?
PolicyAdvisor saves you time and money when comparing Canada’s top insurance companies. Check it out!
GET STARTED

Where to buy Edge Benefits Critical Illness insurance policies?

You can buy Edge Benefits Critical Illness insurance on PolicyAdvisor. Use our free quoting tool or click the button below to get personalized quotes instantly. And, you can also compare those quotes with some of the other best critical illness insurance companies in Canada.

If you would prefer to speak with a licensed insurance agent, we can help with that too! Our experienced advisors would be happy to speak with you and give one-on-one advice.

Edge Benefits critical illness insurance FAQ

Does Edge Benefit cover pre-existing conditions?

No. Edge Benefits critical illness insurance policies will not cover any pre-existing condition diagnosed before the policy’s effective date. However, you can still get coverage for other conditions, even if you’ve been diagnosed with a medical condition.

For example. if you have had paralysis before your policy’s effective date, the policy will not provide a payout if you are diagnosed with paralysis again. But if you were diagnosed with an eligible cancer, you would receive a payout.

Other companies may deny coverage altogether or may significantly increase your premiums if you have a pre-existing condition.

Is there a waiting period before claiming with Edge Benefits?

No. There is no standard waiting period for claiming a newly diagnosed critical illness.

However, if your newly diagnosed illness is related to a previously diagnosed illness. there is a 2-year waiting period.

Example: You were diagnosed with diabetes in childhood. You purchase a guaranteed critical illness insurance policy in your 40s.

❌ If your diabetes led to major organ failure WITHIN 24 months of the policy effective date, major organ failure is NOT covered.
✅ If your diabetes led to major organ failure AFTER  24 months of the policy effective date, major organ failure IS covered.

Can you claim a diagnosis more than once on a critical illness policy with Edge Benefits? 

Yes. For certain conditions, you can claim more than once. For example, if you buy a critical illness policy and are diagnosed with cancer a few months later the claim will be
paid. Then, if you go into remission, but the cancer returns 10 years later, a second claim would be paid out.

What is a Second Event Benefit with Edge Benefits?

A second event benefit is a secondary payout if you are diagnosed with one critical illness and then another after fully recovering from the first illness. Only heart attack and cancer qualify for second-event benefits.

For example, if you are diagnosed with cancer after the policy’s effective date, you will get your first payout. Then, if later you recover from the cancer, but suffer an un-related heart attack, you would get a second payout for the heart attack.

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL
/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

RBC Critical Illness Insurance Review – Updated 2026

PolicyAdvisor Rating

Best Critical Illness Insurance & Long-Term Care Combo

AM Best Rating A

GET QUOTES

RBC critical illness insurance provides a financial safety net for individuals facing unexpected medical challenges. In this review, we’ll evaluate how RBC critical illness insurance can help protect your financial stability during a health crisis. Whether you’re seeking peace of mind or additional financial security, this review will guide you through everything you need to know about RBC’s offerings.

What are the key features of RBC’s critical illness insurance?

RBC offers two types of critical illness insurance plans tailored to meet diverse needs: the Critical Illness Insurance Plan and the Critical Illness Recovery Plan. Coverage amounts range from $10,000 to $2 million, providing flexibility to suit varying financial goals and protection levels.

The basic plan includes a Return of Premium on Death Benefit, offering refunds for all the paid premiums if the policyholder passes away while the policy is in force. Meanwhile, the Recovery plan stands out for its conversion feature, allowing policyholders to transition to a permanent plan without requiring proof of insurability.

Category Details
Minimum issue age 18 years
Maximum issue age 65 years
Coverage amount range
  • $10,000 to $75,000 for the Basic plan
  • $25,000 to $2 million for the Recovery plan
Survival period 30 days
Additional benefits Return of Premium on Death Benefit on the Basic plan

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What are the different critical illness insurance plans offered by RBC?

RBC offers two types of critical illness insurance plans tailored to meet diverse needs: the Critical Illness Insurance Plan and the Critical Illness Recovery Plan. The Recovery plan has four tiers: 10-year term Renewable to age 75, Level cost to age 75, Renewable to age 65, and Renewable to age 75 plans.

While the Basic insurance plan offers coverage for major critical illnesses like cancer, heart attack, and stroke, the Recovery plan covers a detailed list of 30+ critical illnesses. Check out what these plans have to offer:

Key differences between RBC’s critical illness recovery plan and critical illness insurance plan

Feature Critical Illness Recovery Plan Critical Illness Insurance Plan
Purpose Comprehensive financial protection against 30+ critical illnesses Affordable protection for the three most common critical illnesses: Life-threatening cancer, heart attack, and stroke
Eligibility Available to individuals aged 18-65 Available to individuals aged 18-50
Coverage amount Lump sum benefit between $25,000 to $2 million Fixed benefit options of $10,000, $25,000, $50,000, or $75,000
Covered illnesses Covers over 30 illnesses, including cancer, heart attack, stroke, kidney failure, multiple sclerosis, Parkinson’s disease, Alzheimer’s disease, major organ transplant, and more Covers only 3 critical illnesses: Life-Threatening Cancer, Heart Attack, and Stroke
Premiums Depend on the chosen plan Premiums increase every 10 years and can change until age 65
Policy term Flexible term options, including permanent or renewable term policies Renewable term policies with a maximum term period
Long-term care conversion Yes No
Optional riders Includes optional benefits such as:

  • Return of Premium on Death: Refunds premiums if the insured dies without claiming
  • Scheduled Increase Benefit: Increases coverage at predefined intervals
  • Disability Waiver of Premium: Waives premiums if the insured becomes disabled
Return of premium on death
Additional services Provides access to additional services such as Teladoc Health, “The Healing Journey” program and early assistance benefit Access to additional services such as Teladoc Medical Experts+, Medical Confidence, “The Healing Journey” program and early assistance benefit 
Claim process Requires detailed medical documentation; offers flexibility in accessing partial benefits for early-stage illnesses Simplified claims process, but restricted to full payouts for qualifying conditions

What are the critical illnesses covered by RBC?

RBC’s Critical Illness Recovery plan offers comprehensive coverage for a wide range of serious medical conditions, including cancers, heart attacks, loss of limbs, brain damage, organ failure, and more. This can serve as a financial support during challenging times.

Cancer (Life-threatening)

  • Includes carcinoma, melanoma, leukemia, lymphoma, and sarcoma.
  • A detailed explanation of “life-threatening cancer” is outlined in the policy contract.

Heart-related conditions

  • Heart attack
  • Heart surgery requirements, including:
    • Aortic surgery
    • Coronary artery bypass surgery
    • Heart valve replacement or repair

Brain-related diseases

  • Stroke (Cerebrovascular accident)
  • Other brain diseases:
    • Bacterial meningitis
    • Benign brain tumor
    • Dementia, including Alzheimer’s disease
    • Parkinson’s disease and specified atypical Parkinsonian disorders

Loss of senses, limbs, or mobility

  • Blindness: Total and irreversible loss in both eyes
  • Deafness: Total and irreversible loss in both ears
  • Loss of speech: Total and irreversible loss of the ability to speak
  • Loss of limbs: Total severance of two or more limbs
  • Paralysis: Total loss of muscle function in two or more limbs

Organ failure or transplant

  • Kidney failure
  • Major organ failure on waiting list
  • Major Organ Transplant

Other covered conditions

  • Coma
  • Aplastic anemia
  • Loss of independent existence
  • Occupational HIV infection (accidental infection acquired while working)
  • Severe burns

Partial benefits for early-stage conditions

You may qualify for 10% of the benefit amount (up to $50,000) the first time you are diagnosed with one of the following early-stage cancers:

  • Early breast cancer
  • Early prostate cancer
  • Early skin cancer
  • Early-stage intestinal cancer
  • Early thyroid cancer
  • Early-stage blood cancer

Additionally, you may also qualify for 10% of the benefit amount (up to $50,000) if you undergo a coronary angioplasty procedure.

Learn more about what critical illness insurance covers in Canada
Not sure which RBC plan is right for you?

Book a free consultation with our licensed advisors for help

What conditions are excluded from RBC critical illness insurance?

RBC critical illness insurance policies have specific exclusions such as self-inflicted harm, substance abuse, war or hostile conditions, criminal activities, and more. In such cases, no benefits will be paid, and premiums will not be refunded:

  1. Self-inflicted harm: No benefits are payable for injuries or death resulting from self-inflicted harm, attempted suicide, or suicide, regardless of the insured’s state of mind
  2. Substance use: Losses caused by the intentional use of drugs, intoxicants, narcotics, or poisonous substances are excluded
  3. War or hostile actions: Claims resulting from participation in war (declared or undeclared), hostile actions of armed forces, insurrection, or civil commotion are not covered
  4. Criminal activity: No benefits are paid for losses arising from an attempt to commit or the commission of a crime, regardless of whether the insured is charged
  5. Impaired operation of vehicles: Coverage is excluded for accidents occurring while operating a land, water, or air vehicle if:
    • The insured’s blood alcohol concentration exceeds 80 milligrams per 100 milliliters, or
    • The insured is under the influence of drugs, intoxicants, narcotics, or poisonous substances

What is the cost of RBC’s critical illness insurance plans?

The cost of RBC’s critical illness insurance ranges between $17 to $180 based on a person’s age, gender, family medical history and smoking status. The following is an illustration of the monthly premiums for different coverage amounts and smoking status. 

RBC critical illness insurance monthly premiums

Age Coverage amount Monthly premium ( Male Smokers) Monthly premium (Male Non-smokers)
20 $50,000 $17.91 $16.75
30 $100,000 $39.87 $30.33
35 $50,000 $31.23 $21.42
40 $100,000 $78.66 $43.92
45 $50,000 $74.16 $37.80
55 $100,000 $396.45 $179.82

*Sample illustration for male smokers and non-smokers between 20-55 years of age

What are the premium options for RBC’s critical illness insurance plans?

RBC offers flexible premium structures tailored to different coverage needs. The premium options vary based on whether you have chosen the basic plan or the Recovery plan. 

For the Recovery plan, the premium options include Level Premiums to Age 75, Level Premiums to Age 65 or 75, or 10 Year Term, Renewable to Age 75. For the basic plan, there is the provision for 10 Year Term, Renewable to Age 65.

1. Critical Illness Recovery Plan

This plan provides long-term stability with these three premium structures:

Level Premiums to Age 75 (Non-Cancellable)

  • Premiums remain fixed for life, ensuring cost predictability
  • RBC cannot change the premiums, modify policy benefits, or cancel the coverage as long as premiums are paid

Level Premiums to Age 65 or 75 (Guaranteed Renewable)

  • Premiums remain fixed until the selected age
  • While benefits cannot be altered, RBC may adjust future renewal premiums, but only for an entire group of policyholders with similar characteristics

10-Year Term, Renewable to Age 75

  • Premiums are scheduled to change every 10 years
  • Benefits remain fixed, and policy renewal is guaranteed as long as payments are made

2. Basic Critical Illness Insurance Plan

This plan provides more affordable coverage with a shorter renewal structure:

10-Year Term, Renewable to Age 65

  • Premiums increase every 10 years
  • Benefits remain unchanged, but RBC may adjust premiums for a group of policyholders with similar characteristics (not for individuals)
  • Coverage renews automatically until age 65 without requiring new medical assessments

Both plans ensure continued coverage, but the Recovery Plan offers more premium stability, especially with the non-cancellable option.

Why should you choose RBC’s critical illness insurance plan?

RBC Insurance’s Critical Illness Insurance Plan offers an affordable and reliable way to protect your financial well-being in the event of a critical illness. Here’s why you should consider this plan:

  • Financial protection for common critical illnesses: This plan provides coverage for three of the most common critical illnesses, offering peace of mind knowing you’re financially supported if the unexpected happens
  • Flexible benefit amounts: Choose from four benefit options to select the coverage amount that best suits your needs
  • Automatic renewal: The coverage automatically renews every 10 years until age 65 without the need to submit new medical information
  • Transparent cost structure: While the cost for each 10-year period may increase, it will be clearly outlined in your policy contract
  • Group-based premium adjustments: If premiums increase within a 10-year period, it will only apply to the entire group of policyholders with similar characteristics, not to your individual policy. You will be notified in advance of any changes
  • Access to medical assistance: This plan includes valuable support services to assist with your diagnosis and recovery, offering guidance and resources when you need them most
Looking for the best insurance rates?

Our calculator gets you the lowest insurance quotes within minutes!

What are the pros and cons of RBC’s critical illness insurance?

RBC’s critical illness insurance plans have several pros in terms of additional services such as Teladoc Medical Experts. The Healing Journey program and more. However, there are certain downsides in terms of a 90-day waiting period for cancer, limited disease coverage in the Basic plan, and varying premium amounts.

Pros Cons
There are two critical illness insurance options to choose from, based on your budget and needs There is a 90 day waiting period for cancer diagnosis payouts
Teladoc Medical Experts allow you to get expert opinions from renowned medical professionals to confirm your diagnosis, no matter where you live The critical illness insurance plan only has coverage for cancers, heart attack and stroke, leaving out numerous major diseases
RBC’s “Healing Journey Program” can be a useful tool for individuals dealing with anxiety after their diagnosis. The premium amount may change over time
For the Recovery option, individuals can convert their term plans to permanent plans until the age of 71 without having to undergo medical examinations
The offered lump sum benefit is up to $2 million
Policyholders can receive 10% of their benefit (up to $50,000, payable once) without affecting future claims if diagnosed in the early stages of certain cancers or undergo coronary angioplasty, and meet the survival period requirements.

Is RBC’s critical illness insurance policy right for you?

RBC can be a good option for Canadians who are getting older. If you want to protect yourself against financial loss if you suddenly get a critical illness, but you also want to make sure you have a plan for if you need long-term care in your senior years, RBC could be a great option for you.

Plus, they give you a lot of coverage and a fair bit of leeway with their partial condition coverage.

On the other hand, the company does not offer as many rider options as others, so it might not be the best option if you’re looking to get multiple coverages in one go. With their Guaranteed Renewable plans, they’re also the only company in Canada allowed to increase prices not just for one policyholder but for everyone’s policy that has certain characteristics the company decides.

This is why you should speak with a professional before you decide. As Canada’s best online insurance agents, we have insight that can help when you’re making a decision on which critical illness insurance to buy.

At PolicyAdvisor, we work with more than 30 of the best insurance companies in Canada. Speak to our licensed advisors and we can help you decide if RBC’s products are the best fit for you.

Where to buy RBC critical illness insurance policies?

You can buy RBC Critical Illness insurance on PolicyAdvisor. Use our free quoting tool or click the button below to get personalized quotes instantly. And, you can also compare those quotes with some of the other best critical illness insurance companies in Canada.

If you would prefer to speak with a licensed insurance agent, we can help with that too! Our experienced advisors would be happy to speak with you and give one-on-one advice.

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Can I customize the coverage amount in RBC’s critical illness insurance plan?

Yes, RBC allows you to choose from multiple benefit amounts, giving you the flexibility to select a plan that aligns with your financial needs and priorities. This ensures personalized coverage that suits your unique situation.

What happens if I don’t file a claim during my coverage term?

If no claim is filed during a 10-year term, the policy automatically renews until age 65, ensuring uninterrupted coverage without requiring additional medical assessments. RBC’s policy is designed for long-term protection, whether you make a claim or not.

Does RBC’s critical illness insurance policy provide coverage for early-stage illnesses?

Yes, RBC offers a unique feature where you can receive 10% of your benefit amount (up to $50,000) for certain early-stage illnesses, such as Early Skin Cancer or Early Thyroid Cancer. This partial benefit is paid without impacting the full coverage for future claims.

Are premium rates fixed throughout the policy term?

Premiums are guaranteed for each 10-year coverage term but may adjust at renewal based on factors affecting the group of policyholders with similar characteristics. However, RBC ensures individual policies are not singled out for rate increases.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Desjardins Critical Illness Insurance Review – Updated 2026

PolicyAdvisor Rating

Best For Extensive Coverage

AM Best Rating N/A

GET QUOTES

One of Canada’s largest financial institutions, Desjardins offers comprehensive critical illness coverage for individuals, children, and business owners. In this review, we’ll take a closer look at these offerings — their features, benefits, and downsides — to help you determine if they’re the right fit for your needs.

What are the benefits of Desjardins’ critical illness insurance? 

Desjardins’ critical illness insurance, also known as Health Priorities, provides a tax-free lump-sum payment if you’re diagnosed with one of its 26 covered health conditions. This benefit is payable even if you’re diagnosed outside Canada.

Other benefits include:

  • Long-Term Care (LTC): In case of loss of independence with a reasonable chance of recovery, Desjardins will pay 15% of your total insurance benefit (up to a maximum of $25,000)
  • Partial benefit: In addition to the 26 covered conditions, Desjardins offers partial coverage (ranging from 1% to 30% of the insurance amount) for over 16 health conditions
  • Second medical opinion: Following the diagnosis of a covered condition, you can access Desjardins Health Priorities’ second opinion service for a thorough review of your medical records to confirm your diagnosis
  • Autonomy assistance: In the event of a temporary or permanent loss of independence, Desjardins Health Priorities provides home care services to help simplify daily life for you and your caregivers
  • Phone assistance: Desjardins Health Priorities also offers telephonic access to nurses for advice on nutrition, vaccinations, prescription drug use, and other health concerns

Desjardins’ business plan also includes a death benefit that is paid to your company if you die prematurely. This amount is either 100% of all premiums paid by you and your company or 25% of your insurance amount, whichever is greater.

Schedule a call for visitor insurance
Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

What types of critical illness insurance are offered by Desjardins?

Desjardins offers three types of critical illness policies for individuals, business owners (and key employees), and children. Here’s a closer look at these plans:

  • Health Priorities (individual): Offers comprehensive coverage for 26 health conditions and partial coverage for more than 16 conditions, with coverage limits of up to $3 million
  • Executive Health Plan (for businesses): Allows you to own a critical illness policy jointly with your company and pays a lump-sum benefit if you’re diagnosed with a covered health condition. If you remain healthy until the policy’s expiry, you can get back 100% of your paid premiums

Key features of Desjardins’ critical illness insurance

Feature Individual Child Executive Health Plan
Coverage amount range $10,000 to $3 million $10,000 to $1 million $10,000 to $3 million
Issue ages 18 to 65 years 0 to 25 years or 0 to 17 years with additional disease options 18 to 65 years
Premium and coverage options
  • Term 10
  • Term 20
  • Term to 65
  • Term to 75
  • Payable to age 100
  • 10 Pay
  • 20 Pay
  • 20 Pay
  • Term 20
  • Term to 75
  • Payable to age 100
Conditions covered
  • Comprehensive coverage for 26 conditions
  • Partial coverage (or advance) for over 16 conditions
  • Comprehensive coverage for 32 conditions, including 6 childhood diseases
  • Partial coverage (or advance) for over 16 conditions
  • Comprehensive coverage for 26 conditions
  • Partial coverage (or advance) for over 16 conditions
Survival period 30 days for cardiovascular conditions and procedures 30 days for cardiovascular conditions and procedures 30 days for cardiovascular conditions and procedures
Waiting period
  • 90 days for life-threatening and early-stage cancers and benign brain tumors
  • One year for Parkinson’s disease and specified atypical Parkinsonian disorders
  • 90 days for life-threatening and early-stage cancers and benign brain tumors
  • One year for Parkinson’s disease and specified atypical Parkinsonian disorders
  • 90 days for life-threatening and early-stage cancers and benign brain tumors
  • One year for Parkinson’s disease and specified atypical Parkinsonian disorders
Partial benefits 1% to 30% of the insurance amount (depending on the condition) 1% to 30% of the insurance amount (depending on the condition) 15% of your total insurance amount (maximum $50,000)
Return of premiums Optional Included in the policy Included in the policy
Optional benefits Disability waiver of premiums, accidental benefit, accidental fracture, accidental death, dismemberment, or loss of use,  children’s life protection, and  children’s accidental fracture Disability waiver of premiums, accidental benefit, accidental fracture, and accidental death, dismemberment, or loss of use Disability Waiver of Premiums

Source: Desjardins Insurance

What is covered under Desjardins’ critical illness insurance? 

Desjardin’s critical illness insurance covers 26 health conditions across 6 categories:

Category Conditions
Cancer
  • Cancer (life-threatening)
  • Benign brain tumour
Cardiovascular
  • Stroke
  • Aortic surgery
  • Heart attack
  • Coronary artery bypass
  • Heart valve replacement or repair
Neurological
  • Dementia, including Alzheimer’s disease
  • Parkinson’s disease and specified atypical Parkinsonian disorders
  • Motor neuron disease
  • Bacterial meningitis
  • Multiple sclerosis
Accidents and functional loss
  • Severe burns
  • Blindness
  • Coma
  • Acquired brain injury
  • Paralysis
  • Loss of speech
  • Loss of limbs
  • Deafness
Other
  • Aplastic anemia
  • Occupational HIV infection
  • Permanent loss of independent existence
Vital organs
  • Major organ failure on waiting list
  • Major organ transplant
  • Kidney failure

The company also provides coverage for 6 childhood conditions:

  • Autism spectrum disorder
  • Cystic fibrosis
  • Rett syndrome
  • Type 1 diabetes mellitus
  • Muscular dystrophy
  • Cerebral palsy

Additionally, Desjardins pays a partial benefit (or advance) for over 16 health conditions. You can receive up to 5 payments per category, with benefits ranging from 1% to 30% of your coverage amount. The categories are:

  • Early-stage cancer:15% of the insurance amount (maximum $50,000) 
  • Other cancers (non-life threatening):1% of the insurance amount (maximum $5,000)
  • Total mastectomy or prostatectomy: 30% of the insurance amount (maximum $100,000)
  • Minor cardiovascular conditions and procedures: 15% of the insurance amount (maximum $50,000)
  • Temporary loss of independent existence:15% of the insurance amount (maximum $25,000)
Learn more about what’s covered under critical illness insurance here
Affordable insurance for you and your loved ones

Find the lowest critical illness insurance quotes in Canada

Does Desjardins have a qualifying period for critical illnesses?

Yes, Desjardins has a qualifying period for certain illnesses or conditions, during which you must exhibit specific symptoms, neurological deficits, or functional losses to qualify for coverage.

The start date of the qualifying period depends on how the covered condition is defined in your contract. It may begin on:

  • The date of diagnosis,
  • The date of functional loss, or
  • The date of the triggering event

Here’s a list of illnesses that have a qualifying period:

Critical illnesses with a qualifying period

Critical illness or condition Qualifying period
Stroke 30 days
Dementia, including Alzheimer’s disease 6 months
Bacterial meningitis 90 days
Coma 96 hours
Acquired brain Injury 180 days
Paralysis 90 days
Loss of speech 180 days
Occupational HIV infection 90 to 180 days
Permanent or temporary loss of independent existence 90 days
Multiple sclerosis 6 months

Source: Desjardins Insurance

What is not covered under Desjardins’ critical illness insurance?

Procedures like angioplasty and conditions like viral meningitis are not covered under Desjardins’ critical illness insurance. For a complete list of exclusions, consult the Desjardins Critical Illness Guide.

Desjardins also has waiting periods for specific conditions. For example, cancer has a 90-day waiting period, while Parkinson’s disease has a one-year waiting period. If you’re diagnosed with these conditions or show initial symptoms during the waiting period, you won’t be eligible for benefits.

Does Desjardins’ critical illness insurance offer a return of premium options?

Yes, Desjardins’ critical illness insurance, Health Priorities, offers two return of premium options that enable policyholders to recover some or all their premiums under specific conditions:

  • Return of premium: Refunds a percentage of the premiums paid if you terminate the policy, provided you haven’t already claimed the full benefit. The refund percentage increases each year and can reach 100% over time
  • Return of premium on death: In the event of your death, this option refunds either 100% of all premiums paid or 25% of the insurance amount (whichever is greater), provided you haven’t claimed the total benefit. This option is already included in the Executive Health Plan and doesn’t need to be purchased separately

What is the cost of a Desjardins critical illness policy?

The cost of a Desjardins critical illness policy depends on several factors, including:

  • Age: Younger individuals typically pay lower premiums
  • Health status: Pre-existing conditions and habits like smoking may increase your premiums
  • Coverage amount: Higher coverage limits mean higher premiums
  • Term length: The duration of coverage can also affect costs

To give you an idea, here’s what a 20- to 55-year-old individual might pay for $50,000-$100,000 in critical illness coverage over a 10-year term:

Cost of Desjardins critical illness insurance

Age Coverage amount Monthly premium ( Male Smokers) Monthly premium (Male Non-smokers)
20 $50,000 $16.56 $15.07
30 $100,000 $37.35 $28.98
35 $50,000 $30.37 $20.97
40 $100,000 $77.58 $43.83
45 $50,000 $73.80 $37.75
55 $100,000 $373.95 $159.75

Get critical illness insurance

Find the best critical illness insurance rates in Canada

Pros and cons of Desjardins’ critical illness insurance

Desjardins’ critical illness insurance has several benefits, including no survival period for most conditions, phone assistance from nurses, and home care assistance in case of loss of independent existence. However, it also has some drawbacks:

Pros

Cons

No survival period on most conditions (except cardiovascular) Partial benefit is an advance and is deducted from the total insurance amount
Coverage for all types of cancer (with full or partial benefit based on the type of cancer) No second event coverage: Policy terminates after first claim payout
Children’s plan with 32 covered conditions, including 6 childhood conditions
Home care services in case of temporary or permanent loss of independent existence
Telephonic access to nurses for guidance on nutrition, vaccinations, prescriptions, and other health concerns
Long-Term Care (LTC) benefit (typically 15% of the insurance amount) for loss of independent existence with a chance of recovery

Can I cancel or modify my Desjardins critical illness policy?

Yes, you can cancel your Desjardins critical illness policy anytime by calling 1-866-647-5013.

You can also modify your policy in the following ways:

  • Changing beneficiaries: You can contact Desjardins at 1-888-558-5525 to update your beneficiary information
  • Switching coverage options: You can switch from a term critical illness insurance plan to a permanent policy (depending on your policy’s terms)

How can I buy a Desjardins critical illness plan?

Choosing the right critical illness insurance can feel overwhelming, but you don’t have to do it alone. Schedule a free consultation with our licensed advisors for personalized guidance. Our experts can help you compare different providers and their offerings, and find a plan that’s tailored to your needs.

With PolicyAdvisor, you’ll also enjoy lifetime after-sales support for any questions or adjustments down the road. Book your free consultation today and get the best critical illness insurance quotes!

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Is Desjardins’ critical illness insurance worth it?

Yes, Desjardins’ critical illness insurance can ease the financial distress of a health emergency by providing a tax-free lump-sum payment for an insured condition. With coverage limits of up to $3 million and tailored plans for individuals, children, and business owners, it can also give you significant flexibility and control over your healthcare coverage.

However, as with any insurance, we recommend you speak to our licensed insurance advisors for a personalized assessment of your needs and to determine if Desjardins’ critical illness insurance is right for you.

Does Desjardins’ critical illness insurance offer any optional benefits/ add-ons?

Yes, Desjardins’ critical illness insurance offers several optional benefits or riders that allow you to enhance your coverage. These include:

  • Return of premiums: Refunds a percentage of your premiums if you terminate the policy, provided you haven’t claimed the full benefit for a critical illness
  • Return of premiums on death: Refunds either 100% of your premiums paid or 25% of your coverage amount, whichever is greater, in the event of death
  • Disability Waiver of Premiums: Waives premiums if you experience total disability lasting more than six months before age 60.
  • Accident: Pays a predetermined amount to your beneficiary if you die in an accident
  • Accidental fracture: Pays a lump-sum benefit for fractures caused by accidents. The exact amount depends on the fractured bone
  • Accidental death, dismemberment, or loss of use: Pays you or your beneficiary a percentage of the insurance amount if you die or suffer dismemberment due to an accident
  • Children’s life protection: Adds term life insurance for children aged 15 days to 25 years, with the option to convert it to a permanent policy for up to 5 times the basic amount
  • Children’s accidental fracture: Pays a benefit if a child (aged 15 days to 25 years) sustains a fracture due to an accident

What happens if I die while my policy is active?

If your policy included a Return of Premiums on Death rider, your beneficiaries would get 100% of all premiums paid or 25% of the insurance amount, whichever is greater.

Does Desjardins’ critical illness insurance cover pre-existing conditions?

No, Desjardins’ critical illness insurance does not cover pre-existing conditions. To be eligible for coverage, you must not have experienced any symptoms or received a critical illness diagnosis within 90 days of your policy’s start date.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Canada Life Critical Illness Insurance Review – Updated 2026

The Rolls Royce of Critical Illness Coverage
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Policies offered
LifeAdvance critical illness insurance and Child LifeAdvance critical illness insurance
Average criticial illness insurance cost
Female: $26.25/month
Male: $35.57/month
*Based on standard profile
AM Best Rating
A+

Canada Life offers a wide range of solutions to protect Canadians from the financial impact of serious health conditions, and one of them is their critical illness insurance. In this article, we will explore the key features, benefits, and drawbacks of Canada Life’s critical illness insurance to help you determine if it’s the right choice for securing your future.

What are the benefits of Canada Life’s critical illness insurance?

Canada Life’s critical illness insurance provides a tax-free lump sum payment upon diagnosis of a covered health condition. This payment can be used for any purpose, whether replacing lost income, seeking treatment abroad, or managing everyday expenses.

Here are some other benefits of Canada Life’s critical illness insurance:

  • Partial payout benefits: Besides critical illnesses, Canada Life covers 8 early-stage and less-severe conditions, including early-stage thyroid and prostate cancer. You can claim up to 15% of your insurance benefit (maximum $50,000) upon being diagnosed with these conditions
  • Surgery advance: If you need surgery for a covered condition, Canada Life will pay you up to 10% of your benefit (maximum $15,000) to cover costs. This amount will be deducted from your total payout
  • Return of premium option: If you choose this option and make no claim on your insurance policy, you can get back 100% of your premium payments 
  • Medical and emotional support services: You can access a network of 50,000 medical experts for expert opinions on your diagnoses, plus professional counselling and family support services to help you and your loved ones cope with your condition
  • Conversion options: If you buy a children’s critical illness policy, you can convert all or part of the coverage to an adult policy before the child turns 25
Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Types of critical illness insurance offered by Canada Life

Canada Life offers two critical illness insurance plans to cover adults and children, LifeAdvance and Child LifeAdvance, respectively.  

  • LifeAdvance critical illness insurance: This plan provides comprehensive coverage for 25 critical illnesses, including major conditions such as cancer, heart attack, and stroke. Policyholders can choose a coverage amount ranging from $10,000 to $3,000,000
  • Child LifeAdvance critical illness insurance: This plan covers 21 conditions, plus 5 childhood-specific conditions, which are cerebral palsy, type-1 diabetes, cystic fibrosis, congenital heart disease, and muscular dystrophy, with coverage ranging from $10,000 to $250,000

Key features of LifeAdvance and Child LifeAdvance Plans

Feature LifeAdvance Child LifeAdvance
Coverage amount $10,000 to $3 million $10,000 to $250,000
Issue ages 18 – 65 years 60 days to 17 years
Premium and coverage options
  • Permanent level premiums (can be paid up in 15 to 20 years, or up to age 100)
  • Term 10 and Term 20 (renewable up to age 75)
  • Level premium term to age 75 (can be paid up in 20 years, or over your lifetime)
Level premiums up to age 25
Conditions covered Comprehensive coverage for 25 conditions and partial coverage for 8
  • Comprehensive coverage for 21 conditions and partial coverage for 8
  • Coverage for 5 childhood-specific conditions
Survival period
  • 30 days for heart conditions (surgery, stroke, and heart attack)
  • 90 days for bacterial meningitis, loss of independent existence, and paralysis
  • 180 days for brain injury
  • 6 months for dementia (including Alzheimer’s disease)
  • One year for Parkinson’s disease
  • 30 days for heart conditions (surgery, stroke, and heart attack)
  • 90 days for bacterial meningitis, loss of independent existence, and paralysis
  • 180 days for brain injury
Partial benefits 15% of the critical illness benefit (up to $50,000) 15% of the critical illness benefit (up to $37,500)
Surgery advance 10% of the critical illness benefit (up to $15,000) 10% of the critical illness benefit (up to $15,000)
Optional benefits Loss of independent existence, disability waiver of premium, second event, return of premium at withdrawal, return of premium at expiry, return of premium at death Return of premium at expiry and return of premium at death

Not sure which plan is right for you?

Book a free consultation with our licensed advisors for help

What critical illnesses are covered by Canada Life?

Canada Life’s critical illness insurance covers 25 illnesses and life-threatening conditions, including:

  • Aortic surgery
  • Aplastic anaemia
  • Bacterial meningitis
  • Benign brain tumour
  • Blindness
  • Coma
  • Coronary artery bypass surgery
  • Deafness
  • Dementia, including Alzheimer’s disease
  • Heart attack
  • Heart valve replacement or repair
  • Kidney failure
  • Life-threatening cancer
  • Loss of limbs
  • Loss of speech
  • Major organ failure on waiting list
  • Major organ transplant
  • Motor neuron disease
  • Multiple sclerosis
  • Occupational human immunodeficiency virus (HIV) infection
  • Paralysis
  • Parkinson’s disease and specified atypical Parkinsonian disorders 
  • Severe burns
  • Stroke 
Learn more about what’s covered under critical illness insurance here

The company also covers 5 childhood conditions under its children’s plan:

  • Cerebral palsy 
  • Type-1 diabetes
  • Cystic fibrosis
  • Congenital heart disease
  • Muscular dystrophy

What conditions are excluded from Canada Life critical illness insurance?

Canada Life will not pay an insurance benefit, surgery advance, or illness assist benefit (partial payout) if the insured condition arises due to:

  • An attempt by the insured to take their own life or intentionally harm themselves
  • Participation in an assault, battery, or criminal offense (whether or not charges are laid)
  • Use of drugs, intoxicants, narcotics, or any substance not prescribed by a medical practitioner
  • War or hostile actions by armed forces (of any country)
  • Operating or controlling a motorized vehicle with a blood alcohol concentration over 80 milligrams per 100 millilitres of blood

Additionally, claims for benign brain tumours, Parkinson’s disease, life-threatening cancer, or other covered cancers will not be paid if:

  • The condition is diagnosed within 90 days of the policy start date, issue date, or last reinstatement
  • For Parkinson’s disease or atypical Parkinsonian disorders, the diagnosis occurs within one year of the policy start date, issue date, or last reinstatement

Claims will also be denied if there were symptoms, investigations, or a diagnosis of the condition before the waiting period, even if the formal diagnosis was made after the waiting period.

Affordable insurance for you and your loved ones

Find the lowest critical illness insurance rates in Canada within minutes!

What type of term options are available with Canada Life critical illness insurance?

Canada Life offers 7 term options across 3 types of critical illness insurance plans:

Permanent level premium plans

These plans offer lifelong coverage with fixed premiums. You can choose from three payment options:

  • Paid-up at 100: No further premiums are required after age 100
  • Paid-up in 15 years: Premium payments end after 15 years
  • Paid-up in 20 years: Premium payments end after 20 years​

Renewable term plans

These plans offer coverage for a set period (or “term”) and can be renewed at the end of each term without requiring additional medical underwriting. Two term options are available:

  • Term 10: Provides coverage for 10 years. Renewable every 10 years until age 75
  • Term 20: Offers coverage for 20 years. Renewable every 20 years until age 75​

Level premium term plans

This type of insurance offers fixed premiums for the entire term and coverage up to age 75. You can choose from two payment options:

  • Level premium to age 75: Offers fixed premiums until age 75.
  • Level premium to age 75 (paid-up in 20 Years): Premiums are paid up in 20 years, but coverage continues until age 75

Can I cancel or modify my Canada Life critical illness policy?

Yes, you can cancel your Canada Life critical illness policy in two ways:

  • Early cancellation: If you’re dissatisfied with your policy, you can return it within 10 days of its receipt and get a full refund
  • General termination: You can cancel your policy anytime by submitting a cancellation request. Your policy will also end if you request a full withdrawal of your insurance benefit using the return of premium at withdrawal rider.

You can also modify your policy by converting a portion or all of the insurance amount under a Term 10 or Term 20 renewable term policy to a level premium critical illness insurance policy until the age of 65.

What is the cost of a Canada Life critical illness policy?

The cost of a Canada Life critical illness policy is determined by several factors, including:

  • The applicant’s age: Younger applicants usually pay lower premiums
  • Coverage amount: A higher coverage amount entails higher premiums
  • Pre-existing health conditions: These may affect your eligibility or increase your premiums
  • Smoking status: Non-smokers pay significantly lower premiums
  • The policy’s term length: The duration of coverage also influences premiums

For reference, here’s what a 20-55-year-old might pay for $50,000-$100,000 in critical illness coverage over a 10-year term:

Cost of Canada Life critical illness insurance

Age Coverage amount Monthly premium ( Male smokers) Monthly premium (Male non-smokers)
20 $50,000 $16.93 $14.37
30 $100,000 $35.57 $26.25
35 $50,000 $32.45 $19.96
40 $100,000 $74.48 $41.30
45 $50,000 $76.74 $37.49
55 $100,000 $360.99 $161.26

Pros and cons of Canada Life’s critical illness insurance

Canada Life’s critical illness insurance offers several benefits, including comprehensive coverage for 25 conditions, partial coverage for 8 conditions, and a 10% surgery advance benefit. However, it also has some drawbacks:

Pros Cons
Higher coverage amount (up to $3,000,000) and multiple term options Loss of independent existence is a separate rider with additional cost
Comprehensive coverage for 25 conditions, plus partial coverage for 8 The Child LifeAdvance plan does not have second event and disability waiver of premium rider options
Children’s plan with 26 covered conditions Partial/advance payments reduce remaining coverage
10% surgery advance payment (up to $15,000) from total benefit
Second event coverage (only at the issue of basic policy)

How can I buy a Canada Life critical illness insurance plan?

Choosing the right critical illness insurance requires careful consideration of several factors, like coverage amount, premium structure, and your potential healthcare needs, all of which can feel overwhelming

PolicyAdvisor can simplify this process. Our advisors can help you compare different providers and their offerings and select a plan that aligns with your specific requirements.

We also provide lifetime after-sales support to address any questions or policy adjustments you may need in the future. Book a free consultation with our advisors today for personalized critical illness insurance quotes.

Need insurance help?

Give us a call at 1-888-601-9980 or book some time with our licensed experts.

Frequently asked questions

Is Canada Life’s critical illness insurance worth it?

Yes, Canada Life’s critical illness insurance can be a valuable source of financial comfort during an unexpected health problem. Their tailored plans for adults and children make it easier for individuals to buy a policy that suits their unique circumstances. 

With a coverage amount of up to $3 million and additional riders such as the return of premium or disability waiver of death, Canada Life’s critical illness plans are one of the best in the industry. We recommend you speak to one of our licensed insurance advisors for a personalized assessment of your needs and to determine if Canada Life’s critical illness insurance is the right choice for your situation.

Are there any conversion options for my Canada Life critical illness policy?

Yes, until you turn 65, you can convert all or a portion of your insurance amount under a Term 10 or Term 20 renewable term policy to a level premium critical illness insurance policy, without additional medical underwriting.

You can also convert a Term 10 policy with a series date of May 25, 2020, or later to a Term 20 policy within the first five years of issue, provided you are under age 54.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */

Sun Life Term Insurance Review 2026

Best for long-term flexibility
☆☆☆☆☆
★★★★★
PolicyAdvisor rating
Policies offered
Term, whole, universal, permanent, critical, disability
Average life cost
Female: $26/month
Male: $33/month
*Based on standard profile
AM Best Rating
A+
LICAT Ratio
152%

Sun Life stands out for long-term flexibility, offering term coverage from 5 year up to 40 years alongside underwriting tailored for those managing diabetes. Their plans can be customized with valuable add-ons like critical illness, accidental death benefit, waiver of premium, business protection, and more. Sun Life insurance plans also have built-in conversion options that let policy owners seamlessly switch from term to permanent coverage without new medical evidence. These features make Sun Life a top choice for adaptable and long-term protection.

Read our full review below to find out more about the company, the features they offer, and what we rate their life insurance products.

Schedule a call for visitor insurance

Need insurance answers now?

Call 1-888-601-9980 to speak to our licensed advisors right away, or book some time with them below.

Our Sun Life insurance rating and review

Sun Life currently offers Sun Life Evolve Term Insurance as its primary fully underwritten term solution, built for flexible term lengths, higher coverage limits, and the ability to convert to permanent insurance as needs evolve.

Alongside Evolve, Sun Life also offers Sun Life Go and Sun Life Go Simplified, which focus on faster, online approvals and simplified underwriting. However, these options typically come with lower coverage limits, fewer customization features, and less structural flexibility compared to Evolve.

Sun Life also offered SunTerm and SunSpectrum Term previously as its traditional term life products, but both have been replaced by Sun Life Evolve Term as the insurer’s core fully underwritten solution.

You can renew your policy for another term once your first term is done, or you can change it into permanent life insurance. You also have a lot of life insurance rider options that can help you get a wide variety of coverage for an affordable rate.

Sun Life’s premiums can be slightly higher than those of some other companies. However, they also offer some of the highest coverage amounts in the Canadian market.

We would recommend Sun Life if you’re looking for a term life insurance product that offers strong flexibility (from a wide range of term length options to the ability to secure higher coverage amounts) while still giving you room to convert your coverage as your needs evolve.

Sun Life Term Life Insurance — Product Details

  • Available Term Lengths: 5 to 40 years
  • Available Term Types: Guaranteed level premiums
  • Maximum Amount of Coverage: $25,000,000
  • Renewability: Yes, renewable to age 85 (for select plans only)
  • Convertibility: Yes, convertible before age 75 (for select plans only)
  • Added complementary benefits: Terminal illness benefit — insured may be eligible for a 50% advance of the coverage amount in the event of terminal illness, up to a $250,000
  • Other types of insurance: Permanent insurance, critical illness insurance, disability insurance, health & dental insurance, long-term care insurance

Sun Life Insurance pros and cons

Here is what our team ranks as the most and least advantageous features of Sun Life’s term life insurance products for most Canadians.

Sun Life insurance pros

  • Strong name brand recognition
  • Multiple rider options available to help you maximize coverage for yourself and your family
  • Lets you convert into permanent life insurance up to age 75; most other companies allow this only up to age 70 or 71
  • Multiple options to convert into permanent life insurance: whole life or universal life
  • Fully underwritten or non-medical coverage options available
  • Flexibility to choose the coverage period that fits your needs (ranging from 5 to 40 years)
  • Coverage amounts up to $25 million, one of the highest in the Canadian market
  • Online application process
  • Digital e-policy

Sun Life insurance cons

  • Premiums can be higher than competitors’
  • Underwriting can be strict if you have existing health concerns
More choice. Lower price.
PolicyAdvisor saves you time and money when comparing Canada’s top life insurance companies. Check it out!
GET STARTED

About Sun Life Insurance

Sun Life Financial, Inc., founded in 1865, is one of the largest life insurance companies in the world. It was started in Montreal, Quebec, as The Sun Insurance Company of Montreal. In 1979 the company shifted its headquarters from Montreal to Toronto.

Today, Sun Life is a major financial company. It has offices in countries all over the world, including the U.S., the United Kingdom and Ireland, Hong Kong, the Philippines, Japan, Indonesia, India, China, Australia, Singapore, Vietnam, Malaysia, and Bermuda. It has 37,000 employees and sells products through more than 112,000 advisors.

Sun Life Assurance Company of Canada provides insurance and financial services like wealth and asset management. It has over $1.6 trillion CAD worth of assets under management (AUM) across the world.

Blue bulb

Sun Life and Health Insurance Company: Quick Facts

  • Founded: 1865
  • Headquarters: Toronto, Ontario
  • AM Best Rating: A+
  • Better Business Bureau Accreditation and Rating: No / A+
  • Assets: $173.2 billion
  • Annual Premiums: $20.9 billion

Check out more facts about Canada’s biggest life insurance companies

How much does life insurance from Sun Life cost?

Sun Life’s term life insurance may be priced above some lower‑cost options, but it also gives you access to higher coverage limits, offering stronger protection for your loved ones. The table below shows Sun Life term insurance quotes at different ages for their default plan, for a 20-year term, and $500,000 in coverage.

You can easily get a personal Sun Life insurance quote and compare it with other companies right here on our website.

Age Male Female
30 $33.30 $26.10
35 $35.10 $28.80
40 $52.65 $40.50
45 $82.80 $59.40
50 $141.75 $95.85
55 $259.20 $176.40
60 $469.80 $322.20
65 $718.20 $498.60


*Representative values: premiums are based on non-smokers in good health, with a $500,000 benefit and a 20-year term.

What types of term life insurance policies does Sun Life Insurance offer?

Sun Life Insurance offers three different term life insurance products. We’ve provided some details on them below.

Sun Life Evolve Term Insurance

Sun Life Evolve Term is a flexible term life insurance product with options that adapt as your life needs evolve.

  • Coverage starts at $50,000 and goes up to $25 million
  • Renewable terms ranging from 5 to 40 years, depending on your age
  • Option to increase your coverage at key life stages
  • Option to switch to a longer term length
  • Guaranteed conversion to permanent insurance, regardless of health (option only applies until you reach age 75)
  • Choose to make premium payments monthly or annually
  • Joint-first-to-die and multiple life coverage options available
  • Comes with optional benefits such as children’s insurance riders, waiver of premium on total disability, guaranteed insurability, and accidental death benefit

Sun Life Go Term Life Insurance

This Sun Life insurance plan has less strict underwriting, with coverage amounts from $100,000 to $1 million.

  • Available in 10 or 20 year terms for those between the ages of 18 and 69
  • Simpler online application process
  • Answer some health questions to apply online: You will not need to take a medical test
  • Does not have the other benefits/riders available with Sun Evolve
  • Premiums are much higher than those for other term insurance products

Sun Life Go Simplified Term Life Insurance

Sun Life’s no-medical life insurance option. It’s simplified issue, meaning you don’t need to take a medical exam to get approved. You can get small amounts of coverage with this plan.

  • Choose from 3 amounts: $50,000, $75,000 or $100,000
  • The only term available is 10 years
  • You only need to answer 3 health-related questions
  • No other optional riders/benefits
  • Can be useful for people with health issues who may not qualify for traditional term life insurance or other insurance products
  • A lot more expensive

sun life insurance review

What other insurance policies does Sun Life Insurance offer?

Aside from term life insurance, Sun Life also sells the following products:

Permanent life insurance covers you for your entire life. Your premiums are guaranteed to stay the same as long as you have your policy. It’s also often called whole life insurance.

These types of plans also have an investment component that helps you build wealth during your lifetime.

Sun Life has 3 different types of permanent insurance options: non-participating, participating, and universal.

Learn more about permanent life insurance.

Sun Life Non-Participating Life Insurance

Builds cash value over time, but does not pay dividends. Sun Life has 3 options for this type of plan:

Sun Life Participating Life Insurance

Gives you cash value and pays out dividends. Sun Life also has 3 options for this type of policy:

  • Sun Par Protector II. Basic plan to generate long-term cash value and death benefit growth.
  • Sun Par Accumulator II. Focuses on higher cash value growth in a shorter amount of time. Cash value begins after year 1.
  • Sun Par Accelerator. Built for high-income earners. Guaranteed to be fully paid-up in eight years. Provides high cash values in a short period of time.

Sun Life Universal Life Insurance

Lets you manage your own cash value investments instead of letting the insurance company do it for you. Sun Life also has 3 options for this type of coverage:

  • SunUniversalLife II. Policyholders can choose from 21 investment options, six Cost-of-Insurance options, and five death benefit options. Coverage ranges from $100,000 to $25 million.
  • SunUniversalLife Pro. Designed specifically for corporations, business owners, and professionals. Coverage ranges from $100,000 to $15 million.
  • SunSpectrum Universal Life II.  Reduced paid-up feature lets you stop making payments after age 70. It also features a guaranteed investment bonus that rewards you for maintaining and growing the policy. Coverage ranges from $25,000 to $5 million.

Critical illness insurance will give you a one-time lump-sum payment if you become sick with a serious illness and meet the policy requirements (including any survival period). Most insurance companies will pay out for 26 or more of the most common major diseases in Canada, like cancer, heart attack, stroke, and others.

Sun Life offers critical illness insurance for adults and children. The insurance provides comprehensive coverage in amounts from $25,000 to $4 million for adults and from $25,000 to $1 million for children.

They also give you a lot of options to customize your coverage, such as:

  • Enhanced (covers 26 conditions) and children’s coverage (5 additional conditions) available
  • 8 conditions are eligible for partial payouts
  • Early detection is eligible for partial payment (10% of the benefit up to $50,000)
  • Terms: 10 years and to age 75 and 100
  • 10 and 15 year limited pay options
  • Maximum coverage: $4 million for adults and up to $1 million for children
  • Coverage for Loss of Independent Existence Included
  • Return of Premium on death and expiry/cancellation available (after 15 years)

Read our Sun Life Critical Illness Insurance Review

Disability insurance will help pay a big part of your paycheque if you become disabled and cannot work. It’s also called income protection insurance.

Sun Life has disability insurance options for sale. But you have to speak to an insurance broker to find out more information and get quotes for their disability insurance plans.

Learn more about disability insurance in Canada.

Private health insurance helps to pay for health care costs that your provincial or government health plan doesn’t. Most private health plans also help pay for dental costs.

Sun Life is a popular choice for group benefits through your job in Canada. A lot of companies use them to give benefits like private health insurance to their employees. They offer Basic, Standard, and Enhanced plans, with different levels of coverage.

Sun Life also lets you change your group health insurance to a policy you own if you leave the company, so you won’t lose your coverage. They let you do this easily without having to answer a lot of health questions or do a medical exam.

Learn more about private medical insurance in Canada.

Long-term care insurance helps cover ongoing health-care and personal-assistance costs when you can no longer care for yourself, such as help with daily activities or supervision due to diminished physical or cognitive ability

Sun Life in Canada offers long-term care coverage through Sun Retirement Health Assist to protect against healthcare costs in retirement. It provides a monthly income-style benefit, paying between $125 and $2,300 per week.

How to buy Sun Life term life insurance policies?

You can buy life insurance with Sun Life on PolicyAdvisor.com. Use our free quoting tool or click the button below to get personalized quotes instantly. You can also compare those quotes with some of the other top companies for life insurance in Canada.

If you would prefer to speak with a licensed insurance agent, we can help with that too! Our experienced advisors would be happy to speak with you and give one-on-one advice.

Speak with a professional insurance advisor

As Canada’s best online life insurance advisor, we can help you compare and choose the company that matches your needs. Don’t hesitate to speak with our licensed advisors if you need help. We offer no-obligation advice to help you find your best match!

Need help?
Call us at 1-888-601-9980 or book time with our licensed experts.
SCHEDULE A CALL

Frequently Asked Questions

What are the different term life insurance options available with Sun Life?
With Sun Life, you can choose from different term life insurance options. Based on your budget and coverage requirements, you can choose a suitable plan and get the most affordable price.

Is Sun Life a good insurance company?
Yes, Sun Life is a reputable insurance company. It has over $1 trillion CAD worth of assets under management (AUM) across the world, which demonstrates its stable financial strength. The company has also received an A+ rating as per A.M. Best ratings.

How is the cost of Sun Life insurance policy determined?
The cost of Sun Life insurance policy depends on the coverage, age, gender, riders, and a few other factors. Moreover, premiums for a non-smoker are lower than those for a smoker. You can consult our advisor to get the exact premium you need to pay for Sun Life insurance policy.

What happens if I miss Sun Life insurance premium payment?
Sun Life insurance policies usually include a grace period. If a policy lapses, reinstatement may be available within a specified window (subject to conditions). Check your policy contract for exact terms.

/* Custom Archives Functions Go Below this line */ /* Custom Archives Functions Go Above this line */